
 Switzerland Telecom Market | 2026-2036
Switzerland Telecom Market Size, Share, and Industry Trends Forecast 2026-2036
Switzerland Telecom Market Insights
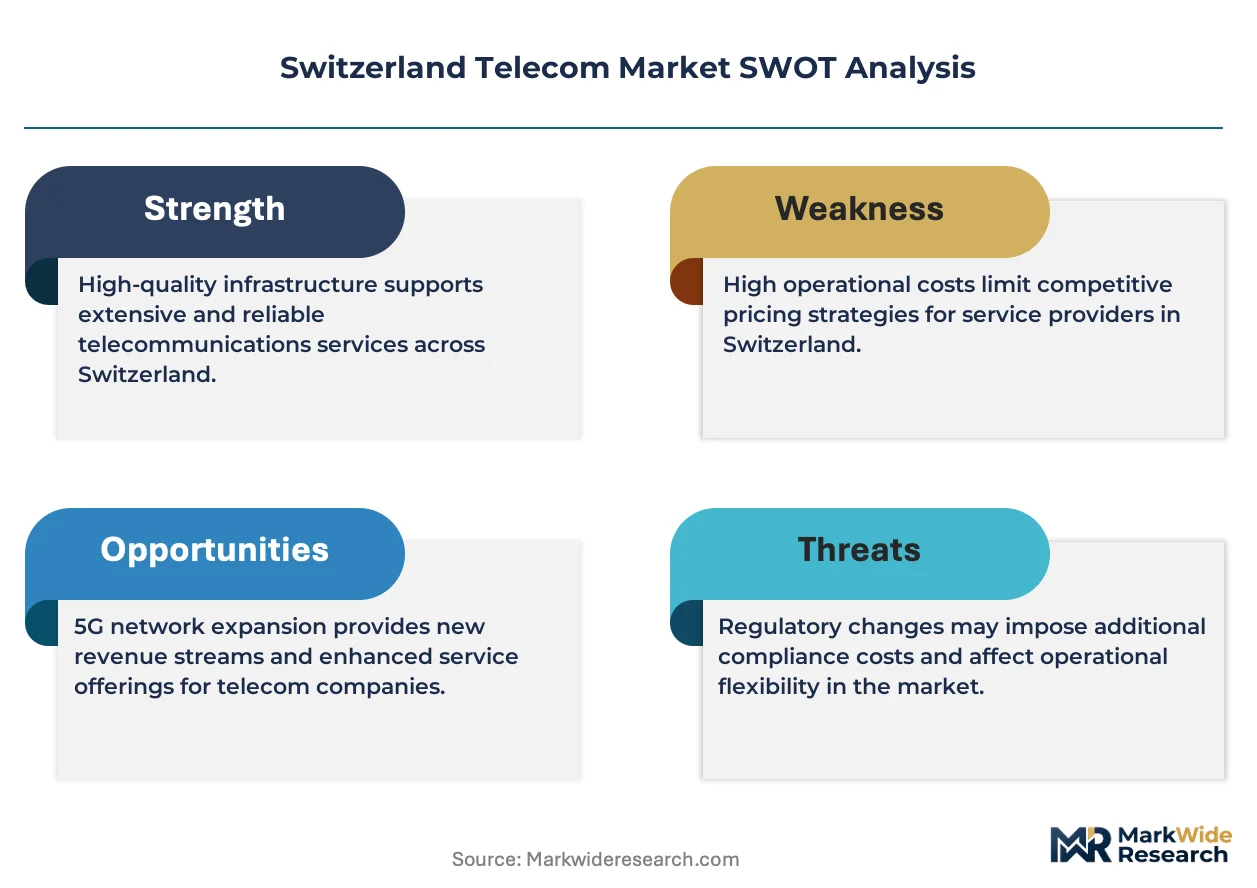
Enterprise cloud connectivity demand is repositioning the Switzerland Telecom Market toward high-margin managed services. Swisscom AG leverages its nationwide fiber backbone to anchor premium enterprise contracts across banking and pharmaceutical verticals. Sunrise Communications AG competes through aggressive 5G standalone deployment, while Salt Mobile SA differentiates with price-transparent mobile data plans targeting cost-sensitive residential segments.
Switzerland Telecom encompasses the infrastructure, services, and licensed spectrum enabling voice, data, and video transmission across fixed and wireless networks, with fiber-to-the-home installations now exceeding 3 million premises and 5G population coverage surpassing 95 percent nationwide. The primary purpose is delivering reliable, low-latency connectivity to support digital operations across financial services, precision manufacturing, and public administration. Mobile data services generate the fastest growth trajectory as unlimited data plans displace metered pricing, while fiber optic technology commands the capital investment focus due to its 25-year asset lifespan and superior throughput economics. Fixed line voice services occupy a mature, declining revenue pool as VoIP and mobile substitution accelerate.
Swisscom AG and its rivals navigate oversight from the Federal Communications Commission (ComCom) and enforcement of the Telecommunications Act, which mandates infrastructure sharing and price caps on wholesale access. The Federal Data Protection and Information Commissioner enforces GDPR-aligned privacy standards that constrain data monetization strategies. Stakeholders must monitor spectrum auction timing and net neutrality rule evolution to calibrate capital allocation between fiber densification and 5G advanced capabilities.
Market Dynamics
The Federal Communications Commission Act revision is compressing wholesale margins while mandating infrastructure sharing, forcing carriers to differentiate through vertical service integration rather than network exclusivity.
Growth Catalysts
- Enterprise cloud connectivity:Swiss financial services institutions are migrating core banking systems to hybrid cloud architectures, creating demand for low-latency fiber backhaul and managed SD-WAN services.
- Telecommunications Act mandates:Infrastructure sharing requirements accelerate 5G standalone deployment by reducing redundant capital expenditure and lowering barriers to rural coverage expansion.
- Zurich-Geneva corridor concentration:Banking and pharmaceutical headquarters clustering drives premium connectivity demand, anchoring high-margin enterprise contracts for fiber and private mobile networks.
Market Restraints
- Wholesale price caps:ComCom-mandated access pricing limits revenue recovery on fiber investments, compressing returns on last-mile infrastructure deployment.
- Copper decommissioning costs:Legacy PSTN switch-off obligations impose stranded asset write-downs and customer migration expenses without offsetting revenue streams.
- Spectrum scarcity:Limited mid-band allocation constrains 5G capacity expansion in dense urban corridors where mobile data traffic concentrates.
Strategic Opportunities
- Private 5G networks:Precision manufacturing facilities in Basel and Lausanne seek dedicated spectrum slices for industrial automation and real-time quality control systems.
- Cross-border data corridors:GDPR-aligned Swiss data protection standards position domestic operators as trusted intermediaries for EU financial data transit and storage.
- Smart grid integration:Utility-sector digitalization creates demand for resilient fiber connectivity to substations and distributed renewable generation assets.
Industry Challenges
- Optical transport engineering shortage:Specialized skills for 400G coherent transmission deployment and DWDM optimization remain scarce in the domestic labor market.
- Multi-vendor interoperability:Disaggregated RAN architectures from diverse suppliers introduce integration complexity and troubleshooting overhead in live network environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Switzerland Telecom Market |
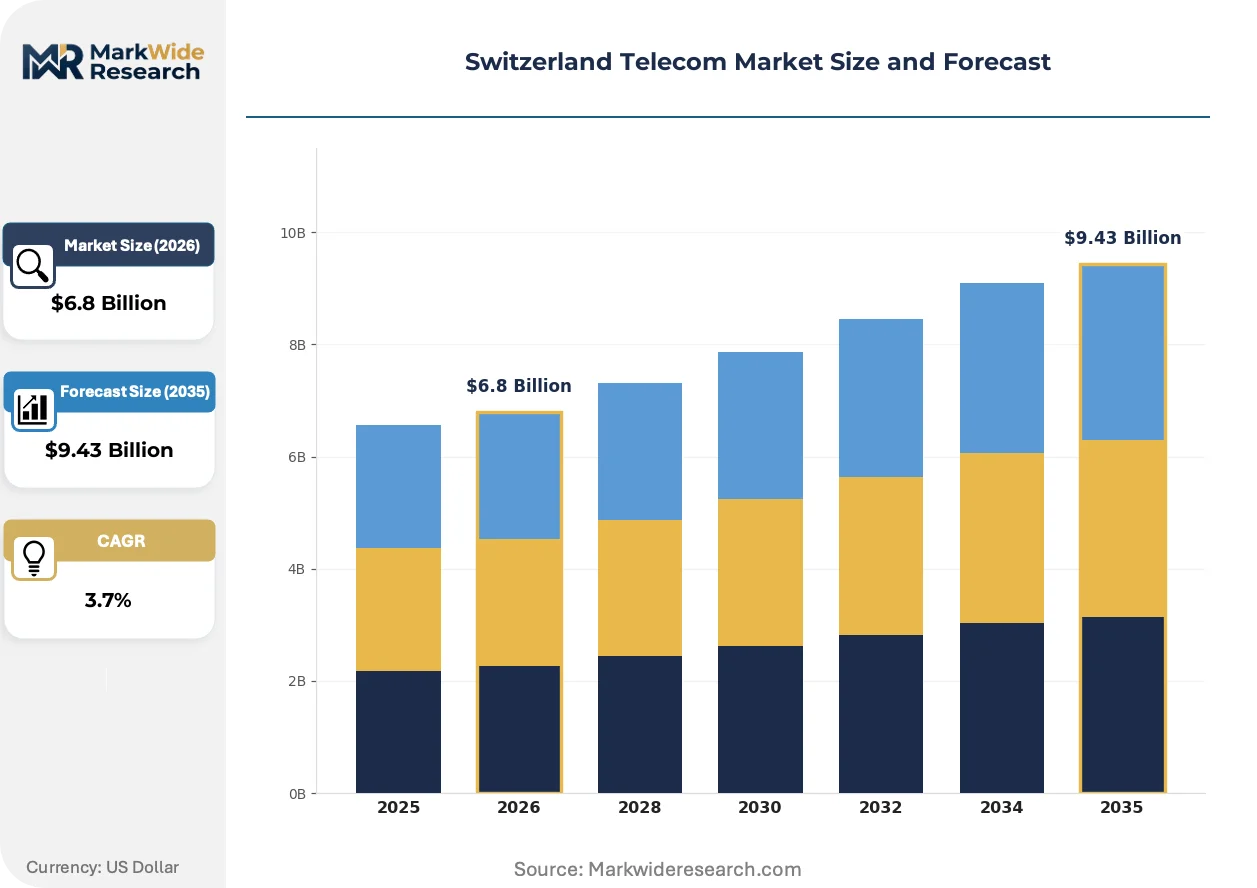
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.43 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mobile Voice, Mobile Data, Fixed Line, Broadband Technology: 4G, 5G, Fiber Optic, DSL Customer Type: Residential, SME, Large Enterprise, Government Distribution Channel: Retail, Online, Direct Sales, Wholesalers |
| Companies Covered | Swisscom AG, Sunrise Communications AG, Salt Mobile SA, UPC Switzerland, Sunrise GmbH, Liberty Global, TX Group AG, Kudelski SA, MCH Group AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Switzerland Telecom Market Trends and Innovations
Network function virtualization is dissolving the boundary between hardware-centric and software-defined service delivery, enabling carriers to reprovision capacity dynamically rather than through physical infrastructure swaps.
Open RAN architectures are integrating disaggregated baseband and radio units from multiple vendors into unified management platforms. Sunrise Communications AG and Salt Mobile SA are deploying multi-vendor RAN stacks in urban test zones to reduce supplier lock-in and accelerate feature velocity. This disaggregation is integrating third-party automation tools into network operations, compressing the traditional equipment vendor value chain.
The Federal Communications Commission Act revision tightens wholesale access obligations and spectrum auction transparency rules. Incumbent carriers must now publish reference offers for dark fiber and bitstream access within 90 days of regulatory request. Swisscom AG and challengers are responding by accelerating vertical service development to offset commoditized connectivity margins.
Enterprise buyers are consolidating vendor relationships and demanding outcome-guaranteed service level agreements with financial penalties for latency or availability breaches. Traditional equipment procurement with separate maintenance contracts is yielding to fully managed network-as-a-service arrangements. This consolidation is most pronounced among pharmaceutical headquarters in Basel and private banking clusters in Zurich, where IT infrastructure teams lack specialized telecommunications engineering depth.
Switzerland Telecom Market Segmentation
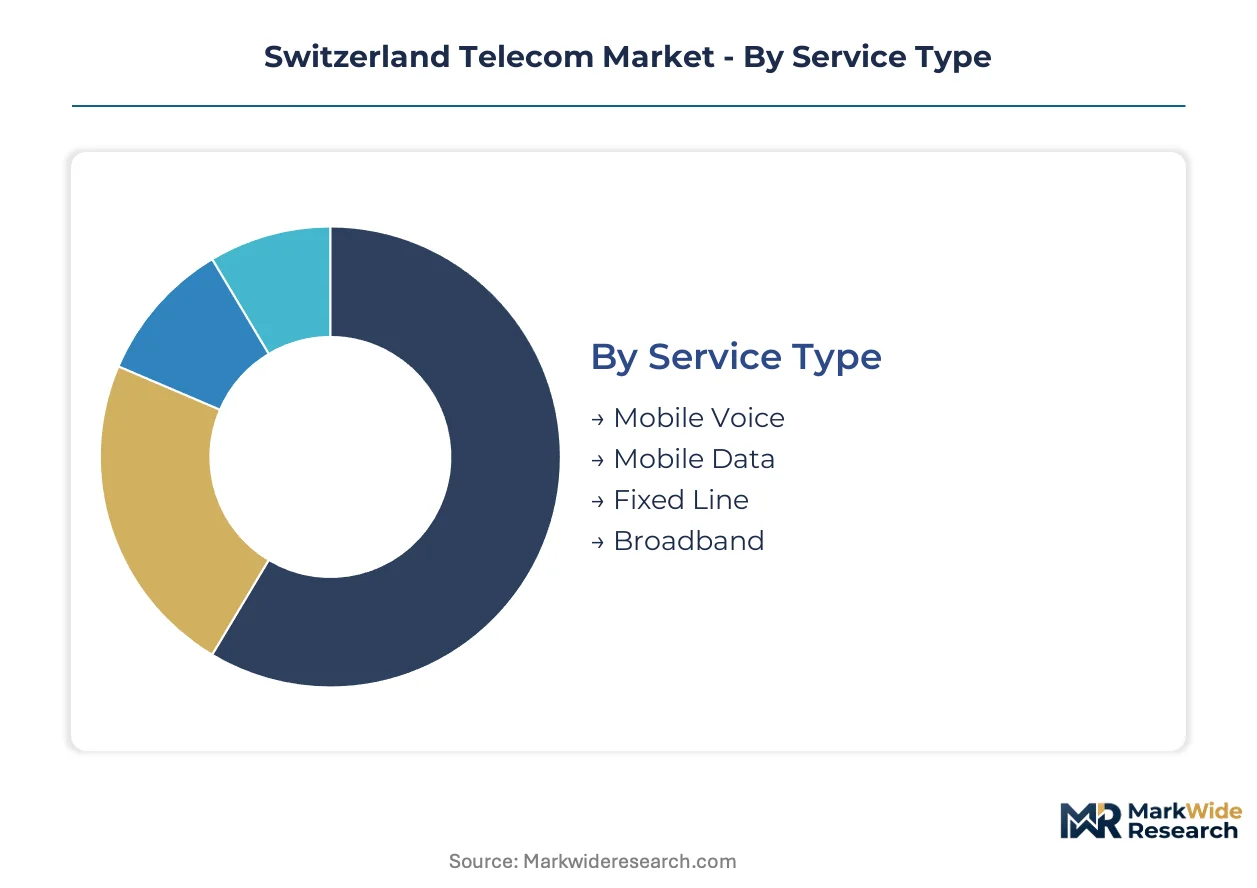
Segmentation in the Switzerland Telecom Market reveals how infrastructure investments and regulatory obligations concentrate returns in specific service tiers. Distinct technology lifecycles and customer procurement patterns create divergent margin profiles across the value chain.
Service Type:
Supply concentration in fiber backhaul and 5G core networks favors service categories with enterprise-grade SLA requirements over commoditized residential offerings.
- Mobile Voice:PSTN-to-VoLTE migration has compressed this segment to basic connectivity bundled with data plans. Swiss banking headquarters in Zurich maintain dedicated voice circuits for trading floor reliability, though volume is shifting to encrypted mobile applications.
- Mobile Data:Unlimited data plans now dominate consumer acquisition, with traffic growth driven by video streaming and cloud application sync. Pharmaceutical field forces in Basel and Geneva corridor generate premium enterprise data demand with guaranteed throughput requirements.
- Fixed Line:Copper decommissioning accelerates subscriber migration to fiber or mobile substitution. Residual demand concentrates in rural Alpine municipalities where wireless coverage remains intermittent.
- Broadband:Fiber-to-the-home installations exceeding 3 million premises anchor this segment, with symmetric gigabit services commanding price premiums in dense urban cantons.
Mobile Data absorbs the bulk of installed capacity; Mobile Data is expanding most quickly.
Technology:
Capital deployment patterns favor technologies with 20-plus year asset depreciation schedules and regulatory protection against stranded investment.
- 4G:Carrier aggregation and MIMO enhancements extend utility for IoT telemetry and voice fallback. Manufacturing facilities in Lausanne retain 4G private networks for equipment monitoring where 5G coverage remains incomplete.
- 5G:Standalone deployment with network slicing enables guaranteed latency for financial trading applications. Sunrise Communications AG and Swisscom AG prioritize mid-band expansion in Zurich-Geneva corridor where enterprise density justifies infrastructure densification.
- Fiber Optic:GPON and XGS-PON architectures deliver 10Gbps symmetrical services with 25-year economic lifespans. Federal Communications Commission Act infrastructure sharing mandates accelerate rural fiber deployment through cost-pooling mechanisms.
- DSL:VDSL2 vectoring extends copper utility in legacy buildings where fiber retrofit costs exceed regulatory recovery allowances. Subscriber bases contract 8-12 percent annually as migration deadlines approach.
Fiber Optic absorbs the bulk of installed capacity; 5G is climbing the fastest.
Customer Type:
Procurement sophistication and contract scale determine pricing power, with consolidated enterprise accounts extracting outcome-guaranteed terms unavailable to fragmented residential markets.
- Residential:Price-transparent mobile data plans and fiber triple-play bundles dominate acquisition. Salt Mobile SA targets cost-sensitive segments with digital-first distribution, while Swisscom AG anchors premium positioning with service reliability guarantees.
- SME:Managed SD-WAN and cloud connectivity services generate recurring revenue with lower churn than commodity broadband. Basel precision manufacturing SMEs demand private 5G pilots for industrial automation quality control.
- Large Enterprise:Hybrid cloud architectures from financial services institutions drive demand for low-latency fiber backhaul with financial penalty SLAs. Pharmaceutical headquarters in Basel consolidate vendor relationships around fully managed network-as-a-service arrangements.
- Government:Federal administration and cantonal authorities mandate resilient connectivity for critical infrastructure operations. Smart grid integration for utility-sector digitalization creates dedicated procurement streams for substation fiber connectivity.
Large Enterprise absorbs the bulk of installed capacity; Large Enterprise is gaining share fastest.
Distribution Channel:
Channel economics reflect customer acquisition cost differentials and service complexity requirements, with high-touch direct sales commanding premium positioning in enterprise segments.
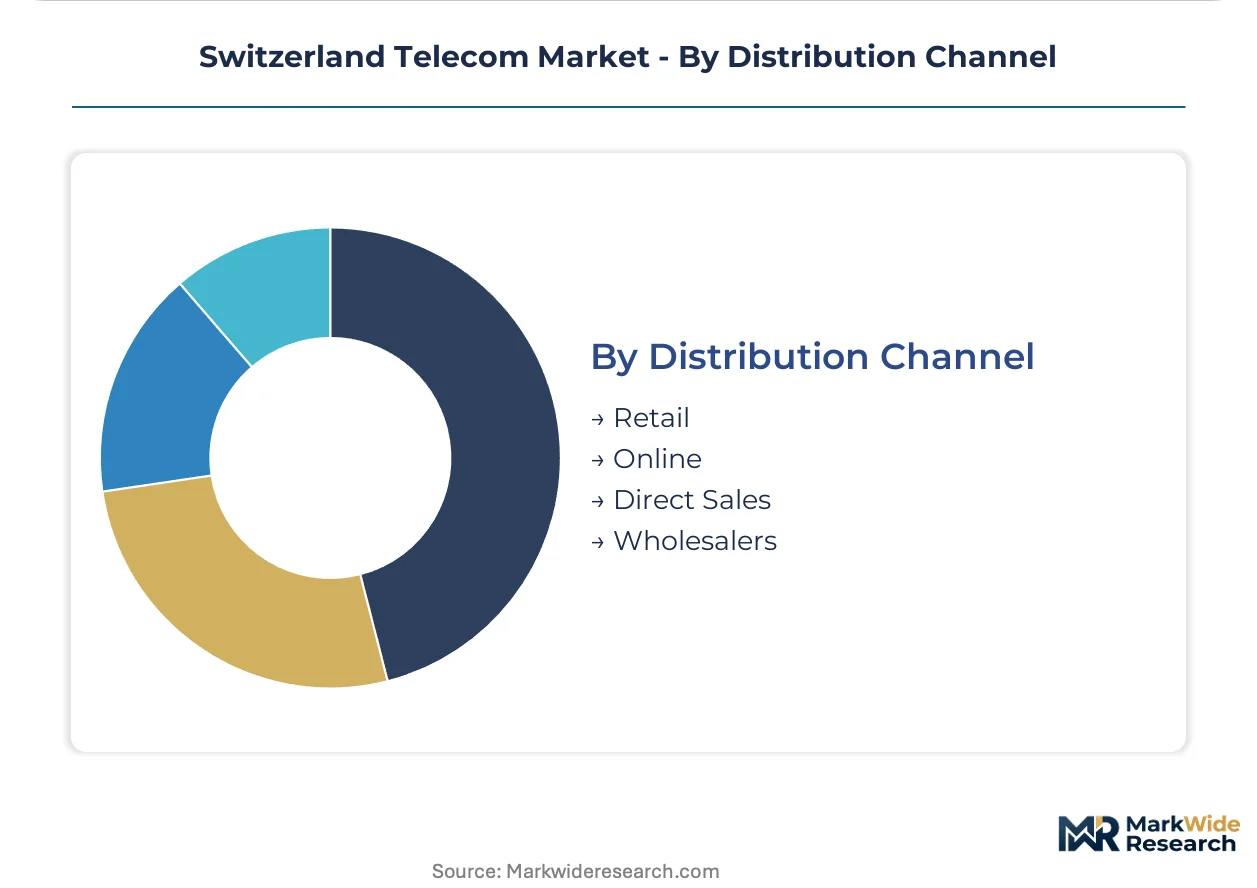
- Retail:Physical storefronts in urban centers handle SIM activation, device financing, and basic service troubleshooting. Foot traffic concentrates in Zurich and Geneva metropolitan areas where population density supports fixed cost coverage.
- Online:Digital self-service portals reduce subscriber acquisition costs by 40-60 percent versus assisted channels. Younger demographics in Lausanne and Bern metropolitan regions prefer app-based plan management and automated billing.
- Direct Sales:Dedicated account teams cultivate multi-year enterprise contracts with customized SLA architectures. Private banking clusters in Zurich and pharmaceutical headquarters in Basel require onsite technical consultation for network design.
- Wholesalers:Bitstream and dark fiber access obligations under Telecommunications Act mandates create regulated wholesale revenue pools. ComCom-mandated reference offers constrain pricing flexibility within 90-day regulatory windows.
Direct Sales absorbs the bulk of installed capacity; Online is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Greater Zurich Area economic promotion zone drives telecom infrastructure concentration through R&D tax credits and innovation hub status. Federal and cantonal incentives cluster enterprise connectivity demand in designated technology corridors.
Zurich
Private banking headquarters and fintech incubators generate low-latency fiber demand for algorithmic trading platforms. The Federal Communications Commission Act mandates infrastructure sharing obligations that accelerate 5G densification. Paradeplatz and surrounding financial district blocks anchor premium enterprise contracts with sub-millisecond SLA requirements.
Geneva
Commodity trading houses and international organization data centers drive cross-border connectivity procurement. FINMA supervisory standards align with GDPR through the Federal Data Protection and Information Commissioner enforcement. The international quarter along Rue de Lausanne concentrates sovereign wealth fund and NGO headquarters demanding resilient redundant paths.
Basel
Pharmaceutical manufacturing campuses and precision chemical facilities require private 5G networks for cleanroom automation. The Swissmedic regulatory framework mandates data integrity standards that favor domestic fiber transit over international routes. The Novartis and Roche headquarters corridor generates dedicated procurement for industrial IoT connectivity.
Lausanne
EPFL research spinoffs and medtech startups create demand for high-bandwidth research network interconnection. The State Secretariat for Education, Research and Innovation funds digital infrastructure through the Swiss Innovation Agency. The Ecublens technology park anchors testbed deployment for Open RAN architectures.
Ticino
Cross-border Italian-speaking commerce and tourism hospitality drive bilingual service delivery requirements. Cantonal authorities enforce Italian-language customer service mandates under the Federal Telecommunications Act. The Lugano financial center replicates Zurich-style private banking connectivity with Milan-facing network architecture.
Switzerland Telecom Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated incumbents commanding enterprise fiber while mobile challengers capture residential data volumes. The Swiss market structures around three tiers: a dominant infrastructure owner with vertical service integration, a 5G-first challenger with aggressive standalone deployment, and price-transparent disruptors in consumer mobile. Competitive moves concentrate on fiber co-investment partnerships with real estate developers and spectrum co-ordination for shared rural 5G coverage.
Within the incumbent tier, Swisscom AG anchors nationwide backbone ownership and enterprise relationship depth. Sunrise Communications AG and Salt Mobile SA occupy challenger positions, with Sunrise emphasizing 5G standalone velocity and Salt targeting digital-native residential segments through transparent pricing. These three entities collectively represent the competitive archetypes visible across service tier and technology generation boundaries.
| Leading Market Players |
|---|
| Swisscom AG |
| Sunrise Communications AG |
| Salt Mobile SA |
| UPC Switzerland |
| Sunrise GmbH |
| Liberty Global |
| TX Group AG |
| Kudelski SA |
| MCH Group AG |
| Others |
Pricing and Supply Chain Analysis
Open RAN disaggregation and multi-vendor stack deployment are simultaneously compressing equipment procurement costs and fragmenting supplier relationships across Swiss carrier networks. This technology transition forces operators to renegotiate legacy vendor contracts while absorbing integration complexity that reshapes total cost of ownership calculations.
Pricing Analysis
Lead-time-driven pricing stratification separates urgent fiber deployment projects from standard provisioning schedules, with premium rates attaching to sub-90-day infrastructure activation. Three-tier pricing structure across premium, standard, and economy levels reflects SLA stringency, geographic density, and contract duration. Cost compression in wholesale bitstream access intensifies because Federal Communications Commission Act reference offer mandates cap recovery rates. Residential mobile subscribers exhibit highest price sensitivity, while private banking clusters in Zurich accept premium positioning for sub-millisecond latency guarantees.
Supply Chain Analysis
Single-source vulnerability sits with specialized optical transport engineering talent concentrated in Germany, Austria, and domestic Swiss technical universities. Equipment procurement draws from Finland, Sweden, and China for baseband units, radio heads, and passive optical components. Tariff exposure on Chinese-manufactured 5G massive MIMO arrays presents structural risk amid evolving trade policy frameworks. Distribution runs through carrier-direct procurement for core infrastructure, with systems integrators handling enterprise edge deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Switzerland Telecom Market reads as a cost-of-compliance story where Federal Communications Commission Act infrastructure sharing mandates and net neutrality enforcement create regulatory moats that favor incumbent scale players over capital-constrained challengers.
For Market Incumbents: Hedge against wholesale margin erosion by accelerating proprietary managed service development in private 5G and SD-WAN verticals. Prioritize fiber co-investment partnerships with Zurich-Geneva corridor real estate developers to lock in enterprise anchor tenants before challenger network completion. ComCom-mandated price caps on bitstream access threaten last-mile returns; offset through premium enterprise SLA pricing. For New Entrants and Emerging Players: Launch via digital-first distribution targeting cost-sensitive residential segments in Lausanne and Bern metropolitan regions where incumbent service premiums create acquisition headroom. White-space concentration sits with precision manufacturing private 5G pilots in Basel and Lausanne where industrial automation demand outstacks incumbent sales force coverage. Partner with EPFL research spinoffs for Open RAN testbed credibility. For Investors and Strategic Acquirers: Exit pathways concentrate in infrastructure asset carve-outs and enterprise service rollup plays rather than consumer mobile subscriber bases facing unlimited data plan margin compression. Long-term viability favors operators with captive fiber depth and vertical service integration rather than pure-play mobile challengers. Monitor spectrum auction timing as inflection indicator for capital intensity shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Private 5G Network Deployment | Captures pharmaceutical manufacturing automation demand in Basel corridor with dedicated spectrum slicing. |
| Fiber Co-Investment Partnership | Locks enterprise anchor tenants in Zurich-Geneva corridor through real estate developer risk-sharing structures. |
| Open RAN Architecture Migration | Reduces Nokia-Ericsson supplier lock-in while accelerating feature velocity through multi-vendor competition. |
| Cross-Border Data Corridor Positioning | Leverages GDPR-aligned Swiss data protection standards for EU financial institution transit and storage mandates. |
| Smart Grid Fiber Integration | Captures utility-sector digitalization procurement for substation connectivity and distributed renewable asset monitoring. |
Research Methodology
Independent corroboration across carrier network planning executives, enterprise IT procurement officers, and Federal Communications Commission regulatory staff underwrites the qualitative findings in this study. Primary fieldwork encompassed structured interviews with Swisscom AG and Sunrise Communications AG infrastructure strategists, Basel pharmaceutical headquarters telecommunications managers, and ComCom wholesale market analysts. Secondary validation drew from SEC filings of listed equipment vendors, Swiss Federal Council telecommunications policy releases, and ITU spectrum allocation databases. Bottom-up service revenue modeling triangulated against top-down macroeconomic consumption projections.
Rate-of-change decomposition across the analysis window segments volume and value trajectories by service type, technology generation, customer procurement sophistication, and distribution channel economics. Segmentation dimensions modeled include mobile versus fixed infrastructure, 4G-5G-fiber technology lifecycle positioning, residential-SME-enterprise-government buyer tiers, and retail-online-direct-wholesale channel mix. CAGRs were derived from installed base depreciation schedules, subscriber migration velocity assumptions, and enterprise contract renewal patterns. Industry-specific forecast inputs incorporated spectrum auction timing scenarios and copper decommissioning regulatory deadlines.
The model assumes a particular technology adoption path; alternative pathways for 5G standalone core deployment would alter the outlook if enterprise demand materializes slower than projected. Forecasts reflect assumptions regarding infrastructure sharing compliance timelines, fiber co-investment partnership formation rates, and optical transport engineering labor market elasticity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Underwater Modems Market
Telecommunications
Kuwait Telecom Market
Telecommunications
GPON Market
Telecommunications
Vietnam Telecom Market
Telecommunications
5G Network and Service Assurance Market
Telecommunications
GPON Equipment Market
Telecommunications
Indonesia ICT Market
Telecommunications
Myanmar ICT Market
Telecommunications
Global Policy Management in Telecom Market
Telecommunications
Carrier Aggregation Solutions Market
Telecommunications
Embedded SIM (Esim) Market
Telecommunications
Cloud Radio Access Network (C-RAN) Market
Telecommunications
Denmark Telecom Market
Telecommunications
Private Branch Exchange Market
Telecommunications
GSM Mobile Phone Market
Telecommunications
Oman Telecommunication Market