
 Service Orchestration Market | 2026-2036
Service Orchestration Market Size, Share, and Industry Trends Forecast 2026-2036
Service Orchestration Market Intelligence
GDPR enforcement is consolidating data sovereignty requirements across automated service workflows. IBM leverages its hybrid cloud portfolio to anchor enterprise orchestration deployments. BMC Software sustains mainframe-to-cloud integration capabilities that dominate financial services pipelines. ServiceNow competes through IT service management workflows that extend into cross-platform orchestration.
Service orchestration coordinates multiple automated tasks, APIs, and microservices through centralized control planes that enforce policy, monitor state, and trigger conditional workflows across distributed systems. The discipline relies on container runtime specifications such as Kubernetes orchestration primitives and service mesh sidecar architectures to maintain resilience at scale. Cloud-based deployment leads adoption as enterprises abandon capital-intensive on-premise infrastructure, while microservices technology captures the fastest expansion as organizations decompose monolithic applications. Integration services retain the deepest margin pools due to complex legacy system connectivity requirements.
The EU AI Act and GDPR jointly constrain how automated orchestration engines process personal data across jurisdictions, forcing vendors to embed compliance checkpoints within workflow logic. The Federal Communications Commission shapes telecommunications-grade orchestration through network reliability standards that filter into service-level architectures. ISO/IEC 27001 certification operates as a de facto market access requirement for security-conscious buyers. Stakeholders must weigh sovereign cloud mandates against the operational efficiency of centralized multi-tenant orchestration platforms.
Market Dynamics
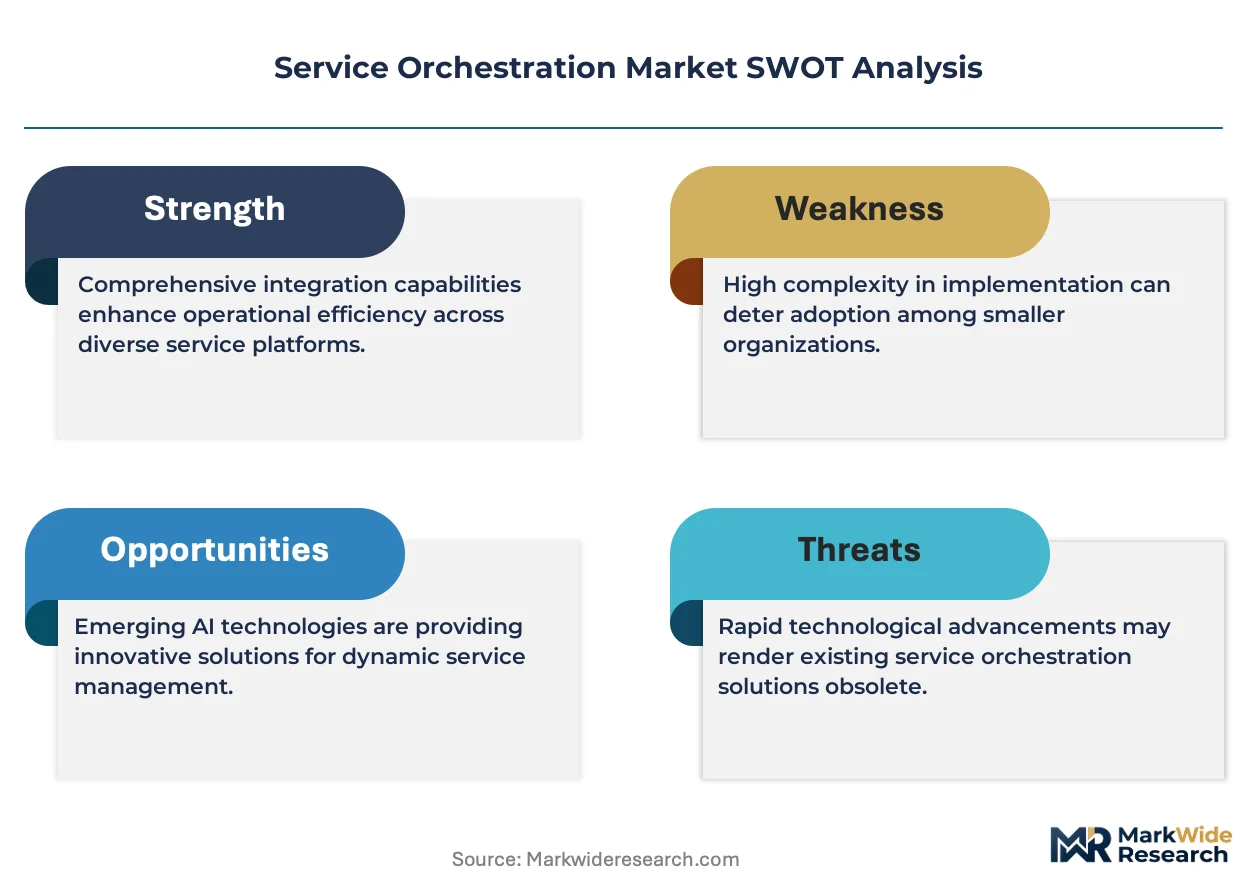
Cloud-native container orchestration is compressing deployment cycles while the EU AI Act and GDPR jointly impose compliance checkpoints that reshape workflow architecture across financial services and telecommunications verticals.
Growth Catalysts
- EU AI Act enforcement:Automated decision-making mandates in the BFSI sector are forcing institutions to deploy auditable orchestration layers that log every API call and data transformation.
- Microservices decomposition:Kubernetes-native service meshes enable banks to break monolithic core banking systems into independently scalable components without downtime.
- Germany's IT modernization wave:Mittelstand manufacturers and automotive suppliers are retiring legacy SAP landscapes in favor of API-first orchestration platforms.
Market Restraints
- Specialized talent scarcity:Site reliability engineering expertise concentrates in Berlin, London, and Bangalore, creating wage inflation above 40 percent for Kubernetes-certified architects.
- Legacy integration tax:Mainframe connectivity adapters for IBM z/OS and Unisys ClearPath consume 60-70 percent of implementation budgets in established financial institutions.
- Sovereign cloud fragmentation:France, Germany, and Italy operate incompatible national cloud certification schemes that prevent unified multi-tenant orchestration deployments.
Strategic Opportunities
- Edge orchestration for manufacturing:Discrete automation lines in Stuttgart and Wolfsburg require sub-10-millisecond latency coordination that centralized clouds cannot deliver.
- CSRD-aligned sustainability tracking:The EU Corporate Sustainability Reporting Directive creates demand for orchestration workflows that aggregate carbon footprint data across distributed supplier networks.
- Telecom network slicing:5G standalone deployments by Deutsche Telekom and Vodafone need intent-based orchestration to manage slice lifecycle across radio, transport, and core domains.
Industry Challenges
- ISO/IEC 27001 audit timelines:Certification for orchestration control planes now requires 14-18 months, delaying production deployments in security-sensitive healthcare and government segments.
- API versioning entropy:Microservices architectures accumulate technical debt when 200-plus internal services operate on incompatible OpenAPI specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Service Orchestration Market |
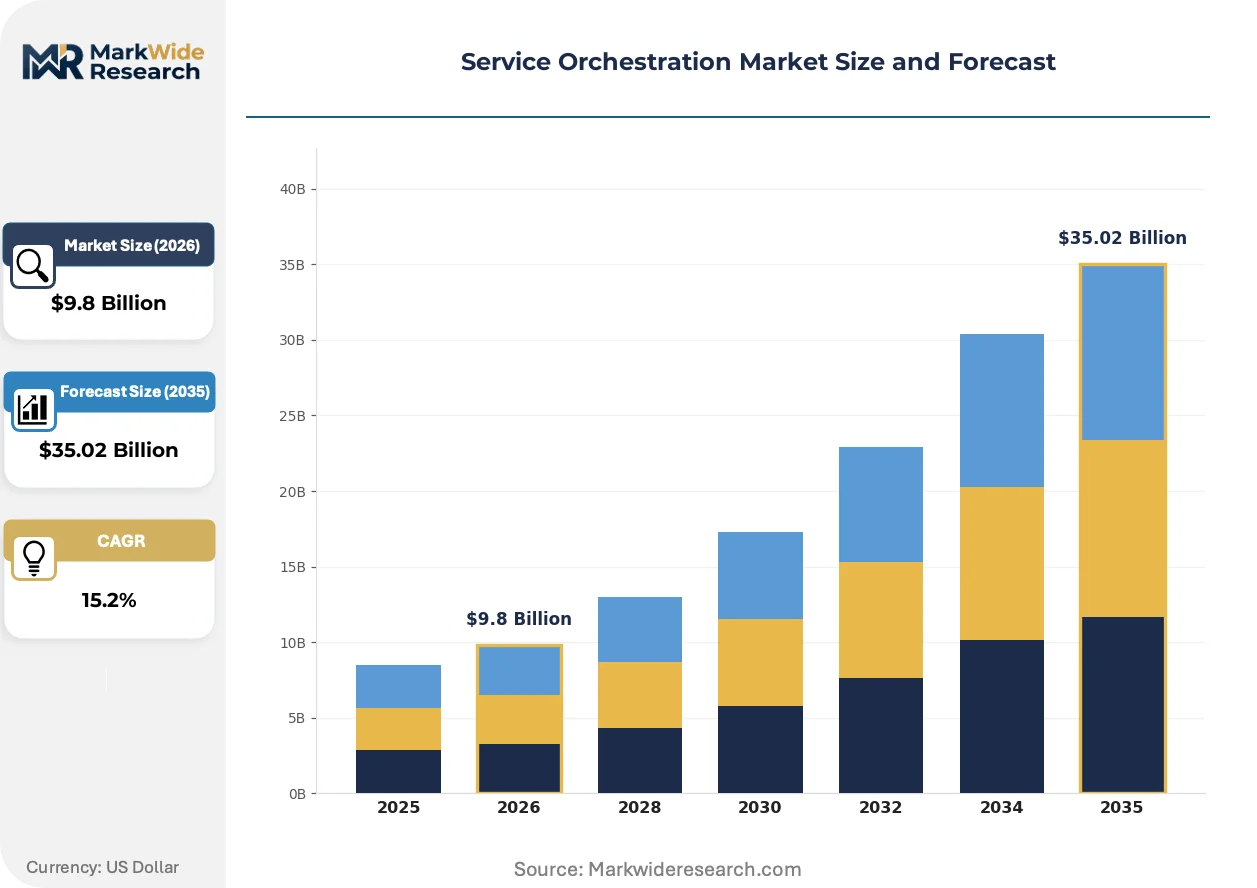
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $35.02 Billion |
| CAGR (2026 – 2036) | 15.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Multi-Cloud Service Type: Integration Services, Automation Services, Management Services, Monitoring Services End User: Telecommunications, BFSI, Healthcare, Retail Technology: API Management, Microservices, Containers, Serverless |
| Companies Covered | IBM, BMC Software, Stonebranch, Cisco Systems, Hewlett Packard Enterprise, Ericsson, ServiceNow, ActiveBatch, Redwood Software, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Service Orchestration Market Strategic Shifts & Innovations
Artificial intelligence is embedding inference capabilities directly into orchestration control planes, enabling predictive scaling and anomaly detection without human intervention. Three interconnected developments are restructuring competitive positioning.
GitOps workflows is expanding into enterprise platform engineering teams as the dominant deployment paradigm. Platform engineers at major European banks now manage infrastructure through version-controlled declarative specifications rather than imperative scripts. This shift compresses incident recovery times from hours to minutes while reducing configuration drift.
The EU AI Act's risk-based classification system imposes documentation burdens on high-risk automated decision systems. Orchestration vendors must now embed model cards, data lineage trackers, and human-in-the-loop checkpoints within workflow definitions. Financial services deployments in Frankfurt and Paris face the strictest compliance timelines.
FinOps practices are reshaping how platform teams procure cloud infrastructure. Engineering organizations now tag every orchestrated workload with cost-center attribution, triggering automated rightsizing when spend thresholds breach budgets. This behavioral shift is most pronounced in German automotive and industrial conglomerates managing multi-thousand-node Kubernetes estates.
Service Orchestration Market Segmentation
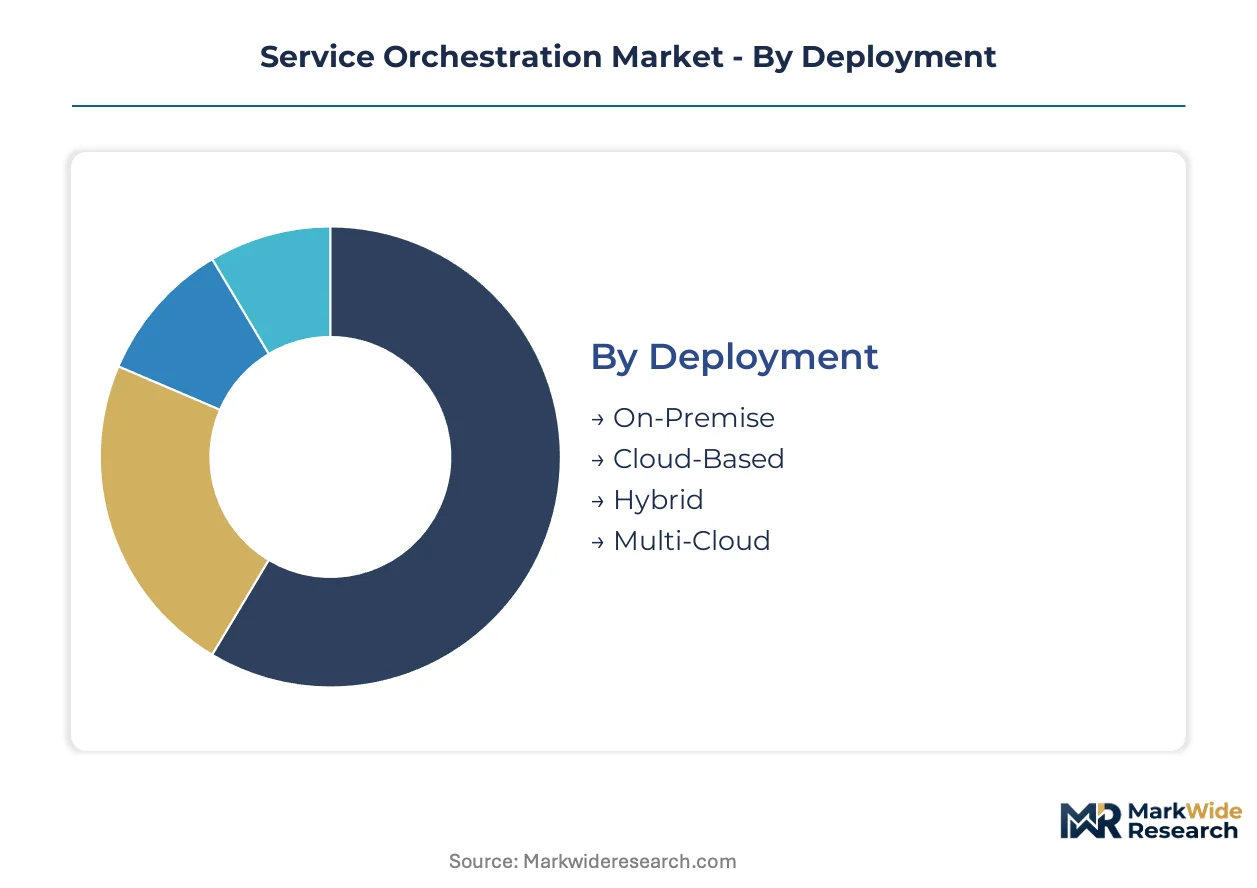
Service orchestration architectures fragment across deployment topologies, service layers, and underlying infrastructure primitives. Each segmentation axis carries distinct margin profiles, compliance burdens, and vendor ecosystem dependencies that reshape procurement decisions.
Deployment:
Supply concentration in cloud-native tooling compresses margins for on-premise hardware vendors while elevating recurring revenue multiples for managed orchestration platforms.
- Cloud-Based:Multi-tenant control planes deliver centralized policy enforcement and elastic capacity scaling without capital expenditure. Financial institutions in Frankfurt and Paris favor this model to satisfy EU AI Act auditability requirements without owning physical infrastructure.
- Hybrid:Workload portability across on-premise data centers and public cloud regions preserves legacy system connectivity while enabling burst capacity. German automotive suppliers deploy hybrid stacks to keep proprietary design data on-site while orchestrating supplier-facing APIs through cloud gateways.
- On-Premise:Dedicated orchestration clusters serve air-gapped environments in defense and critical infrastructure sectors. High fixed costs and extended procurement cycles limit expansion outside regulated verticals.
- Multi-Cloud:Abstraction layers normalize APIs across AWS, Azure, and GCP to prevent vendor lock-in. Complexity premiums drive implementation costs upward, constraining adoption to enterprises with mature platform engineering functions.
Cloud-Based deployments absorb the bulk of installed capacity; Multi-Cloud configurations are expanding most quickly as enterprises diversify supplier risk.
Service Type:
Margin pools deepen where integration complexity intersects with legacy system preservation, creating durable competitive moats for vendors with mainframe connectivity expertise.
- Integration Services:Middleware adapters bridge SOAP-based enterprise systems with RESTful microservices, handling protocol translation and data transformation. BFSI institutions allocate the largest integration budgets to maintain connectivity with core banking platforms.
- Automation Services:Event-driven workflow engines execute conditional logic across distributed services without human intervention. Telecommunications operators deploy these capabilities to automate network slice provisioning.
- Management Services:Lifecycle operations including deployment, scaling, and rollback orchestration for containerized workloads. Platform teams at industrial conglomerates consume these through internal developer portals.
- Monitoring Services:Distributed tracing and telemetry aggregation that correlates logs, metrics, and traces across service boundaries. Healthcare providers mandate these for patient-facing application reliability.
Integration Services command the deepest margin pools; Automation Services are climbing the fastest as AI-augmented decisioning propagates through operational workflows.
End User:
Demand concentration in regulated sectors elevates compliance tooling from optional feature to table-stakes procurement criterion.
- BFSI:Real-time payment orchestration and fraud detection pipelines require sub-second latency with complete audit trails. EU AI Act documentation mandates reshape vendor selection in Frankfurt, Paris, and Amsterdam.
- Telecommunications:5G network slicing and edge service orchestration demand intent-based control planes that span radio access, transport, and core domains. Deutsche Telekom and Vodafone drive standardization through open source reference implementations.
- Healthcare:Patient data sovereignty requirements under GDPR constrain cross-border orchestration flows. ISO/IEC 27001 certification operates as a de facto market access gate.
- Retail:Seasonal demand spikes and omnichannel inventory synchronization prioritize elastic scaling over deep customization. Margin pressure limits willingness to pay for premium orchestration tiers.
BFSI absorbs the bulk of installed capacity; Telecommunications is gaining share fastest as 5G standalone deployments accelerate across European markets.
Technology:
Infrastructure abstraction layers concentrate vendor power where runtime specifications achieve de facto standardization.
- Microservices:Fine-grained service decomposition enables independent deployment velocity and fault isolation. Kubernetes-native service meshes from Linkerd and Istio dominate new implementations.
- Containers:Docker and containerd runtime specifications provide portable packaging for application dependencies. German platform engineering teams treat containerization as a prerequisite for CI/CD maturity.
- API Management:Gateway policies enforce rate limiting, authentication, and transformation at the edge of service architectures. Financial services deployments emphasize Open Banking compliance.
- Serverless:Function-as-a-Service execution eliminates capacity planning overhead for event-driven workloads. Cold-start latency constraints limit applicability to non-user-facing batch processing.
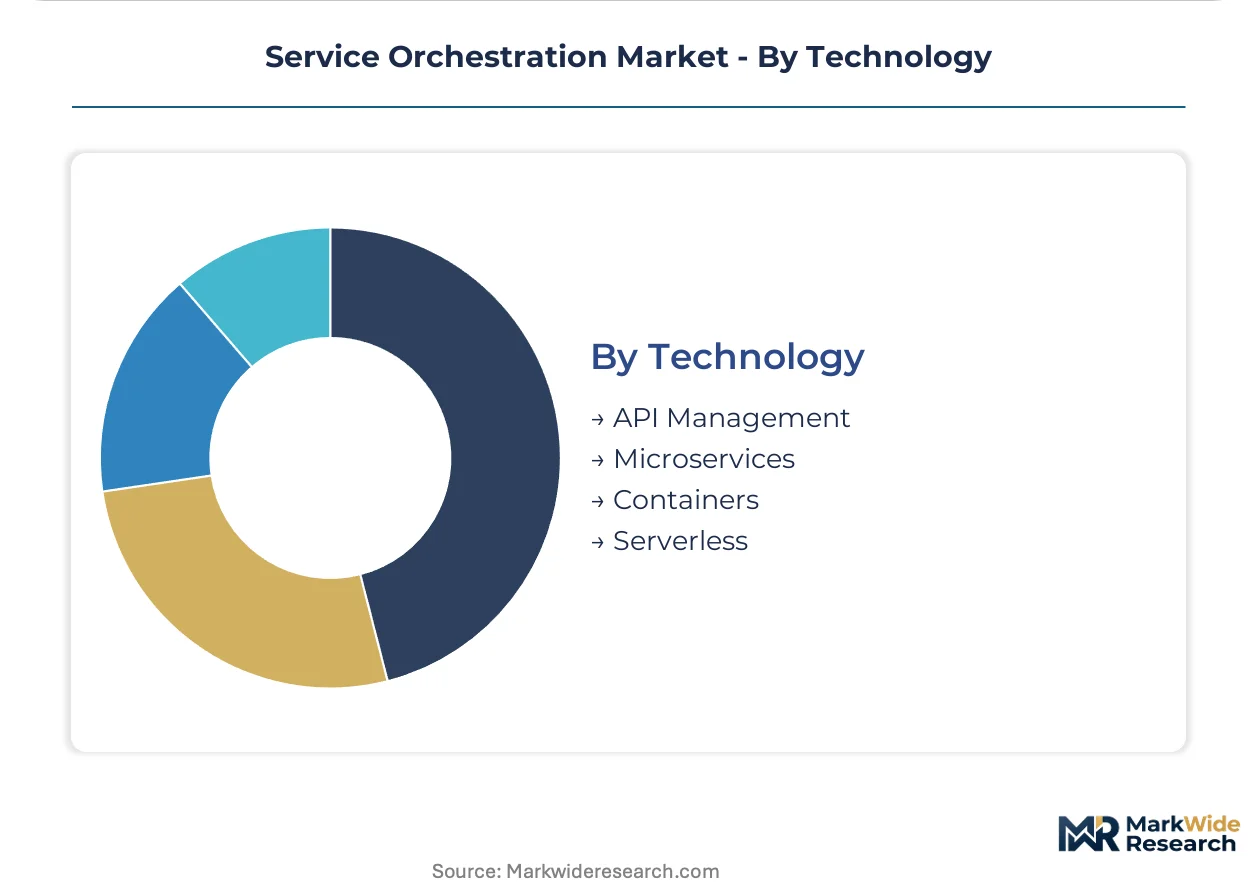
Containers hold the bulk of installed capacity; Microservices architectures are expanding most quickly as monolithic decomposition accelerates through platform engineering mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Financial institutions in Germany and telecommunications operators across Western Europe concentrate near-term demand for compliant orchestration platforms. National cloud sovereignty mandates fragment procurement patterns across the continent.
Germany
Mittelstand manufacturers and automotive suppliers drive cloud migration spending. The EU AI Act imposes strict documentation requirements on automated decision systems used in Frankfurt's banking sector. Bavarian industrial clusters in Munich and Stuttgart deploy edge orchestration for factory-floor latency requirements.
United Kingdom
London-based fintechs and legacy banks compete for Kubernetes-certified platform engineering talent. GDPR enforcement through the Information Commissioner's Office shapes cross-border data flow architectures. The Thames Valley technology corridor hosts concentrated service mesh deployments for financial services workloads.
France
Parisian banking groups modernize core systems under regulatory pressure from ANSM and CNIL oversight. The national cloud certification scheme prevents seamless multi-tenant deployments with German counterparts. Île-de-France hosts the densest concentration of ISO/IEC 27001-certified orchestration providers.
United States
Enterprise platform engineering teams at Fortune 500 companies expand GitOps adoption. FCC network reliability standards influence telecommunications-grade orchestration architectures. Seattle and San Francisco Bay Area clusters concentrate site reliability engineering expertise at wage premiums exceeding forty percent.
India
Bangalore-based technology services firms supply Kubernetes architecture talent to global financial institutions. RBI guidelines on data localization constrain cloud orchestration strategies for domestic banks. Hyderabad's HITEC City corridor specializes in mainframe-to-cloud integration services for overseas BFSI clients.
Service Orchestration Market Key Industry Players
North American technology conglomerates anchor the enterprise platform tier; European specialists hold regulated verticals through compliance depth. Market structure tilts toward consolidated control in cloud-native tooling alongside persistent fragmentation in legacy integration services. Three archetypes dominate: hybrid cloud portfolio vendors, mainframe connectivity specialists, and IT service management workflow extenders. Competitive moves concentrate on strategic partnerships with telecommunications operators and portfolio diversification into edge orchestration capabilities.
Within the hybrid cloud portfolio tier, IBM occupies a position exemplifying mainframe-to-cloud bridge architectures. BMC Software represents the mainframe connectivity specialist archetype through sustained z/OS integration capabilities. ServiceNow sits within the IT service management workflow extender category, competing through cross-platform orchestration layers that absorb adjacent automation functions.
| Leading Market Players |
|---|
| IBM |
| BMC Software |
| Stonebranch |
| Cisco Systems |
| Hewlett Packard Enterprise |
| Ericsson |
| ServiceNow |
| ActiveBatch |
| Redwood Software |
| Others |
Cost & Logistics Intelligence
ISO/IEC 27001 certification tiers create a pronounced bifurcation between premium-compliant orchestration platforms and commodity alternatives, with certified vendors commanding sustained margin premiums while uncertified suppliers face pricing compression from security-conscious buyers in Frankfurt and Paris.
Pricing Analysis
Volume concentrates in subscription-based SaaS tiers while margin pools deepen in project-based integration engagements. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and legacy system connectivity depth. Cost compression in the economy tier is intensifying because cloud-native entrants erode per-seat pricing. Healthcare and government segments show least price sensitivity due to compliance mandates, while retail buyers resist premium tiers.
Supply Chain Analysis
Dual-sourcing requirements from Deutsche Telekom and Vodafone mandate multi-supplier qualification for orchestration control plane components. Supply concentrates in the United States, Germany, and India for platform engineering talent and Kubernetes-native tooling. Component dependencies include service mesh proxies, API gateway appliances, and legacy mainframe adapters. Single-source vulnerability persists for IBM z/OS connectivity expertise. Distribution runs through direct enterprise sales with systems integrator overlays.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market consolidation accelerates as EU AI Act compliance costs force sub-scale vendors toward exit or acquisition, rewarding platforms with embedded audit capabilities.
For Market Incumbents: Deepen mainframe-to-cloud integration moats through captive development of IBM z/OS adapters. Expand ISO/IEC 27001 certification coverage into edge orchestration modules before emerging entrants achieve compliance parity. The EU AI Act documentation burden threatens margin erosion for unprepared platforms.
For New Entrants and Emerging Players: The EU AI Act in Germany opens a window for compliance-native architectures that embed audit logging from inception. Target Mittelstand manufacturers in Stuttgart and Wolfsburg with edge orchestration solutions for sub-10-millisecond factory-floor requirements. Lead with GitOps-native deployment models to differentiate from legacy imperative competitors.
For Investors and Strategic Acquirers: Re-rating potential sits with mainframe connectivity specialists given persistent legacy integration tax burdens in BFSI institutions. Long-term viability favors vendors with durable certification barriers and telecommunications operator relationships. Watch Deutsche Telekom and Vodafone procurement decisions as inflection indicators for edge orchestration demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Absorbing adjacent IT service management workflows strengthens cross-sell into existing ServiceNow deployments. |
| Strategic Partnership | Telecommunications alliances with Deutsche Telekom validate intent-based orchestration for 5G network slicing. |
| Acquisition of Specialist Firm | Mainframe connectivity targets in Hyderabad address 60-70 percent integration budget concentration in BFSI. |
| Geographic Expansion | Bavarian industrial clusters in Munich require localized edge orchestration for manufacturing latency requirements. |
| Product Launch | CSRD-aligned sustainability tracking modules capture EU Corporate Sustainability Reporting Directive workflow demand. |
Research Approach
Document review covered SEC filings from orchestration vendors, hyperscaler capex disclosures, and EU regulatory guidance, complemented by interviews with platform engineering directors at European banks, site reliability engineering leads at telecommunications operators, IT procurement officers in automotive supply chains, and compliance officers navigating EU AI Act implementation. Secondary sources included Kubernetes ecosystem documentation, ISO/IEC 27001 certification databases, and BFSI technology spend surveys. Bottom-up deployment estimates triangulated against top-down market sizing.
Cross-referencing historical adoption curves against expert panel inputs anchored growth projections across the analysis window. Segmentation dimensions modeled include deployment topology, service layer, end-user vertical, and infrastructure technology primitive. CAGRs derived from weighted average of technology diffusion rates and regulatory enforcement timelines. Kubernetes penetration curves and mainframe modernization spend patterns served as primary demand indicators.
The model assumes a particular technology adoption path; alternative pathways for serverless function-as-a-service execution would alter the outlook if cold-start latency constraints resolve faster than projected. Deviation in EU AI Act enforcement intensity or sovereign cloud certification fragmentation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Cloud Supply Chain Management Market
Digital Solutions
Global Ad Tech Software Market
Digital Solutions
Workflow Management System Market
Digital Solutions
Cloud Based Drug Discovery Platform Market
Digital Solutions
Laser Page-Turning Pen Market
Digital Solutions
Event Apps Market
Digital Solutions
Electronic Records Management Solutions Market
Digital Solutions
Kuwait ICT Market
Digital Solutions
Europe Content Moderation Services Market
Digital Solutions
Kenya ICT Market
Digital Solutions
Japan Digital Twin Market
Digital Solutions
Global E-Signature Platform Market
Digital Solutions
Global Corporate Volunteering Platform Market
Digital Solutions
Europe Digital Twin Market
Digital Solutions
Global Capacity Management Market
Digital Solutions
Smart Dictation Systems Market