
 Hungary ICT Market | 2026-2036
Hungary ICT Market Size, Share, and Industry Trends Forecast 2026-2036
Hungary ICT Market Insights
GDPR enforcement is expanding the cost-of-entry calculus for data processors serving Hungarian enterprises. Magyar Telekom leverages its fiber backbone to dominate enterprise connectivity in Budapest and regional hubs. 4iG anchors its position through aggressive infrastructure consolidation across fixed and mobile assets. Microsoft Corporation competes by embedding Azure cloud services into public sector digitalization frameworks.
Information and communications technology in Hungary encompasses hardware systems, software platforms, telecommunications infrastructure, and digital services governed by EU interoperability standards and national cybersecurity protocols. The sector functions as the operational backbone for financial services, automotive supply chains, and public administration digitization. Software and cloud services capture expanding margin pools as Hungarian SMEs migrate from on-premise legacy systems. Hardware retains structural importance in data center buildouts driven by hyperscaler entry and domestic cloud sovereignty requirements. Cybersecurity services are accelerating fastest as NIS2 transposition raises baseline obligations for critical infrastructure operators.
BIS, the EU AI Act, and Hungary's National Cybersecurity Strategy shape compliance timelines and procurement specifications for ICT vendors. The EU AI Act imposes conformity assessment requirements on high-risk AI deployments in public administration and financial scoring, redirecting vendor development resources. Stakeholders must monitor transposition speed of the NIS2 directive into Hungarian law and align service portfolios with emerging supervisory expectations from the national cybersecurity authority.
Market Dynamics
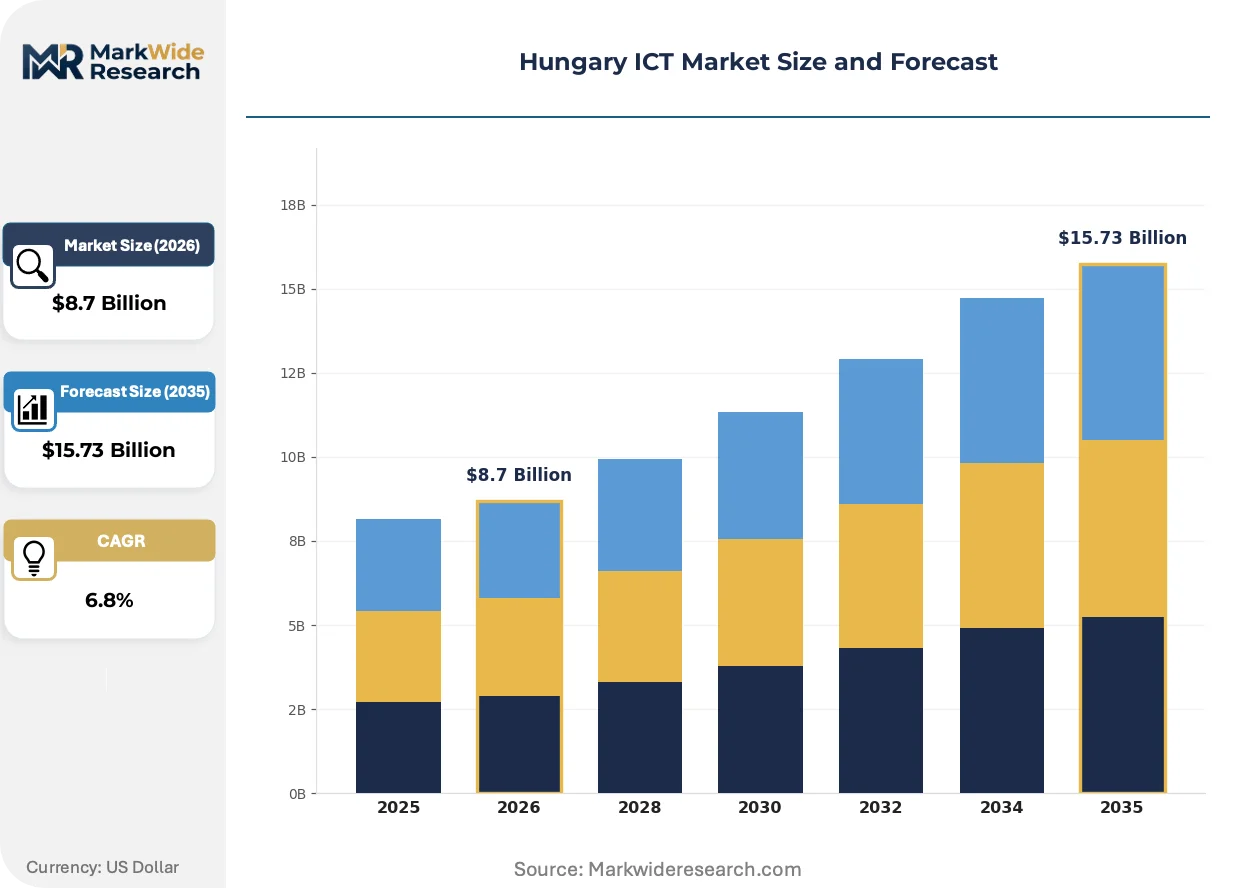
Cloud migration momentum across Hungarian enterprises is restructuring procurement patterns, as legacy infrastructure depreciation cycles collide with EU AI Act compliance deadlines and hyperscaler data center commitments.
Growth Catalysts
- EU AI Act Conformity Assessments:High-risk AI deployments in public administration and financial scoring create mandatory vendor certification requirements, expanding serviceable addressable market for compliance-ready ICT providers.
- NIS2 Directive Transposition:Hungary's cybersecurity authority is elevating baseline obligations for critical infrastructure operators, accelerating managed security services procurement across energy and transport verticals.
- Budapest Technology Corridor Concentration:Enterprise demand clusters in the capital region, enabling infrastructure providers to achieve route density economics in fiber and data center interconnectivity.
Market Restraints
- GDPR Enforcement Escalation:Hungarian data protection authority penalties are expanding cost-of-entry calculus for data processors, particularly affecting mid-market SaaS entrants without dedicated compliance functions.
- Skilled Labor Pool Constraints:Cybersecurity and cloud architecture expertise concentrates in Budapest, creating wage inflation and recruitment bottlenecks for regional deployment scaling.
- Hyperscaler Infrastructure Lock-In:Public sector digitalization frameworks embedded with Azure create switching friction and margin compression for domestic alternative cloud providers.
Strategic Opportunities
- Debrecen and Szeged Secondary Hubs:Underpenetrated regional cities outside Budapest offer first-mover advantages for edge computing nodes and enterprise connectivity buildouts.
- AI Sovereignty Requirements:National cybersecurity protocols and EU data localization norms are creating demand for domestic language model training infrastructure and sovereign cloud instances.
- Automotive Supply Chain Digitization:Electrification and connected vehicle programs at Hungarian manufacturing plants are pulling industrial IoT and private 5G network deployments.
Industry Challenges
- Legacy System Integration Complexity:SME migration from on-premise enterprise resource planning systems to cloud-native platforms requires costly middleware development and change management.
- NIS2 Certification Timeline Compression:Critical infrastructure operators face compressed compliance windows, straining vendor capacity to deliver assessed security architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hungary ICT Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, Services, Consulting End User: SMEs, Corporations, Government, Education Service Type: Cloud Services, IT Support, Managed Services, Cybersecurity Technology: AI, IoT, Big Data, Blockchain |
| Companies Covered | 4iG, Magyar Telekom, Yettel, One, Tata Consultancy Services, SAP SE, Oracle Corporation, Microsoft Corporation, IBM Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hungary ICT Market Trends and Innovations
Generative AI capabilities are penetrating Hungarian enterprise workflows, while regulatory frameworks harden around algorithmic accountability and data sovereignty requirements.
Multimodal large language models are integrating into Hungarian public sector document processing and citizen service interfaces. Government agencies in Budapest are piloting automated case management systems. This capability compression is reducing headcount requirements in administrative functions while elevating integration complexity for ICT vendors.
The EU AI Act imposes conformity assessment requirements on high-risk algorithmic systems deployed in financial scoring and public benefits administration. Hungarian regulators are aligning national supervisory expectations with Brussels timelines. Financial institutions are restructuring procurement specifications to prioritize vendors with established EU-notified body certifications.
Enterprise buyers are consolidating vendor relationships around integrated platform providers capable of delivering infrastructure, security, and application layers under unified service level agreements. This preference compression disadvantages point-solution specialists. Manufacturing and automotive verticals in western Hungary are most advanced in this consolidation pattern.
Hungary ICT Market Segmentation
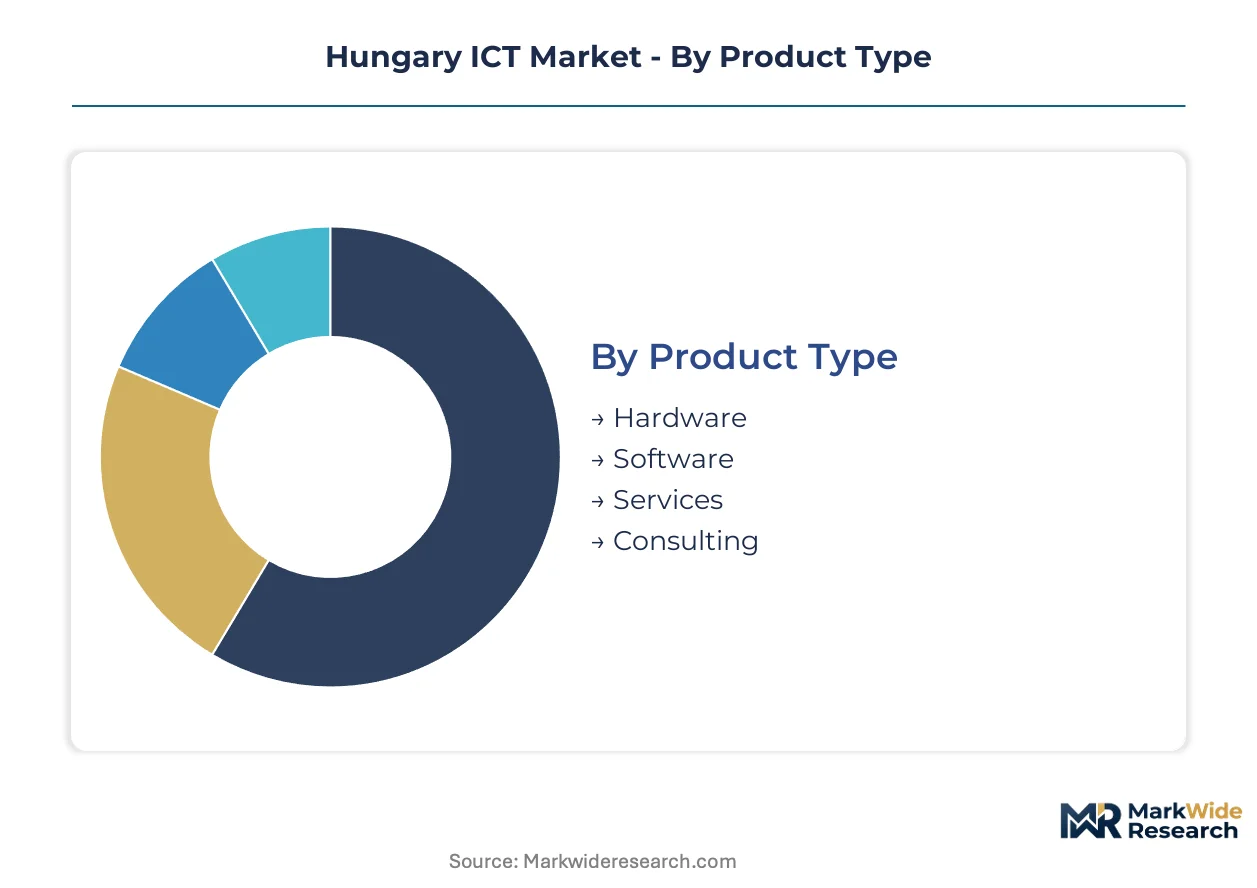
Segmentation in Hungary's ICT market exposes divergent procurement patterns between Budapest's enterprise corridor and regional deployments. Hardware and software categories split along cloud migration timelines, while service demand concentrates where EU AI Act and NIS2 compliance deadlines create urgency.
Product Type:
Standardization dominates hardware procurement, while software and services tilt toward customization as Hungarian enterprises navigate legacy system constraints.
- Hardware:Servers, networking equipment, and endpoint devices form the physical layer. Data center buildouts in Budapest and Debrecen drive demand for high-density compute infrastructure as hyperscalers establish local presence.
- Software:Enterprise resource planning, customer relationship management, and vertical applications constitute this segment. SMEs across Hungary's western manufacturing belt are displacing on-premise licenses with subscription models.
- Services:Implementation, integration, and maintenance contracts support technology deployment. Public sector digitalization frameworks in Budapest generate multi-year service agreements with strict EU interoperability requirements.
- Consulting:Strategic advisory and change management expertise. EU AI Act readiness assessments and NIS2 gap analyses are climbing fastest among critical infrastructure operators.
Most installed capacity flows through Hardware. Expansion is steepest in Software.
End User:
Volume concentrates in large enterprises, though margin pools favor specialized segments where compliance complexity elevates pricing power.
- SMEs:Fragmented demand across Hungary's regional cities. Cloud migration acceleration in Szeged and Pécs is creating procurement clusters outside Budapest's orbit.
- Corporations:Multinational manufacturing and financial services anchor this tier. Automotive supply chain digitization at Hungarian plants is pulling industrial IoT and private network investments.
- Government:Central and municipal administration procurement. EU fund absorption requirements and cybersecurity protocols structure tender specifications toward certified vendors.
- Education:Universities and vocational training institutions. Research computing infrastructure at Budapest technical universities is driving high-performance computing demand.
Government channels carry the highest contract values. SMEs are gaining share fastest as cloud economics democratize enterprise-grade capabilities.
Service Type:
Margin distribution follows risk transfer intensity, with outcomes-based pricing expanding where vendors assume operational accountability.
- Cloud Services:Infrastructure-as-a-service, platform-as-a-service, and software-as-a-service delivery models. Hungarian enterprises are consolidating around hybrid architectures to satisfy data sovereignty requirements.
- IT Support:Break-fix and helpdesk operations. Regional dispersion of Hungarian manufacturing is forcing support network restructuring beyond Budapest concentration.
- Managed Services:Outsourced infrastructure and application management. NIS2 transposition is elevating managed security service demand across energy and transport operators.
- Cybersecurity:Threat detection, incident response, and compliance advisory. Hungary's national cybersecurity authority supervision is mandating baseline capabilities for critical infrastructure.
Cloud Services absorb the largest procurement budgets. Cybersecurity is expanding most quickly as regulatory baselines harden.
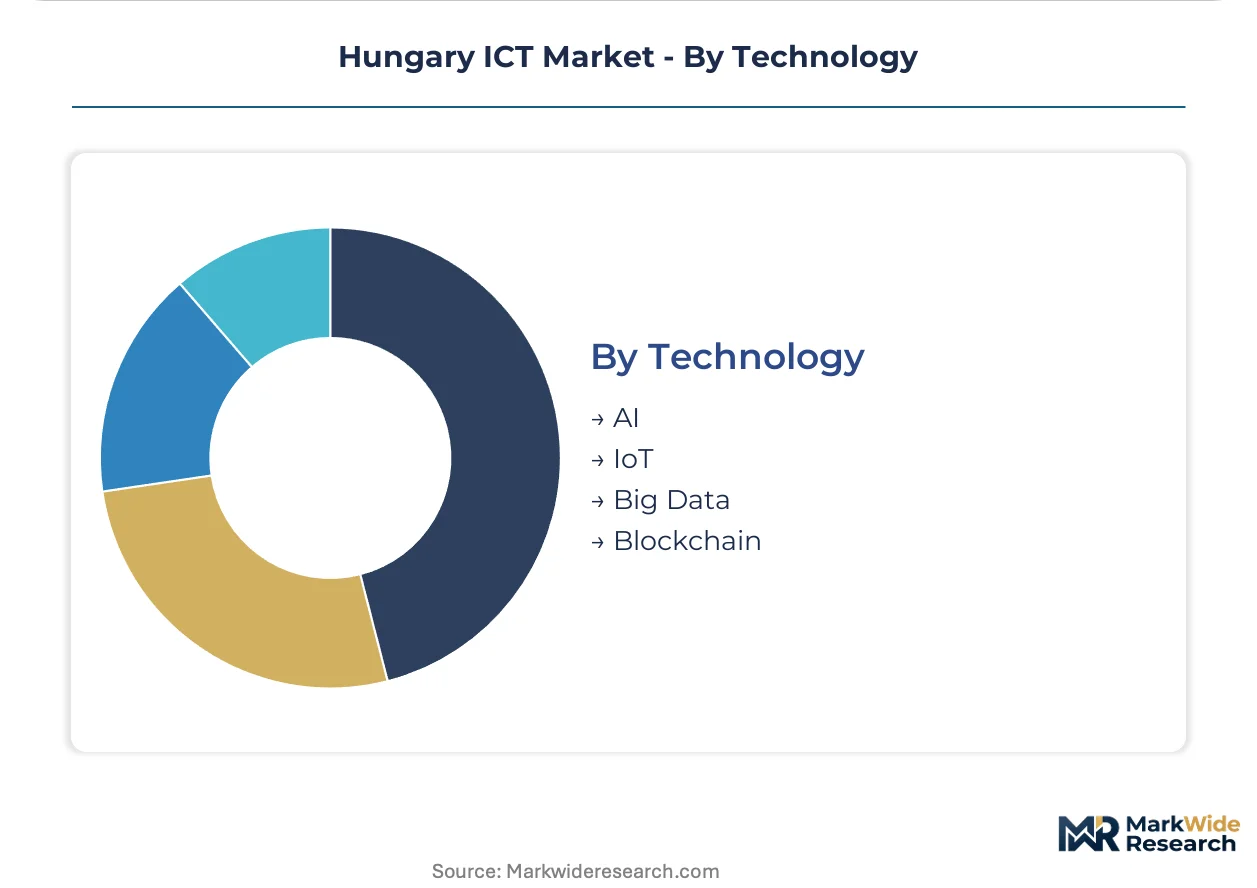
Technology:
Adoption maturity separates experimental deployments from production-scale implementations across Hungarian enterprise verticals.
- AI:Machine learning and generative AI capabilities. EU AI Act conformity assessments are restructuring vendor selection criteria for public administration and financial scoring applications.
- IoT:Connected sensors and edge computing infrastructure. Automotive manufacturing plants in western Hungary are deploying private 5G networks to support real-time quality monitoring.
- Big Data:Analytics platforms and data lake architectures. Hungarian financial institutions are consolidating disparate data silos to support real-time risk scoring.
- Blockchain:Distributed ledger for supply chain and identity verification. Pilot programs in Hungarian customs and trade finance remain limited by interoperability constraints.
Big Data platforms carry the deepest installed base. AI is climbing the fastest as generative capabilities penetrate document processing workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Technical talent pools in Budapest anchor Hungary's ICT expansion, drawing hyperscaler investments and enterprise procurement concentration into the capital corridor.
Budapest and Central Hungary
Enterprise cloud migration and public sector digitalization drive procurement volume. The National Cybersecurity Authority enforces NIS2 baseline obligations for critical infrastructure operators. Government agencies pilot automated case management systems using generative AI capabilities.
Debrecen
Automotive electrification programs pull industrial IoT and private 5G network deployments. EU fund absorption requirements structure tender specifications toward certified vendors. Edge computing nodes emerge as first-mover opportunities outside the capital concentration.
Szeged
Regional cloud procurement clusters form as SME migration accelerates. GDPR enforcement by the Hungarian data protection authority elevates compliance costs for mid-market SaaS entrants. University research computing infrastructure drives high-performance computing demand.
Pécs
Manufacturing supply chain digitization creates procurement pull for connected sensor networks. EU AI Act conformity assessment deadlines compress vendor certification timelines. Regional support network restructuring extends beyond Budapest talent concentration.
Győr and Western Hungary
Automotive supply chain digitization anchors industrial IoT deployments. Financial institutions consolidate data silos to support real-time risk scoring. Manufacturing verticals lead vendor consolidation around integrated platform providers.
Hungary ICT Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Hungary's ICT procurement landscape. The vendor base organizes around infrastructure ownership, platform integration, and compliance advisory capabilities. Three strategic archetypes dominate: telecommunications incumbents with fiber backbone assets, hyperscale cloud providers embedding into public sector frameworks, and system integrators managing legacy-to-cloud transitions. Competitive moves concentrate on infrastructure consolidation and strategic partnerships with automotive manufacturers.
Within the telecommunications tier, Magyar Telekom and 4iG anchor enterprise connectivity through fiber and mobile asset positions. Microsoft Corporation exemplifies hyperscale platform integration, occupying a central role in public sector digitalization frameworks. These three represent the dominant competitive archetypes shaping procurement patterns across Budapest's technology corridor and regional manufacturing hubs.
| Leading Market Players |
|---|
| 4iG |
| Magyar Telekom |
| Yettel |
| One |
| Tata Consultancy Services |
| SAP SE |
| Oracle Corporation |
| Microsoft Corporation |
| IBM Corporation |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal compliance mandates gate qualified supply access and premium-tier pricing power for ICT vendors serving Hungarian enterprises, as carbon disclosure requirements and circular economy standards filter hardware procurement eligibility and elevate certified service premiums.
Pricing Analysis
The bundled-vs-unbundled service split defines pricing architecture across Hungarian enterprise ICT procurement. Subscription SaaS tiers dominate software delivery, while project-based consulting commands premiums for EU AI Act readiness assessments. Price differentiation rests on certification grade—vendors with EU-notified body credentials extract 15-30% uplifts—and vertical integration depth in security operations. Cost compression in mid-market SaaS is intensifying because GDPR enforcement escalates compliance overhead. SMEs exhibit highest price sensitivity; government channels absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for server and networking hardware, while tiered distribution serves fragmented SME procurement across regional Hungarian cities. Manufacturing concentration centers on Taiwan, China, and South Korea for semiconductor components and high-density compute infrastructure. Raw material dependencies span rare earth elements for magnetic storage, advanced substrates for chip packaging, and lithium-ion cells for uninterruptible power systems. Single-source vulnerability in advanced GPU supply creates procurement risk for AI training infrastructure. Distribution runs through authorized value-added resellers and systems integrators with NIS2 certification credentials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, as EU AI Act conformity requirements and NIS2 cybersecurity baselines redirect procurement toward certified vendors with proven compliance architectures.
For Market Incumbents: Acquire managed security service capabilities to anchor recurring revenue streams as NIS2 mandates expand addressable market for outsourced cybersecurity operations. Consolidate fiber assets in Debrecen and Szeged secondary hubs before hyperscalers establish edge presence. Certification investment in EU-notified body AI assessment credentials represents the critical defensive lever against emerging compliance-ready specialists. For New Entrants and Emerging Players: Cloud-native channel routes into underpenetrated regional manufacturing corridors offer lowest customer acquisition costs outside Budapest's saturated enterprise corridor. Target industrial IoT deployments at automotive electrification programs in Győr and western Hungary, where private 5G network demand outpaces incumbent delivery capacity. Partner with established systems integrators holding existing government framework agreements to bypass tender qualification barriers. For Investors and Strategic Acquirers: Roll-up economics work for specialized cybersecurity boutiques because NIS2 transposition fragments compliance service demand across energy, transport, and healthcare verticals with divergent supervisory expectations. Long-term viability hinges on platform consolidation around integrated infrastructure-security-application stacks. Monitor Hungarian cybersecurity authority enforcement velocity as inflection indicator for managed services valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Certification Investment | EU-notified body credentials unlock high-risk AI deployment contracts in Budapest public administration. |
| Regional Edge Computing Buildout | Debrecen and Szeged nodes capture automotive and university research computing demand outside capital concentration. |
| Managed Security Service Expansion | NIS2 baseline obligations for critical infrastructure operators accelerate outsourced cybersecurity procurement across energy verticals. |
| Hyperscaler Partnership Structuring | Azure and AWS framework integrations embed vendors into public sector digitalization tenders with multi-year visibility. |
| Automotive Supply Chain Digitization | Industrial IoT and private 5G deployments at Hungarian manufacturing plants pull specialized integration expertise. |
Research Methodology
Bottom-up enterprise ICT procurement modeling reconciled against top-down hyperscaler infrastructure tracking forms the analytical core. Primary interviews with CTOs, IT procurement officers, national cybersecurity authority officials, and systems integration specialists informed demand-side calibration. Secondary validation drew from EU AI Act implementation timelines, NIS2 transposition documents, Hungarian public procurement databases, and hyperscaler data center capex disclosures. Triangulation across these sources anchored segmentation-specific penetration assumptions.
Input-output matrices mapped hardware, software, and services demand against end-user size tiers, technology adoption maturity, and regional deployment patterns across the projection horizon. Segmentation dimensions modeled include product type, end-user category, service delivery model, and technology adoption stage. CAGRs derived from installed base depreciation cycles colliding with compliance deadline acceleration and cloud migration S-curve positioning. Forecast inputs incorporated EU fund absorption rates and automotive electrification program timelines.
The model assumes a particular technology adoption path; alternative pathways for generative AI deployment would alter the outlook if EU AI Act enforcement delays or accelerates beyond baseline expectations. Forecasts reflect documented assumptions regarding NIS2 transposition speed and hyperscaler localization commitments. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Global Virtual PBX Market
Telecommunications
Private LTE in Mining Industry Market
Telecommunications
Rich Communication Services (RCS) Market
Telecommunications
Hong Kong Telecom Market
Telecommunications
Explosion Proof Mobile Communication Devices Market
Telecommunications
United States Mobile Virtual Network Operator (MVNO) Market
Telecommunications
Nigeria Telecom Market
Telecommunications
Mobile Voice Market
Telecommunications
IoT MVNO (Services) Market
Telecommunications
Prepaid Communication Market
Telecommunications
France Telecom Market
Telecommunications
5G Equipment Market
Telecommunications
Telecom Radio System Software Market
Telecommunications
Poland Telecom Market
Telecommunications
Portable Base Station (PBS) Market
Telecommunications
CDMA Mobile Phone Market