
 RF Power Dividers Market | 2026-2036
RF Power Dividers Market Size, Share, and Industry Trends Forecast 2026-2036
RF Power Dividers Market Intelligence
China's semiconductor packaging corridor is reconfiguring regional supply dynamics for passive RF components. Mini-Circuits leverages broad catalog depth and domestic US manufacturing to sustain price competitiveness in standard power divider lines. Marki Microwave specializes in broadband and millimeter-wave designs, occupying premium niches where performance specifications tighten. ETL Systems anchors broadcast and satellite ground segment demand with hardened designs for outdoor infrastructure.
RF power dividers are passive microwave components that split an incoming signal into multiple output paths with controlled amplitude and phase relationships, typically operating from DC through millimeter-wave frequencies with insertion loss below 0.5 dB in premium designs. These devices enable antenna array feeds, test instrumentation, and signal distribution networks where phase coherence and power balancing determine system performance. Wilkinson dividers dominate high-isolation applications in telecommunications base stations and defense radar, while resistive dividers serve test and measurement environments where flat frequency response outweighs insertion loss penalties. Reactive and directional coupler technologies capture aerospace and research institution demand where power handling and thermal stability justify higher unit costs. Coaxial form factors remain the volume standard, though integrated and miniature variants gain traction in phased array and software-defined radio platforms.
FCC Part 15 emissions standards and ITAR export controls shape product qualification requirements and market access for US-based manufacturers serving defense end users. CE marking under the EU Radio Equipment Directive and REACH material compliance obligations govern European commercial and aerospace procurement channels. Stakeholders must monitor evolving spectrum allocation decisions by national regulators and the trajectory of Open RAN disaggregation standards, as these will determine whether integrated or modular divider architectures prevail in next-generation network deployments.
Market Dynamics
The transition to Open RAN architectures and 5G-Advanced deployments is fragmenting traditional integrated radio designs, forcing component suppliers to modularize power divider specifications for disaggregated base station procurement.
Growth Catalysts
- NATO defense procurement expansion:Electronic warfare and radar modernization programs across member states are specifying high-isolation Wilkinson dividers for phased array antenna feeds.
- FCC spectrum reallocation:Mid-band auction proceeds are funding 5G infrastructure builds requiring broadband power dividers capable of covering 3.7-3.98 GHz C-band allocations.
- Millimeter-wave test equipment:Semiconductor R&D labs in Taiwan and South Korea are sourcing ultra-broadband resistive dividers for 5G NR and 6G prototype validation.
Market Restraints
- Aluminum and copper price volatility:Raw material swings compress margins on coaxial housing production, particularly affecting standard catalog lines with thin pricing buffers.
- China packaging corridor concentration:Surface-mount and chip-scale divider assembly capacity clusters in Jiangsu and Guangdong provinces, creating single-source vulnerability for fabless designers.
- ITAR export licensing friction:US State Department classification reviews delay delivery timelines for defense-qualified components, pushing NATO buyers toward European alternative suppliers.
Strategic Opportunities
- India telecom infrastructure buildout:Reliance Jio and Bharti Airtel 5G rollouts are generating demand for cost-optimized power dividers in massive MIMO antenna configurations.
- Satellite ground segment expansion:Low-earth orbit constellation gateway deployments require hardened outdoor-rated dividers with thermal cycling resilience.
- EU Green Deal procurement criteria:REACH-compliant material declarations and conflict mineral traceability are becoming mandatory in European aerospace tenders, favoring suppliers with documented supply chain transparency.
Industry Challenges
- Millimeter-wave design talent scarcity:Electromagnetic simulation expertise for 28 GHz and 39 GHz broadband matching networks concentrates among senior engineers at a handful of specialized firms.
- Open RAN certification timelines:O-RAN Alliance interoperability testing extends product qualification cycles by six to nine months before network operator approval.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | RF Power Dividers Market |
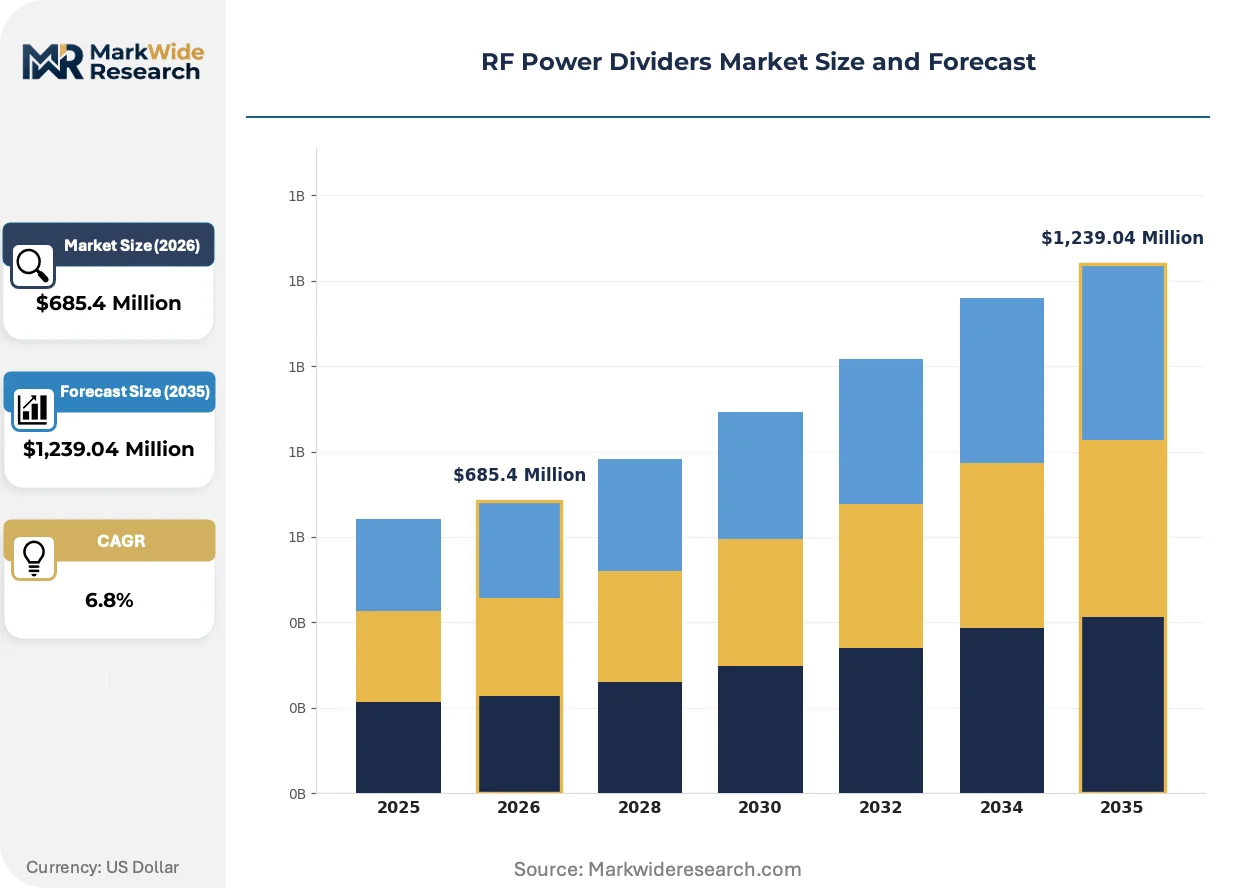
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Form Factor: Miniature, Coaxial, Rack-Mount, Integrated Technology: Directional Couplers, Resistive Dividers, Reactive Dividers, Wilkinson Dividers End User: Telecommunications, Aerospace, Defense, Research Institutions Power Rating: Low Power, Medium Power, High Power, Ultra High Power |
| Companies Covered | Marki Microwave, TTM Technologies, Analog Devices, API Technologies, ETL Systems, MACOM, Mini-Circuits, L3 Narda-MITEQ, Rohde & Schwarz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RF Power Dividers Market Strategic Shifts & Innovations
RF power divider architectures are converging with semiconductor packaging roadmaps, creating pressure to miniaturize while preserving power handling and phase stability across wider instantaneous bandwidths.
Silicon-glass interposer technology is hybridizing traditional coaxial divider functions into wafer-level packages. Defense prime contractors in the United States are qualifying these integrated solutions for software-defined radio platforms. The approach is hybridizing the boundary between discrete passive components and monolithic microwave ICs, compressing supplier margins on conventional connectorized products.
REACH substance restrictions on hexavalent chromium plating are forcing redesigns of brass and aluminum housing finishes. European aerospace and broadcast equipment manufacturers now specify nickel-palladium-gold surface treatments or stainless steel alternatives. German satellite ground station integrators have accelerated vendor qualification programs to verify long-term corrosion resistance under these new material constraints.
Consolidated buying by tier-one network equipment manufacturers is compressing distributor roles in RF component procurement. Direct vendor-managed inventory agreements now cover high-volume power divider SKUs for 5G base station production. This pattern is most pronounced in South Korea, where Samsung Networks and domestic subcontractors have integrated passive component sourcing into centralized commodity management functions.
RF Power Dividers Market Segmentation
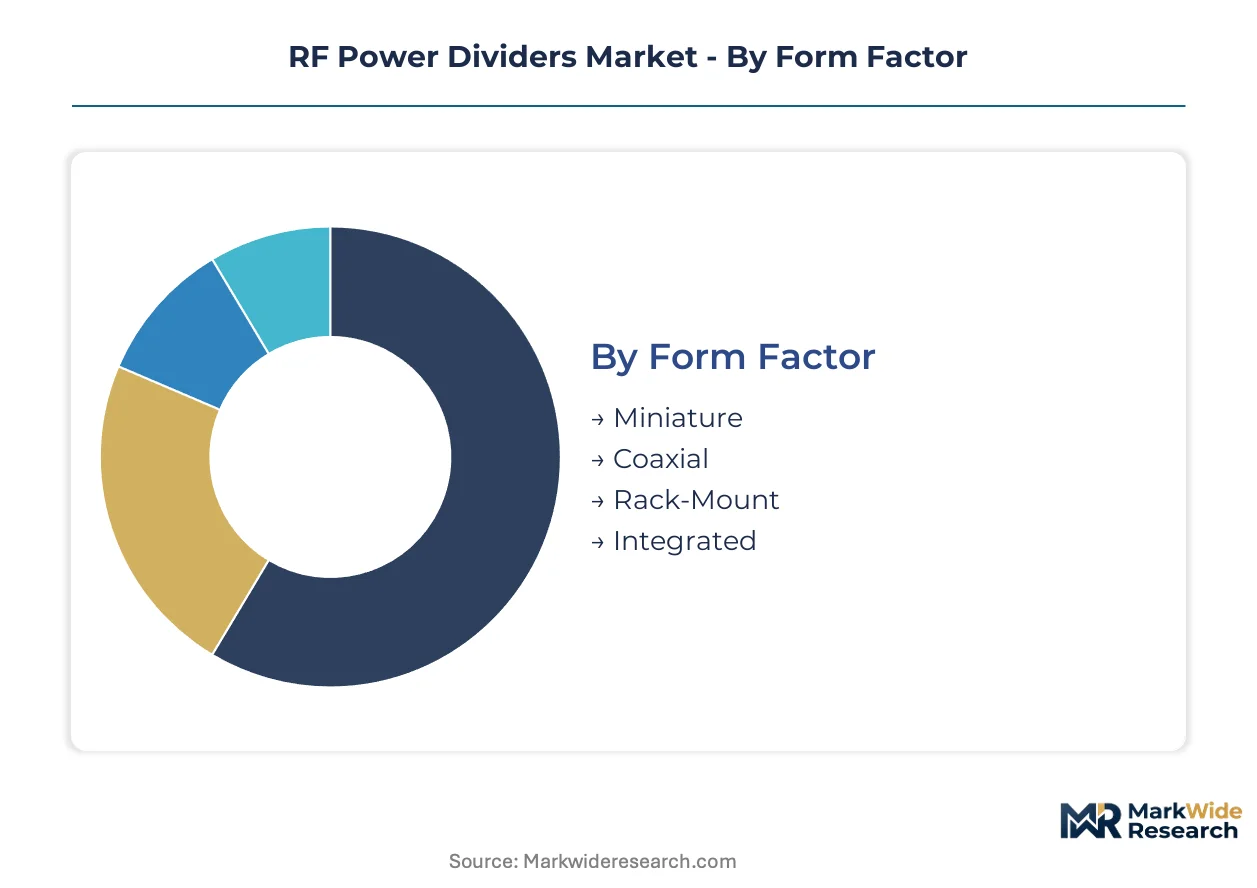
RF power divider procurement patterns diverge sharply across deployment environments, with field-replaceable requirements driving specification trade-offs between connectorized durability and integrated miniaturization. Component suppliers must align warranty terms and technical support depth to the operational criticality of each segment.
Form Factor:
After-sales service intensity varies dramatically by mechanical packaging, with rack-mount and coaxial variants demanding field engineering support while integrated solutions shift burden to semiconductor foundry relationships.
- Coaxial:Connectorized metal housings with SMA, N-type, or 2.92mm interfaces dominate telecommunications infrastructure and test bench applications. Base station OEMs in South Korea and the United States specify these for field serviceability and hot-swap maintenance protocols. Coaxial holds the largest share; momentum sits with Integrated.
- Integrated:Wafer-level and laminate-based implementations merge divider functions with semiconductor packaging roadmaps. Defense prime contractors in the United States qualify these for software-defined radio platforms where SWAP-C constraints dominate. Supply chain vulnerability concentrates in China's Jiangsu packaging corridor.
- Miniature:Chip-scale and surface-mount devices serve phased array antenna elements and portable electronic warfare systems.
- Rack-Mount:19-inch chassis configurations anchor broadcast transmission facilities and satellite ground segment equipment.
Coaxial maintains installed base dominance; Integrated climbs fastest on aerospace qualification timelines.
Technology:
Cost tier stratification separates premium isolation performance from economy broadband flatness, with Wilkinson architectures commanding qualification premiums in defense channels.
- Wilkinson Dividers:Quarter-wave transmission line structures with isolation resistors achieve 20-30 dB inter-port isolation for phased array feeds. NATO radar modernization programs across Germany, the United Kingdom, and Poland specify these for electronic warfare antenna matrices. FCC Part 15 emissions compliance adds qualification overhead for commercial variants.
- Resistive Dividers:Broadband resistive networks sacrifice insertion loss for frequency flatness from DC through millimeter-wave bands. Semiconductor R&D labs in Taiwan and South Korea deploy these for 5G NR and 6G prototype validation where absolute amplitude accuracy outweighs efficiency penalties.
- Directional Couplers:Coupled-line structures provide sampling ports for power monitoring in base station transmit chains.
- Reactive Dividers:Capacitive and inductive networks optimize for specific narrowband applications with minimal insertion loss.
Wilkinson Dividers anchor defense procurement value; Resistive Dividers expand most quickly on test equipment demand.
End User:
Customer type determines certification burden and contract structure, with defense agencies imposing ITAR compliance and aerospace OEMs demanding REACH material traceability.
- Defense:Electronic warfare and radar programs specify high-reliability components with documented thermal cycling and shock resistance. US State Department export licensing creates delivery friction, pushing NATO buyers toward European alternative suppliers.
- Telecommunications:Open RAN disaggregation and 5G-Advanced deployments fragment procurement across modular base station subsystems. Reliance Jio and Bharti Airtel in India drive volume demand for cost-optimized massive MIMO configurations.
- Aerospace:Satellite ground segment and airborne platforms require hardened outdoor-rated designs with corrosion-resistant finishes.
- Research Institutions:National laboratories and university consortia source ultra-broadband components for experimental physics and wireless communications research.
Defense commands premium pricing; Telecommunications generates steepest volume expansion trajectory.
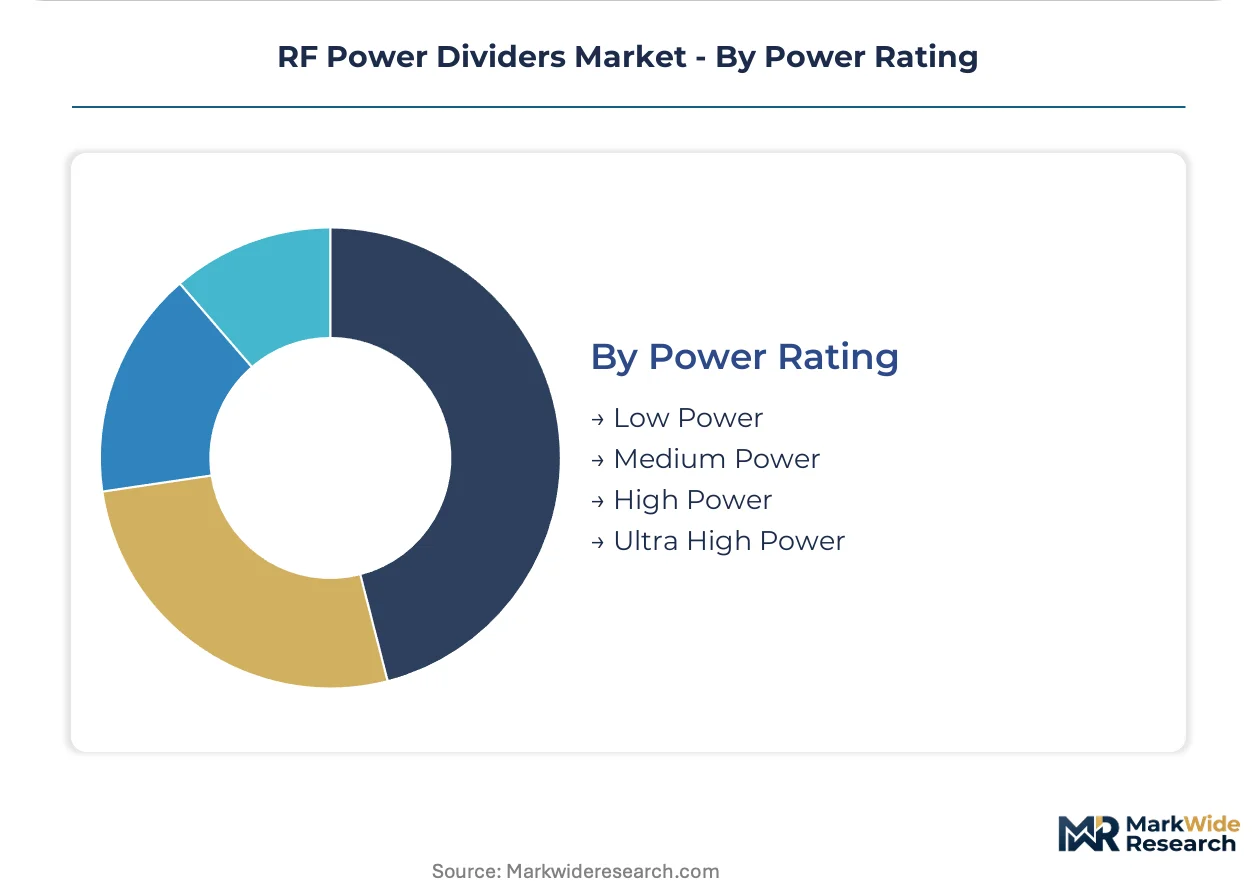
Power Rating:
Margin structure tightens at lower power tiers where catalog competition intensifies, while high-power designs reward thermal engineering expertise with pricing power.
- High Power:Components handling 100W to 1kW serve broadcast transmitters and military radar systems where thermal management determines reliability. Aluminum and copper price volatility compresses margins on housing production for standard catalog lines.
- Low Power:Sub-watt devices dominate consumer test equipment and receive-chain signal distribution. Mini-Circuits leverages domestic US manufacturing to sustain price competitiveness in this commoditized tier.
- Medium Power:1W to 100W range covers cellular base station intermediate power stages and commercial satellite equipment.
- Ultra High Power:Specialized designs above 1kW address unique broadcast and radar applications with extensive customization requirements.
High Power captures value concentration; Low Power faces steepest pricing pressure from Asian manufacturing competition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement agencies in the United States deploy Wilkinson dividers for phased array radar feeds, while semiconductor R&D labs in Taiwan and South Korea source resistive dividers for 5G NR validation—revealing a consumption-mix split between military-grade isolation performance and test-equipment broadband flatness.
United States
Prime contractors in Massachusetts and California drive demand for ITAR-compliant high-isolation dividers in electronic warfare programs. FCC Part 15 emissions standards govern commercial qualification for C-band infrastructure components. The Dallas-Fort Worth metro anchors domestic manufacturing capacity for standard catalog coaxial lines serving telecommunications OEMs.
Germany
Bundeswehr radar modernization specifies REACH-compliant Wilkinson architectures with nickel-palladium-gold surface treatments. The EU Radio Equipment Directive and EU Green Deal procurement criteria mandate documented supply chain transparency for aerospace tenders. Bavarian satellite ground station integrators have accelerated vendor qualification for corrosion-resistant outdoor-rated designs.
China
Jiangsu and Guangdong provinces concentrate surface-mount and chip-scale divider assembly capacity for fabless designers serving 5G base station production. MIIT spectrum allocation decisions shape modular versus integrated architecture preferences in domestic network deployments. Shanghai-based packaging facilities are reconfiguring regional supply dynamics for passive RF components.
South Korea
Samsung Networks and domestic subcontractors have centralized passive component sourcing into commodity management functions for massive MIMO configurations. The Korean Agency for Technology and Standards (KATS) governs electromagnetic compatibility certification for telecommunications infrastructure. Seoul Capital Area semiconductor R&D labs source ultra-broadband resistive dividers for 6G prototype validation.
India
Reliance Jio and Bharti Airtel 5G rollouts generate volume demand for cost-optimized power dividers in disaggregated base station architectures. TRAI spectrum policy and the PLI scheme for telecom equipment manufacturing incentivize domestic assembly partnerships. Karnataka's Bengaluru-Tumkur electronics corridor is emerging as a qualification hub for Open RAN-compliant modular components.
RF Power Dividers Market Key Industry Players
Capability concentration sits with specialized millimeter-wave design houses; scale advantage sits with catalog-depth manufacturers serving high-volume telecommunications procurement. The vendor base organizes into three tiers: premium niche specialists commanding qualification premiums, mid-tier regional fabricators with defense-aerospace focus, and high-volume catalog suppliers competing on price and delivery. Dominant competitive moves include backward integration into semiconductor packaging roadmaps and direct vendor-managed inventory agreements with tier-one network equipment manufacturers.
Among US-based specialists, Marki Microwave and Mini-Circuits occupy distinct positioning vectors—Marki exemplifying the premium broadband and millimeter-wave niche where electromagnetic simulation expertise concentrates, Mini-Circuits representing scale-driven catalog depth sustained by domestic manufacturing cost discipline. ETL Systems anchors the broadcast-satellite ground segment tier with hardened outdoor-rated specializations. Together these three illustrate how supplier archetypes map to end-use procurement requirements rather than competing directly across specification tiers.
| Leading Market Players |
|---|
| Marki Microwave |
| TTM Technologies |
| Analog Devices |
| API Technologies |
| ETL Systems |
| MACOM |
| Mini-Circuits |
| L3 Narda-MITEQ |
| Rohde & Schwarz |
| Others |
Cost & Logistics Intelligence
Overcapacity in Jiangsu and Guangdong packaging corridors is compressing spot pricing for surface-mount power dividers while tightening contract terms for buyers seeking supply security. This utilization imbalance rewards fabless designers with leverage in short-cycle procurement but squeezes margins for catalog suppliers locked into long-term offtake agreements with telecommunications OEMs.
Pricing Analysis
Long-term offtake agreements dominate procurement between tier-one network equipment manufacturers and domestic US fabricators, insulating premium Wilkinson divider lines from aluminum and copper spot volatility. Pricing stratifies across ITAR-certified defense tiers, REACH-compliant aerospace tiers, and standard commercial tiers, with certification grade commanding the steepest premium. Cost compression in low-power catalog lines is intensifying because Mini-Circuits sustains price discipline through captive domestic manufacturing. Telecommunications OEMs exhibit highest price sensitivity; defense prime contractors demonstrate lowest sensitivity due to qualification lock-in.
Supply Chain Analysis
Extended payment terms from South Korean network equipment consolidators are restructuring working capital requirements across the supplier base, favoring balance-sheet-strong incumbents. Manufacturing capacity concentrates in China, the United States, and Germany, with the Jiangsu corridor feeding fabless designers and Dallas-Fort Worth anchoring domestic coaxial production. Raw material dependencies center on aluminum housings, copper transmission lines, and nickel-palladium-gold surface treatments. Single-source vulnerability in Chinese surface-mount assembly creates systemic exposure. Distribution runs through direct vendor-managed inventory agreements with tier-one OEMs, bypassing traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
RF power divider procurement is evolving into a service-attach opportunity as field calibration and thermal cycling warranty extensions expand faster than hardware unit growth. Recurring revenue from qualification maintenance and ITAR documentation renewal is displacing pure component margin as the primary value capture mechanism.
For Market Incumbents: Build certification moats through accelerated O-RAN Alliance interoperability testing and REACH-compliant material traceability systems. Deepen backward integration into semiconductor packaging roadmaps to defend against silicon-glass interposer displacement. Lock in defense prime contractor relationships with dedicated program management cells addressing State Department export licensing friction. For New Entrants and Emerging Players: India's disaggregated base station architecture presents the most penetrable volume opportunity, with Reliance Jio and Bharti Airtel procurement windows favoring cost-optimized massive MIMO configurations. Satellite ground segment thermal cycling specifications remain underserved by incumbent broadcast specialists. A technical sales model embedding field engineering support with hardware supply secures initial qualification. For Investors and Strategic Acquirers: Capital is best deployed toward millimeter-wave electromagnetic simulation boutiques with captive senior engineering talent and established defense qualification histories. Long-term viability hinges on positioning ahead of 6G prototype validation cycles and software-defined radio platform integration. The signal to monitor is Open RAN certification timeline compression by major network operators.| Strategic Initiative | Industry Significance |
|---|---|
| Semiconductor Packaging Integration | Hybridizes divider functions into wafer-level packages for software-defined radio platforms at US defense primes. |
| REACH-Compliant Surface Treatment Qualification | Accelerates vendor approval for nickel-palladium-gold finishes at Bavarian satellite ground station integrators. |
| Direct Vendor-Managed Inventory Agreements | Consolidates passive component sourcing into Samsung Networks commodity management functions in Seoul. |
| Millimeter-Wave Design Talent Acquisition | Captures scarce electromagnetic simulation expertise for 28 GHz and 39 GHz broadband matching networks. |
| India Domestic Assembly Partnership | Leverages PLI scheme incentives and Karnataka corridor qualification for Open RAN-compliant modular production. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FCC equipment authorization databases, ITAR commodity jurisdiction determinations, and O-RAN Alliance interoperability specifications. Primary engagement encompassed RF component procurement directors at telecommunications OEMs, defense prime contractor subsystem engineers, semiconductor packaging specialists, and satellite ground station integrators. Secondary validation drew from SEC 10-K disclosures of listed component suppliers, ECHA REACH substance restriction updates, and customs trade data on aluminum and copper RF housing imports. Bottom-up unit demand modeling triangulates against top-down infrastructure capex allocation analysis.
Forecast inputs incorporate Open RAN disaggregation penetration curves, NATO radar modernization program commitments, and 5G-Advanced spectrum auction proceeds across modeled geographies. Segmentation dimensions span form factor, technology architecture, end-user certification tier, and power handling rating. CAGRs derive from regression against historical telecommunications infrastructure deployment cycles and defense procurement authorization patterns. Industry-specific inputs include millimeter-wave test equipment demand from Taiwan and South Korea semiconductor R&D labs, and thermal cycling specification tightening for low-earth orbit gateway deployments.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by fabless designers or rapid O-RAN certification acceleration by network operators would shift outcomes. Macroeconomic deviation in aluminum and copper pricing, regulatory restriction expansion under REACH substance controls, or technological displacement by monolithic microwave IC integration would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
RF Semiconductor Market
RF Components
RF Antenna Market
RF Components
High Reliability Oscillators Market
RF Components
Microwave Devices Market
RF Components
Low Noise Amplifier Market
RF Components
Multiband Booster Market
RF Components
Toroid Inductor Market
RF Components
RF and Microwave Diodes Market
RF Components
UHF RFID Inlays Market
RF Components
Global Inductors Market
RF Components
5G Gain Block Amplifier Market
RF Components
Noise Suppression Components Market
RF Components
RF Transceiver Chip Market
RF Components
RF Spectrum Analyzer Market
RF Components
RF Gan Market
RF Components
Stand-Alone Radio Receivers Market