
 ISP Management Systems Market | 2026-2036
ISP Management Systems Market Size, Share, and Industry Trends Forecast 2026-2036
ISP Management Systems Market Foresight
Platform licensing revenue is tilting from perpetual on-premises contracts toward recurring SaaS arrangements. Huawei Technologies Co., Ltd leverages its telecom infrastructure footprint to bundle management software with routing hardware. Splynx sro specializes in modular billing and network automation for mid-sized wireless ISPs. Ubersmith anchors its position through deep workflow customization for cable and fiber operators.
ISP management systems comprise software platforms that provision subscriber accounts, meter bandwidth consumption, automate invoicing, and monitor network health through SNMP and TR-069 protocols. These systems serve commercial purposes by reducing operational expenditure through automated fault detection and service activation. Cloud-based deployment now captures the fastest expansion as ISPs seek elastic capacity during peak usage periods. Network management functions sit at the core margin pool given their integration with physical infrastructure. Billing systems remain mature with stable renewal patterns across established providers.
The FCC enforces broadband consumer labels that require ISPs to disclose speed, latency, and pricing data through standardized APIs. GDPR in Europe shapes how subscriber data traverses cloud-hosted management platforms. India's TRAI mandates specific quality benchmarks that ISPs must document through certified management dashboards. Stakeholders must weigh sovereignty requirements against cloud scalability when selecting deployment architecture.
Market Dynamics
Fiber-to-the-home infrastructure investments are forcing ISPs to abandon siloed operational tools in favor of unified orchestration platforms that synchronize subscriber provisioning with physical layer management.
Growth Catalysts
- FCC Broadband Labeling:Mandated disclosure APIs in the United States push vendors to embed real-time data transparency into subscriber portals.
- India TRAI Quality Benchmarks:Documented service-level requirements drive adoption of certified network dashboards among domestic operators.
- Cloud Elasticity:Peak-traffic capacity demands during streaming and gaming surges accelerate migration from fixed-capacity on-premises deployments.
Market Restraints
- GDPR Data Sovereignty:Cross-border subscriber data restrictions complicate multi-tenant cloud architectures for European deployments.
- SNMP-to-API Transition Friction:Legacy protocol dependencies slow integration of modern REST-based management layers with installed CPE bases.
- Specialized Talent Scarcity:Shortage of engineers fluent in both telecommunications infrastructure and cloud-native development constrains rollout velocity.
Strategic Opportunities
- Rural Wireless Expansion:Fixed-wireless access rollouts in underserved territories create demand for lightweight, modular management stacks.
- AI-Driven Fault Prediction:Convergence of machine learning with streaming telemetry enables proactive network remediation before subscriber impact.
- Outcome-Based Pricing Models:Uptime-guarantee contracts replace per-seat licensing, aligning vendor revenue with operational performance metrics.
Industry Challenges
- Multi-Vendor Integration Complexity:Heterogeneous equipment from OLT manufacturers, CPE suppliers, and third-party OSS tools demands custom middleware development.
- TR-069 Certificate Management:Device authentication credential rotation at scale requires automated PKI infrastructure that many mid-sized ISPs lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ISP Management Systems Market |
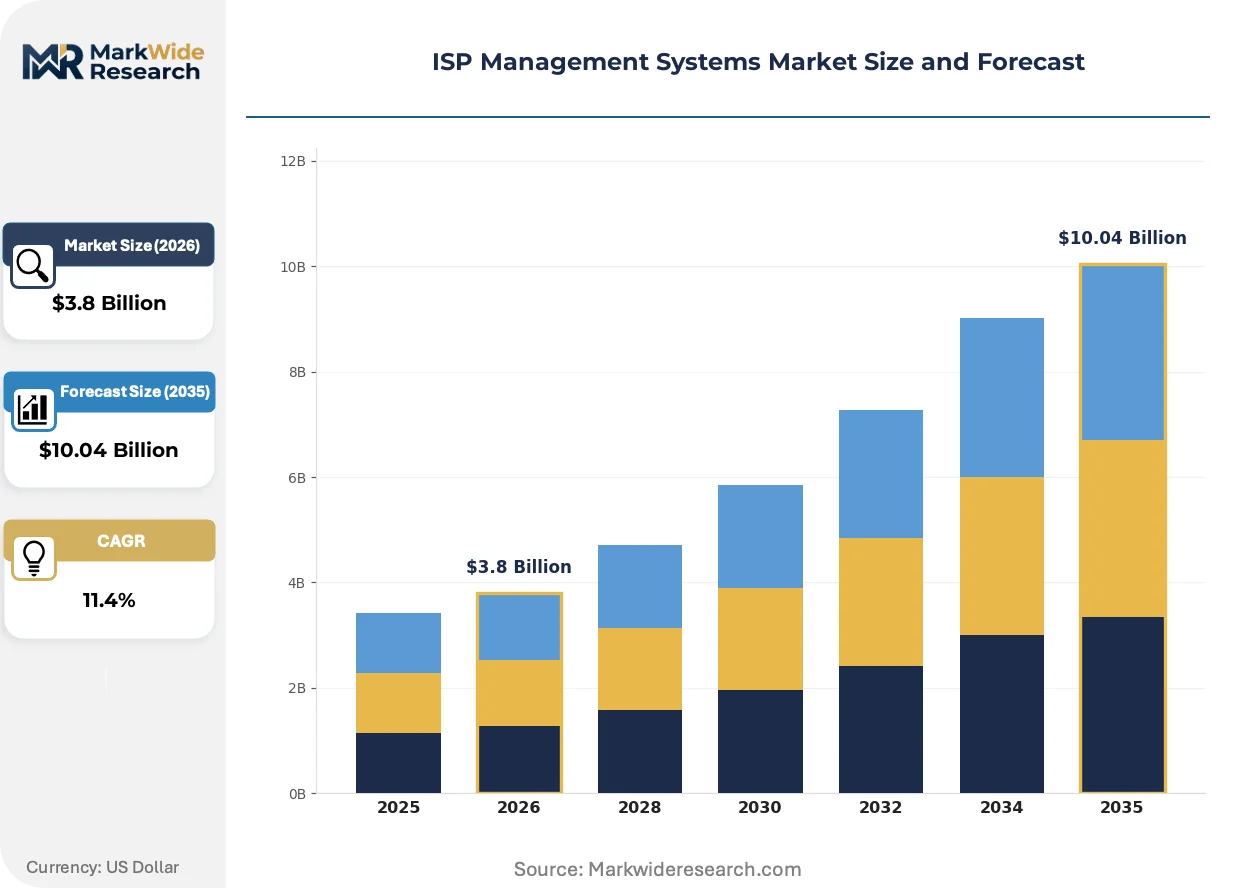
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Billing Systems, Network Management, Customer Relationship Management, Technical Support Deployment Model: On-Premises, Cloud-Based, Hybrid, SaaS End User: Telecommunications Providers, Internet Service Providers, Managed Service Providers, Enterprises Customer Type: Residential, Business, Government, Educational |
| Companies Covered | Splynx sro, Xonware Technologies Pvt. Ltd, Huawei Technologies Co., Ltd, Sonar, Ubersmith, SoftifyBD Ltd, Netwall Expert, Hydra Billing Solutions LLC, ICONWAVE TECHNOLOGIES PVT. LTD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ISP Management Systems Market Shifts & Advancements
Zero-touch provisioning architectures are collapsing deployment timelines from weeks to hours, reshaping how operators scale subscriber bases without proportional headcount expansion.
Containerized microservices architectures are rendering obsolete monolithic management suites that require coordinated version upgrades across billing, provisioning, and monitoring modules. Tier-two fiber operators in Germany and the Netherlands are migrating workloads to Kubernetes-orchestrated environments. This shift compresses vendor switching costs and accelerates feature deployment cycles.
The EU AI Act's risk-classification framework imposes documentation requirements on automated network optimization algorithms that adjust bandwidth allocation without human intervention. ISPs deploying predictive congestion management must maintain audit trails of algorithmic decisions. French and Spanish operators are prioritizing explainable AI tools that satisfy regulatory scrutiny while maintaining performance gains.
Self-service subscriber portals are displacing traditional call-center interactions for routine account modifications and service upgrades. Brazilian and Mexican cable operators report portal adoption rates above sixty percent for plan changes and payment scheduling. This channel migration reduces operational expenditure per subscriber while creating data-rich interaction logs for churn prediction models.
ISP Management Systems Market Segmentation
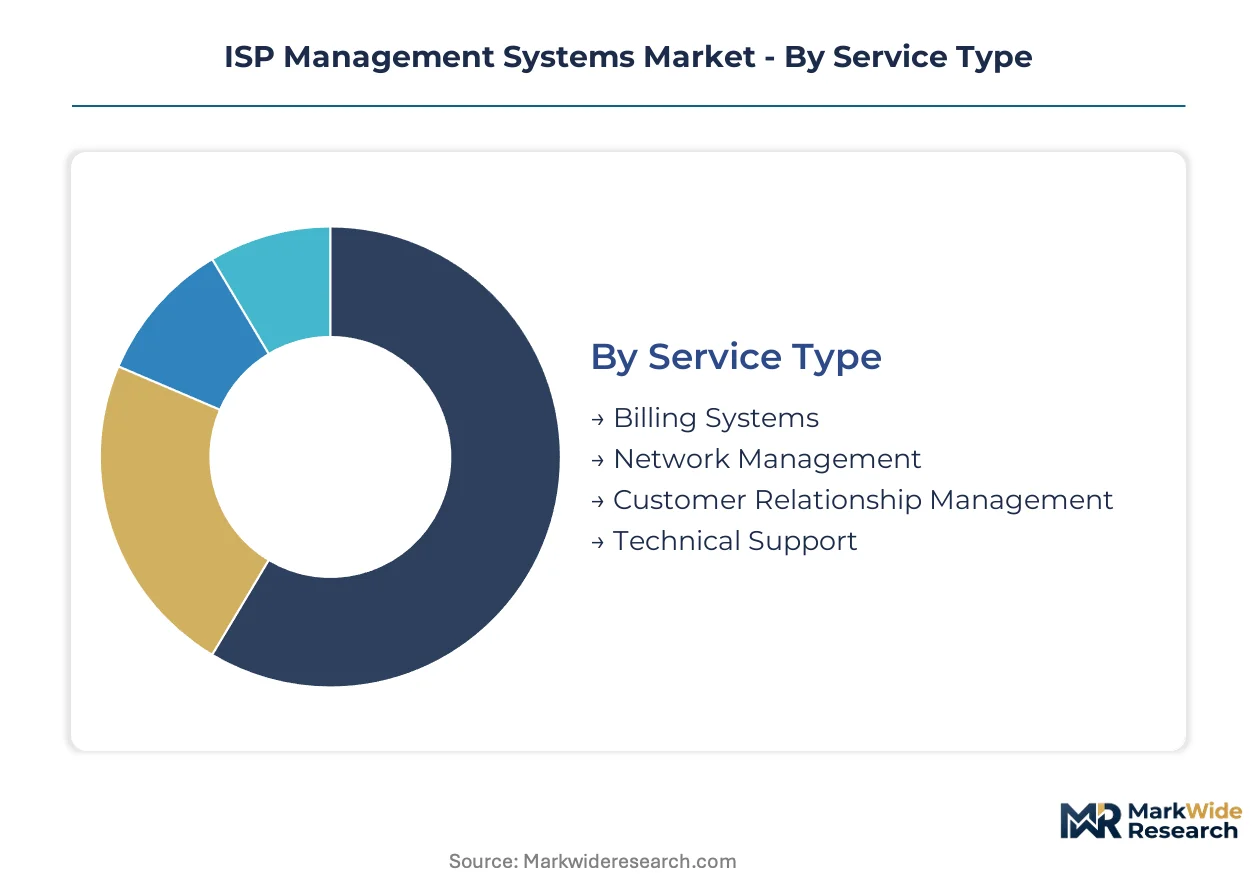
ISP management systems fragment across four operational dimensions that determine vendor selection criteria and deployment architecture. Each segmentation layer carries distinct margin profiles, integration complexity, and renewal dynamics that shape competitive positioning.
Service Type:
After-sales service intensity varies sharply across functional modules, with network management demanding continuous telemetry tuning while billing systems stabilize after initial configuration.
- Billing Systems:Core platforms automate invoicing cycles, payment processing, and tax calculation across heterogeneous service bundles. Indian operators under TRAI quality mandates drive demand for billing systems that integrate subscriber complaint tracking with penalty calculations. This segment holds the largest share; momentum sits with network management.
- Network Management:SNMP and TR-069 protocol stacks monitor CPE health, OLT performance, and fiber link status through centralized dashboards. German and Dutch fiber operators are migrating these workloads to Kubernetes-orchestrated microservices for faster feature deployment. The steepest expansion trajectory concentrates here as FTTH rollouts accelerate.
- Customer Relationship Management:Subscriber portals and ticketing workflows reduce call-center dependency. Brazilian and Mexican cable operators report portal adoption above sixty percent for routine account modifications.
- Technical Support:Remote diagnostics and field technician dispatch modules address fault resolution. Mid-sized wireless ISPs favor lightweight implementations that minimize specialized engineering headcount.
Network management commands premium pricing through infrastructure integration; billing systems face commoditization pressure from SaaS entrants.
Deployment Model:
Cost tier stratification separates capital-intensive on-premises installations from operational expenditure models that dominate greenfield deployments.
- On-Premises:Perpetual licensing with dedicated hardware remains entrenched among tier-one operators with legacy OSS investments and sovereignty requirements. European deployments under GDPR data localization rules sustain this model despite higher total cost of ownership.
- Cloud-Based:Elastic capacity provisioning accommodates traffic spikes from streaming and gaming surges without fixed infrastructure commitments. Indian ISPs scaling rapidly under TRAI quality benchmarks favor this architecture for speed-to-market.
- Hybrid:Sensitive subscriber data resides on-premises while analytics workloads burst to public cloud. French operators navigating EU AI Act documentation requirements for automated optimization algorithms deploy this configuration.
- SaaS:Recurring subscription models align vendor incentives with uptime performance. Mid-sized wireless ISPs in rural expansion territories prioritize modular SaaS stacks that minimize upfront investment.
On-premises retains the largest installed base; SaaS gains share fastest among entrants lacking legacy protocol dependencies.
End User:
Application requirements diverge between infrastructure owners and service intermediaries that layer value-added functions atop wholesale connectivity.
- Telecommunications Providers:Integrated orchestration platforms synchronize subscriber provisioning with physical layer management across fiber, DSL, and wireless access technologies. Huawei bundles management software with routing hardware to capture this segment.
- Internet Service Providers:Specialized provisioning and bandwidth metering tools address multi-tenant residential and business service delivery. Splynx sro targets mid-sized wireless ISPs with modular automation suites.
- Managed Service Providers:White-label management platforms enable outsourced network operations for enterprise clients. Demand concentrates where internal IT capabilities lag infrastructure complexity.
- Enterprises:Private network management for campus WiFi, SD-WAN, and dedicated fiber links. Custom workflow requirements distinguish this segment from service-provider deployments.
Telecommunications providers represent the deepest revenue pool; managed service providers expand most quickly as outsourcing accelerates.
Customer Type:
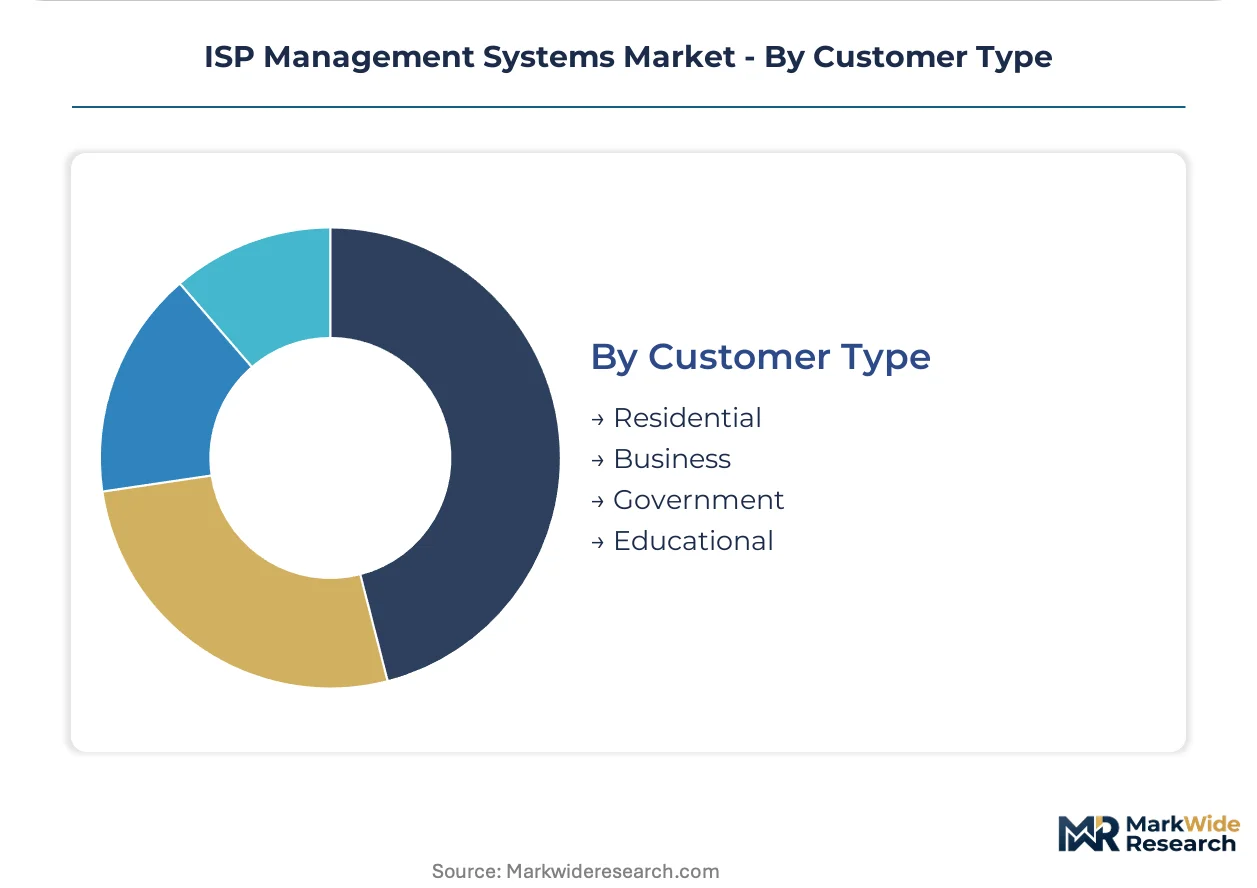
Volume concentration and margin profile separate mass-market residential subscribers from contractual business relationships with negotiated service levels.
- Residential:High-volume, low-margin accounts with standardized service tiers and self-service portal expectations. Brazilian and Mexican operators leverage portal adoption to reduce per-subscriber operational expenditure.
- Business:SLA-guaranteed connectivity with dedicated support channels and custom bandwidth profiles. Uptime-guarantee contracts are displacing per-seat licensing in this segment.
- Government:Procurement through certified vendor lists with emphasis on data sovereignty and audit trail completeness. European public sector deployments prioritize GDPR-compliant architectures.
- Educational:Seasonal usage patterns and bulk pricing negotiations for campus-wide connectivity. Cloud elasticity appeals to institutions managing variable demand across academic calendars.
Residential accounts dominate subscriber counts; business customers generate the highest revenue per user and fastest-growing contract values.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. Indian operators prioritize rapid cloud deployment under regulatory pressure, while European incumbents favor hybrid architectures balancing sovereignty with elasticity. North American cable providers drive API standardization for consumer transparency mandates.
United States
FCC broadband labeling rules and fiber-to-the-home overbuilds dominate procurement criteria. The FCC's mandated disclosure APIs force vendors to embed real-time data transparency into subscriber portals. Texas and Florida cable operators are consolidating billing and network orchestration onto unified platforms to reduce operational headcount.
Germany
Tier-two fiber operators are migrating network management workloads to Kubernetes-orchestrated microservices for faster feature deployment. The EU AI Act imposes documentation requirements on automated bandwidth optimization algorithms that adjust allocation without human intervention. The Ruhr industrial corridor hosts concentrated vendor development activity for explainable AI tools that satisfy regulatory scrutiny.
India
Domestic ISPs scaling rapidly under TRAI quality-of-service benchmarks favor cloud-based architectures for speed-to-market. TRAI mandates specific quality benchmarks that operators must document through certified management dashboards. Bangalore and Hyderabad technology clusters are driving adoption of integrated network orchestration suites among mid-sized wireless providers.
Brazil
Cable operators report self-service portal adoption above sixty percent for routine account modifications and payment scheduling. ANVISA data handling guidelines shape how subscriber information traverses cloud-hosted platforms. São Paulo metropolitan operators are reducing per-subscriber operational expenditure through channel migration from call centers to digital interfaces.
Netherlands
Fiber operators are collapsing deployment timelines through zero-touch provisioning architectures that synchronize subscriber activation with physical layer management. GDPR data sovereignty rules sustain hybrid deployment models where sensitive data remains on-premises while analytics burst to cloud. The Randstad conurbation concentrates vendor engineering resources for containerized microservices development.
ISP Management Systems Market Competitive Landscape
Capability concentration sits with infrastructure-integrated software vendors; scale advantage sits with modular SaaS specialists. The market structures around three tiers: telecom equipment bundlers, standalone management platform vendors, and vertical-specific workflow customizers. Consolidation pressure favors unified orchestration suites over point solutions. Dominant competitive moves include strategic bundling of software with hardware procurement cycles and geographic expansion through localized compliance certification.
Within the infrastructure-bundler tier, Huawei Technologies Co., Ltd occupies a position exemplifying telecom equipment integration with management software. Splynx sro and Ubersmith represent contrasting archetypes—modular automation for mid-sized wireless ISPs versus deep workflow customization for cable and fiber operators. These three anchors illustrate the strategic divergence between hardware-coupled scale plays and specialized software configurability.
| Leading Market Players |
|---|
| Splynx sro |
| Xonware Technologies Pvt. Ltd |
| Huawei Technologies Co., Ltd |
| Sonar |
| Ubersmith |
| SoftifyBD Ltd |
| Netwall Expert |
| Hydra Billing Solutions LLC |
| ICONWAVE TECHNOLOGIES PVT. LTD |
| Others |
Supply & Pricing Matrix
The Shanghai-Singapore submarine cable corridor carries management system codebases and hardware components between Asian development centers and Southeast Asian deployment sites, with freight cost volatility compressing margins for vendors serving price-sensitive mid-tier ISPs while amplifying differentiation premiums for orchestration suites with embedded compliance modules.
Pricing Analysis
Long-term SaaS subscription contracts dominate enterprise procurement, displacing perpetual licensing arrangements that once anchored vendor revenue. Three-tier pricing structure across premium, standard, and economy levels separates full-stack orchestration platforms from modular billing tools and entry-level provisioning software. Price differentiation rests on certification depth for TRAI quality dashboards and GDPR-compliant data architectures. Pricing pressure stems from open-source network automation frameworks gaining traction among cost-conscious wireless operators. Tier-two fiber providers exhibit highest price sensitivity; government and enterprise segments tolerate premium positioning for sovereignty-guaranteed deployments.
Supply Chain Analysis
Contract manufacturing for management system appliances concentrates in Taiwan, Malaysia, and Vietnam, with Foxconn and Wistron holding substantial server assembly capacity for on-premises deployments. Software supply chains draw from Indian development centers for billing module engineering and Eastern European hubs for protocol stack optimization. Single-source vulnerability sits with specialized SNMP-to-REST gateway chipsets fabricated at TSMC facilities. Distribution runs through direct vendor sales teams for tier-one telecommunications providers and regional value-added resellers serving mid-market ISPs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISP management systems sit in early-cycle expansion as fiber-to-the-home overbuilds force operational tool consolidation and regulatory transparency mandates create first-mover advantages for compliant platform vendors.
For Market Incumbents: Harden defensive moats by embedding zero-touch provisioning workflows deeper into optical line terminal hardware partnerships, neutralizing the threat from modular SaaS entrants targeting mid-sized wireless ISPs. Pursue backward integration into subscriber identity management to capture recurring authentication revenue streams. Prioritize certification investment for India's TRAI quality dashboards and the EU AI Act's algorithmic documentation requirements.
For New Entrants and Emerging Players: Rural fixed-wireless territories in Brazil's interior states and India's tier-three cities present the most penetrable white-space for lightweight, containerized management stacks with minimal upfront infrastructure. Target municipal broadband authorities with outcome-based pricing tied to uptime guarantees rather than per-seat licensing. Deploy Kubernetes-native architectures to compress implementation timelines and reduce specialized engineering dependencies.
For Investors and Strategic Acquirers: Modular SaaS specialists with proven TR-069 certificate automation and established wireless ISP customer bases represent compelling acquisition archetypes for platform consolidation plays. Long-term viability hinges on regulatory compliance depth rather than feature breadth. Monitor FCC broadband label API adoption rates and TRAI quality benchmark certification velocity as inflection indicators for vendor competitive positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Zero-Touch Provisioning Deployment | Collapses subscriber activation timelines from weeks to hours for fiber operators scaling rapidly. |
| Kubernetes Microservices Migration | Enables German and Dutch tier-two operators to accelerate feature release cycles without coordinated upgrades. |
| Explainable AI Tool Development | Satisfies EU AI Act documentation requirements for automated bandwidth optimization algorithms in France and Spain. |
| Self-Service Portal Expansion | Brazilian cable operators report sixty percent adoption for routine account modifications, reducing call-center expenditure. |
| Hybrid Sovereignty-Compliant Architecture | Addresses GDPR data localization while preserving cloud elasticity for analytics workloads bursting. |
Research Methodology
A spread of perspectives from network operations executives at tier-one telecommunications providers, CTOs at mid-sized wireless ISPs, procurement leads at managed service providers, and regulatory affairs specialists converged on the working assumptions. Primary interview findings were cross-checked against secondary sources including FCC broadband labeling rulemakings, TRAI quality-of-service circulars, EU AI Act implementation guidance, and vendor SEC filings. Bottom-up subscriber provisioning volume estimates were reconciled with top-down market size benchmarks derived from capital expenditure disclosures by major fiber operators.
Demand-supply balance dynamics across the projection horizon were modeled through segmentation across deployment models, end-user categories, service types, and customer segments. The analytical framework incorporated protocol transition timelines from SNMP to REST-based APIs, cloud elasticity adoption curves, and regulatory compliance certification velocities. CAGRs were derived from weighted scenario analysis of fiber rollout schedules and subscriber growth trajectories without assuming technological disruption beyond documented vendor roadmaps.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hyperscale cloud providers entering network orchestration or open-source automation consortiums achieving enterprise-grade reliability would shift outcomes. Quarterly review of TRAI quality benchmark adoption rates, FCC broadband label API implementation timelines, and containerized microservices migration announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Passive Optical LAN (POL) Market
Network Technology
US Private LTE and 5G Network Market
Network Technology
2.4GHz Router Market
Network Technology
Ethernet Backhaul Equipment Market
Network Technology
Router and Switch Market
Network Technology
Global Private 5G Network Market
Network Technology
Smart Network Interface Card (Smartnic) Market
Network Technology
Global Carrier Ethernet Equipment Market
Network Technology
Global 5G Smart Antenna Market
Network Technology
UK B2B Fixed Connectivity Market
Network Technology
Application Delivery Controller (ADC) Market
Network Technology
Lit Fiber Market
Network Technology
Residential Routers Market
Network Technology
IT Connector Market
Network Technology
Global Network Management Market
Network Technology
Europe Private 5G Network Market