
 Global Hardware Acceleration Market | 2026-2036
Global Hardware Acceleration Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hardware Acceleration Market Foresight
Hyperscale cloud providers is unwinding the historical balance between enterprise IT buyers and telecommunications providers as the dominant hardware acceleration procurement archetype. NVIDIA sustains technology leadership in GPU-based training clusters through its CUDA software ecosystem lock-in. AMD competes aggressively in data center accelerators with its Instinct product line, while Intel anchors x86-adjacent acceleration through integrated CPU-GPU packages for mainstream inference workloads.
Hardware acceleration refers to the use of specialized computing architectures—such as ASICs, FPGAs, and GPUs—to execute specific computational workloads orders of magnitude faster than general-purpose processors, typically measured in teraflops or inference queries per watt. These devices integrate billions of transistors on advanced process nodes, often below 5nm, to achieve parallel execution of matrix operations essential to modern AI and signal processing. Graphics Processing Units continue to dominate training workloads due to mature software stacks, though Application-Specific Integrated Circuits capture margin pools in large-scale inference deployment where power efficiency dictates total cost of ownership. Tensor Processing Units represent the fastest-growing category as Google and cloud providers expand custom silicon programs.
The US Commerce Department's Bureau of Industry and Security restricts export of advanced accelerators to specific countries, fragmenting supply geography and accelerating indigenous chip programs in China and Europe. The EU AI Act imposes risk-classification requirements on high-performance computing deployments, shaping product certification and liability frameworks for accelerator vendors serving European cloud providers and research institutions. Stakeholders must monitor how export control alignment between the US, Japan, and the Netherlands evolves, as this trilateral coordination determines foundry equipment access and ultimately which geographies can manufacture next-generation accelerators.
Market Dynamics
Hyperscale cloud providers are consolidating procurement power faster than enterprise data centers can adapt, concentrating demand around AI training clusters and reshaping how accelerator vendors prioritize roadmap investments.
Growth Catalysts
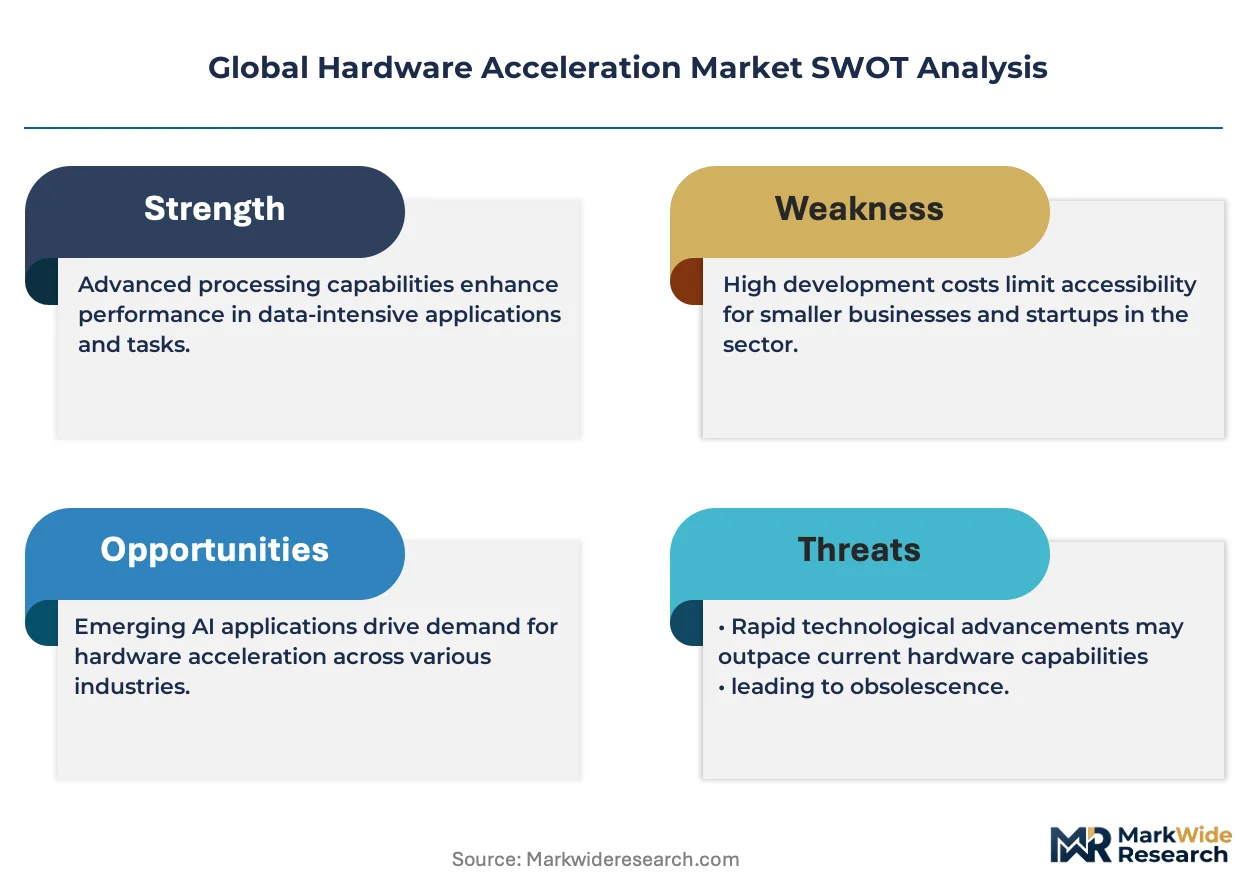
- EU AI Act risk classification:High-performance computing deployments in European research institutions face mandatory certification requirements, creating structured demand for compliant accelerator architectures.
- Advanced packaging capacity concentration:Taiwan's foundry dominance positions TSMC's CoWoS technology as the binding constraint on next-generation AI chip supply.
- Cloud inference at scale:Hyperscalers deploying recommendation engines and search ranking systems drive sustained orders for power-efficient inference accelerators.
Market Restraints
- TSMC foundry concentration:Single-source dependency for sub-5nm logic and advanced packaging creates systemic supply risk for GPU and ASIC roadmaps.
- US BIS export controls:Commerce Department licensing restrictions fragment market access and accelerate indigenous chip programs in China.
- High-NAND memory bandwidth requirements:HBM3 and HBM3e supply constraints from SK Hynix and Samsung limit accelerator performance scaling.
Strategic Opportunities
- Edge AI deployment in India:Manufacturing and smart city initiatives under the PLI scheme create localized demand for low-power inference accelerators.
- CPU-GPU convergence:Integrated packages combining x86 cores with matrix engines address mainstream inference workloads previously served by discrete cards.
- Japan's semiconductor revitalization:METI subsidies for domestic foundry capacity at Rapidus and existing Kioxia operations attract accelerator packaging investments.
Industry Challenges
- CUDA software ecosystem lock-in:Porting optimized workloads to alternative instruction set architectures demands scarce compiler and kernel engineering talent.
- Multi-die thermal management:Chiplet-based designs exceeding 700W TDP require novel liquid cooling integration at data center scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hardware Acceleration Market |
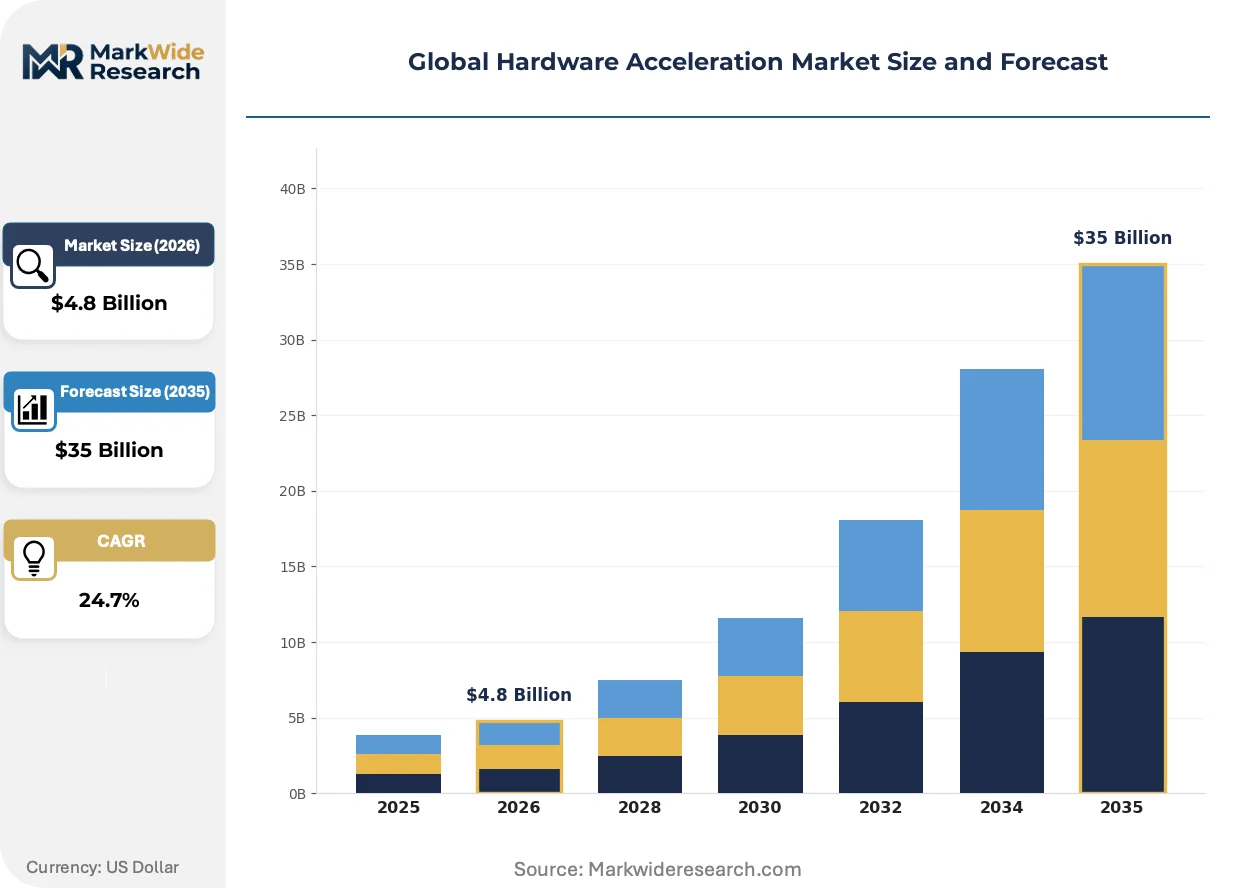
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $35 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Graphics Processing Units, Field Programmable Gate Arrays, Digital Signal Processors, Application-Specific Integrated Circuits, Tensor Processing Units Technology: ASIC, FPGA, GPU, DSP, TPU, NPU Application: Data Analytics, Cryptography, Network Processing, Machine Learning, Scientific Computing, Computer Vision End User: Telecommunications Providers, Cloud Providers, Semiconductor Designers, Financial Analysts, Research Institutions |
| Companies Covered | Qualcomm, Broadcom, NVIDIA, Cerebras Systems, Google, AMD, TSMC, Groq, Intel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hardware Acceleration Market Shifts & Advancements
Accelerator architectures are fragmenting into specialized inference and training designs as power efficiency constraints override general-purpose performance scaling. This divergence is compressing product lifecycles and forcing vendors to commit to process nodes before demand materializes.
Chiplet-based designs are decomposing monolithic GPU dies into discrete compute, memory, and I/O tiles connected through advanced packaging. Hyperscalers including Google and Amazon Web Services are adopting these modular architectures for custom silicon programs. The approach is decomposing historical performance-per-watt advantages held by integrated designs and enabling faster iteration on specific subsystems.
The EU AI Act's risk-based classification system imposes documentation and conformity assessment burdens on high-performance computing deployments serving European cloud providers. Research institutions must demonstrate traceability and auditability in accelerator procurement. German and French national supercomputing centers are front-loading compliance costs into tender specifications, filtering vendor pools before technical evaluation.
Buyers are consolidating procurement around long-term capacity reservations rather than spot purchasing. Cloud providers negotiate multi-year wafer allocations directly with foundries, bypassing traditional distributor channels. This pattern is most visible in Taiwan and South Korea, where TSMC and Samsung have established dedicated account structures for hyperscale customers with minimum volume commitments.
Global Hardware Acceleration Market Segmentation
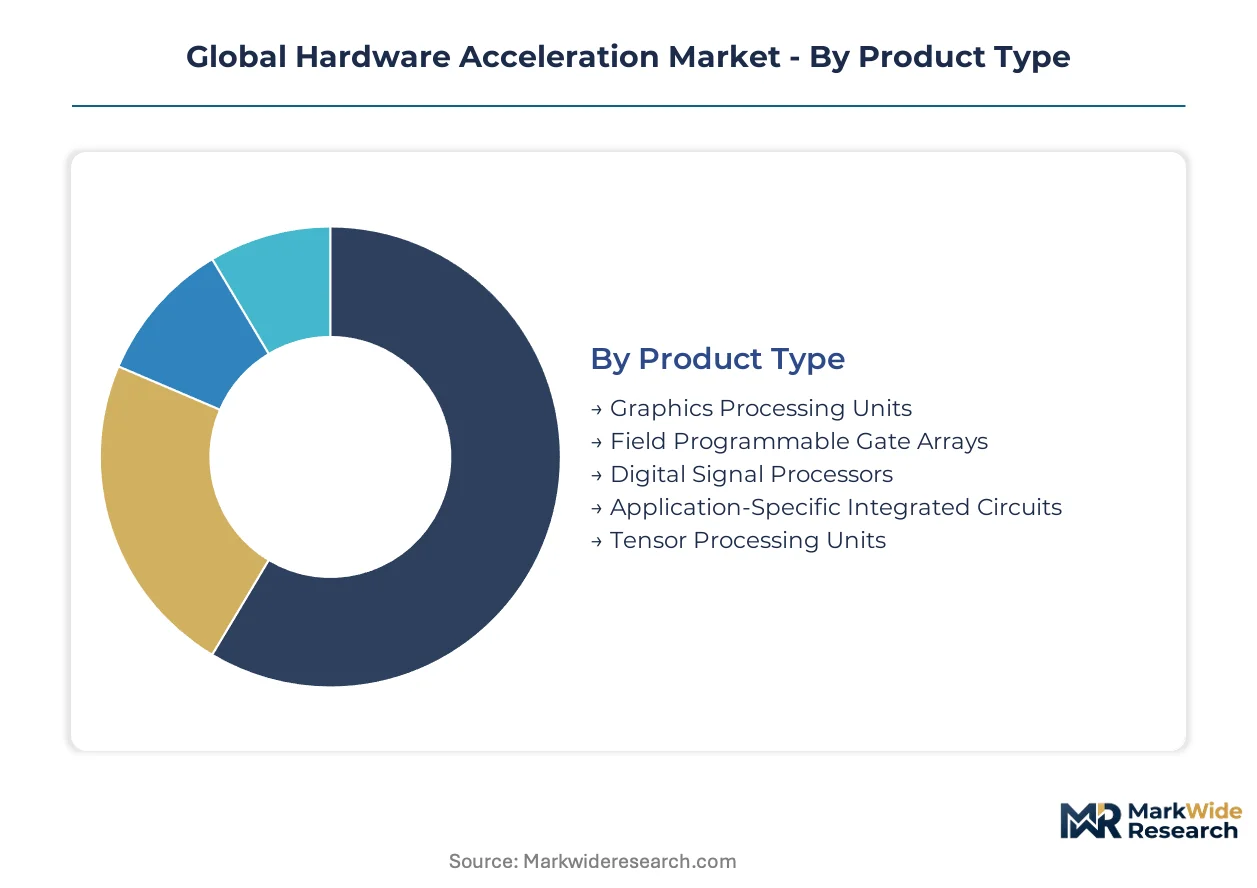
Accelerator architectures fragment along workload specialization, with training-optimized designs facing displacement from inference-efficient alternatives. Vendors must align roadmaps to end-user procurement consolidation among hyperscalers while navigating process-node commitments that lock in performance-per-watt trajectories years ahead of demand materialization.
Product Type:
Graphics Processing Units face the most acute substitution pressure as workload-specific ASICs and TPUs capture margin pools in large-scale inference deployment where power efficiency dictates total cost of ownership.
- Graphics Processing Units:Parallel processing architectures integrating billions of transistors on sub-5nm nodes execute matrix operations essential to AI training. Cloud providers in the United States and Taiwan concentrate procurement around NVIDIA's CUDA-enabled clusters, though software ecosystem lock-in creates porting friction for alternative architectures.
- Application-Specific Integrated Circuits:Custom silicon designs optimize die area and power draw for fixed computational patterns. Google and Amazon Web Services deploy proprietary ASICs for recommendation engines and search ranking, bypassing general-purpose accelerator margins.
- Tensor Processing Units:Google's custom matrix-math engines accelerate neural network inference with deterministic latency profiles.
- Field Programmable Gate Arrays:Reconfigurable logic fabrics enable rapid prototyping of signal processing pipelines without mask-set costs.
- Digital Signal Processors:Specialized multiply-accumulate units target audio, radar, and telecommunications baseband processing.
Graphics Processing Units retain volume leadership; Tensor Processing Units hold the steepest expansion curve.
Technology:
Cost tier stratification separates premium custom silicon from mainstream programmable fabrics, with foundry allocation agreements determining which architectures achieve commercial scale.
- ASIC:Full-custom designs sacrifice flexibility for die-area efficiency and deterministic performance. TSMC's advanced packaging capacity in Taiwan binds supply for hyperscale customers negotiating multi-year wafer commitments.
- TPU:Google's proprietary instruction set architecture targets tensor operations with systolic array layouts. European research institutions under EU AI Act compliance mandates evaluate TPUs against documentation and auditability requirements.
- GPU:Massively parallel thread processors dominate training clusters through mature software stacks.
- FPGA:Reprogrammable gate arrays suit low-volume applications and algorithmic experimentation.
- DSP:Fixed-function signal processors anchor telecommunications infrastructure.
- NPU:Neural processing units integrate inference engines into mobile and edge devices.
ASIC captures the premium cost tier; NPU expands most quickly into consumer electronics.
Application:
Customer type concentration among hyperscalers reshapes demand geography, with machine learning and data analytics workloads absorbing the majority of accelerator procurement volume.
- Machine Learning:Training and inference pipelines for large language models and computer vision systems drive accelerator attach rates. United States-based cloud providers negotiate direct foundry allocations, displacing traditional enterprise IT procurement channels.
- Data Analytics:Columnar query acceleration and real-time stream processing demand high memory bandwidth. Financial analysts in London and Singapore deploy FPGA clusters for low-latency trading analytics.
- Computer Vision:Convolutional neural networks for autonomous systems and industrial inspection require deterministic inference latency.
- Scientific Computing:Climate modeling and molecular dynamics simulations leverage double-precision floating-point units.
- Cryptography:Hardware-accelerated encryption and zero-knowledge proof verification target blockchain and secure communications.
- Network Processing:SmartNICs offload packet inspection and load balancing from host CPUs.
Machine Learning commands procurement volume; Cryptography gains share fastest among emerging workloads.
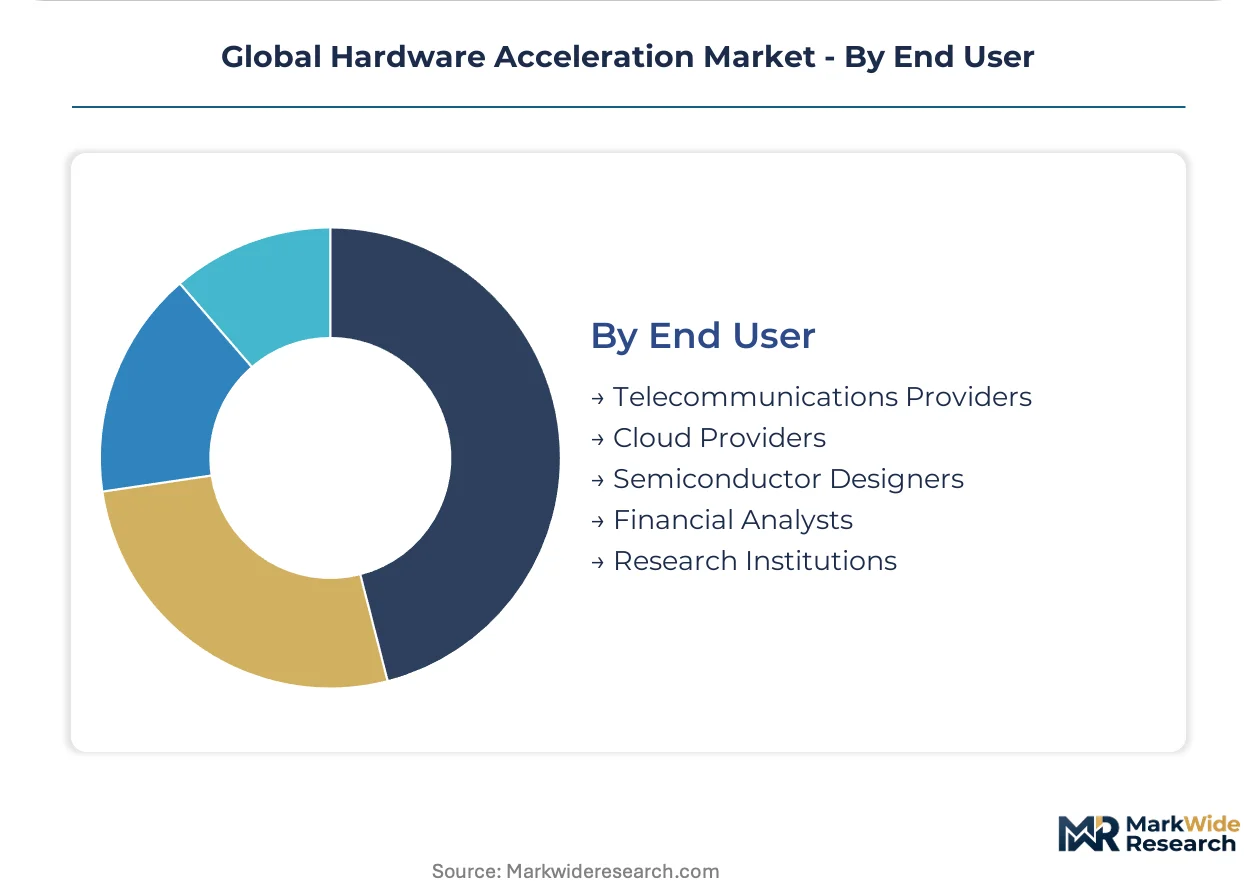
End User:
Supply concentration in Taiwan and South Korea creates procurement risk tiering, with cloud providers securing capacity reservations while research institutions face allocation uncertainty.
- Cloud Providers:Hyperscale operators including Amazon Web Services, Microsoft Azure, and Google Cloud Platform consolidate demand for training clusters and inference fleets. Direct wafer agreements with TSMC and Samsung bypass distributor channels.
- Research Institutions:National supercomputing centers in Germany, France, and Japan front-load EU AI Act compliance costs into tender specifications. Jülich and GENCI filter vendor pools before technical evaluation based on documentation requirements.
- Telecommunications Providers:5G baseband processing and edge computing deployments drive low-power accelerator demand.
- Semiconductor Designers:EDA workloads for physical verification and simulation consume high-performance compute cycles.
- Financial Analysts:Quantitative trading firms deploy FPGA clusters for microsecond-latency analytics.
Cloud Providers dominate procurement volume; Research Institutions face the steepest compliance-driven cost escalation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan exports advanced packaging capacity to United States cloud providers, creating a trade corridor that concentrates procurement power among hyperscale buyers while fragmenting supply geography under export control regimes.
United States
Hyperscale cloud providers in Virginia and Oregon data center clusters negotiate direct wafer allocations with TSMC for AI training clusters. The Bureau of Industry and Security restricts accelerator exports to specific countries, fragmenting market access. Austin and Phoenix host emerging domestic packaging investments responding to CHIPS Act subsidies.
Taiwan
TSMC's foundry dominance in Hsinchu and Tainan anchors global supply for sub-5nm logic and CoWoS advanced packaging. The National Development Council prioritizes semiconductor infrastructure retention amid geopolitical pressure. Kaohsiung's emerging packaging hub attracts capacity expansion for AI chiplet assembly.
China
Indigenous accelerator programs in Beijing and Shanghai accelerate under US export control pressure. MIIT channels subsidies toward domestic GPU and ASIC design houses. Hefei and Wuhan foundry clusters advance mature-node packaging to circumvent equipment access restrictions.
Germany
Jülich Supercomputing Centre front-loads EU AI Act compliance costs into accelerator tender specifications. The Federal Ministry of Education and Research funds Gauss Centre for Supercomputing procurement. Bavaria's Munich semiconductor cluster attracts packaging equipment investments from Japanese suppliers.
Japan
METI subsidizes Rapidus foundry development in Hokkaido and Kioxia memory expansion in Iwate for domestic accelerator supply chains. Tokyo and Osaka data centers deploy power-efficient inference accelerators for manufacturing AI. Yokohama's packaging research consortium advances chiplet thermal management solutions.
Global Hardware Acceleration Market Competitive Landscape
Listed leaders compete with private specialists across software ecosystem control and foundry access dimensions. The market structures around three tiers: GPU incumbents with mature developer tools, cloud-provider captive silicon programs, and venture-backed inference specialists. Strategic moves concentrate on multi-year wafer reservations and compiler talent acquisition.
Within the GPU incumbent tier, NVIDIA and AMD occupy positions defined by developer ecosystem maturity and data center accelerator roadmaps. Google exemplifies the captive silicon archetype through its TPU program. Cerebras Systems and Groq represent venture-backed challengers targeting training and inference specialization respectively. Intel anchors the integrated package segment combining x86 cores with matrix acceleration.
| Leading Market Players |
|---|
| Qualcomm |
| Broadcom |
| NVIDIA |
| Cerebras Systems |
| AMD |
| TSMC |
| Groq |
| Intel |
| Others |
Supply & Pricing Matrix
Chiplet-based architecture substitution for monolithic GPU designs simultaneously redistributes foundry demand toward advanced packaging capacity in Taiwan and compresses pricing premiums for legacy integrated solutions. Hyperscale buyers negotiate multi-year wafer commitments that lock in cost structures before process-node transitions materialize.
Pricing Analysis
Technology-generation pricing gaps between 3nm training clusters, 5nm inference accelerators, and mature-node edge devices stratify procurement budgets across cloud provider tiers. Contract-based long-term offtake dominates, with price differentiation driven by HBM memory bandwidth allocation and TSMC CoWoS certification grade. Cost compression in mainstream inference silicon intensifies as Google and Amazon Web Services deploy captive ASICs. Research institutions exhibit highest price sensitivity due to EU AI Act compliance cost absorption, while United States hyperscalers demonstrate lowest sensitivity through direct foundry bargaining power.
Supply Chain Analysis
Inventory lead times for HBM3e memory modules extend procurement cycles beyond traditional semiconductor planning horizons. Geographic supply concentration centers on Taiwan for sub-5nm logic and CoWoS packaging, South Korea for HBM memory, and Japan for packaging equipment and photoresist materials. Raw material dependencies include high-purity silicon wafers, EUV photoresists, and cobalt-tungsten interconnect metals. Single-source vulnerability at TSMC's Hsinchu facilities creates systemic exposure. Distribution runs through direct hyperscale account structures that bypass traditional semiconductor distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Capital expenditure cyclicality in cloud infrastructure tracks AI training cluster deployment waves, positioning the current upswing as a mid-cycle expansion with inference buildouts sustaining demand through the projection horizon.
For Market Incumbents: Fortify software ecosystem moats through compiler toolchain investments that increase porting friction for CUDA-optimized workloads. Secure multi-year CoWoS capacity reservations at TSMC's Kaohsiung packaging hub to defend against supply rationing. Deepen backward integration into HBM memory controller IP to reduce SK Hynix and Samsung dependency.
For New Entrants and Emerging Players: Compiler and kernel engineering talent scarcity in Europe creates service-layer gaps where incumbents under-serve EU AI Act documentation requirements. Target German and French national supercomputing centers with pre-certified accelerator architectures. Pursue white-label silicon partnerships with Japanese packaging consortiums to bypass TSMC queue constraints.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with venture-backed inference specialists holding tape-out-proven architectures but lacking hyperscale customer traction. Five-to-ten year viability hinges on multi-foundry manufacturing strategies that dilute Taiwan concentration risk. Monitor Bureau of Industry and Security licensing alignment between the United States, Japan, and the Netherlands as the critical inflection signal for indigenous Chinese accelerator substitution pace.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Year Wafer Reservation | TSMC direct agreements lock in CoWoS capacity ahead of AI chiplet demand surges. |
| Compiler Ecosystem Acquisition | Kernel engineering talent scarcity makes specialist firms critical for CUDA porting tools. |
| EU AI Act Pre-Certification | Documentation readiness filters vendor pools at Jülich and GENCI tender stages. |
| Advanced Packaging Joint Venture | Rapidus Hokkaido partnerships diversify supply from TSMC concentration risk. |
| HBM Supply Agreement | SK Hynix and Samsung long-term contracts secure memory bandwidth for training clusters. |
Research Methodology
The analysis maps GPU, ASIC, TPU, FPGA, and NPU sub-sectors, each validated through hyperscale cloud procurement officers, foundry account managers, supercomputing center technical directors, and EDA toolchain engineers. Primary interview insights triangulate against TSMC and Samsung capex disclosures, United States Bureau of Industry and Security export control filings, EU AI Act regulatory texts, and hyperscaler infrastructure investment announcements. Bottom-up unit shipment modeling and top-down semiconductor equipment spend analysis cross-validate volume estimates.
Consistency checks against external benchmarks confirm projection outputs align with foundry revenue reporting and cloud provider infrastructure depreciation schedules. The analytical framework segments by accelerator architecture, workload specialization, end-user procurement archetype, and regional regulatory cluster across the modeling period. CAGRs derive from process-node transition pacing and hyperscaler capacity reservation trajectories. Forecast inputs incorporate EU AI Act compliance cost pass-through rates and trilateral export control alignment scenarios.
Forecasts assume regulatory continuity in United States Commerce Department licensing, EU AI Act risk classification, and Japan METI subsidy regimes; material policy shifts would require re-modeling. Geopolitical disruption to Taiwan Strait logistics or coordinated equipment access restrictions represent specific revision triggers. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Plastic Films and Sheets Market
Others
Fluid Bed Systems Market
Others
Automotive Smart Lighting Market
Others
Heavy Duty Vacuum Bottle Market
Others
Asia-Pacific Medium-Density Fiberboard Market
Others
France Smart Home Market
Others
North America Industrial Wearable Devices Market
Others
Japan Automotive LED Lighting Market
Others
Operator Training Simulator Market
Others
Cloud Digital Video Recorder Market
Others
Healthcare Bioconvergence Market
Others
Nanomedicine for Drug Delivery Market
Others
Cloud Advertising Market
Others
Smartphone Gimbal Market
Others
Wingboards Market
Others
Insoluble Sulfur Market