
 Security Envelopes Market | 2026-2036
Security Envelopes Market Size, Share, and Industry Trends Forecast 2026-2036
Security Envelopes Market Outlook
ISO 27001 certification for information security management is rotating as a de facto gate for envelope suppliers serving banking and government contracts. Blake Envelopes leverages its British manufacturing base to sustain defense and financial sector relationships. NELMAR Security Packaging Systems anchors North American demand through specialized tamper-evident designs. Western States Envelopes & Label competes on scale across mid-market commercial channels.
Security envelopes are engineered containment vessels constructed from kraft paper, Tyvek, or polyethylene substrates with integrated tamper-evident features such as void-pattern adhesives, fiber tear seams, and holographic verification strips; their primary purpose is to protect confidential documents, currency, and negotiable instruments from unauthorized access during transit. Paper-based stock still dominates volume but faces margin compression from sustainability mandates, while Tyvek segments command premium positioning due to tear resistance and archival longevity. Peel & Seal closure formats are displacing gummed alternatives in automated insertion environments where moisture-activated adhesives create line stoppages.
FDA guidelines for pharmaceutical sample mailers, EU Packaging and Packaging Waste Regulation targets, and BIS certification requirements for Indian postal security products collectively tighten material compliance and testing documentation burdens across jurisdictions. The EU Green Deal's recyclability thresholds are forcing substrate reformulation investments that smaller converters cannot absorb. Stakeholders must monitor evolving postal operator specifications and decide whether to absorb certification costs or cede institutional contract pools to vertically integrated competitors.
Market Dynamics
The EU Green Deal's recyclability mandates are compressing margins for paper-based substrate converters while accelerating Tyvek and polyethylene formulation investments across European supply chains.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Germany's banking sector is consolidating vendor relationships under stricter procurement standards that favor certified tamper-evident suppliers.
- Pharmaceutical sample distribution:FDA guidelines for mailer security are expanding addressable demand for void-pattern adhesive formats in US healthcare logistics.
- Automated insertion environments:Peel & Seal closure formats are displacing gummed alternatives as moisture-activated adhesives cause line stoppages in high-speed processing facilities.
Market Restraints
- Pulp price volatility:Kraft paper input costs fluctuate with Nordic timber supply cycles, squeezing converter margins on standard-grade products.
- Substrate reformulation costs:EU Green Deal thresholds require capital outlays that regional mid-tier converters cannot absorb without consolidation.
- Digital document substitution:Electronic check clearing and encrypted file transfer protocols reduce physical security envelope volumes in corporate treasury operations.
Strategic Opportunities
- Indian postal security modernization:BIS certification requirements for government document mailers create a compliance-driven entry point for ISO 27001-certified suppliers.
- Tyvek archival longevity:Museums and legal repositories are adopting tear-resistant polyethylene envelopes for multi-decade document retention protocols.
- Holographic verification integration:Convergence of optical security printing with blockchain traceability systems enables premium positioning in negotiable instrument transit.
Industry Challenges
- ISO 27001 audit timelines:Certification cycles for information security management stretch 12-18 months, delaying contract eligibility for new market entrants.
- Multi-jurisdiction testing documentation:Converters must maintain parallel compliance files for FDA pharmaceutical mailers, EU REACH substance registrations, and BIS product standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Security Envelopes Market |
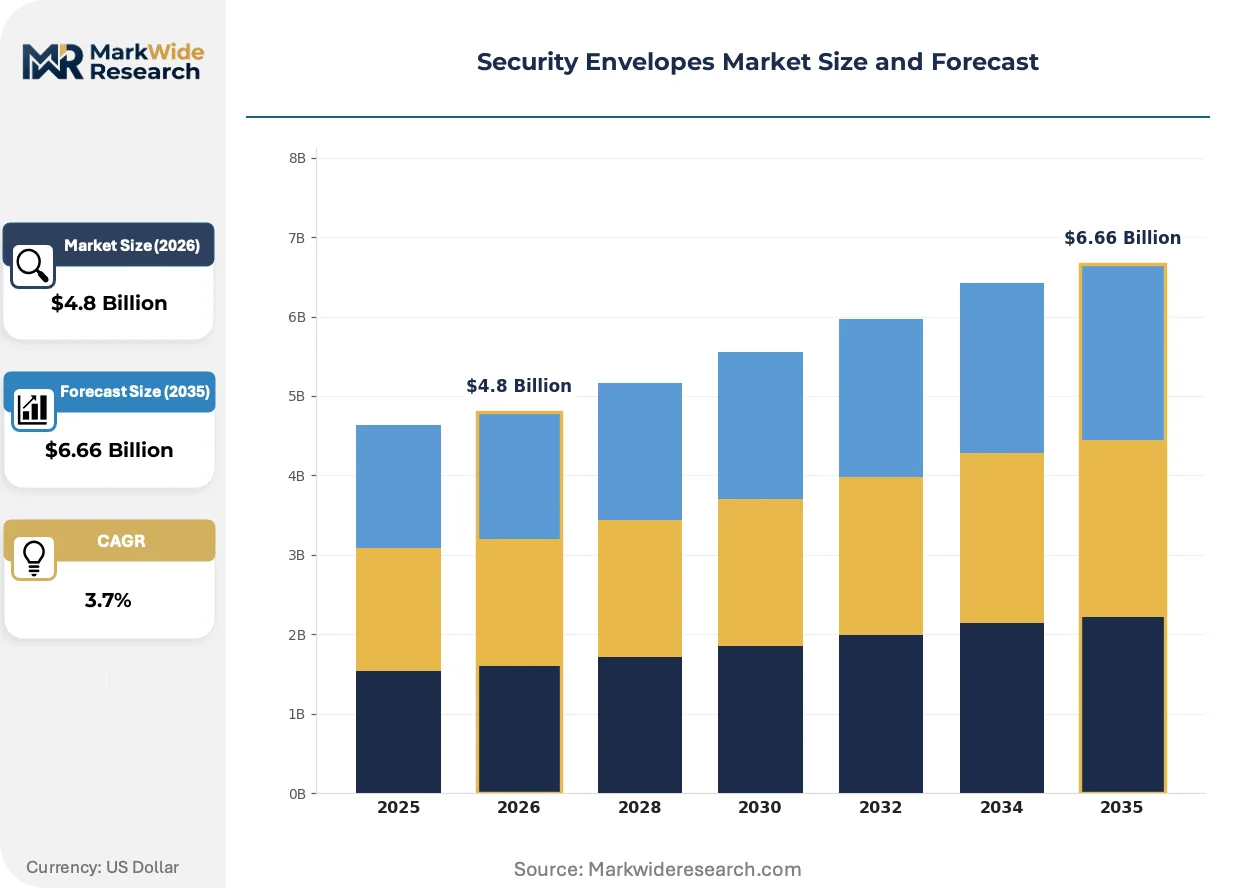
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Paper, Plastic, Tyvek, Polyethylene Closure Type: Self-Seal, Peel & Seal, Gummed, Press-Seal End Use: Banking, Retail, Government, Legal Design Feature: Windowed, Printed, Tamper-Evident, Water-Resistant |
| Companies Covered | Blake Envelopes, National Envelope, Royal Envelope Co., NELMAR Security Packaging Systems, Western States Envelopes & Label, Cenveo Corporation, LA Envelope Inc., Bigname Envelopes, International Plastics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Security Envelopes Market Strategic Shifts
Material science advances and regulatory stringency are fragmenting the historical dominance of commodity kraft paper, creating tiered performance categories around tear resistance, recyclability, and automated processing compatibility.
Void-pattern adhesive technology is decomposing the traditional security envelope value proposition. Fiber tear seams and holographic strips now embed directly into substrate layers rather than applying as secondary features. Major US financial institutions are specifying these integrated formats for high-value check remittance programs. The technology is decomposing the aftermarket security printing segment as primary converters capture tamper-evident functionality in-line.
REACH substance restrictions and EU Green Deal recyclability thresholds are forcing substrate reformulation across European manufacturing bases. ECHA candidate list screenings now cover adhesives and coatings previously exempt from hazardous substance protocols. German envelope converters are absorbing testing costs to maintain Bundesbank supplier status while smaller competitors exit institutional procurement pools.
Centralized procurement functions at consolidated European banking groups are compressing vendor rosters to ISO 27001-certified suppliers exclusively. Relationship-based purchasing through regional distributors is contracting as procurement teams mandate direct contracting with vertically integrated manufacturers. This concentration is most visible in Germany, where Sparkassen and cooperative banking networks have unified envelope specifications under single-source frameworks.
Security Envelopes Market Segmentation
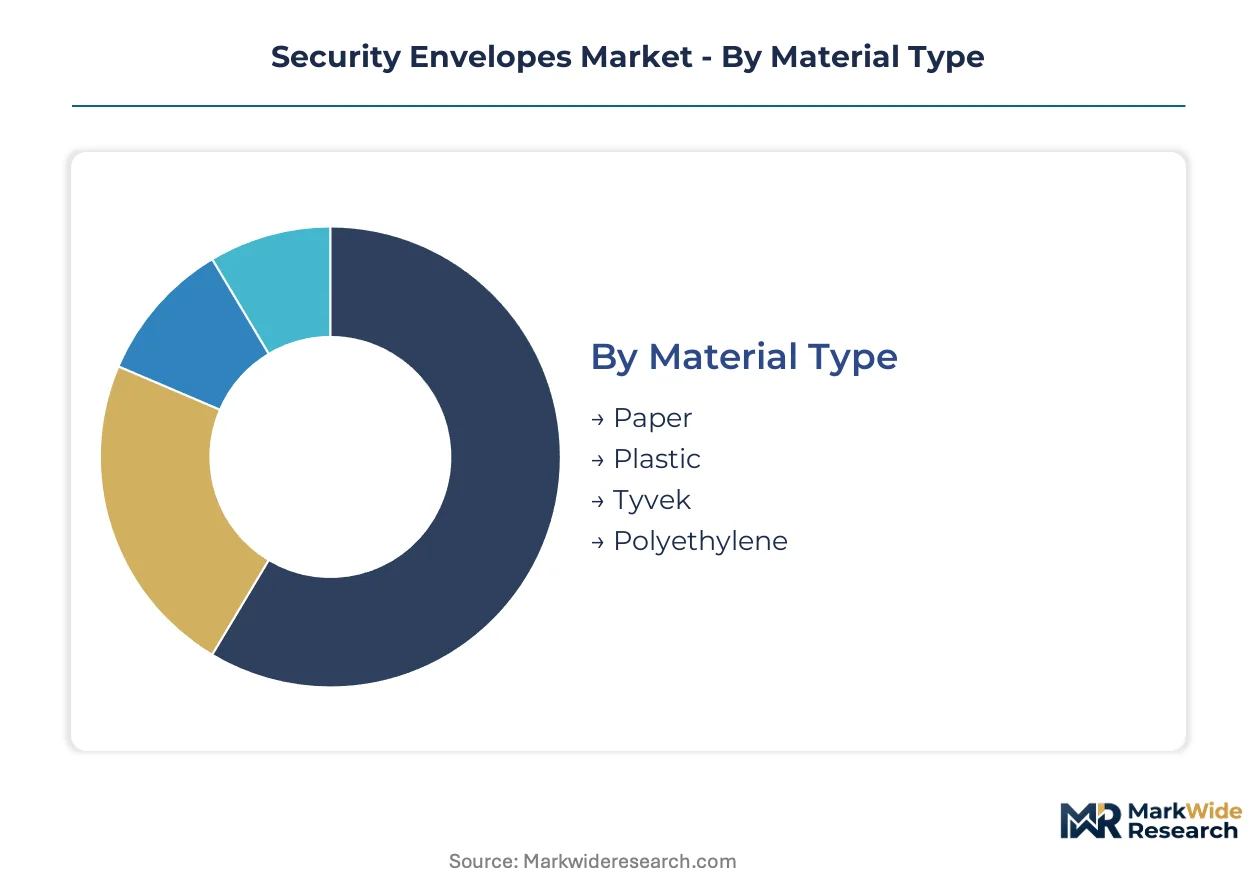
Security envelope procurement splits across four distinct axes that determine compliance burden, automation compatibility, and margin structure. Material and closure specifications carry the heaviest regulatory weight, while end-use and design feature selections drive volume concentration among institutional buyers.
Material Type:
EU Green Deal recyclability thresholds and FDA pharmaceutical mailer requirements create divergent compliance pathways across substrate categories.
- Paper:Kraft-based stock dominates institutional procurement volumes through cost efficiency and established recycling infrastructure. German banking networks specify FSC-certified paper grades for check remittance programs under Bundesbank supplier protocols, though margin compression from pulp price volatility limits converter investment capacity.
- Tyvek:High-density polyethylene spunbond construction delivers tear resistance and archival longevity exceeding paper alternatives by decades. Museums and legal repositories in Switzerland and Austria specify Tyvek for multi-decade document retention, commanding premium positioning despite higher unit costs.
- Plastic:Conventional polyethylene formulations face REACH substance scrutiny across ECHA candidate list screenings, requiring reformulation investments that mid-tier converters struggle to absorb.
- Polyethylene:Specialized extruded grades enable water-resistant performance for pharmaceutical sample distribution under FDA guidelines, with demand concentrating among US healthcare logistics providers.
Established volume favors Paper; emerging adoption favors Tyvek.
Closure Type:
Automation penetration in high-speed insertion environments determines closure format viability across customer tiers.
- Peel & Seal:Pressure-sensitive adhesive strips eliminate moisture activation delays that cause line stoppages in automated processing facilities. Major US financial institutions specify this format for high-volume check remittance programs where throughput metrics dominate procurement criteria.
- Gummed:Traditional moisture-activated adhesives retain position in low-volume manual processing environments and government document protocols where equipment modernization lags. Indian postal security modernization under BIS certification maintains residual demand for gummed formats in rural distribution networks.
- Self-Seal:Two-strip adhesive systems offer intermediate automation compatibility without the premium positioning of Peel & Seal, capturing mid-market commercial banking contracts.
- Press-Seal:Mechanical interlock closures serve specialized tamper-evident applications where adhesive residue concerns limit conventional options, particularly in legal document chains of custody.
Procurement gravity centers on Peel & Seal for automated facilities; Self-Seal captures transitional upgrade demand.
End Use:
ISO 27001 certification requirements and procurement centralization reshape competitive access across institutional buyer categories.
- Banking:Consolidated vendor rosters at European banking groups mandate direct contracting with vertically integrated manufacturers, compressing distributor-mediated relationships. Sparkassen and cooperative networks in Germany have unified envelope specifications under single-source frameworks that exclude uncertified suppliers.
- Government:BIS certification for Indian postal security products and EU defense procurement standards create compliance-driven entry barriers that favor established ISO 27001-certified converters.
- Retail:Mid-market commercial channels compete on scale and turnaround speed rather than certification depth, with price sensitivity limiting substrate upgrade adoption.
- Legal:Document retention protocols and chain-of-custody requirements drive specification toward tamper-evident and archival-grade materials, with smaller practice volumes limiting contract attractiveness for major converters.
Banking concentrates procurement power most intensely; Legal presents niche premium opportunities.
Design Feature:
Security functionality integration and optical verification technologies differentiate product tiers beyond substrate and closure specifications.
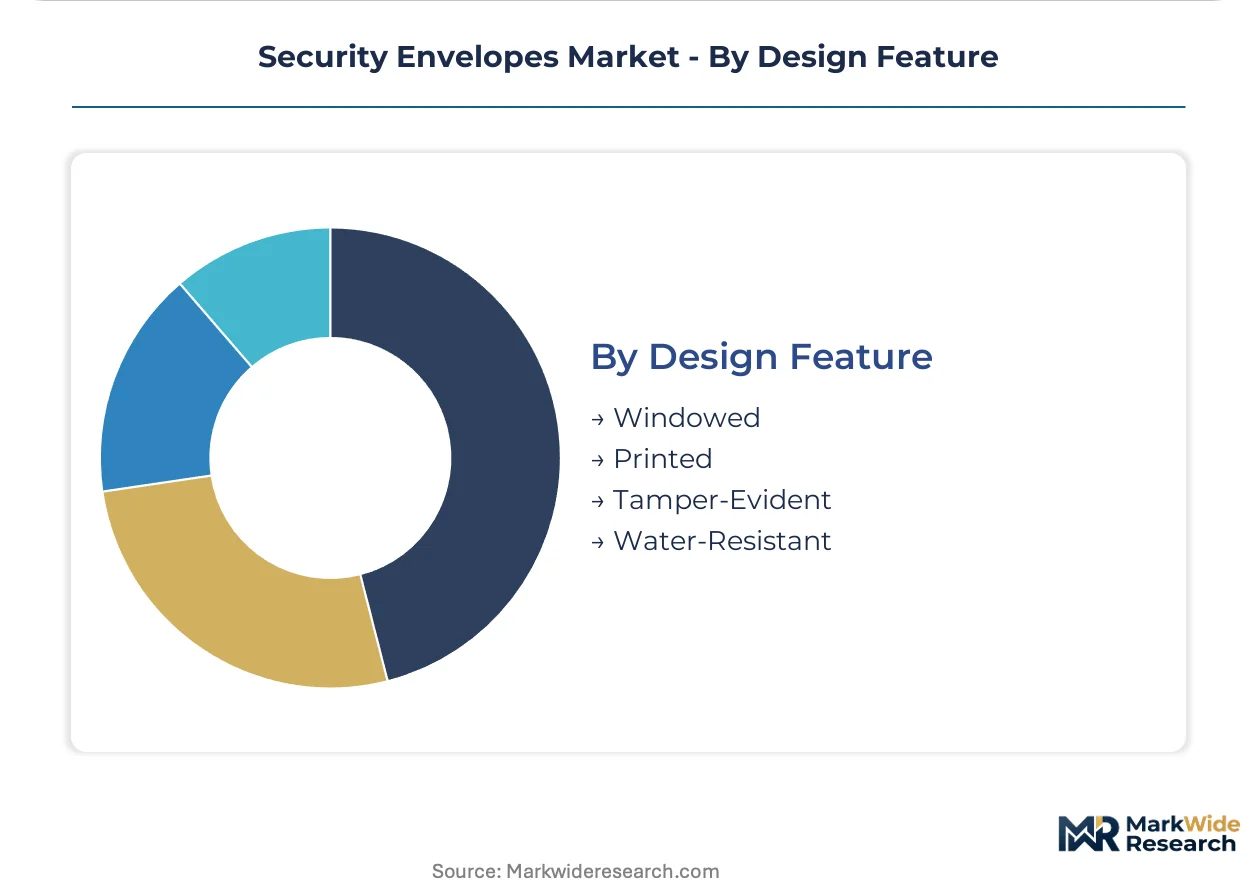
- Tamper-Evident:Void-pattern adhesives and fiber tear seams embed directly into substrate layers rather than applying as secondary features, capturing high-value check remittance specifications from major US financial institutions. The technology compresses aftermarket security printing margins as primary converters capture functionality in-line.
- Windowed:Transparent film panels enable address visibility without envelope opening, serving high-volume transactional mail where processing efficiency outweighs premium security requirements.
- Printed:Custom branding and routing information support corporate treasury and retail distribution applications, with digital substitution pressures reducing growth trajectory.
- Water-Resistant:Specialized coatings and substrate selections serve pharmaceutical sample distribution and outdoor postal operations, with FDA guidelines expanding addressable demand in US healthcare logistics.
Tamper-Evident commands the steepest expansion trajectory; Printed faces headwinds from document digitization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Institutional banking procurement concentrates demand across developed economies, with financial sector consolidation and postal security modernization creating divergent growth vectors by geography.
Germany
Sparkassen and cooperative banking networks drive tamper-evident envelope procurement through unified single-source frameworks. Bundesbank supplier protocols mandate FSC-certified substrates under EU Green Deal thresholds. Manufacturing clusters in North Rhine-Westphalia absorb testing costs to maintain institutional contract eligibility.
United States
Major financial institutions specify Peel & Seal formats for high-volume check remittance programs where throughput metrics dominate. FDA guidelines for pharmaceutical sample mailers expand addressable demand among healthcare logistics providers. Midwestern converters serve automated insertion environments across commercial banking channels.
India
BIS certification requirements for government document mailers create compliance-driven entry barriers favoring ISO 27001-certified suppliers. Postal security modernization maintains residual gummed format demand in rural distribution networks. Manufacturing activity concentrates in Maharashtra and Gujarat for domestic procurement fulfillment.
Switzerland
Museums and legal repositories specify Tyvek substrates for multi-decade document retention protocols commanding premium positioning. Swissmedic-aligned archival standards exceed conventional durability requirements. Zurich and Geneva house specialized converters serving institutional preservation contracts.
United Kingdom
Defense and financial sector relationships sustain domestic manufacturing despite Brexit-adjusted supply chain configurations. ISO 27001 certification rotates as a de facto gate for government contract eligibility. British converters leverage established relationships against continental procurement consolidation.
Security Envelopes Market Competitive Environment
Player mix skews toward vertically integrated specialists and regional scale operators competing on certification depth and automation compatibility. Market structure exhibits moderate concentration with tiered differentiation between premium archival-grade suppliers and commodity kraft converters. Two strategic archetypes dominate: ISO 27001-certified institutional specialists capturing banking and government contracts; scale-driven commercial operators competing on turnaround speed in mid-market channels. Competitive moves center on substrate reformulation investments for EU compliance and direct contracting relationships that bypass distributor networks.
Among North American specialists, NELMAR Security Packaging Systems exemplifies the tamper-evident design archetype, while Western States Envelopes & Label occupies a position within scale-driven commercial channels. Blake Envelopes represents the geographically anchored specialist model, leveraging British manufacturing presence for defense and financial sector access. These three entities illustrate the competitive spectrum without exhausting the vendor landscape.
| Leading Market Players |
|---|
| Blake Envelopes |
| National Envelope |
| Royal Envelope Co. |
| NELMAR Security Packaging Systems |
| Western States Envelopes & Label |
| Cenveo Corporation |
| LA Envelope Inc. |
| Bigname Envelopes |
| International Plastics |
| Others |
Value Chain & Pricing Dynamics
Tyvek displacement of commodity kraft in archival-grade applications simultaneously redraws manufacturing footprints toward specialized polyethylene spinbond facilities and compresses margin structures for legacy paper converters facing EU Green Deal reformulation costs. This substrate migration concentrates pricing power with vertically integrated suppliers capable of absorbing REACH compliance investments while tier-2 regional players cede institutional banking contracts.
Pricing Analysis
Cost-plus contracts indexed to Nordic pulp futures dominate kraft-based procurement, while Tyvek and specialty polyethylene grades command fixed-price premiums tied to certification tier rather than input volatility. Price differentiation separates ISO 27001-certified institutional suppliers from uncertified commercial converters, with the former capturing 40-60% premiums on Bundesbank and Sparkassen frameworks. Pricing pressure stems from EU recyclability mandates forcing substrate reformulation without corresponding buyer willingness to absorb pass-through costs. Mid-market retail channels exhibit acute price sensitivity, whereas banking and government procurement prioritizes compliance depth over unit economics.
Supply Chain Analysis
Inventory lead times stretch 8-14 weeks for FSC-certified paper grades as Nordic timber supply cycles tighten, while Tyvek feedstock from US and Belgian spunbond facilities operates on 4-6 week schedules with price stability clauses. Geographic supply concentration centers on Germany, the United States, and India, with North Rhine-Westphalia manufacturing clusters serving EU banking demand, Midwestern converters feeding automated US check remittance programs, and Maharashtra-Gujarat production fulfilling BIS-certified postal security contracts. Raw material dependencies span Nordic softwood pulp, high-density polyethylene resin, and pressure-sensitive adhesive polymers. Tariff exposure on US-EU polyethylene trade creates margin vulnerability for cross-border Tyvek distributors. Distribution runs through direct contracting with consolidated banking procurement functions, bypassing traditional distributor networks in institutional channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 27001 certification capacity operates as the binding constraint separating contract-eligible suppliers from price-takers, with fewer than twelve converters globally maintaining simultaneous Bundesbank, BIS, and major US financial institution approvals. This credential scarcity justifies defensive consolidation moves among incumbents and targeted capability acquisition by new entrants.
For Market Incumbents: Secure certification maintenance through accelerated audit cycles and captive testing laboratory investments to defend against emerging Asian converters acquiring ISO 27001 credentials through acquisition. Prioritize backward integration into FSC-certified pulp supply or polyethylene resin offtake agreements to isolate margin structures from Nordic timber volatility and REACH substance restriction cascades. For New Entrants and Emerging Players: Aftermarket security printing services represent the most penetrable white-space as primary converters capture tamper-evident functionality in-line and displace legacy void-pattern adhesive applicators. Target Indian postal security modernization under BIS certification timelines, where incumbent European suppliers face logistics cost disadvantages and local manufacturing partnerships can satisfy domestic content preferences. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-cap converters in Germany and the United Kingdom holding dormant ISO 27001 certifications and underutilized Tyvek extrusion capacity. Long-term viability hinges on substrate portfolio breadth spanning paper, polyethylene, and archival-grade synthetics. Watch for EU Packaging and Packaging Waste Regulation enforcement variance across member states as the signal for margin compression acceleration or relief.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 27001 Certification Acceleration | Compresses vendor rosters at Sparkassen and cooperative banking networks to certified suppliers exclusively. |
| Tyvek Extrusion Capacity Expansion | Captures museum and legal repository demand in Switzerland and Austria for multi-decade archival protocols. |
| Backward Integration into Pulp Supply | Isolates margin structures from Nordic timber price cycles squeezing kraft converter profitability. |
| Direct Contracting Relationship Development | Bypasses distributor networks as European banking procurement centralizes under single-source frameworks. |
| REACH Substance Reformulation Investment | Maintains ECHA compliance eligibility for EU institutional contracts exiting non-compliant competitors. |
Study Parameters
A spread of perspectives from envelope manufacturing plant managers, banking procurement officers at consolidated European financial institutions, postal security directors at BIS-regulated Indian operators, and adhesive polymer technical directors converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through customs trade data for kraft paper and polyethylene resin flows, SEC filings from listed packaging converters, EU ECHA substance registration databases, and Bundesbank supplier registry documentation. Bottom-up volume estimates from end-use segmentation triangulated against top-down macroeconomic envelope consumption proxies.
Segmentation dimensions modeled span material substrate category, closure format automation compatibility, end-use institutional buyer type, and security feature integration level across the projection horizon. CAGRs derive from regression-weighted historical consumption patterns adjusted for regulatory inflection points including EU Packaging and Packaging Waste Regulation phased implementation and FDA pharmaceutical mailer guideline expansion. Industry-specific forecast inputs incorporate check remittance volume trajectories at major US financial institutions and Indian postal modernization procurement schedules.
Underlying assumptions cover sustained EU Green Deal enforcement stringency, stable Nordic timber supply availability, and continued banking sector procurement centralization, with deviation risk concentrated in digital document substitution acceleration and REACH substance list expansion beyond current ECHA candidate screenings. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Tripod Market
Others
Global Multi-Access Edge Computing Market
Others
Deep Sea Mining Market
Others
Middle East and Africa Cocoa Products Market
Others
Asia Pacific Cloud Infrastructure Testing Services Market
Others
North America Industrial Wearable Devices Market
Others
Voice Controlled Devices Market
Others
Wearable AI Market
Others
Foldable Smartphone Market
Others
Digital Transformation of Maritime Freight Market
Others
Sprockets Market
Others
Hybrid Switchgear Market
Others
Mainframe Computers Market
Others
Cloud Digital Video Recorder Market
Others
Global Enterprise Mobility in Healthcare Market
Others
Asia-Pacific Road Safety Market