
 Cashew Kernel Market | 2026-2036
Cashew Kernel Market Size, Share, and Industry Trends Forecast 2026-2036
Cashew Kernel Market Analysis
Vietnamese processor networks is repositioning toward higher-value W180 and W210 grades as raw nut costs climb across West African origins. Olam International leverages vertical integration from farm-gate sourcing through roasting facilities to secure margin capture. VINACAS anchors national export volumes through collective bargaining with Ivory Coast and Ghana suppliers. John B. Sanfilippo & Son Inc. differentiates via branded retail presence in North American grocery channels.
Cashew kernel denotes the edible seed of Anacardium occidentale, typically graded by kernel count per pound with W180 representing the largest and most premium classification. The roasting and pasteurization processes determine shelf stability, flavor profile, and compliance with ready-to-eat food safety protocols for downstream bakery and snack applications. W320 grade dominates volume flows due to its price-accessibility balance for food processing buyers, while vacuum pack formats command margin premiums through extended shelf-life guarantees. Specialty stores and online channels represent the fastest-expanding distribution vectors as direct-to-consumer nut brands bypass traditional wholesale tiers.
FDA food safety modernization rules and FSSAI contaminant thresholds shape import acceptance criteria for roasted kernel shipments entering the United States and India respectively. REACH chemical safety protocols in Europe restrict certain fumigation residues used in bulk storage, redirecting processor investment toward controlled-atmosphere alternatives. Stakeholders must monitor evolving mycotoxin limits across destination markets and assess backward integration into African shelling operations as a supply security hedge.
Market Dynamics
Raw nut procurement costs from Ivory Coast and Ghana are compressing processor margins while simultaneously accelerating grade stratification, forcing Vietnamese and Indian facilities to prioritize W180 and W210 classifications over commoditized W320 volumes.
Growth Catalysts
- FSSAI contaminant thresholds:India's tightened mycotoxin limits for imported kernels are pushing domestic processors to upgrade pasteurization infrastructure, creating certified-supply premiums for compliant exporters.
- Roasting automation:Continuous-flow thermal processing systems are reducing labor dependency in Vietnam's Binh Phuoc facilities while standardizing moisture content for North American snack manufacturers.
- West African shelling clusters:Ivory Coast's mechanized cracking cooperatives are shortening transit times to Ho Chi Minh City processors, tightening the farm-gate-to-factory window for raw material freshness.
Market Restraints
- Raw material cost volatility:Cashew nut-in-shell prices fluctuate with West African rainfall patterns, exposing processors to margin erosion during drought cycles in Ghana and Guinea-Bissau.
- REACH fumigation restrictions:ECHA protocols banning methyl bromide residues are forcing European importers to reject conventional bulk storage methods, raising compliance costs for traditional shippers.
- Kernel breakage rates:Mechanical shelling technologies still generate 12-18% whole-kernel loss versus hand-cracking, limiting scale economies in automated African facilities.
Strategic Opportunities
- Specialty retail channels:Direct-to-consumer nut brands in Germany and the Netherlands are bypassing wholesale tiers through subscription models, capturing margin pools previously held by distributors.
- PLI scheme alignment:India's production-linked incentive framework for food processing offers capital subsidies for integrated roasting and packaging lines serving export markets.
- Controlled-atmosphere storage:Nitrogen-flushed vacuum formats are extending shelf life guarantees from 12 to 24 months, enabling ocean freight substitution for air cargo on trans-Pacific routes.
Industry Challenges
- Traceability system integration:Blockchain-enabled farm-to-fork tracking demanded by FDA food safety modernization rules requires middleware upgrades incompatible with legacy ERP systems in mid-sized Vietnamese processors.
- Skilled thermal operator scarcity:Roasting profile optimization for flavor consistency depends on experienced technicians, yet training pipelines in India's Kerala processing belt have contracted since 2020.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cashew Kernel Market |
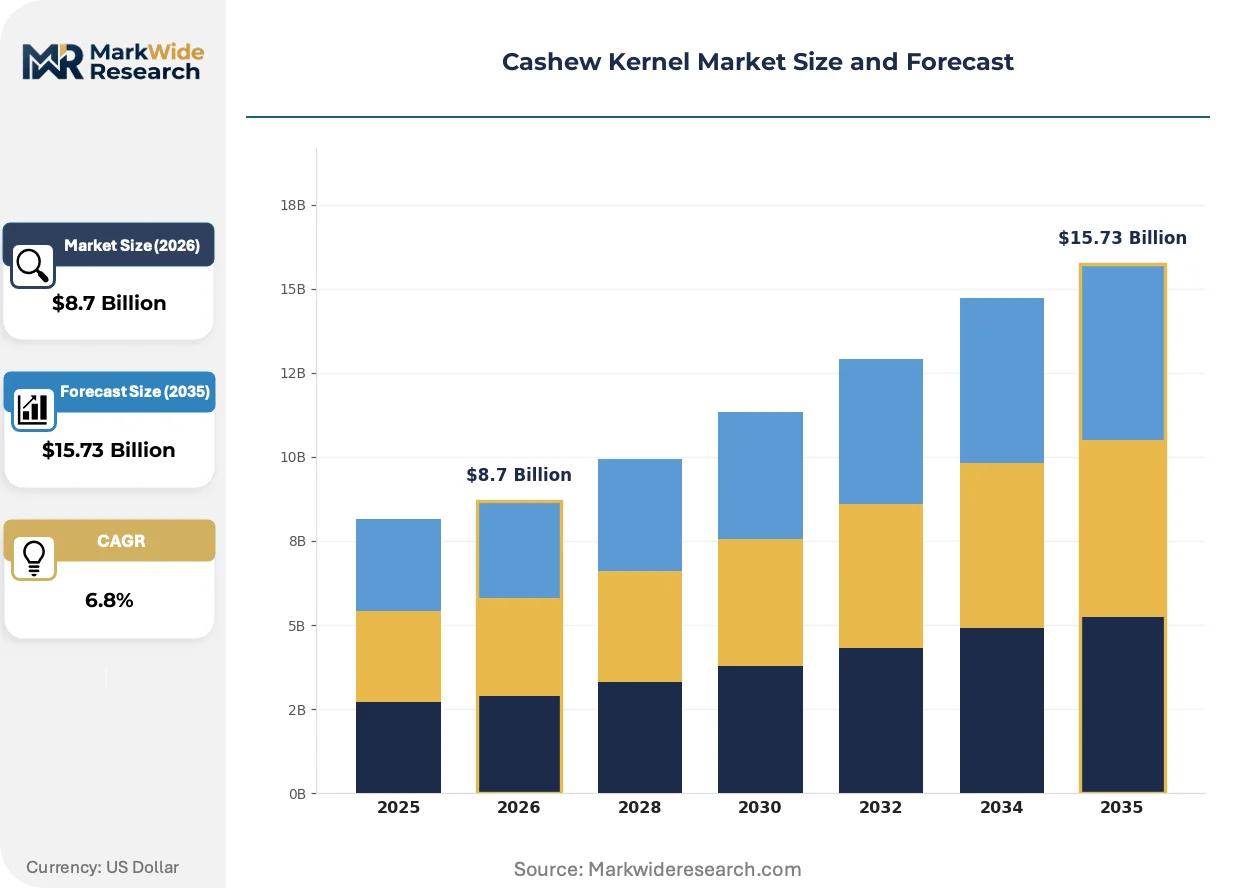
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: W180, W210, W240, W320 Packing Type: Inner Pack, Bulk Pack, Retail Pack, Vacuum Pack Distribution Channel: Online, Supermarkets, Wholesale, Specialty Stores End User: Food Processing, Bakery, Snack Food, Food Service |
| Companies Covered | Nestlé S.A., Archer Daniels Midland Company, Bunge Limited, Vietnam Cashew Corporation (VINACAS), Olam International, Haldiram Foods International Private Limited, John B. Sanfilippo & Son Inc., Alphonsa Cashew Industries, Nutsco Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cashew Kernel Market Emerging Trajectories
Processing technology and regulatory compliance frameworks are converging to reshape competitive positioning in kernel classification and preservation methods, with automation and chemical safety protocols driving capital allocation decisions.
Steam pasteurization systems are replacing oil-roasting for pathogen reduction in facilities supplying ready-to-eat channels. North American bakery and snack manufacturers are adopting these systems at accelerated cadences to meet FDA food safety modernization rule documentation requirements. This shift is absorbing margin pressure from energy-intensive thermal processes while enabling shorter production cycles for just-in-time retail replenishment.
REACH chemical safety protocols in Europe are restricting phosphine fumigation residues permitted in bulk kernel shipments entering Rotterdam and Hamburg ports. ECHA's tightened maximum residue limits are redirecting processor investment toward carbon dioxide-based controlled atmosphere alternatives. German and Dutch importers are now requiring third-party certification of fumigation-free status for contract renewals, disadvantaging traditional bulk handlers.
Food service buyers are consolidating procurement through approved-supplier programs rather than spot-market purchasing. Large North American snack manufacturers are disqualifying non-vertically integrated processors from vendor lists, replacing fragmented multi-source buying with single-source accountability. This concentration is most visible in California and Texas distribution corridors where direct mill-to-warehouse contracts now dominate volume flows.
Cashew Kernel Market Segmentation
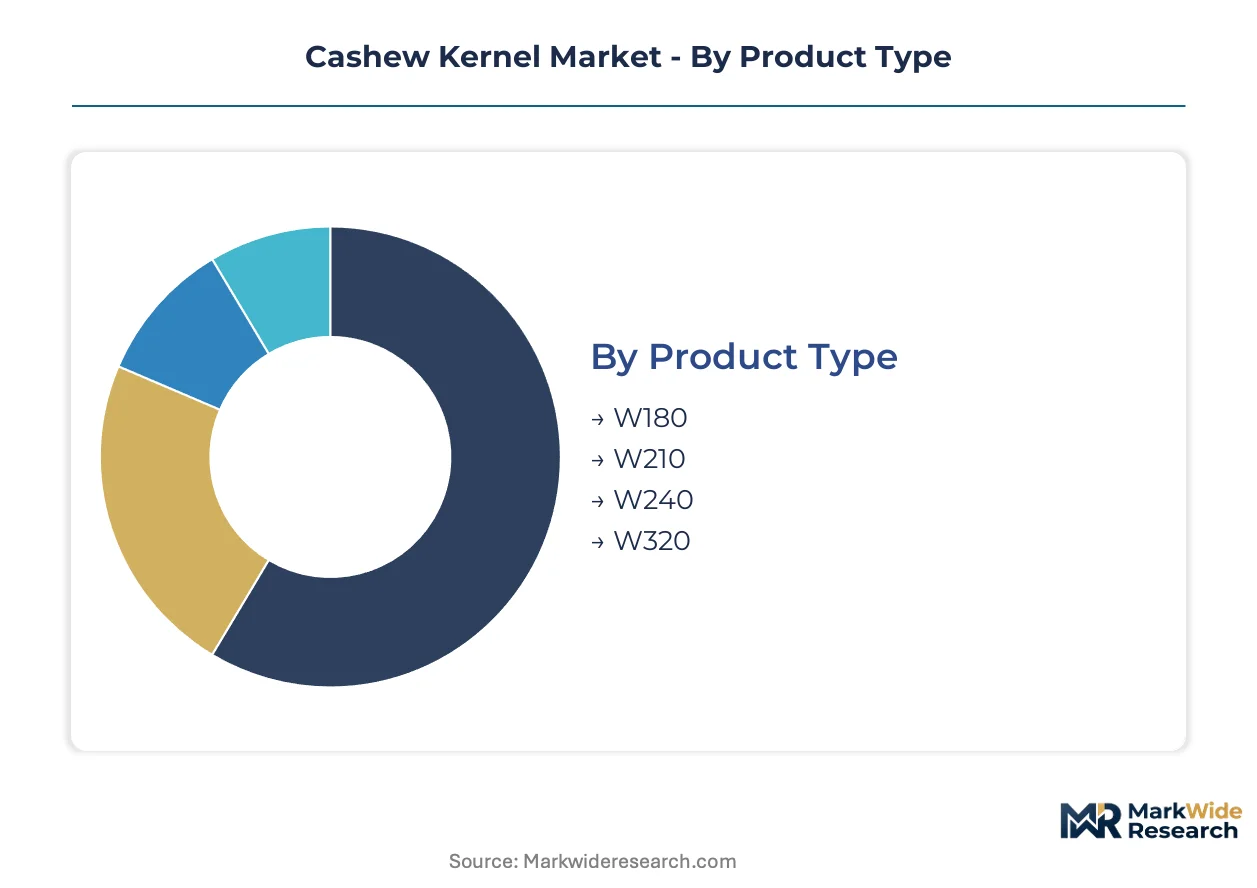
Cashew kernel segmentation reflects the tension between commodity-grade volume flows and premium-grade margin capture. Grade stratification and packaging format decisions determine processor profitability and end-market access.
Product Type:
Whole kernel grades span standalone premium applications through embedded food-manufacturing inputs, with size classification directly mapping to price tier and end-use suitability.
- W180:The largest whole kernel classification, commanding maximum unit value in gift-box and luxury confectionery channels. Indian premium exporters concentrate W180 volumes toward Middle Eastern and European specialty retailers where kernel visual uniformity determines placement.
- W210:Slightly smaller whole kernels finding strongest traction in North American natural food stores and direct-to-consumer subscription services. Vietnamese processors prioritize W210 for its balance of yield recovery and price accessibility relative to W180 scarcity.
- W240:Mid-tier whole kernels serving mainstream roasted snack applications where size consistency matters less than cost control.
- W320:The dominant volume grade, embedded ubiquitously across bakery mixes, granola production, and industrial food manufacturing where kernel pieces are acceptable.
W320 leads volumes today; W180 is gaining share fastest.
Packing Type:
Packaging configuration determines shelf-life economics and channel eligibility, with cost tier directly correlating to atmosphere control sophistication.
- Vacuum Pack:Nitrogen-flushed barrier formats extending shelf stability to 24 months, enabling ocean freight substitution for air cargo on trans-Pacific routes to North American distributors.
- Retail Pack:Consumer-facing formats with branding real estate, capturing margin premiums in German and Dutch specialty stores through direct-to-consumer bypass of wholesale tiers.
- Inner Pack:Intermediate bulk formats for food service and institutional procurement, balancing handling efficiency with portion control.
- Bulk Pack:Traditional jute or polypropylene sacks for industrial buyers, facing displacement from REACH-compliant alternatives as ECHA fumigation restrictions tighten.
Bulk Pack still dominates tonnage; Vacuum Pack shows the steepest expansion trajectory.
Distribution Channel:
Channel selection separates spot-market commodity flows from contracted premium distribution, with customer type determining fulfillment infrastructure requirements.
- Specialty Stores:Curated retail environments in the Netherlands and Germany where origin labeling and organic certification command price premiums from discerning consumers.
- Online:Direct-to-consumer platforms and subscription models capturing margin pools previously held by distributors, with fastest expansion in North American urban corridors.
- Supermarkets:Mass retail placement requiring scale supply commitments and promotional funding, favoring W320 volume suppliers with national distribution reach.
- Wholesale:Traditional tiered distribution for food service and small processing accounts, facing compression as approved-supplier programs consolidate procurement.
Wholesale retains the largest transaction count; Online climbs the fastest.
End User:
End-use application dictates kernel specification, pasteurization requirements, and supply security protocols, with food safety liability concentrating procurement among certified processors.
- Snack Food:Ready-to-eat roasted kernel demand from North American manufacturers requiring FDA food safety modernization rule documentation and steam pasteurization systems for pathogen reduction.
- Food Processing:Industrial ingredient buyers consolidating procurement through approved-supplier programs, disqualifying non-vertically integrated processors from vendor lists.
- Bakery:Kernel piece and fragment applications where W320 grade suitability and moisture content consistency determine batch performance.
- Food Service:Restaurant and hospitality procurement shifting from spot-market purchasing toward contracted supply with traceability guarantees.
Food Processing leads volume absorption; Snack Food expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnam processes more raw cashew than India, yet India's domestic consumption absorbs larger kernel volumes through its snack food and confectionery channels.
Vietnam
Binh Phuoc province hosts the densest concentration of mechanized shelling and roasting facilities serving export markets. VINACAS coordinates collective bargaining with Ivory Coast suppliers to stabilize raw nut inflows. Ho Chi Minh City's logistics corridor channels W180 and W210 grades toward European specialty retailers.
India
Kerala's processing belt specializes in hand-cracked whole kernels for Middle Eastern gift-box markets. FSSAI tightened mycotoxin thresholds in 2023, forcing pasteurization infrastructure upgrades across Maharashtra and Gujarat facilities. The PLI scheme for food processing subsidizes integrated roasting and packaging lines in Karnataka's emerging industrial zones.
United States
California and Texas distribution corridors now favor direct mill-to-warehouse contracts over spot-market purchasing. FDA food safety modernization rules mandate documentation for steam pasteurization systems. Large snack manufacturers in the Midwest are consolidating procurement through approved-supplier programs that disqualify non-vertically integrated vendors.
Germany
REACH protocols banning methyl bromide residues have redirected importer preferences toward controlled-atmosphere storage alternatives. Rotterdam and Hamburg ports now require third-party certification of fumigation-free status for contract renewals. Specialty retailers in Berlin and Munich capture premium margins through origin-labeled organic kernels.
Ivory Coast
Mechanized cracking cooperatives in the northern growing regions are shortening transit times to Asian processors. The national cashew council promotes farm-gate quality standards to reduce breakage rates in automated shelling. Abidjan's port infrastructure expansion targets direct containerized shipments to Ho Chi Minh City.
Cashew Kernel Market Vendor Landscape
Vietnamese producers anchor one tier; Indian specialists hold another through distinct grade positioning and channel access. The market structure fragments across scale-driven exporters, domestic brand owners, and African-origin processors. Three archetypes dominate: vertically integrated traders controlling farm-gate sourcing, regional roasting specialists serving branded retail, and cooperative federations aggregating smallholder output. Competitive moves center on backward integration into West African shelling operations and automation investments in thermal processing.
Among publicly traded agribusiness conglomerates, Olam International exemplifies the integrated trader archetype through captive supply chains spanning multiple origins. John B. Sanfilippo & Son Inc. occupies a position within the North American branded retail tier. VINACAS represents the cooperative federation model, anchoring national export volumes through collective bargaining structures.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Archer Daniels Midland Company |
| Bunge Limited |
| Vietnam Cashew Corporation (VINACAS) |
| Olam International |
| Haldiram Foods International Private Limited |
| John B. Sanfilippo & Son Inc. |
| Alphonsa Cashew Industries |
| Nutsco Inc. |
| Others |
Supply Flow & Price Mechanics
North American snack food manufacturers consolidate procurement through approved-supplier programs, anchoring contract-based long-term offtake pricing that insulates premium grades from spot-market volatility while compressing margins for non-vertically integrated processors.
Pricing Analysis
Capacity additions in Vietnam's Binh Phuoc province are reshaping price floors for W320 commodity grades while W180 and W210 premiums widen. Three-tier pricing structure across premium, standard, and economy levels separates hand-cracked whole kernels from mechanized output from broken grades. Cost compression in West African raw nut procurement is intensifying because drought cycles in Ghana and Guinea-Bissau expose processors to margin erosion. Food service buyers show highest price sensitivity; gift-box and luxury confectionery channels demonstrate lowest.
Supply Chain Analysis
Single-source vulnerability sits with Ivory Coast and Ghana for raw nut-in-shell supply, with Vietnam and India dominating kernel processing. The supply chain draws from West African farm-gate cooperatives, Asian roasting facilities, and European specialty retailers. Commodity price volatility in cashew nut-in-shell markets creates structural risk as rainfall-dependent harvests fluctuate. Distribution runs through Ho Chi Minh City logistics corridors for Asian exports and direct mill-to-warehouse contracts for North American snack manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cashew kernel market functions as a stable compounder, with FSSAI and FDA food safety modernization rules driving steady infrastructure investment cycles that sustain processor differentiation.
For Market Incumbents: Acquire mechanized shelling capacity in Ivory Coast's northern growing regions to shorten farm-gate-to-factory windows and secure raw material freshness. Invest in steam pasteurization systems to meet FDA documentation requirements for North American ready-to-eat channels. Threat of REACH fumigation restrictions disadvantaging traditional bulk handlers makes controlled-atmosphere storage certification a critical lever for European contract retention. For New Entrants and Emerging Players: Blockchain-enabled traceability platforms offer technology-first entry into approved-supplier programs disqualifying legacy processors. White-space concentrates in German and Dutch direct-to-consumer subscription services where origin-labeled organic kernels command premium margins. Target specialty retail channels with nitrogen-flushed vacuum formats that enable ocean freight substitution and 24-month shelf-life guarantees. For Investors and Strategic Acquirers: Branded snack food conglomerates represent the most active acquirer in this space, seeking backward integration into African shelling operations. Long-term viability rests on processors demonstrating certified compliance across multiple regulatory jurisdictions. Acquisition target archetype: mid-scale Vietnamese or Indian facilities with existing FSSAI certification and underutilized roasting capacity. Signal to watch: consolidation of procurement by North American snack manufacturers into single-source accountability structures.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into West African Shelling | Captures margin pools from farm-gate sourcing through Ho Chi Minh City processing corridors. |
| Steam Pasteurization Infrastructure Deployment | Enables FDA food safety modernization rule compliance for ready-to-eat snack channels. |
| Controlled-Atmosphere Storage Certification | Satisfies ECHA REACH protocols banning methyl bromide residues in European bulk shipments. |
| Blockchain Traceability Middleware Installation | Responds to FDA farm-to-fork documentation demands incompatible with legacy ERP systems. |
| Direct-to-Consumer Channel Launch | Bypasses wholesale tiers in German and Dutch specialty retail to capture distributor margin pools. |
Methodological Framework
Coverage spans Vietnam, India, Ivory Coast, Germany, and the United States, with primary inputs from each market combining interviews with processing facility managers, export cooperative directors, snack food manufacturer procurement leads, and specialty retail category buyers. Secondary validation draws from FSSAI regulatory filings, ECHA REACH guidance documents, FDA food safety modernization rule dockets, and Vietnam Cashew Association trade statistics. Bottom-up facility capacity assessments and top-down trade flow analysis enable triangulation.
Granularity-level modeling disaggregates volume and value across kernel grade classification, packaging atmosphere control tier, distribution channel structure, and end-use application requirements. CAGRs derive from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporate FSSAI mycotoxin threshold enforcement timelines and West African mechanized shelling cooperative formation rates.
The model holds under stable regulatory enforcement intensity; deviation in FDA audit frequency or ECHA maximum residue limit revisions would shift processor compliance cost assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Deep Sea Mining Market
Others
Europe Indoor Air Purification Market
Others
Next Gen Video Codecs Market
Others
US Quantum Computing Market
Others
Global Thermally Conductive Grease Market
Others
Global Retail Media Networks Market
Others
Global Fertility Tracking Apps Market
Others
Europe Aircraft Lighting Systems Market
Others
France Automotive LED Lighting Market
Others
Hybrid Switchgear Market
Others
Infant Fever Stickers Market
Others
Global Food Fiber Market
Others
Safety Critical Software Testing Market
Others
Digital LUX Meter Market
Others
Air Separation Plant Market
Others
North America Video Conferencing Hardware Market