
 Lined Tank Market | 2026-2036
Lined Tank Market Size, Share, and Industry Trends Forecast 2026-2036
Lined Tank Market Outlook
The gap between engineered fluoropolymer linings and commodity polyethylene shells is rebalancing as project engineers weigh lifecycle costs against upfront capital. Poly Processing leverages vertical integration in rotational molding to control resin sourcing and quality consistency. CST Industries sustains geographic dominance in bolted steel tanks with integrated glass-fused-to-steel linings for water and wastewater applications. Pfaudler Group differentiates through specialized alloy and fluoropolymer linings for aggressive chemical service.
A lined tank is a vessel incorporating an internal protective barrier—typically polyethylene, fiberglass, carbon steel, or stainless steel—bonded or suspended within a structural shell to prevent corrosion, contamination, or leakage during storage, transportation, treatment, or mixing operations. Manufacturing methods include rotational molding, filament winding, and weld-overlay cladding, with liner thickness and chemical resistance ratings determining service life in acidic or caustic environments. Stainless steel linings command premium positioning in food and beverage applications where FDA sanitary standards apply, while fiberglass-reinforced plastic segments gain traction in water and wastewater treatment for chlorine resistance and design flexibility. Carbon steel with rubber or epoxy linings remains the volume workhorse in oil and gas storage, though margin pools are thinning as commodity competition intensifies.
EPA regulations under the Spill Prevention, Control, and Countermeasure program mandate secondary containment and integrity testing for aboveground tanks, directly shaping liner specification requirements in chemical and petroleum end uses. ASTM D1998 for polyethylene tanks and API 650 Appendix H for internal floating roofs establish material and design benchmarks that manufacturers must meet for market access. Stakeholders should monitor evolving state-level groundwater protection rules and material substitution trends as fluoropolymer costs fluctuate and bio-based liner alternatives advance through pilot testing phases.
Market Dynamics
The US EPA Spill Prevention, Control and Countermeasure program is compressing replacement cycles for aging aboveground storage infrastructure, forcing facility operators to prioritize corrosion-resistant liner specifications over initial capital outlays.
Growth Catalysts
- EPA SPCC Rule Tightening:The US EPA's expanded integrity testing mandates for aboveground chemical storage are accelerating liner replacement schedules at Texas Gulf Coast refineries and chemical processing complexes.
- Fluoropolymer Performance Gains:Advanced PTFE and ETFE lining formulations are extending service intervals in sulfuric acid and hydrochloric acid service beyond traditional rubber or epoxy alternatives.
- Water Infrastructure Modernization:Municipal wastewater treatment expansions across the United States are specifying glass-fused-to-steel and epoxy-lined carbon steel tanks for chlorine and UV resistance.
Market Restraints
- Resin Input Volatility:Polyethylene and fluoropolymer resin prices track ethylene and fluorochemical feedstock markets, compressing margin visibility for rotational molders.
- Fabrication Labor Scarcity:Certified weld-overlay technicians for alloy-lined pressure vessels concentrate in the Gulf Coast and Great Lakes industrial corridors, constraining capacity expansion elsewhere.
- ASTM D1998 Compliance Burden:Third-party certification and hydrostatic testing requirements for polyethylene tank manufacturing add fixed cost layers that disadvantage smaller fabricators.
Strategic Opportunities
- Carbon Capture Storage:Amine-based CO2 capture facilities are emerging as a new specification channel for stainless-clad carbon steel tanks resisting corrosive solvent chemistry.
- Modular Field-Erected Systems:Bolted steel tank designs with factory-applied linings are reducing site construction timelines for remote mining and power generation installations.
- Remanufacturing Services:In-situ liner rehabilitation and recoating offerings are capturing aftermarket value from installed base owners seeking to defer full tank replacement.
Industry Challenges
- Multi-Material Welding Certification:Fabricators serving dual chemical and food-grade markets must maintain separate ASME and 3-A Sanitary Standards qualifications, fragmenting workforce training investments.
- Legacy Tank Assessment Protocols:Non-destructive evaluation of existing lined vessels using ultrasonic and eddy current methods requires specialized technicians in short supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lined Tank Market |
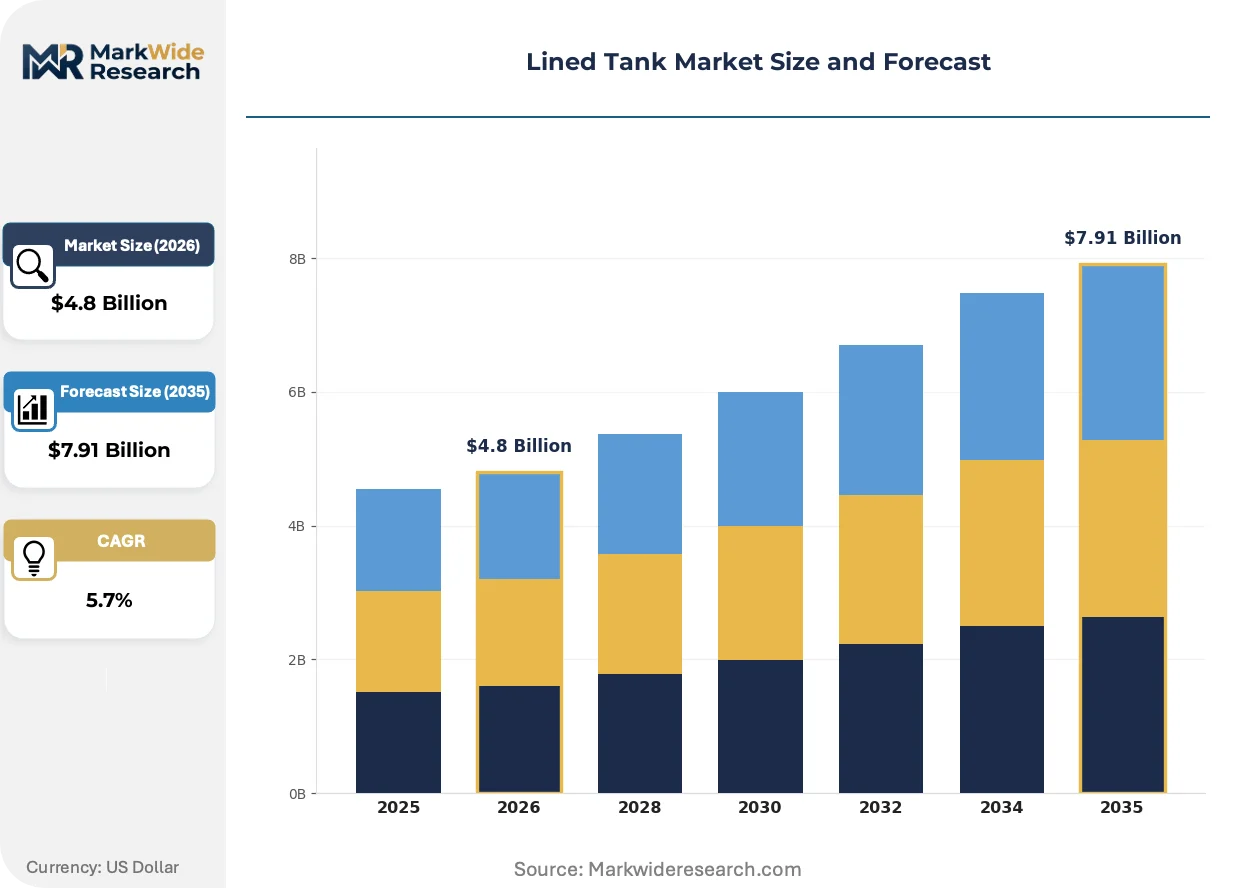
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Fiberglass, Carbon Steel, Stainless Steel End User: Chemical Manufacturing, Food and Beverage, Water and Wastewater, Oil and Gas Application: Storage, Transportation, Treatment, Mixing Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | Poly Processing, HMT LLC, CST Industries, Niles Steel Tank, Caldwell Tanks, Tank Connection, Cleveland Tank, Pfaudler Group, Snyder Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lined Tank Market Strategic Shifts
Digital inspection technologies and advanced polymer formulations are compressing maintenance intervals while expanding the chemical resistance envelope of lined storage systems.
Mobile robotic ultrasonic scanning systems are decentralizing tank integrity assessment by enabling in-service evaluation without draining or cleaning vessels. Chemical processors in the Texas Gulf Coast and Ohio River Valley petrochemical corridors are adopting these systems on quarterly cycles. This capability is decentralizing maintenance planning from centralized engineering departments to site operations teams.
The US EPA's finalized methane emissions rules for petroleum storage are mandating vapor recovery system integration with aboveground tank designs. Tank fabricators must now engineer liner-to-roof sealing interfaces that maintain chemical resistance while accommodating floating roof mechanisms. Chemical terminals along the Houston Ship Channel are retrofitting existing tanks with modified liner termination details to meet these requirements.
Engineering-procurement-construction firms are consolidating supplier relationships around single-source tank-and-liner packages. Midstream oil and gas operators are shifting from component bidding to performance-specification contracting. This consolidation is most pronounced in Permian Basin water handling and Delaware Basin produced water storage projects.
Lined Tank Market Segmentation
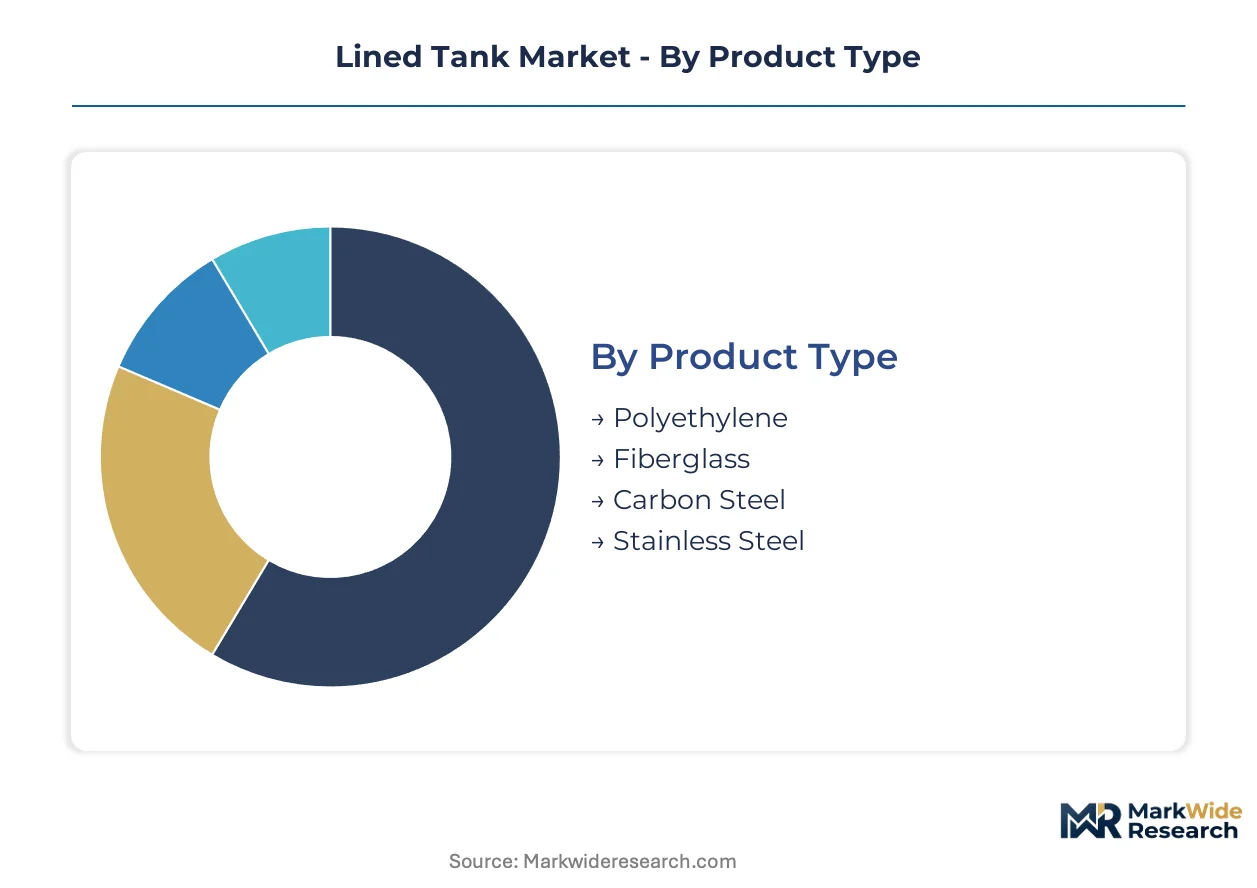
Liner material selection dictates capital deployment patterns across the Lined Tank Market, with fluoropolymer and alloy specifications requiring substantially higher upfront investment than commodity polyethylene alternatives. End-use concentration in chemical processing and petroleum storage creates divergent specification requirements that fragment procurement strategies. Understanding these segment boundaries clarifies where margin pools concentrate versus where volume commoditization pressures dominate.
Product Type:
Capital intensity varies sharply across liner technologies, with fluoropolymer and stainless steel specifications demanding 3-5x the upfront investment of commodity polyethylene systems.
- Polyethylene:Rotationally molded high-density polyethylene liners dominate bulk chemical and water storage through cost-efficient manufacturing at lower pressure ratings. Demand concentrates in municipal wastewater expansions across the Texas Gulf Coast where chlorine resistance and design flexibility outweigh premium material performance.
- Stainless Steel:Weld-overlay or solid stainless constructions command premium positioning in food and beverage applications requiring FDA sanitary compliance and clean-in-place capability. Texas and California dairy processing facilities are expanding orders for 316L and duplex grades to meet stringent hygiene protocols.
- Fiberglass:Filament-wound FRP tanks with vinyl ester or epoxy matrices serve corrosive chemical environments where metal fatigue risks dominate.
- Carbon Steel:Rubber-lined or epoxy-coated carbon steel remains the volume workhorse in oil and gas storage, though margin compression from commodity competition intensifies.
Carbon steel absorbs the bulk of installed capacity; stainless steel is expanding most quickly.
End User:
Specification authority resides with distinct engineering teams across end-use sectors, creating fragmented procurement channels with divergent compliance requirements.
- Chemical Manufacturing:Aggressive acid and caustic service drives demand for fluoropolymer-lined vessels with extended service intervals. Gulf Coast petrochemical complexes are replacing aging rubber-lined tanks with PTFE and ETFE specifications to meet tightened EPA SPCC integrity mandates.
- Oil and Gas:Produced water handling and midstream storage require corrosion-resistant linings in high-salinity environments. Permian Basin operators are consolidating supplier relationships around single-source tank-and-liner packages for water recycling infrastructure.
- Water and Wastewater:Municipal treatment expansions specify glass-fused-to-steel and epoxy-lined tanks for chlorine and UV resistance.
- Food and Beverage:Sanitary-grade stainless linings dominate where 3-A Standards and FDA compliance apply.
Chemical manufacturing absorbs the bulk of installed capacity; oil and gas is expanding most quickly.
Application:
Functional requirements determine liner thickness, seam welding protocols, and inspection intervals across the operational lifecycle.
- Storage:Static containment applications dominate volume, with aboveground tanks subject to EPA SPCC secondary containment and integrity testing rules. Houston Ship Channel terminals are retrofitting floating roof seals to meet finalized methane emissions regulations.
- Treatment:Agitated vessels and clarifiers require abrasion-resistant linings in continuous-duty municipal wastewater service.
- Transportation:Mobile tank specifications prioritize weight reduction and impact resistance for rail and road logistics.
- Mixing:High-shear environments demand specialized alloy overlays where mechanical wear accelerates liner degradation.
Storage absorbs the bulk of installed capacity; treatment is expanding most quickly.
Distribution Channel:
Channel selection reflects project scale and specification complexity, with large engineered systems bypassing intermediaries entirely.
- Direct Sales:Engineering-procurement-construction firms and major operators source complex tank-and-liner packages directly from manufacturers. Midstream oil and gas operators in the Permian Basin have shifted from component bidding to performance-specification contracting with single-source accountability.
- Distributors:Regional stocking distributors serve maintenance, repair, and operations procurement for standard tank sizes and liner replacement kits.
- Online Sales:Digital channels capture standardized polyethylene tank specifications for agricultural and small commercial applications.
- Retail:Limited to consumer-grade containment products outside industrial scope.
Direct sales absorbs the bulk of installed capacity; distributors is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Texas Gulf Coast industrial corridor anchors North American lined tank demand, with Houston Ship Channel petrochemical complexes driving specification intensity for corrosion-resistant storage systems.
United States
EPA SPCC rule tightening accelerates replacement cycles at Gulf Coast refineries and chemical processing facilities. The agency's expanded integrity testing mandates force operators toward fluoropolymer-lined vessels over traditional rubber alternatives. Houston Ship Channel terminals retrofit floating roof seals to meet finalized methane emissions regulations.
Germany
REACH compliance pressures chemical manufacturers toward extended-service liner specifications that minimize environmental release risks. ECHA substance restrictions on certain rubber accelerators redirect specification authority toward PTFE and ETFE alternatives. BASF's Ludwigshafen complex and Bayer's Leverkusen operations represent concentrated demand nodes for high-performance lined storage.
China
Dual carbon goals and MEE emissions standards compress replacement intervals for aging aboveground storage infrastructure. Ningbo and Shanghai petrochemical zones specify glass-fused-to-steel and epoxy-lined carbon steel tanks for chlorine resistance in wastewater treatment expansions. State-owned refineries consolidate procurement around single-source tank-and-liner packages.
Saudi Arabia
SABIC expansion programs and downstream chemical diversification drive demand for sulfuric acid and hydrochloric acid service vessels. The country's national environmental regulator enforces spill prevention protocols modeled on EPA frameworks. Jubail Industrial City and Yanbu complexes concentrate specification authority for aggressive chemical storage applications.
India
Petrochemical investment corridors in Gujarat and Maharashtra specify corrosion-resistant linings for acid and caustic service. BIS standards for pressure vessel integrity create compliance thresholds that favor established fabricators with certification infrastructure. Reliance's Jamnagar complex and Gujarat State Fertilizers' operations anchor regional demand concentration.
Lined Tank Market Competitive Environment
Premium-margin players sit above commodity-margin players across material specification intensity, with fluoropolymer and stainless steel specialists capturing value pools unavailable to polyethylene rotational molders. The vendor base organizes into three tiers: integrated steel tank fabricators with captive lining capabilities, specialized polymer liner manufacturers supplying third-party shells, and regional job shops serving maintenance-driven replacement cycles. Consolidation pressure concentrates among mid-scale rotational molders facing ASTM D1998 compliance burdens. Dominant competitive moves include backward integration into resin sourcing and geographic expansion through bolted tank field-erection capabilities.
Among North American fabricators, Poly Processing exemplifies vertical control over polyethylene resin sourcing and quality consistency. CST Industries occupies a position in bolted steel tank systems with integrated glass-fused-to-steel lining technology. Pfaudler Group represents specialized alloy and fluoropolymer lining expertise for aggressive chemical service applications.
| Leading Market Players |
|---|
| Poly Processing |
| HMT LLC |
| CST Industries |
| Niles Steel Tank |
| Caldwell Tanks |
| Tank Connection |
| Cleveland Tank |
| Pfaudler Group |
| Snyder Industries |
| Others |
Value Chain & Pricing Dynamics
Fluoropolymer resin feedstock costs cascade through three distinct pricing tiers, with PTFE and ETFE specifications commanding premium positioning against commodity polyethylene alternatives as project engineers at Texas Gulf Coast refineries weigh lifecycle durability against capital constraints.
Pricing Analysis
Service-interval guarantees anchor value-based pricing for fluoropolymer-lined vessels, with Gulf Coast chemical processors paying premiums for 15-year corrosion resistance warranties. Price differentiation hinges on ASTM D1998 certification tier and liner thickness specifications. Cost compression in rubber-lined carbon steel intensifies as commodity competition from Asian fabricators erodes margin pools. Municipal wastewater operators exhibit highest price sensitivity, while pharmaceutical and food-grade buyers prioritize FDA compliance over unit economics.
Supply Chain Analysis
Domestic-content mandates in US infrastructure procurement are redirecting specification authority toward North American rotational molders with captive resin sourcing. Manufacturing gravity centers on the United States, Germany, and China for engineered linings. Raw material flows draw from ethylene crackers along the Texas Gulf Coast, fluorochemical complexes in the US Southeast, and specialty alloy foundries in Germany and Japan. Single-source vulnerability concentrates in certified weld-overlay technicians for alloy-lined pressure vessels. Distribution runs through engineering-procurement-construction firms for large projects and regional distributors for maintenance-driven replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Lined Tank Market functions as a cost-of-compliance arena where EPA SPCC rule tightening constructs formidable barriers to entry for uncertified fabricators, entrenching incumbents with established testing infrastructure and third-party validation relationships.
For Market Incumbents: To counter margin erosion from commodity polyethylene imports, deepen captive control over resin sourcing and expand field-erection capabilities for bolted steel systems in remote mining and power generation installations. Prioritize ASTM D1998 certification maintenance as a competitive moat against smaller regional fabricators facing fixed compliance cost burdens. For New Entrants and Emerging Players: Begin with carbon capture storage applications, where amine-based CO2 capture facilities lack established supplier relationships and specification standards remain fluid. Target remanufacturing services for installed base rehabilitation, capturing aftermarket value from facility operators seeking to defer full tank replacement through in-situ liner recoating offerings. For Investors and Strategic Acquirers: Consolidation announcements among mid-scale rotational molders unable to absorb ASTM D1998 compliance costs is the leading indicator that market structure is shifting toward vertically integrated players with captive lining technology. Long-term viability favors fabricators with dual ASME and 3-A Sanitary Standards qualifications serving both chemical and food-grade end uses.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Sourcing | Poly Processing's captive polyethylene supply secures margin control against ethylene price volatility. |
| Bolted Tank Field-Erection Capability | CST Industries' factory-applied glass-fused-to-steel linings compress site construction timelines for remote installations. |
| Dual Certification Investment | ASME and 3-A Sanitary Standards qualifications unlock food and beverage procurement channels beyond commodity chemical storage. |
| Remanufacturing Service Launch | In-situ liner rehabilitation captures deferred replacement demand from EPA SPCC-mandated integrity testing cycles. |
| Carbon Capture Specification Development | Stainless-clad carbon steel tanks for amine-based CO2 capture open new demand channels ahead of competitor positioning. |
Study Parameters
Independent corroboration across plant managers at Gulf Coast petrochemical complexes, procurement leads at downstream chemical manufacturers, and distribution channel partners underwrites the qualitative findings in this study. Primary interviews with technical R&D directors at rotational molding operations, aftermarket service heads for tank rehabilitation, and EPC contractors specifying tank-and-liner packages combined with secondary validation from EPA SPCC enforcement data, ASTM certification registries, and SEC 10-K disclosures of publicly traded fabricators. Bottom-up demand modeling triangulated against top-down supply-side capacity assessments.
Historical reference periods spanning pre-regulatory tightening through current EPA SPCC enforcement intensity anchored the forecast window across the projection horizon. Segmentation dimensions modeled include liner material grade, end-use industry concentration, application functional requirements, and regional regulatory cluster stringency. CAGRs derived from installed base replacement cycle compression and specification upgrade intensity, with fluoropolymer cost trajectories and certified technician availability serving as industry-specific forecast inputs.
Underlying measurement precision varies by segment; fluoropolymer-lined vessels for aggressive chemical service carry tighter precision than commodity polyethylene water storage. Forecasts reflect documented assumptions regarding EPA enforcement continuity and resin feedstock price stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Basketball Apparel Market
Others
Belt Press Filter Market
Others
Europe Intercom Devices Market
Others
ASEAN Smart Homes Market
Others
US Cat Food Market
Others
Automatic Barriers and Bollards Market
Others
Coriolis Meters Market
Others
Cloud Digital Video Recorder Market
Others
Europe Astrology Market
Others
Sunflower Husk Pellets Market
Others
Global Maritime Freight Transport Market
Others
Commercial Aircraft Angle of Attack Sensors Market
Others
Global Optical Comparator Market
Others
Smart Home Solutions Market
Others
GCC Health and Wellness Market
Others
Global Geotechnical Instrumentation and Monitoring Market