
 Taiwan Retail Market | 2026-2036
Taiwan Retail Market Size, Share, and Industry Trends Forecast 2026-2036
Taiwan Retail Market Insights
The warehouse-format capability gap between mass-market operators is unwinding as digital infrastructure investments reshape competitive thresholds. Costco Taiwan leverages its membership model to sustain bulk-purchase loyalty in suburban zones. momo.com anchors Taiwan's e-commerce channel with same-day fulfillment networks. RT-Mart competes through hypermarket densification across secondary cities.
Taiwan Retail encompasses the sale of finished goods to end consumers through physical and digital channels, spanning product categories from perishables to durable goods with inventory turnover cycles ranging from days for fresh groceries to months for luxury apparel. Its primary commercial purpose is matching manufacturer output with fragmented household and corporate demand through intermediating logistics, payment, and trust infrastructure. Groceries dominates transaction volume but operates on thin margin pools constrained by price-sensitive household budgets. Electronics generates outsized revenue per transaction through premium-tier smartphones and computing equipment. E-commerce is the fastest-growing distribution channel, though convenience stores retain structural importance as pickup nodes and impulse-purchase outlets.
Taiwan's Fair Trade Commission monitors retail pricing transparency and promotional claims, while the Consumer Protection Commission enforces product safety and labeling standards that shape sourcing requirements for cross-border sellers. The Bureau of Standards, Metrology and Inspection administers compulsory commodity inspections that filter non-compliant imports from mainland China and Southeast Asian suppliers. Stakeholders must monitor evolving data privacy obligations under Taiwan's Personal Data Protection Act as loyalty programs and facial-recognition retail analytics deepen consumer surveillance.
Market Dynamics
Taiwan's retail sector faces structural compression from warehouse-format saturation in Greater Taipei, where Costco's membership density and momo.com's same-day fulfillment networks have reset competitive thresholds for suburban and digital channels alike.
Growth Catalysts
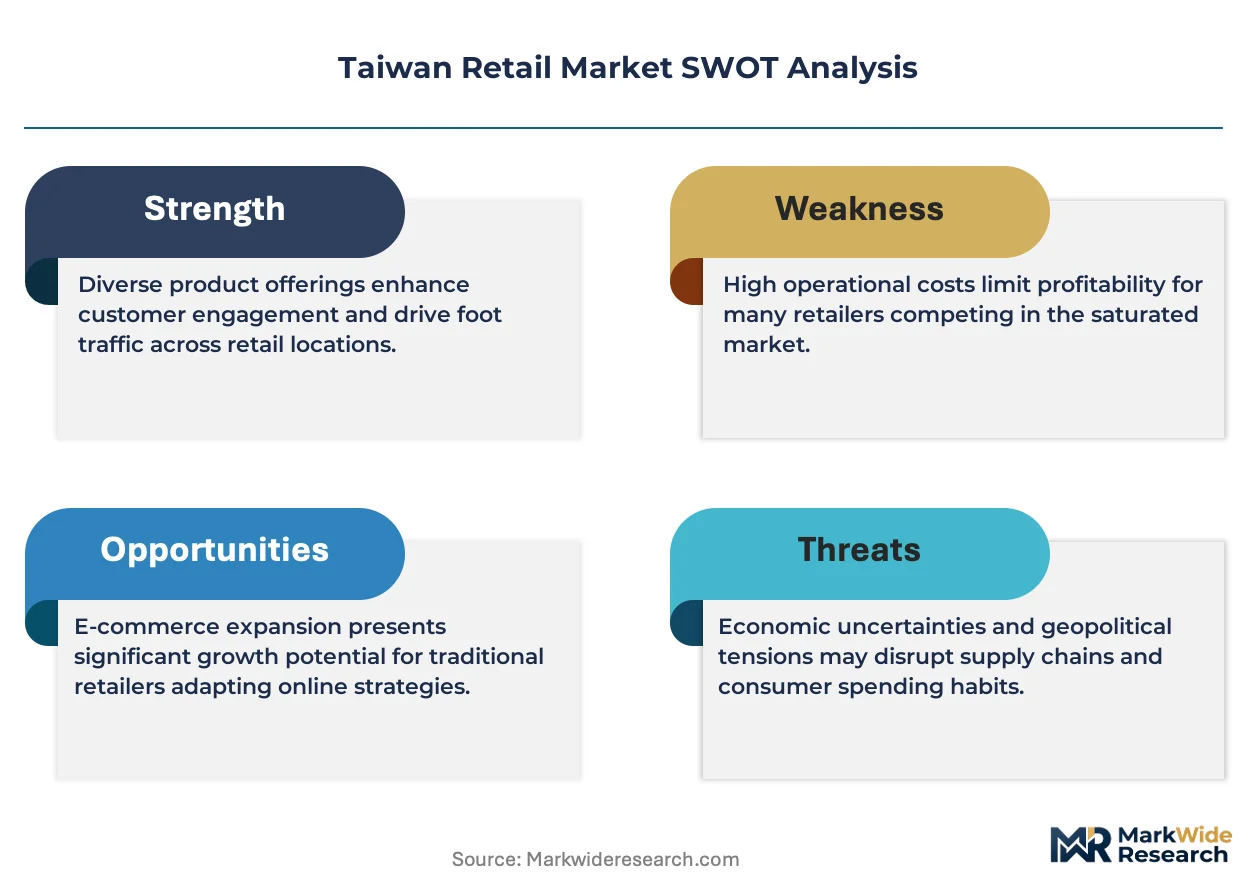
- Personal Data Protection Act enforcement:Stricter consent frameworks for loyalty analytics are forcing retailers to rebuild first-party data architectures, creating technical moats for compliant operators.
- Experiential retail formats:Young professionals in New Taipei and Taoyuan are driving foot traffic to concept stores that blend food service with merchandise discovery.
- Cross-border e-commerce integration:Bureau of Standards, Metrology and Inspection streamlining compulsory commodity inspections for ASEAN-sourced goods is accelerating SKU expansion for digital marketplaces.
Market Restraints
- Fresh produce input volatility:Thin grocery margins leave hypermarket operators exposed to typhoon-season supply disruptions from central Taiwan agricultural zones.
- Mainland China supplier concentration:Compulsory inspection backlogs at Kaohsiung port create inventory risk for electronics retailers dependent on Shenzhen manufacturing clusters.
- Urban real estate cost escalation:Taipei commercial lease rates are compressing convenience store expansion economics in prime districts.
Strategic Opportunities
- Taoyuan Aerotropolis corridor:Underpenetrated warehouse-club density in the airport-adjacent logistics zone offers first-mover positioning for bulk-format operators.
- Consumer Protection Commission labeling mandates:Strict origin-disclosure rules create differentiation space for retailers with transparent, short-chain sourcing.
- Facial-recognition analytics convergence with mobile payment:Biometric-enabled personalized promotions are opening new revenue streams for department stores with legacy loyalty infrastructure.
Industry Challenges
- Legacy ERP integration with real-time inventory systems:Mid-market retailers struggle to synchronize warehouse management platforms with convenience store POS networks.
- Data privacy officer talent scarcity:Personal Data Protection Act compliance requirements have outpaced qualified legal-technical hybrid staffing in the retail sector.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Taiwan Retail Market |
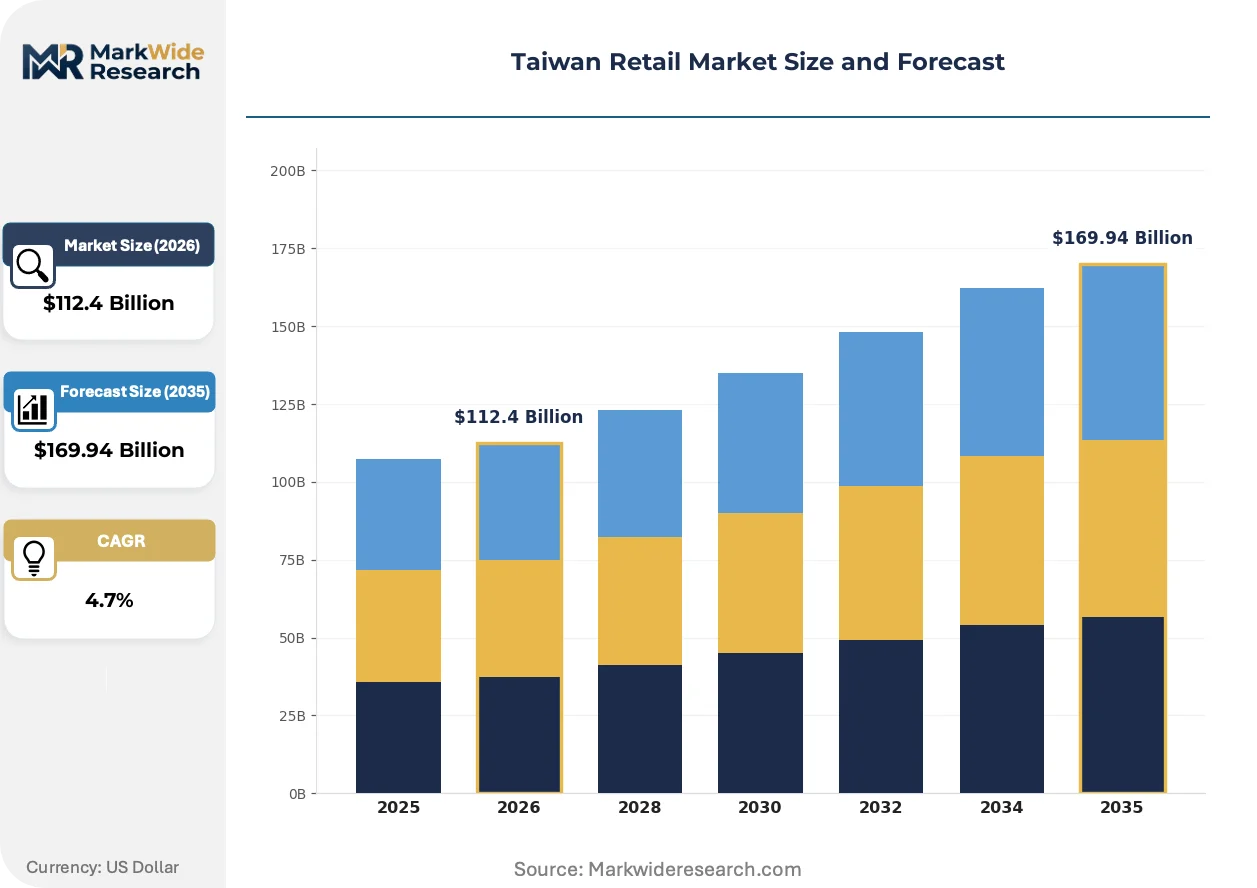
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $169.94 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Apparel, Electronics, Groceries, Home Goods Customer Type: Individuals, Families, Corporates, Students Distribution Channel: E-commerce, Hypermarkets, Convenience Stores, Specialty Shops Price Tier: Budget, Mid-range, Premium, Luxury |
| Companies Covered | Costco Taiwan, RT-Mart, President Chain Store Corp, Far Eastern Group, POYA International Co. Ltd, PX Mart, momo.com, Mercuries & Associates Holding Ltd, Taiwan FamilyMart Co. Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Taiwan Retail Market Trends and Innovations
Retail technology in Taiwan is pivoting from channel-specific optimization toward unified commerce architectures that collapse the distinction between online discovery and physical fulfillment.
Edge computing infrastructure is decomposing the traditional separation between warehouse management and last-mile dispatch systems. RT-Mart and Carrefour Taiwan are deploying localized server nodes in hypermarket basements to process same-day delivery routing without cloud latency. This architecture is compressing fulfillment windows for fresh groceries from four hours to ninety minutes in Greater Taipei.
Taiwan's Consumer Protection Commission has tightened product safety recall protocols for electronics and children's goods sold through cross-border platforms. Retailers must now maintain domestic legal representatives and localized documentation for all direct-to-consumer imports. Digital marketplaces with mainland China supply chains are absorbing the highest compliance costs, redirecting procurement toward South Korean and Japanese certified manufacturers.
Subscription-based replenishment is displacing discretionary impulse purchasing for household staples. momo.com and PChome have built predictive auto-ship algorithms around consumption velocity data from their loyalty programs. Young professional households in New Taipei exhibit the highest adoption rates, with pantry categories showing the strongest migration from cart-based to scheduled delivery models.
Taiwan Retail Market Segmentation
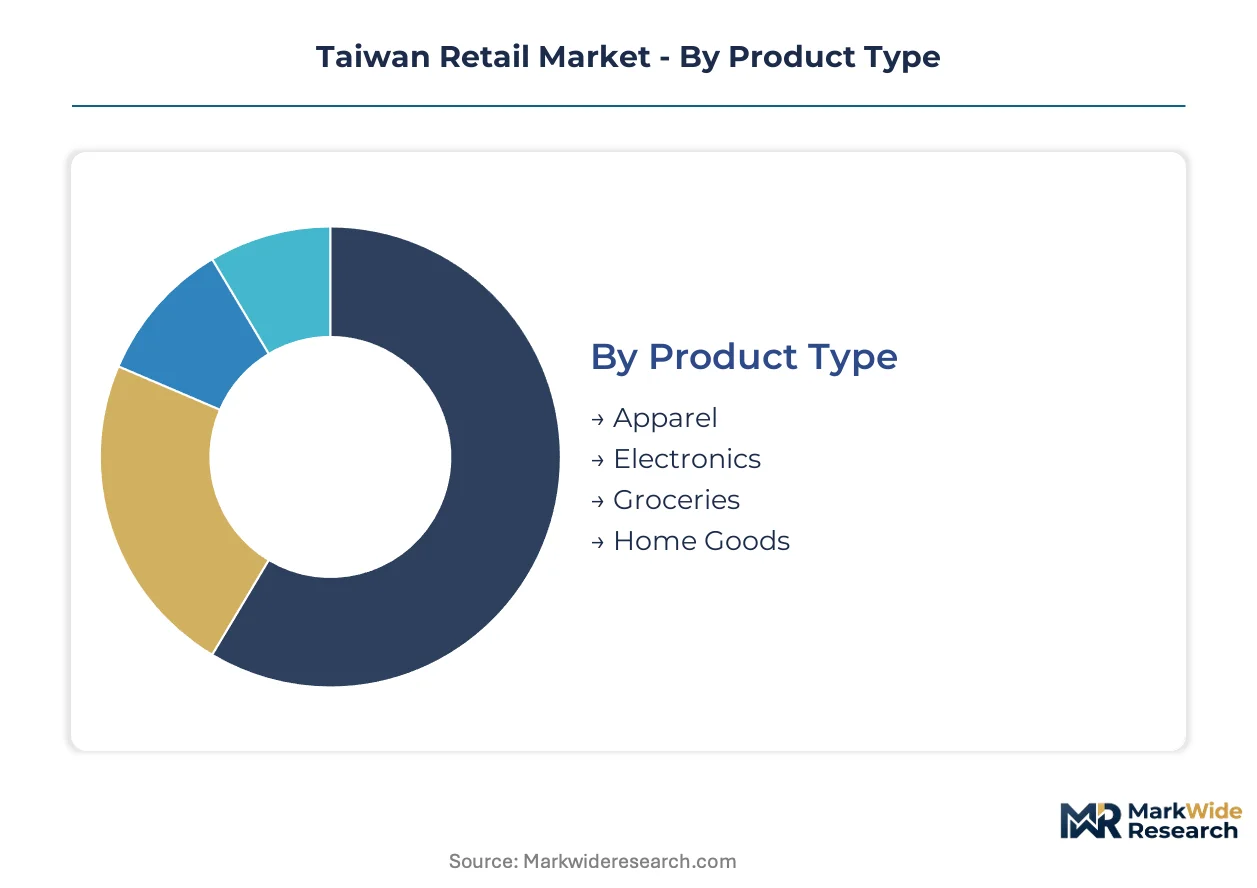
Taiwan's retail segmentation reflects concentrated demand corridors in Greater Taipei against dispersed consumption across secondary cities. Channel and price tier fragmentation creates distinct competitive arenas where warehouse clubs, e-commerce platforms, and convenience networks pursue non-overlapping household segments.
Product Type:
Domestic consumption anchors groceries and home goods, while electronics sourcing integrates deeply with cross-border manufacturing clusters in Shenzhen and Kaohsiung port logistics.
- Apparel:Seasonal fast-fashion cycles dominate mass-market turnover, with domestic brands leveraging short lead times from central Taiwan textile zones. Young professionals in New Taipei drive demand for experiential concept stores blending merchandise with food service.
- Electronics:Premium-tier smartphones and computing equipment generate outsized revenue per transaction. Bureau of Standards, Metrology and Inspection compulsory inspections filter non-compliant imports, creating compliance moats for certified South Korean and Japanese suppliers.
- Groceries:Thin margin pools constrain hypermarket operators exposed to typhoon-season supply disruptions from central Taiwan agricultural zones.
- Home Goods:Furniture and household durables exhibit extended inventory cycles, with demand concentrating in suburban zones surrounding Taoyuan Aerotropolis corridor development.
Groceries commands the established base. The steepest expansion runs through Electronics.
Customer Type:
Volume concentration separates household segments with predictable replenishment patterns from corporate procurement with contract-negotiated terms.
- Individuals:Single-person households in Taipei metropolitan core drive convenience store impulse purchasing and meal-kit subscription adoption. Personal Data Protection Act consent frameworks reshape loyalty analytics targeting this privacy-sensitive cohort.
- Families:Multi-generational households in New Taipei and Taoyuan anchor warehouse club membership density. Costco Taiwan's bulk-purchase model captures pantry stocking and seasonal durable purchases through suburban big-box locations.
- Corporates:B2B procurement of office supplies and refreshment services runs through specialized distributors with negotiated rebate structures.
- Students:University corridor demand in Taipei and Taichung concentrates on electronics, convenience food, and fast-fashion with extreme price sensitivity.
Families command the established base. Individuals are gaining share fastest through subscription migration.
Distribution Channel:
Fulfillment speed separates digital-native platforms from physical networks, with hybrid models emerging at convenience store pickup nodes.
- E-commerce:Same-day fulfillment networks in Greater Taipei compress delivery windows through localized edge computing nodes. momo.com's predictive auto-ship algorithms convert pantry categories from cart-based to scheduled delivery.
- Hypermarkets:RT-Mart and Carrefour Taiwan deploy basement server infrastructure to process ninety-minute fresh grocery routing. Densification across secondary cities targets underpenetrated Taichung and Kaohsiung corridors.
- Convenience Stores:7-Eleven and FamilyMart retain structural importance as pickup nodes for e-commerce orders and impulse-purchase outlets in prime Taipei districts facing lease rate escalation.
- Specialty Shops:Electronics and luxury apparel boutiques concentrate in Taipei Xinyi and Zhongxiao commercial zones with biometric-enabled personalized promotions.
Hypermarkets command the established base. E-commerce shows the steepest upward trajectory.
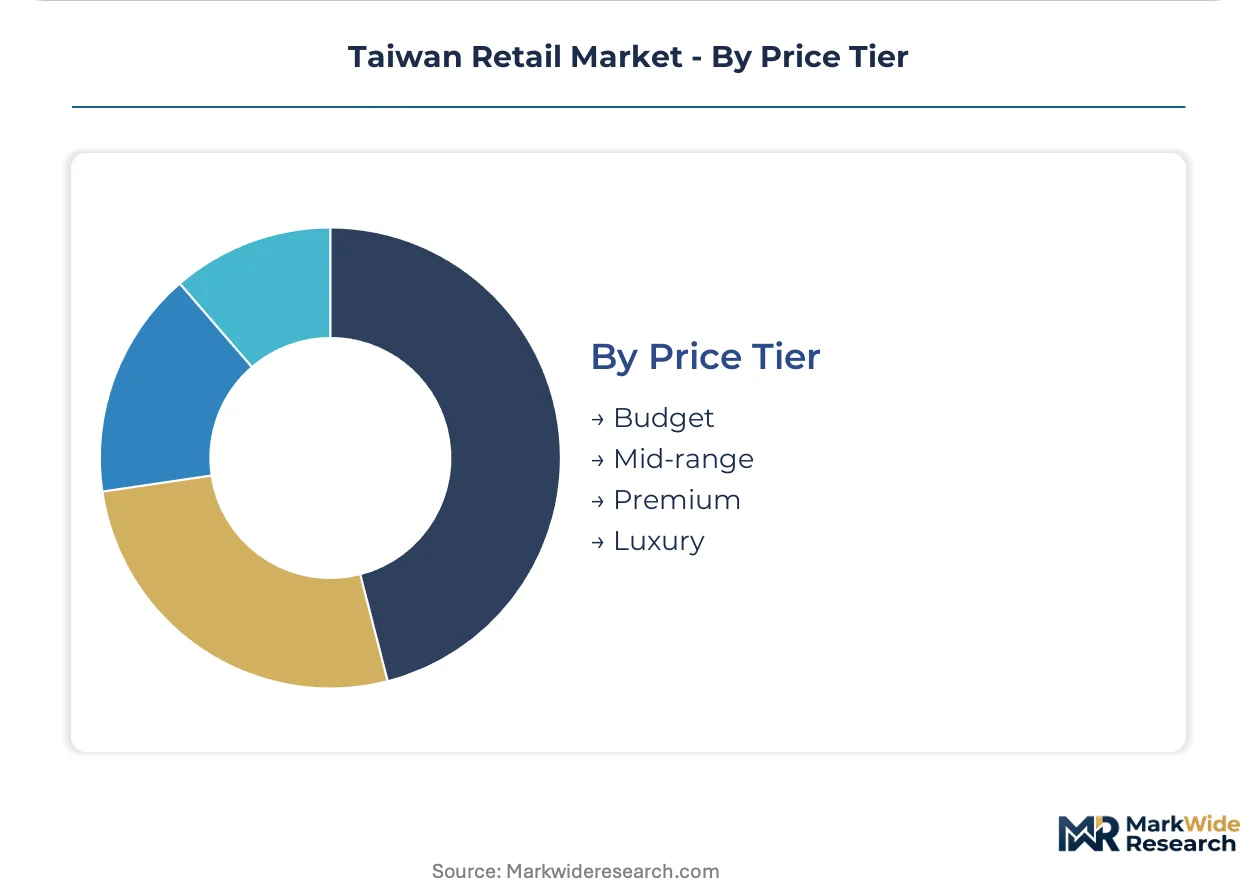
Price Tier:
Margin structure stratifies across certification grade and sourcing transparency rather than pure performance differentiation.
- Budget:Price-sensitive household staples and private-label groceries dominate, with procurement shifting toward ASEAN-sourced goods under streamlined Bureau of Standards inspection protocols.
- Mid-range:Mass-market electronics and fast-fashion serve the broad Taiwanese middle class with three-tier pricing separating domestic from certified import supply.
- Premium:Short-chain sourcing with origin-disclosure compliance creates differentiation space under Consumer Protection Commission labeling mandates. Korean and Japanese certified manufacturers capture this tier.
- Luxury:Department stores with legacy loyalty infrastructure deploy facial-recognition analytics for personalized promotions targeting high-net-worth households in Taipei core districts.
Mid-range commands the established base. Premium tier climbs the fastest on transparency-driven sourcing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across Taiwan diverge sharply between the dense Greater Taipei corridor and the island's secondary cities. Young professionals cluster in New Taipei and Taoyuan, driving experiential retail adoption, while central and southern regions maintain traditional hypermarket loyalty with stronger price sensitivity.
Greater Taipei Metropolitan Corridor
Young professionals in Taipei, New Taipei, and Taoyuan propel demand for concept stores blending food service with merchandise discovery. The Consumer Protection Commission enforces strict origin-disclosure labeling that shapes sourcing for cross-border e-commerce platforms. Xinyi and Zhongxiao commercial districts concentrate luxury department stores deploying facial-recognition analytics for personalized promotions.
Taoyuan Aerotropolis Corridor
Underpenetrated warehouse-club density in this airport-adjacent logistics zone offers first-mover positioning for bulk-format operators targeting multi-generational families. Bureau of Standards, Metrology and Inspection streamlines compulsory commodity inspections for ASEAN-sourced goods, accelerating SKU expansion. The zone's industrial parks attract distribution centers serving northern Taiwan's subscription-based replenishment growth.
Central Taiwan Agricultural Belt
Fresh produce supply from Nantou and Taichung agricultural zones anchors grocery retail but exposes hypermarket operators to typhoon-season volatility. Thin margin pools constrain pricing flexibility when weather disruptions compress supply windows. Taichung city serves as the logistics hub connecting central farming regions to Greater Taipei distribution networks.
Southern Taiwan Manufacturing Zone
Kaohsiung port handles electronics imports from Shenzhen manufacturing clusters, where compulsory inspection backlogs create inventory risk for retailers. The city's commercial districts maintain stronger convenience store density per capita than northern counterparts. Electronics retailers here source heavily through South Korean and Japanese certified manufacturers to bypass mainland China compliance costs.
Eastern Taiwan Coastal Region
Hualien and Taitung counties exhibit lower retail format diversity, with convenience stores and traditional markets dominating household purchasing. Tourism-driven seasonal demand spikes challenge inventory planning for fresh groceries and specialty foods. The region's limited warehousing infrastructure extends fulfillment windows for e-commerce platforms serving dispersed rural populations.
Taiwan Retail Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with membership-based warehouse clubs and same-day e-commerce platforms resetting competitive thresholds. The market structure compresses around two dominant vectors: suburban bulk-format density and urban digital fulfillment speed. Three archetypes prevail—membership-driven warehouse operators, predictive auto-ship platforms, and convenience store networks serving as hybrid pickup nodes. Competitive moves concentrate on edge computing infrastructure deployment and hypermarket densification across underpenetrated corridors.
Within the membership-driven tier, Costco Taiwan exemplifies bulk-purchase loyalty architecture through suburban big-box positioning. Among digital-native platforms, momo.com occupies the predictive replenishment vector with same-day fulfillment networks. RT-Mart represents hypermarket densification strategy, deploying localized server infrastructure to compress fresh grocery delivery windows. These three anchors illustrate how infrastructure investment, rather than format alone, now separates market tiers.
| Leading Market Players |
|---|
| Costco Taiwan |
| RT-Mart |
| President Chain Store Corp |
| Far Eastern Group |
| POYA International Co. Ltd |
| PX Mart |
| momo.com |
| Mercuries & Associates Holding Ltd |
| Taiwan FamilyMart Co. Ltd |
| Others |
Pricing and Supply Chain Analysis
Costco Taiwan's membership density in suburban zones establishes scale thresholds that compress price floors for bulk-format competitors while anchoring supply contracts through predictable volume commitments. This concentration of purchasing power simultaneously shapes supplier negotiation leverage and consumer price expectations across Greater Taipei's warehouse-club corridor.
Pricing Analysis
Membership renewal fees and ancillary services drive lifetime value beyond transactional merchandise margins. Three-tier pricing structure across premium, standard, and economy levels segments households by purchase frequency and basket size. Pricing pressure stems from momo.com's predictive auto-ship algorithms converting pantry categories to scheduled delivery with lower per-unit margins. Students and single-person households in Taipei core districts exhibit extreme price sensitivity, while multi-generational families in Taoyuan show lower elasticity for certified imports.
Supply Chain Analysis
Kaohsiung port congestion on the Shenzhen-Taiwan trade lane elevates inbound logistics costs for electronics retailers dependent on mainland China manufacturing clusters. Procurement draws from China, South Korea, and Japan for consumer electronics, with ASEAN sources expanding for budget-tier household goods. Compulsory inspection backlogs at Bureau of Standards, Metrology and Inspection checkpoints create single-source vulnerability for Shenzhen-dependent inventory. Distribution runs through hypermarket basement edge-computing nodes and convenience store pickup networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Talent scarcity for Personal Data Protection Act compliance officers constrains mid-market retailers from deploying facial-recognition analytics at scale, creating asymmetric capability gaps between legacy department stores and digital-native platforms.
For Market Incumbents: Shield warehouse-club membership density through suburban real estate preemption in Taoyuan Aerotropolis corridor before competitors achieve minimum viable scale. Invest in first-party data architecture rebuilds to capture technical moats from stricter consent frameworks. Vertical integration into edge-computing infrastructure at hypermarket basements compresses fulfillment windows against momo.com's same-day networks. For New Entrants and Emerging Players: Differentiate on transparent short-chain sourcing with Consumer Protection Commission-compliant origin disclosure to capture premium-tier households. Target underpenetrated warehouse-club density in Taoyuan Aerotropolis logistics zone where bulk-format operators lack presence. Build go-to-market around subscription-based replenishment algorithms for young professional households in New Taipei exhibiting highest adoption velocity. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors operators with deployed edge-computing infrastructure and compliant first-party data architectures over legacy ERP-dependent mid-market retailers. Long-term viability hinges on unified commerce capability separating online discovery from physical fulfillment. Acquisition targets should demonstrate localized server node deployment and Personal Data Protection Act-compliant loyalty analytics. Watch Bureau of Standards inspection protocol streamlining for ASEAN goods as inflection signal for SKU expansion economics.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Computing Infrastructure Deployment | Localized server nodes in hypermarket basements compress fresh grocery fulfillment from four hours to ninety minutes. |
| First-Party Data Architecture Rebuild | Stricter Personal Data Protection Act consent frameworks create technical moats for compliant loyalty analytics operators. |
| Suburban Warehouse-Club Densification | Taoyuan Aerotropolis corridor offers first-mover positioning for bulk-format operators targeting multi-generational families. |
| Cross-Border E-Commerce Integration | Bureau of Standards streamlining of ASEAN-sourced goods inspections accelerates SKU expansion for digital marketplaces. |
| Subscription-Based Replenishment Buildout | Predictive auto-ship algorithms convert pantry categories from cart-based to scheduled delivery for New Taipei professionals. |
Research Methodology
Cross-validation between executive interviews at warehouse-club and e-commerce operators and secondary trade data anchors the qualitative findings. Primary fieldwork engaged retail operations directors, logistics planners at hypermarket chains, convenience store franchise managers, and Consumer Protection Commission regulatory officers. Secondary sources included Bureau of Standards inspection disclosure records, Fair Trade Commission pricing transparency filings, customs import manifests at Kaohsiung port, and commercial lease rate indices from Taipei brokerage networks. Bottom-up channel volume estimates and top-down household expenditure surveys were reconciled through iterative triangulation.
Sensitivity analysis around typhoon-season agricultural supply disruption scenarios and inspection backlog duration assumptions tested forecast robustness across the projection horizon. Segmentation dimensions modeled include product category, household structure, distribution channel, and price tier alongside geographic corridor density. CAGRs were derived from trend extrapolation of channel-shift velocities and infrastructure deployment timelines. Key inputs incorporated edge-computing node deployment schedules and membership renewal rate trajectories at warehouse-club operators.
Material uncertainties — typhoon frequency intensification, mainland China trade policy shifts, Personal Data Protection Act enforcement escalation — sit outside the modeled envelope. Forecasts reflect documented assumptions about infrastructure investment continuity and regulatory inspection capacity expansion. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Super Computer Market
Others
APAC Machine Vision Systems Market
Others
Digital Transformation of Maritime Freight Market
Others
North America Micro Market
Others
Smart Electric Curtain Market
Others
Middle East & Africa Air Insulated Switchgear Market
Others
Thermal Energy Flow Metering Solutions Market
Others
Africa Cotton Market
Others
Global Optical Comparator Market
Others
Medium-Voltage Switchgear Market
Others
Inorganic Tin Chemicals Market
Others
Fresh Pears Market
Others
Gas Radiators Market
Others
Global Compact Wheel Loaders Market
Others
Pet Care Packaging Market
Others
Banknote Printing Machine Market