
 Molybdenum-99 Market | 2026-2036
Molybdenum-99 Market Size, Share, and Industry Trends Forecast 2026-2036
Molybdenum-99 Market Foresight
Hospital procurement of molybdenum-99 is rotating toward diagnostic center networks and specialized imaging facilities as outpatient cardiac and cancer screening volumes climb. IRE leverages its BR-2 reactor capacity in Belgium to anchor European supply reliability. NTP Radioisotopes competes through Safari-1 reactor output in South Africa, while Nordion sustains North American channel control via longstanding distribution partnerships with technetium-99m generator manufacturers.
Molybdenum-99 is a synthetic radioisotope produced primarily through neutron irradiation of highly enriched uranium or low-enriched uranium targets in research reactors, decaying with a 66-hour half-life to yield technetium-99m for single-photon emission computed tomography imaging. Its primary commercial purpose centers on supplying the diagnostic backbone for oncology staging, myocardial perfusion studies, and bone scans that depend on same-day radiopharmaceutical availability. Nuclear reactor technology dominates current production architecture, though cyclotron-based methods are gaining investment traction as non-HEU alternatives mature. Among end users, hospitals retain the largest installed base of gamma cameras, yet imaging facilities capture faster volume growth as decentralized diagnostics expand.
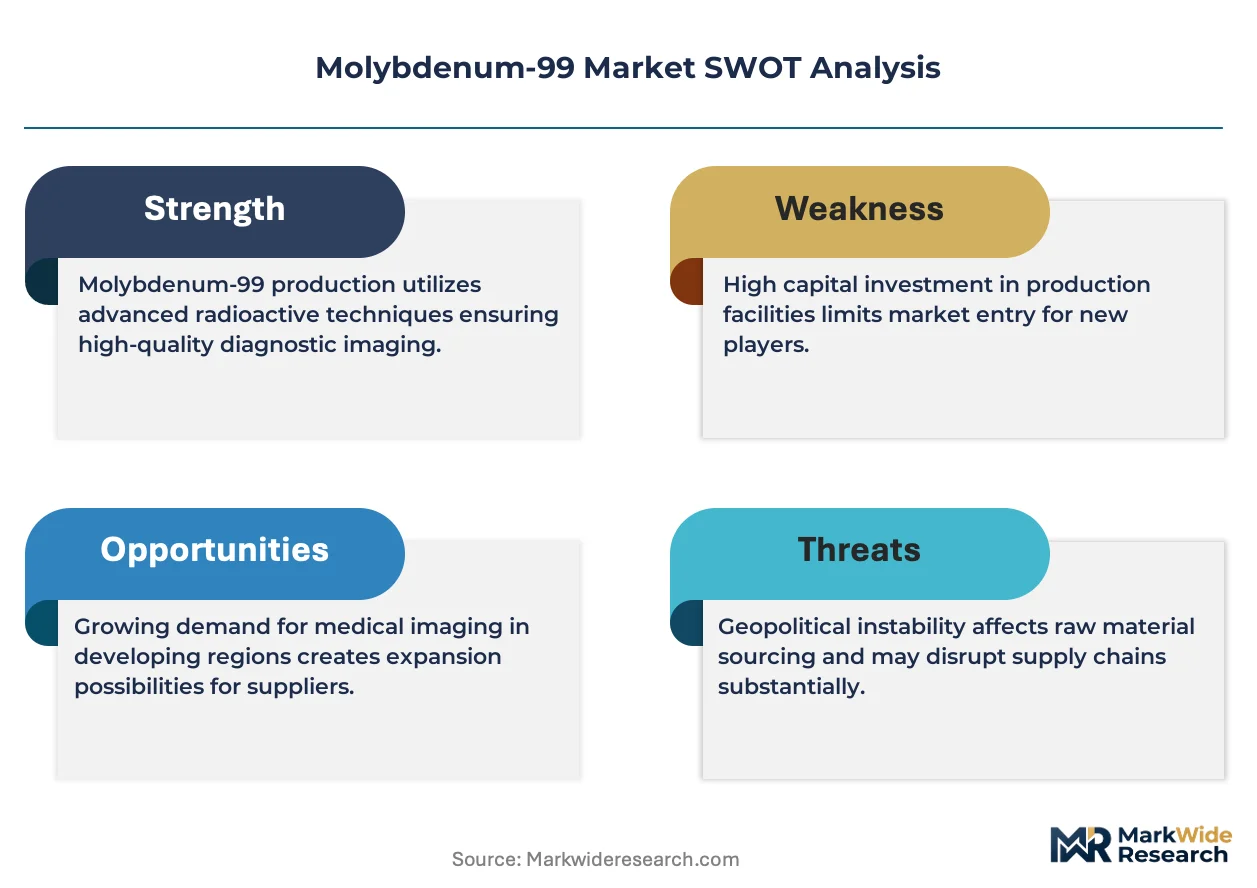
The FDA enforces current good manufacturing practice standards for technetium-99m generators under 21 CFR Part 212, while the NRC governs reactor licensing and radioactive materials transport. The IAEA coordinates international efforts to minimize and eliminate HEU use in civilian applications, pressuring producers toward LEU conversion. Stakeholders must monitor reactor aging schedules, LEU target qualification timelines, and regional generator stockpiling behavior to anticipate supply discontinuities.
Market Dynamics
Reactor aging schedules and LEU conversion timelines are compressing supply elasticity while diagnostic imaging networks expand their Mo-99 consumption footprints. This structural tension between constrained production architecture and rising clinical demand defines current market mechanics.
Growth Catalysts
- Technetium-99m generator qualification:FDA orphan drug guidance tightens purity benchmarks, forcing quality upgrades that lock in premium supply relationships with certified producers.
- Cardiac imaging protocols:Myocardial perfusion studies at outpatient diagnostic centers now account for the dominant share of same-day radiopharmaceutical procedures.
- BR-2 reactor reliability:Belgian production capacity anchors European supply continuity against competing reactor maintenance windows.
Market Restraints
- HEU phase-out costs:IAEA minimization mandates require target requalification investments that strain producer balance sheets during LEU conversion.
- Reactor concentration risk:Safari-1, BR-2, and OPAL collectively control the majority of non-HEU output, creating single-point vulnerability.
- Cyclotron substitution limits:Accelerator-based technetium-99m production remains clinically unproven at commercial scale.
Strategic Opportunities
- Australian export expansion:OPAL reactor output under ANSTO licensing can displace aging European supply into Southeast Asian diagnostic networks.
- Decentralized generator deployment:Point-of-care technetium-99m synthesis at major cancer centers reduces logistics cold-chain dependency.
- 21 CFR Part 212 compliance services:cGMP consulting for generator manufacturers creates recurring revenue adjacent to core isotope sales.
Industry Challenges
- Radiochemical processing expertise:Target dissolution and molybdenum separation skills concentrate among retiring reactor operators.
- Transport cask certification:NRC Type B package approvals for high-activity Mo-99 shipments face 18-24 month backlog.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Molybdenum-99 Market |
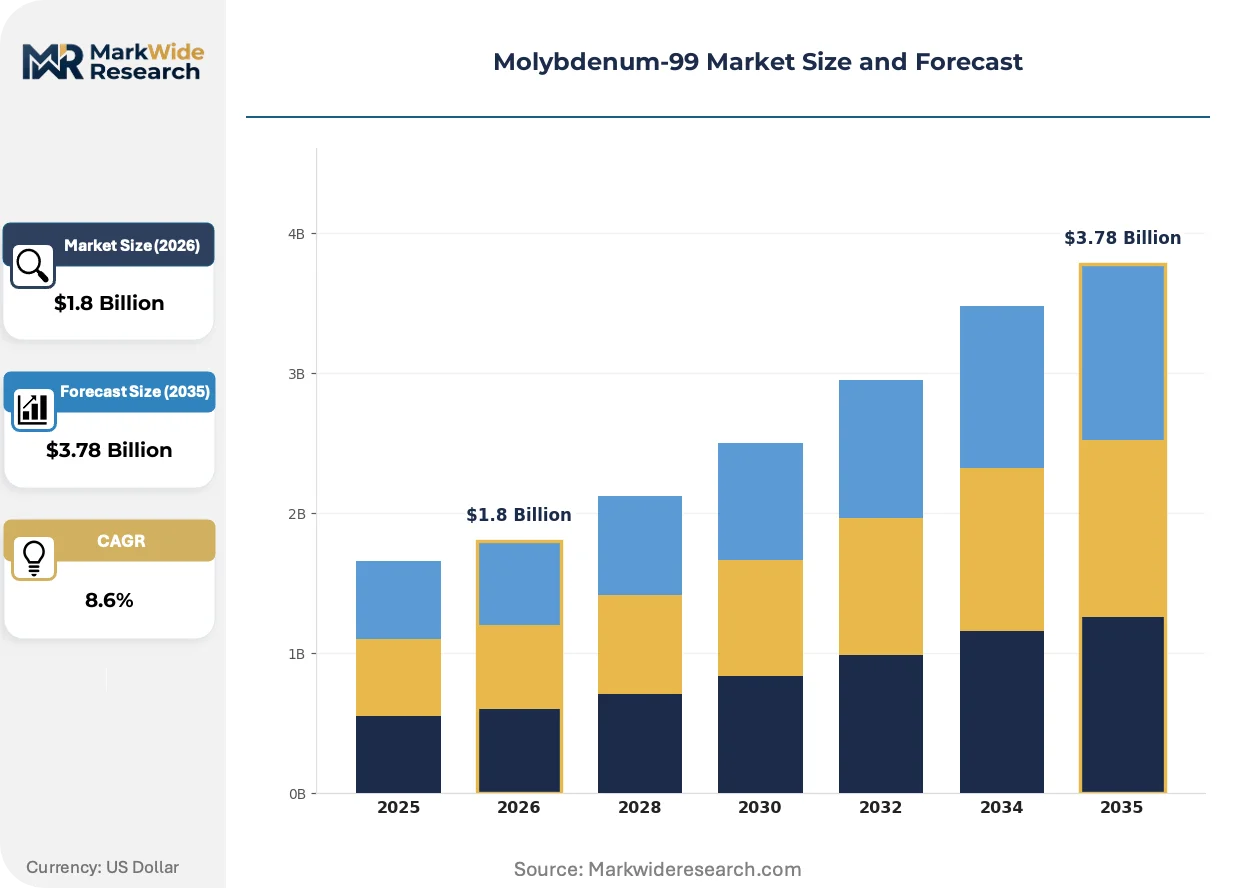
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.78 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Westinghouse, GE Healthcare, R&D Systems, Mallinckrodt End User: Hospitals, Diagnostic Centers, Research Institutions, Imaging Facilities Application: Oncology, Cardiology, Neurology, Infectious Diseases Technology: Nuclear Reactor, Cyclotron, Radioisotope Generator, Radiopharmaceuticals |
| Companies Covered | IRE, NTP Radioisotopes, Nordion, Rosatom, NRG, Mallinckrodt Pharmaceuticals, ANSTO, Curium Pharma, Lantheus Medical Imaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Molybdenum-99 Market Shifts & Advancements
Electron accelerator methods and regulatory harmonization efforts are actively restructuring how technetium-99m reaches diagnostic facilities. These shifts promise to reduce reactor dependency while raising quality thresholds.
Cyclotron-based technetium-99m production through proton irradiation of enriched molybdenum-100 targets is decomposing the historical reactor monopoly. Canadian and Australian research hospitals now pilot these systems for regional self-sufficiency. This distributed model compresses generator logistics costs and insulates clinical operations from reactor outage risk.
EMA's revised radiopharmaceutical guidelines now align impurity specifications with FDA orphan drug frameworks. Generator manufacturers face synchronized compliance burdens across Atlantic markets. European diagnostic networks respond by consolidating procurement through qualified suppliers with dual-continent certification.
Hospital buying groups now negotiate multi-year technetium-99m generator contracts with price collars tied to reactor availability indices. Imaging facility chains displace traditional hospital radiopharmacy departments as volume aggregators. This concentration is most visible in US cardiac imaging corridors where specialized operators capture outpatient migration from general hospitals.
Molybdenum-99 Market Segmentation
Molybdenum-99 market segmentation reveals distinct margin architectures across production methods and clinical applications. Each dimension carries implications for supply security, regulatory burden, and pricing power that shape procurement decisions at diagnostic networks worldwide.
Product Type:
Margin concentration flows toward suppliers with vertically integrated reactor-to-generator capabilities and established FDA 21 CFR Part 212 certifications.
- Westinghouse:Leverages LEU target conversion expertise and BR-2 reactor partnerships to supply technetium-99m generators with certified cold-chain logistics. North American hospital networks favor Westinghouse for multi-year contracts tied to reactor availability indices.
- GE Healthcare:Controls distribution channels through integrated radiopharmacy networks and same-day delivery infrastructure. GE's generator qualification speed under FDA orphan drug guidance locks in premium pricing at cardiac imaging corridors.
- R&D Systems:Focuses on research-grade molybdenum-99 for preclinical imaging and radiochemistry method development.
- Mallinckrodt:Serves mid-tier diagnostic centers with standardized generator formats and simplified regulatory documentation.
The dominant share belongs to GE Healthcare, while Westinghouse is closing the gap fastest through LEU conversion leadership.
End User:
Volume distribution tracks the migration of nuclear medicine procedures from inpatient to outpatient settings.
- Hospitals:Retain the largest installed base of gamma cameras and SPECT systems. Academic medical centers in the US and Belgium anchor demand for complex oncology staging protocols requiring same-day technetium-99m availability.
- Diagnostic Centers:Capture the steepest expansion trajectory as decentralized cardiac and cancer screening volumes climb. Outpatient myocardial perfusion studies now dominate same-day radiopharmaceutical consumption in US metropolitan corridors.
- Research Institutions:Drive demand for high-specific-activity molybdenum-99 in radiochemistry innovation and novel imaging tracer development.
- Imaging Facilities:Aggregate procurement through specialized operators that displace traditional hospital radiopharmacy departments in volume negotiations.
Hospitals still command the largest revenue pool, though diagnostic centers are expanding most quickly through outpatient procedure migration.
Application:
Clinical utility concentrates where technetium-99m's 6-hour half-life enables same-day diagnostic workflows.
- Oncology:Bone metastasis detection and sentinel lymph node mapping depend on reliable technetium-99m generator supply. Cancer center networks in the Netherlands and Australia prioritize qualified suppliers with dual-continent EMA and TGA certification.
- Cardiology:Myocardial perfusion imaging represents the highest-volume single application. US cardiac imaging corridors drive demand concentration as specialized operators consolidate procurement.
- Neurology:Cerebral blood flow studies and dementia screening protocols require precise radiopharmaceutical timing.
- Infectious Diseases:White blood cell labeling for osteomyelitis and soft-tissue infection localization serves niche but stable demand.
Oncology holds the dominant share, while cardiology is gaining ground fastest through outpatient screening expansion.
Technology:
Production architecture determines supply security, regulatory exposure, and capital intensity for market participants.
- Nuclear Reactor:BR-2 in Belgium, Safari-1 in South Africa, and OPAL in Australia control the majority of non-HEU molybdenum-99 output. Reactor aging schedules and LEU conversion timelines compress supply elasticity while diagnostic networks expand consumption footprints.
- Cyclotron:Proton irradiation of enriched molybdenum-100 targets is decomposing the historical reactor monopoly. Canadian and Australian research hospitals pilot these systems for regional self-sufficiency and logistics cost compression.
- Radioisotope Generator:Technetium-99m generator qualification under FDA 21 CFR Part 212 and EMA radiopharmaceutical guidelines creates synchronized compliance burdens across Atlantic markets.
- Radiopharmaceuticals:Cold-kit formulation and compounding services add value adjacent to core isotope production.
Nuclear reactor technology retains the dominant share, while cyclotron methods are climbing the fastest as non-HEU alternatives mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Antwerp-Bruges cold-chain infrastructure underwrites Belgium's role in European Mo-99 distribution, while the OPAL reactor at Lucas Heights anchors Australian export capacity into Southeast Asian diagnostic networks.
United States
Outpatient cardiac imaging corridors in Cleveland and Houston drive generator procurement concentration. The FDA enforces 21 CFR Part 212 cGMP standards for technetium-99m generator qualification, tightening purity benchmarks that favor certified suppliers. Mallinckrodt's St. Louis operations and Lantheus Medical Imaging in North Billerica anchor domestic distribution partnerships with major hospital networks.
Belgium
Academic medical centers in Leuven and Brussels anchor demand for complex oncology staging protocols requiring same-day radiopharmaceutical availability. The Belgian Federal Agency for Medicines and Health Products aligns with EMA radiopharmaceutical guidelines on impurity specifications. IRE leverages BR-2 reactor capacity at Mol to supply European diagnostic networks against competing reactor maintenance windows.
South Africa
Gauteng province diagnostic centers capture outpatient migration from Johannesburg academic hospitals. The National Nuclear Regulator governs Safari-1 reactor licensing and radioactive materials transport under IAEA safeguards protocols. NTP Radioisotopes at Pelindaba anchors African supply reliability while serving export markets during European reactor outages.
Australia
Sydney and Melbourne cancer center networks prioritize qualified suppliers with TGA certification for bone metastasis detection protocols. The Australian Radiation Protection and Nuclear Safety Agency coordinates OPAL reactor licensing under IAEA minimization mandates for HEU phase-out. ANSTO at Lucas Heights expands generator export capacity into Singapore, Malaysia, and Thai diagnostic facilities.
Netherlands
Rotterdam and Amsterdam imaging facility chains consolidate procurement through specialized operators displacing traditional hospital radiopharmacy departments. The Healthcare and Youth Inspectorate enforces EMA-aligned radiopharmaceutical quality standards. NRG at Petten maintains research reactor output for European Mo-99 supply diversification alongside Belgian production clusters.
Molybdenum-99 Market Competitive Landscape
Listed leaders compete with private specialists across reactor capacity and generator qualification capabilities. The vendor base clusters around three reactor operators controlling non-HEU output, two radiopharmaceutical generators with integrated distribution networks, and several regional distributors serving mid-tier diagnostic centers. Three archetypes dominate: vertically integrated reactor-to-generator operators, pure-play generator manufacturers with cold-chain logistics, and research-institute-backed production facilities. Competitive moves concentrate on LEU conversion partnerships and multi-year procurement contracts tied to reactor availability indices.
Within the reactor-operator tier, IRE and NTP Radioisotopes exemplify vertically integrated production architecture, while Nordion occupies a position as a North American distribution anchor. Mallinckrodt Pharmaceuticals represents the standardized generator format archetype serving mid-tier diagnostic centers with simplified regulatory documentation. These named entities illustrate how geographic reactor concentration and regulatory certification stratify competitive positioning across Atlantic and Asia-Pacific markets.
| Leading Market Players |
|---|
| IRE |
| NTP Radioisotopes |
| Nordion |
| Rosatom |
| NRG |
| Mallinckrodt Pharmaceuticals |
| ANSTO |
| Curium Pharma |
| Lantheus Medical Imaging |
| Others |
Supply & Pricing Matrix
Multi-year offtake contracts tied to reactor availability indices lock in supply access for US cardiac imaging corridors while capping price volatility for Belgian and Australian producers serving European and Asia-Pacific diagnostic networks. These structures embed LEU conversion cost pass-through clauses and generator qualification premiums that stratify buyer tiers.
Pricing Analysis
Volume-discount tiering separates academic medical centers procuring multi-generator annual contracts from mid-tier diagnostic centers purchasing quarterly lots. Pricing stratifies across premium, standard, and economy tiers based on FDA 21 CFR Part 212 certification grade and cold-chain reliability guarantees. Cost compression in the economy tier is intensifying as LEU target requalification expenses flow downstream. Academic medical centers anchored in Cleveland and Houston exhibit lowest price sensitivity due to same-day radiopharmaceutical workflow dependencies.
Supply Chain Analysis
Strategic stockpile preferences dominate Belgian and Australian producer behavior given reactor maintenance windows, while US diagnostic centers run just-in-time generator inventories compressed to technetium-99m's 6-hour half-life. Supply concentrates in Belgium, South Africa, and Australia as IAEA HEU minimization mandates reshape production geography. Raw material dependencies rest on highly enriched uranium and low-enriched uranium target supplies, neutron flux reactor capacity, and technetium-99m generator column substrates. Single-source vulnerability permeates the reactor-operator tier where BR-2, Safari-1, and OPAL control non-HEU output. Distribution runs through cold-chain logistics partnerships anchored at the Port of Antwerp-Bruges and Lucas Heights export facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Outpatient cardiac and cancer screening migration positions the market at early-cycle expansion, with decentralized diagnostic facility growth outpacing traditional hospital radiopharmacy capacity.
For Market Incumbents: Consolidate reactor-to-generator vertical control through LEU conversion partnerships at BR-2 and OPAL to defend against cyclotron substitution threats. Lock in multi-year procurement contracts with price collars before accelerator-based methods achieve clinical scale. Prioritize FDA 21 CFR Part 212 certification maintenance as orphan drug guidance tightens purity benchmarks. For New Entrants and Emerging Players: Differentiate on regional self-sufficiency by deploying cyclotron-based technetium-99m production at Canadian and Australian research hospitals. Target Southeast Asian diagnostic networks in Singapore, Malaysia, and Thailand where OPAL export expansion creates supply gaps. Pursue TGA and EMA dual-certification pathways to qualify for cancer center network procurement. For Investors and Strategic Acquirers: The market sits at an infrastructure-constrained phase that favors reactor-operator archetypes with LEU conversion completion and established cold-chain distribution. Long-term viability hinges on HEU phase-out execution and accelerator technology maturation. Acquisition targets should demonstrate captive BR-2, Safari-1, or OPAL offtake agreements. The signal to watch is cyclotron clinical trial readouts achieving commercial-scale technetium-99m purity thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| LEU Target Conversion Partnership | IRE and ANSTO partnerships secure non-HEU supply continuity under IAEA minimization mandates. |
| FDA 21 CFR Part 212 Certification Investment | Generator qualification speed locks in premium pricing at US cardiac imaging corridors. |
| Cyclotron Clinical Scale-Up | Canadian and Australian hospital pilots test regional self-sufficiency against reactor outage risk. |
| Southeast Asian Export Expansion | OPAL output displaces aging European supply into Singapore and Malaysian diagnostic networks. |
| Multi-Year Procurement Contract Negotiation | Price collars tied to reactor availability indices stabilize revenue for Belgian and South African producers. |
Research Methodology
A standing panel of reactor operations directors, radiopharmaceutical procurement managers at hospital networks, FDA regulatory affairs specialists, and nuclear medicine clinicians provided ongoing calibration against market developments. Primary interviews with IAEA safeguards officers and generator manufacturing quality heads combined with secondary validation from FDA 21 CFR guidance documents, EMA radiopharmaceutical submissions, IAEA HEU minimization reports, and hospital procurement databases. Bottom-up generator shipment modeling and top-down diagnostic procedure volume estimates triangulated market sizing.
Consistency checks validated volume and value outputs against reactor capacity utilization disclosures and technetium-99m consumption patterns across the projection horizon. The analytical framework segmented by production technology, end-user facility type, clinical application, and regional regulatory cluster. CAGRs were derived from reactor aging schedule impacts, LEU conversion timeline assumptions, and outpatient diagnostic migration rates. Industry-specific inputs incorporated Safari-1 maintenance windows, BR-2 reliability metrics, and OPAL export license expansions.
Decision-makers should treat outputs as directional under assumptions of sustained reactor reliability and cyclotron substitution remaining below clinical scale; material deviation would warrant model refresh. Revision becomes warranted when accelerator-based technetium-99m purity crosses FDA orphan drug thresholds or reactor unplanned outages exceed historical maintenance schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
China Cloud Gaming Technology Market
Others
Military Sensors Market
Others
Technical Films Market
Others
Surgical Simulation Market
Others
Grna Market
Others
Singapore Retail Market
Others
Global Simulation in Healthcare Market
Others
Turkey Health and Medical Insurance Market
Others
AI In Government And Public Services Market
Others
Indoor LBS Market
Others
PC As a Service Market
Others
Tripod Market
Others
Folding Screen Mobile Phone Market
Others
Germany Smart Home Market
Others
Wearable Translator Market
Others
US Tablet Market