
 Reinforcement Geosynthetics Market | 2026-2036
Reinforcement Geosynthetics Market Size, Share, and Industry Trends Forecast 2026-2036
Reinforcement Geosynthetics Market Analytics
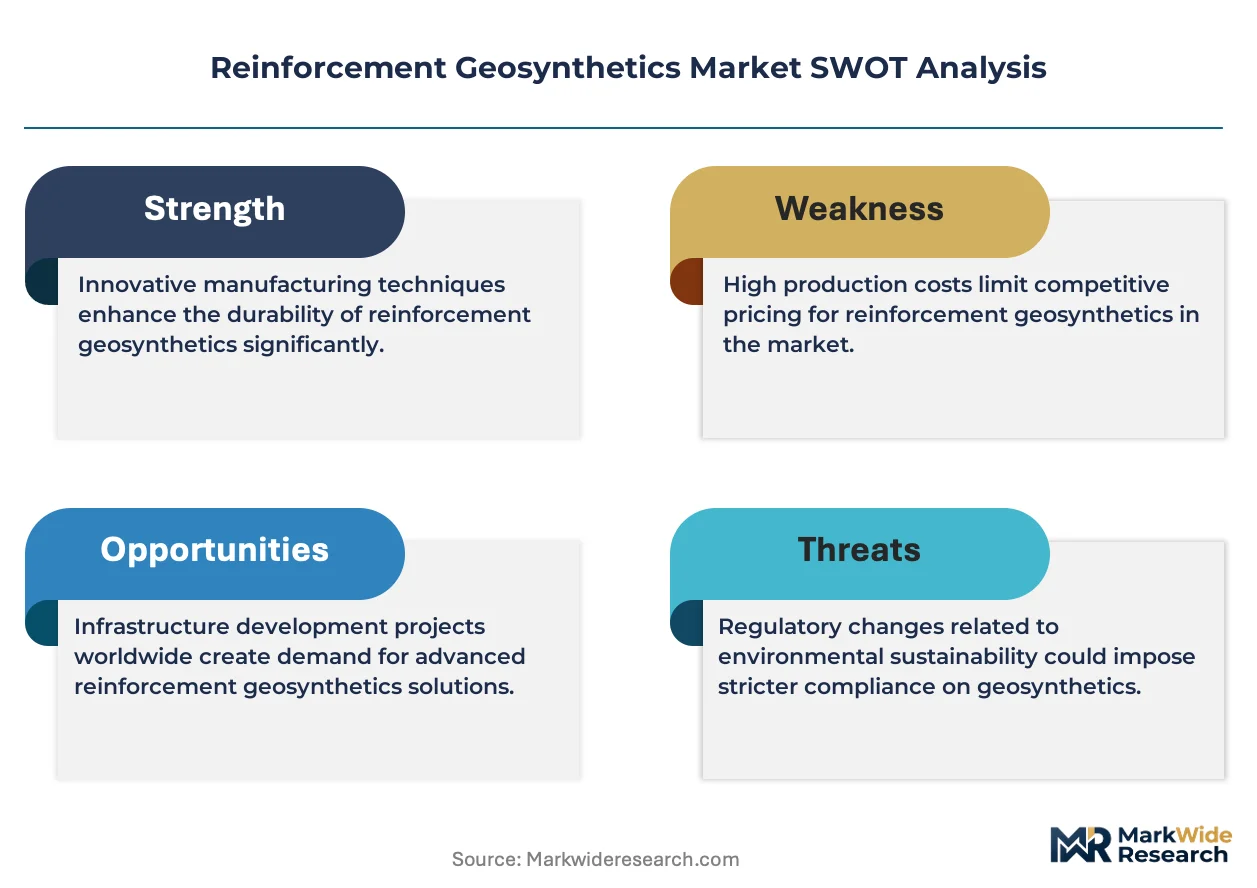
Performance-based maintenance contracts is decoupling capital equipment sales from recurring revenue streams across the reinforcement geosynthetics sector. Koninklijke TenCate N.V. leverages its vertically integrated polymer extrusion capabilities to control raw material quality from resin to finished geogrid. Solmax International Inc. anchors its competitive position through dominance in geomembrane-liner integration for mining containment projects. HUESKER Synthetic GmbH differentiates via specialized polyester geogrid formulations engineered for high-load railway embankments.
Reinforcement geosynthetics comprise polymeric materials manufactured through extrusion, weaving, or welding processes to achieve specified tensile strengths ranging from 20 kN/m to 800 kN/m, functioning primarily to stabilize soil masses and distribute structural loads across civil engineering applications. Geogrids command the largest product category due to their established performance in mechanically stabilized earth walls and base reinforcement, while geocells represent the fastest-expanding segment driven by demand for three-dimensional confinement in channel protection and vegetated slope applications. Polypropylene maintains material leadership through cost efficiency and chemical resistance, though polyester is gaining specification share in permanent load-bearing installations where creep performance governs design life.
The U.S. Federal Highway Administration's AASHTO M288 standard shapes geotextile specification requirements for federal-aid road projects, while the EU's Construction Products Regulation mandates CE marking and harmonized EN 13249-13257 testing protocols for geosynthetics deployed in European infrastructure. India's Bureau of Indian Standards enforces IS 16315 for geosynthetic reinforcement in roadworks, creating compliance barriers for uncertified imports. Stakeholders must monitor evolving polymer recycling mandates and embodied-carbon disclosure rules that will increasingly determine specification eligibility in publicly funded projects.
Market Dynamics
Performance-based maintenance contracts are decoupling capital equipment sales from recurring revenue streams across the reinforcement geosynthetics sector. Infrastructure agencies now specify long-term soil stabilization performance rather than product procurement alone.
Growth Catalysts
- EU Green Deal procurement mandates:Public works contracts now require recycled polymer content in geosynthetics, redirecting specification standards toward sustainable materials.
- India's National Highway Development corridors:Federal budget allocations for slope stabilization have intensified demand concentration along arterial road networks.
- Geocell three-dimensional confinement technology:Channel protection and vegetated slope applications are driving specification shifts from planar geogrids to cellular systems.
Market Restraints
- Polypropylene resin price volatility:Feedstock cost swings compress margins for extrusion-dependent manufacturers.
- Polymer recycling infrastructure gaps:Limited industrial-scale processing capacity constrains compliance with EU recycled-content mandates.
- Creep performance limitations in polypropylene:Permanent load-bearing installations require polyester substitution, fragmenting material supply chains.
Strategic Opportunities
- Indonesia's Trans-Sumatra Highway expansion:Soft soil conditions across the corridor create specification pull for high-tensile geogrid stabilization.
- Geomembrane-liner integration in mining containment:Convergence of reinforcement and barrier functions opens bundled contract opportunities.
- CE marking harmonization under EN 13249-13257:Simplified cross-border certification reduces compliance friction for multi-country suppliers.
Industry Challenges
- Geotechnical engineer talent scarcity:Specialized design expertise for mechanically stabilized earth walls limits project execution capacity.
- Bureau of Indian Standards IS 16315 certification timelines:Extended testing protocols delay market entry for imported products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reinforcement Geosynthetics Market |
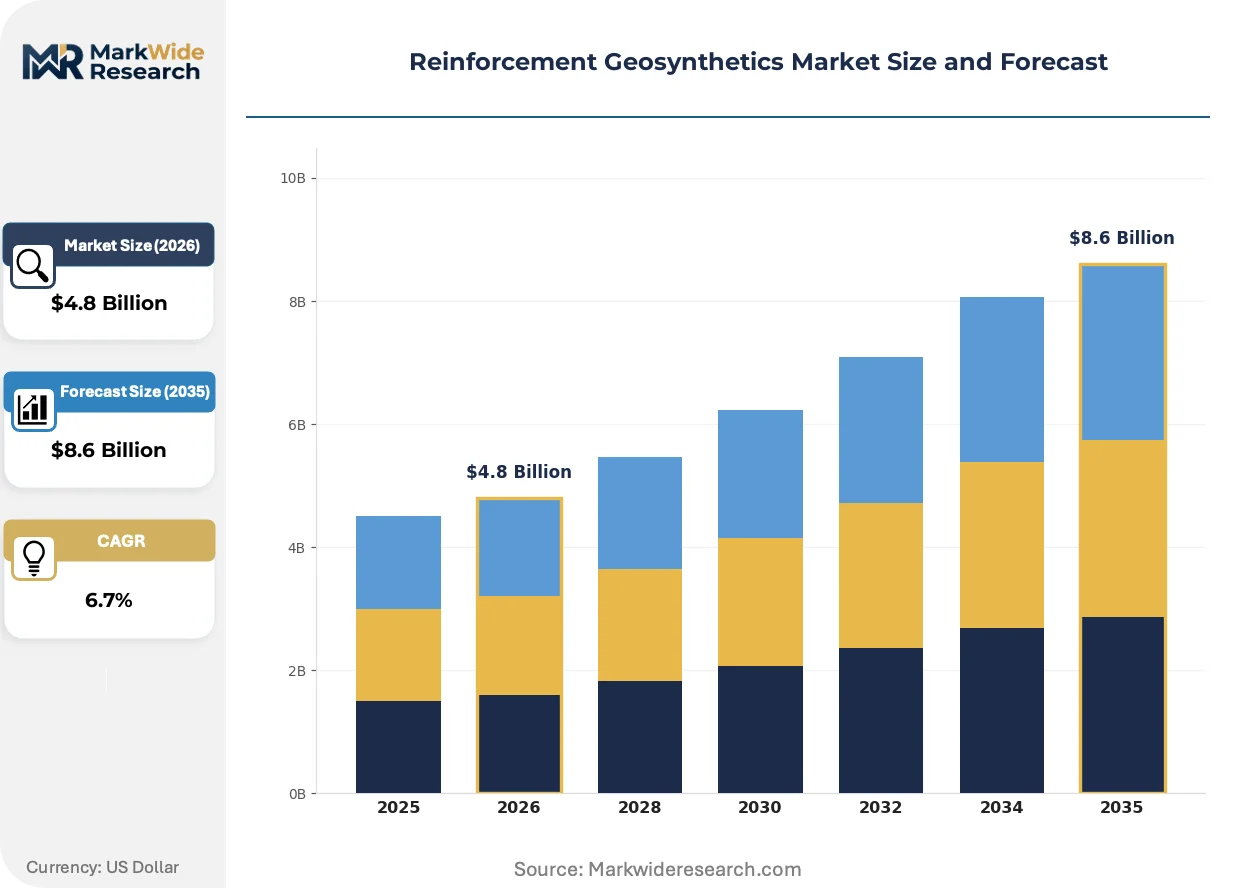
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Geogrids, Geotextiles, Geocells, Geomembranes Application: Soil Reinforcement, Slope Stabilization, Road Construction, Retaining Structures Material: Polypropylene, Polyester, Polyethylene, Natural Fiber End User: Infrastructure, Mining, Agriculture, Transportation |
| Companies Covered | Koninklijke TenCate N.V., Solmax International Inc., HUESKER Synthetic GmbH, Tensar International Corporation, SKAPS Industries, GSE Environmental, NAUE GmbH & Co. KG, Geofabrics Australasia, Officine Maccaferri S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reinforcement Geosynthetics Market Evolving Landscape
Material science advances and procurement model evolution are compressing traditional specification hierarchies. Buyers now prioritize performance guarantees over brand heritage.
Multiaxial geogrid architectures with improved junction strength are consolidating market share in mechanically stabilized earth applications. Mining operators in Chile and Australia specify these systems for haul road bases to reduce aggregate thickness. The technology is consolidating supplier margins by displacing conventional biaxial products in high-load environments.
REACH polymer registration requirements are tightening supply chain documentation obligations for European infrastructure projects. Manufacturers must demonstrate full substance inventory transparency to maintain CE marking eligibility. Geotextile categories face the steepest compliance burden, with some suppliers exiting the market rather than absorbing registration costs.
Asset-owner procurement teams now unbundle installation from material supply, creating direct relationships with geosynthetic manufacturers. Engineering-procurement-construction contractors resist this disintermediation, but public-private partnership structures in the United Kingdom and Australia increasingly favor separated contracting. This pattern concentrates volume with vertically integrated producers capable of offering design-build warranties.
Reinforcement Geosynthetics Market Segmentation
Segmentation in reinforcement geosynthetics reveals how specification criteria diverge across civil engineering disciplines. Material selection, dimensional stability requirements, and load-bearing duration dictate purchasing patterns more than brand loyalty.
Product Type:
Engineers select product categories based on load distribution geometry and installation labor intensity rather than unit cost alone.
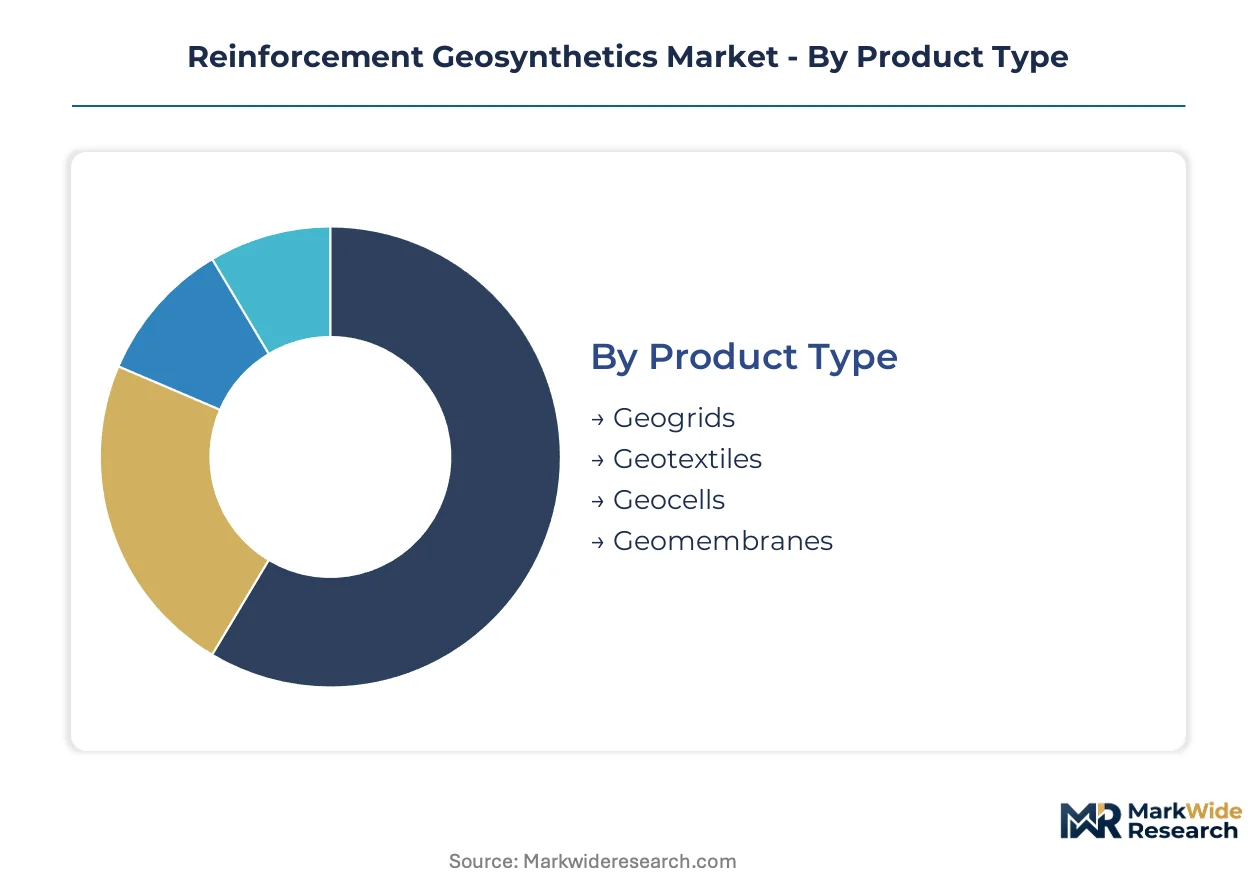
- Geogrids:Manufactured through extrusion or welding processes to create open-grid structures with tensile strengths spanning 20 kN/m to 800 kN/m. Demand concentrates in mechanically stabilized earth walls across India's National Highway Development corridors, where federal slope stabilization budgets have intensified procurement volumes.
- Geocells:Three-dimensional honeycomb structures expand during deployment to confine infill materials. Channel protection and vegetated slope applications in Indonesia's Trans-Sumatra Highway expansion are driving specification shifts from planar systems, as soft soil conditions require cellular confinement.
- Geotextiles:Permeable fabrics manufactured via weaving or non-woven needle-punching for filtration and separation functions.
- Geomembranes:Impermeable polymeric sheets serving barrier functions in containment applications, increasingly bundled with reinforcement layers in mining contracts.
Geogrids lead on scale; geocells lead on momentum.
Application:
Application selection follows substrate conditions and design life requirements, with permanent installations demanding different material specifications than temporary works.
- Road Construction:Base reinforcement and subgrade stabilization consume the largest product volumes, with AASHTO M288 specifications governing U.S. federal-aid projects and IS 16315 compliance mandatory for Indian arterial networks.
- Slope Stabilization:Mechanically stabilized earth systems and soil nail facing applications require high-tensile geogrids with specified junction strength. EU Green Deal procurement mandates for recycled polymer content are redirecting material specifications in European public works.
- Soil Reinforcement:Load transfer platforms and bearing capacity improvement for soft ground conditions.
- Retaining Structures:Facing elements and connection systems for permanent wall installations.
Road construction dominates procurement volume; slope stabilization commands the steepest expansion trajectory.
Material:
Material chemistry determines creep performance, chemical resistance, and compliance with emerging recycled-content mandates.
- Polypropylene:Dominates extruded geogrid production through cost efficiency and chemical resistance in aggressive soil environments. Polypropylene resin price volatility compresses margins for manufacturers dependent on feedstock extrusion.
- Polyester:High-tenacity yarns deliver superior creep performance for permanent load-bearing installations. Railway embankment specifications increasingly require polyester substitution where design life governs material selection.
- Polyethylene:Geomembrane and geocell production relies on HDPE formulations for chemical containment.
- Natural Fiber:Biodegradable options for temporary erosion control with limited structural load capacity.
Polypropylene anchors volume leadership; polyester gains share fastest in permanent infrastructure.
End User:
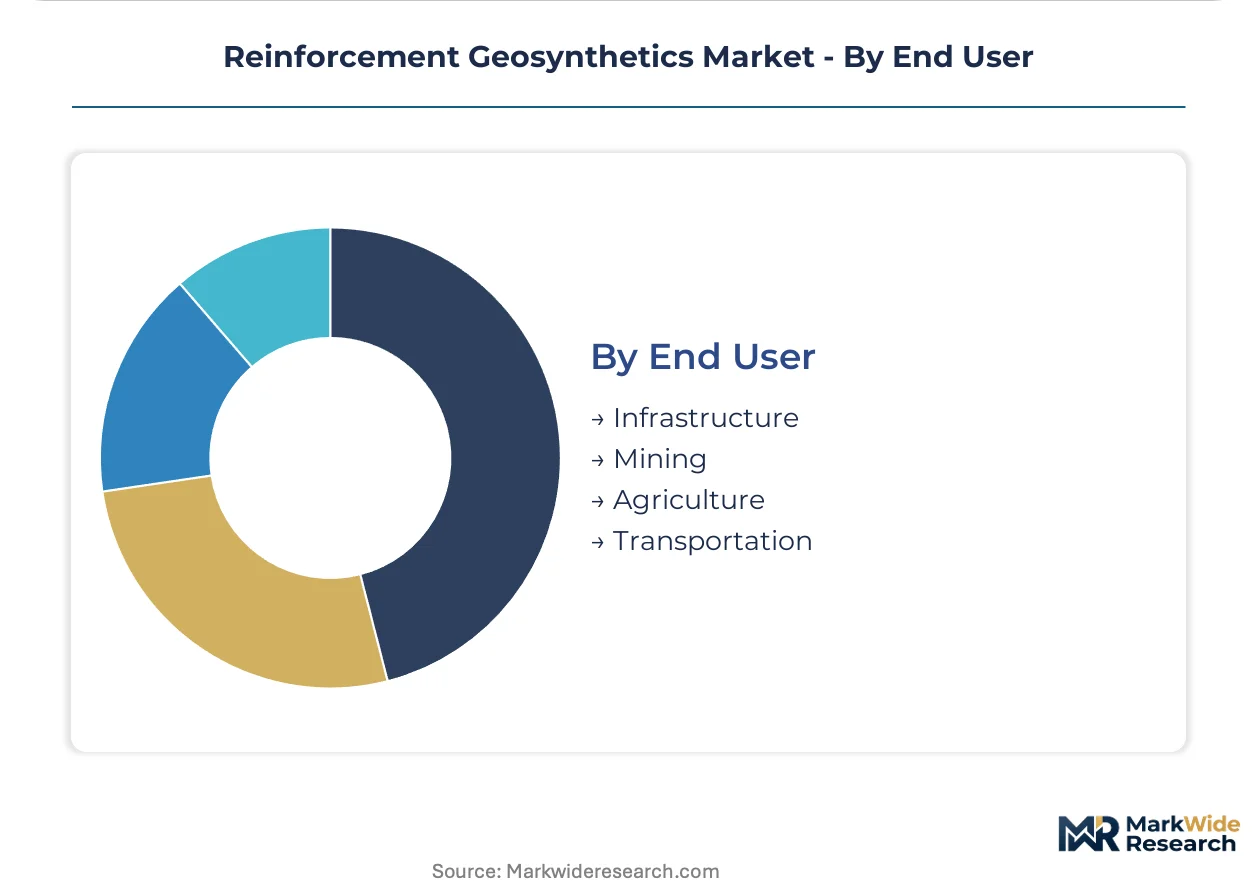
End-user procurement maturity varies sharply, with infrastructure agencies adopting performance-based maintenance contracts while mining operators prioritize bundled containment solutions.
- Infrastructure:Highway agencies and municipal authorities specify long-term soil stabilization performance rather than product procurement alone. Performance-based maintenance contracts decouple capital equipment sales from recurring revenue streams.
- Mining:Operators in Chile and Australia specify multiaxial geogrid systems for haul road bases to reduce aggregate thickness. Geomembrane-liner integration creates bundled contract opportunities combining reinforcement and barrier functions.
- Transportation:Railway authorities demand specialized polyester geogrid formulations for high-load embankment stabilization.
- Agriculture:Pond liners and secondary containment applications with lower specification intensity.
Infrastructure leads on procurement scale; mining offers the fastest-growing contract value per project.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's National Highway Development corridors are absorbing geogrid volumes faster than Germany's railway embankment renewal programs, though both markets operate under stringent certification regimes that filter supplier participation.
United States
The Federal Highway Administration's AASHTO M288 standard governs geotextile specifications for federal-aid road projects across the Interstate system. State DOTs in Texas and California are expanding performance-based maintenance contracts that separate material procurement from installation services. The I-35 corridor reconstruction through Oklahoma and Kansas is driving multiaxial geogrid specifications for soft subgrade stabilization.
Germany
Railway embankment renewal along the Rhine-Alpine freight corridor requires specialized polyester geogrid formulations with certified creep performance. The EU Green Deal's recycled polymer procurement mandates are redirecting specification standards toward sustainable materials in federal infrastructure tenders. Industrial clusters in North Rhine-Westphalia host extrusion facilities serving cross-border projects into the Netherlands and Belgium.
India
Federal budget allocations for slope stabilization have intensified demand concentration along the Mumbai-Delhi Industrial Corridor and Bengaluru-Chennai Expressway. The Bureau of Indian Standards enforces IS 16315 certification for geosynthetic reinforcement in roadworks, creating compliance barriers for uncertified imports. Manufacturing capacity is clustering in Gujarat and Maharashtra to serve western highway corridors.
Indonesia
The Trans-Sumatra Highway expansion traverses soft peat soils that require high-tensile geogrid stabilization and cellular confinement systems. National infrastructure agencies are unbundling installation contracts from material supply, enabling direct procurement relationships with extrusion manufacturers. Project clusters in North Sumatra and Riau provinces are absorbing geocell volumes for channel protection applications.
Australia
Mining operators in Western Australia's Pilbara region specify multiaxial geogrid systems for haul road bases to reduce aggregate thickness and maintenance frequency. The convergence of reinforcement and barrier functions is creating bundled contract opportunities combining geogrids with geomembrane liners. Queensland's coal seam gas containment projects are driving specification pull for integrated geosynthetic systems.
Reinforcement Geosynthetics Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with vertically integrated extruders commanding premium positioning in specification-intensive applications while regional fabricators compete on logistics proximity. The vendor base organizes into three tiers: polymer producers with captive geogrid operations, independent converters sourcing commodity resins, and installation contractors backward-integrating into material supply. Dominant competitive moves include capacity expansion in Southeast Asian growth corridors and strategic partnerships between extrusion specialists and mining EPC contractors.
Among European-headquartered specialists, Koninklijke TenCate N.V. and HUESKER Synthetic GmbH exemplify the vertically integrated archetype controlling resin-to-finished-product quality chains. Solmax International Inc. occupies a position representing North American-scale producers with emphasis on containment-integrated solutions. These three entities anchor the premium tier where design-build warranties and long-term performance guarantees determine specification outcomes.
| Leading Market Players |
|---|
| Koninklijke TenCate N.V. |
| Solmax International Inc. |
| HUESKER Synthetic GmbH |
| Tensar International Corporation |
| SKAPS Industries |
| GSE Environmental |
| NAUE GmbH & Co. KG |
| Geofabrics Australasia |
| Officine Maccaferri S.p.A. |
| Others |
Value Network & Pricing Analysis
Captive polymer extrusion capabilities at TenCate, Solmax, and HUESKER anchor both supply security and pricing power, insulating premium-tier producers from polypropylene resin volatility while forcing commodity converters into margin compression during feedstock spikes.
Pricing Analysis
Capacity additions in Gujarat and Maharashtra are reshaping price floors for standard-grade geogrids across South Asian infrastructure tenders. Project-based contract pricing dominates procurement, with differentiation anchored in IS 16315 certification tier and design-build warranty duration. Cost compression in economy-tier biaxial geogrids is intensifying because Indonesian and Vietnamese converters are absorbing regional resin price swings to maintain volume share. State highway agencies in India exhibit the sharpest price sensitivity, while Australian mining operators prioritize performance guarantees over unit cost.
Supply Chain Analysis
Specialized polymer extrusion technicians are scarce in North Rhine-Westphalia and Gujarat industrial clusters, constraining capacity expansion timelines for multiaxial geogrid production. Manufacturing concentrates in Germany, India, and Indonesia, with raw material supply drawing from Saudi Arabian and U.S. Gulf Coast polypropylene feedstock. Single-source vulnerability in high-tenacity polyester yarn supply from China creates exposure for European railway embankment specifications. Distribution runs through engineering-procurement-construction contractors in legacy markets, while Indonesia and Australia increasingly favor direct manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in reinforcement geosynthetics rests on polyester substitution premiums and bundled geomembrane-reinforcement contracts that capture containment-project value pools.
For Market Incumbents: To counter disintermediation by asset-owner procurement teams, secure design-build warranty capabilities through captive installation partnerships or certified installer networks. Deepen upstream control over polymer compounding to guarantee recycled-content compliance under EU Green Deal mandates without sourcing dependency. For New Entrants and Emerging Players: The premium-economy price gap in Indian National Highway Development corridors creates entry space for IS 16315-certified regional converters with logistics proximity to Maharashtra and Gujarat project clusters. Target geocell three-dimensional confinement applications where specification standards remain less codified than geogrid categories. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale extrusion specialists with certified testing laboratories because fragmented regional compliance requirements favor consolidated certification assets. Watch for Bureau of Indian Standards accelerated approval pathways as inflection signal for import substitution momentum.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive recycled-content production secures EU Green Deal eligibility without external sourcing risk. |
| Geocell Manufacturing Scale-Up | Cellular confinement demand in Indonesia's soft-soil corridors outpaces planar geogrid specification growth. |
| IS 16315 Certification Investment | Indian federal highway mandates filter import competition through extended testing protocols. |
| Geomembrane-Liner Integration | Mining containment bundling in Chile and Australia captures barrier-function contract value. |
| Multiaxial Geogrid Product Launch | Haul road specifications in Western Australia's Pilbara region displace conventional biaxial systems. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with geotechnical design engineers, polymer extrusion plant managers, highway agency procurement officers, and mining EPC contract specialists against secondary validation through AASHTO M288 specification databases, Bureau of Indian Standards certification registries, EU Construction Products Regulation harmonized standards, and customs trade data for polypropylene resin flows. Bottom-up project pipeline assessment and top-down infrastructure budget allocation analysis were triangulated.
Historical reference periods anchored volume and value modeling across the projection horizon, with segmentation dimensions spanning product type, material chemistry, application discipline, and end-user procurement maturity. CAGRs were derived from installed-base replacement cycles and greenfield infrastructure pipeline conversion rates. Industry-specific forecast inputs included federal highway budget appropriation trajectories and mining capital expenditure survey data.
Caveats apply where polymer recycling infrastructure buildout lags EU mandate timelines or where geotechnical engineer talent scarcity constrains mechanically stabilized earth project execution capacity. Forecasts reflect assumptions about certification harmonization progress and resin price stabilization. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Aluminium Clad Printed Circuit Board Market
Others
Europe Electric Forklift Market
Others
Taiwan Retail Market
Others
Storm Surge Barriers Market
Others
Defense Optronics Market
Others
Global Smart Devices Market
Others
Smart Home As a Service Market
Others
China Online Gambling Market
Others
Global Personal Care Packaging Market
Others
High-Performance Films Market
Others
5G Enabled Healthcare Services Market
Others
Global on-Demand Laundry Service Market
Others
Next Gen Video Codecs Market
Others
Rope Market
Others
US Automotive LED Lighting Market
Others
Germany Smart Home Market