
 Artificial Urinary Sphincters Market | 2026-2036
Artificial Urinary Sphincters Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Urinary Sphincters Market Analysis
Implantable silicone elastomer engineering is fragmenting across competing material platforms, forcing manufacturers to choose between established polydimethylsiloxane formulations and newer hybrid polymers. Boston Scientific Corporation leverages vertical integration in balloon reservoir production to sustain margin control across its AMS 800 supply chain. Zephyr Surgical Implants anchors European market access through CE-marked adjustable pressure systems. GT Urological specializes in cost-optimized mechanical designs that compete aggressively in Asia-Pacific price-sensitive tenders.
Artificial urinary sphincters are implantable hydraulic prostheses comprising an inflatable cuff, pressure-regulating balloon, and control pump, typically constructed from medical-grade silicone with radio-opaque markers for fluoroscopic verification; they restore urethral coaptation pressure in patients with sphincter deficiency. Inflatable devices dominate procedural volume due to decades of clinical validation and surgeon familiarity, though adjustable devices represent the fastest-expanding segment as urologists seek postoperative pressure modulation without revision surgery. Minimally invasive delivery modes are capturing preference share as ambulatory surgery centers expand eligible case mixes, while stress incontinence applications anchor the indication base despite mixed incontinence presenting faster diagnostic growth.
The FDA's stringent PMA pathway for Class III urological implants shapes product development timelines and capital requirements for market entry, while CE marking under the EU Medical Device Regulation imposes enhanced clinical evidence standards on European manufacturers. Health Canada and Japan's PMDA maintain parallel but distinct biological safety testing protocols that fragment regulatory strategy for multinational suppliers. Stakeholders must monitor evolving reimbursement thresholds for outpatient minimally invasive procedures versus traditional surgical implantation, as payer category definitions will determine which delivery modes achieve scalable adoption.
Market Dynamics
Implantable silicone elastomer engineering is fragmenting across competing material platforms, forcing manufacturers to choose between established polydimethylsiloxane formulations and newer hybrid polymers that promise enhanced biocompatibility profiles.
Growth Catalysts
- Aging Demographics:Japan's super-aged society and Germany's expanding over-65 population create sustained procedural demand for sphincter deficiency treatment in established reimbursement environments.
- CE Marking Under EU MDR:Enhanced clinical evidence standards accelerate consolidation among European manufacturers capable of funding post-market surveillance infrastructure.
- Radio-Opaque Marker Integration:Fluoroscopic verification capabilities embedded in medical-grade silicone cuffs reduce revision rates and expand surgeon confidence in outpatient settings.
Market Restraints
- Medical-Grade Silicone Price Volatility:Petrochemical feedstock fluctuations and specialized purification requirements compress margins for balloon reservoir production.
- FDA PMA Pathway Duration:Class III urological implant premarket approval timelines extending 18-36 months deter venture capital from early-stage device development.
- Mechanical Competitors:Male slings and injectable bulking agents capture price-sensitive cases in Asia-Pacific tender environments where hydraulic systems face reimbursement caps.
Strategic Opportunities
- Adjustable Pressure Systems:Postoperative modulation without revision surgery addresses the fastest-expanding segment as urologists prioritize patient-specific pressure calibration.
- Ambulatory Surgery Center Expansion:Minimally invasive delivery modes capture preference share as ASCs in the United States broaden eligible case mixes beyond hospital settings.
- Japan PMDA Parallel Track:Distinct biological safety testing protocols create first-mover advantages for manufacturers establishing localized quality management systems.
Industry Challenges
- Implantable Device Engineering Talent:Scarce expertise in silicone elastomer fatigue testing and hydraulic seal design constrains product development velocity.
- ISO 10993 Biological Evaluation:Extended cytotoxicity and sensitization study timelines delay market entry for novel hybrid polymer formulations.
- Legacy Cuff Integration:Surgeon familiarity with decades-old inflatable designs creates adoption friction for next-generation adjustable mechanisms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Urinary Sphincters Market |
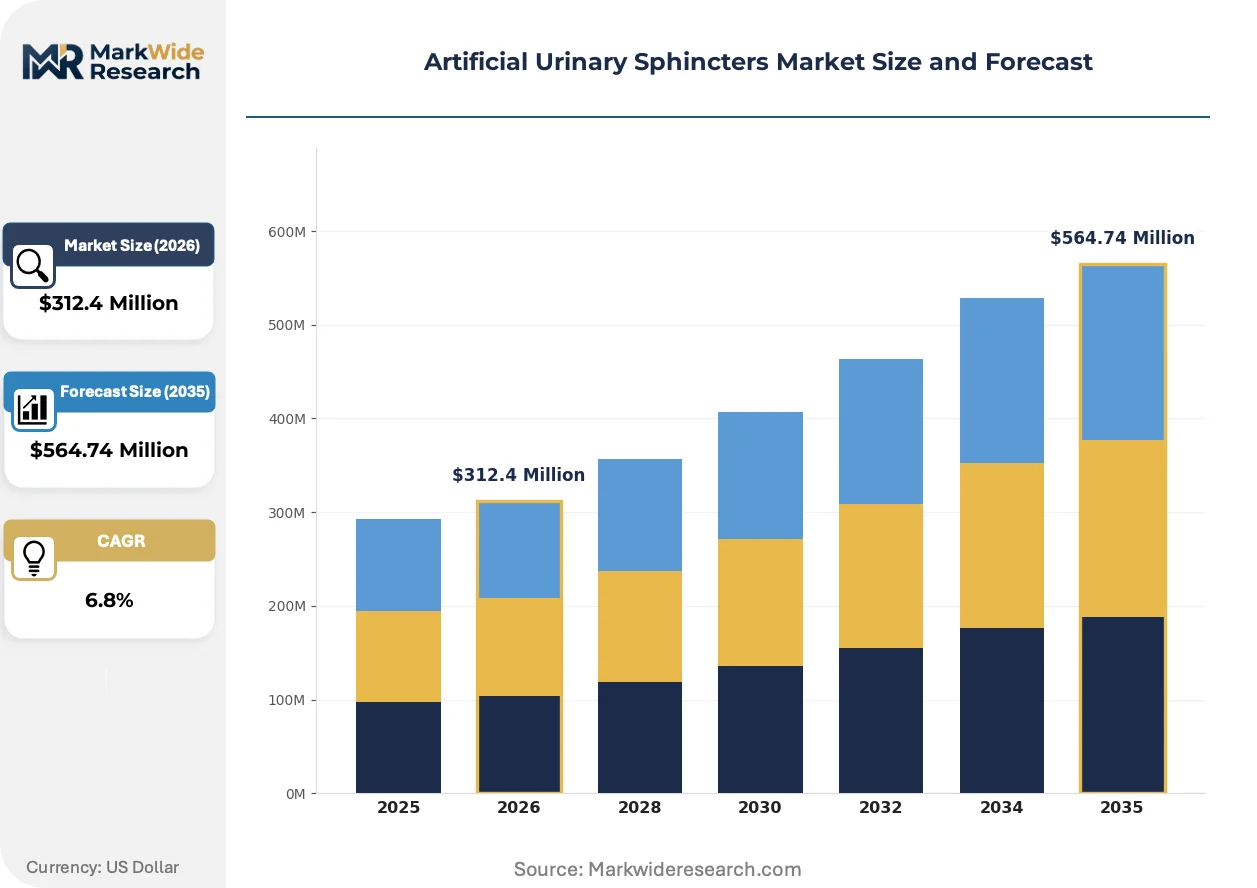
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inflatable Devices, Magnetic Devices, Prosthetic Devices, Adjustable Devices End User: Urology Clinics, Hospitals, Rehabilitation Centers, Specialty Practices Delivery Mode: Surgical Procedure, Outpatient Procedure, Minimally Invasive Procedure, Transurethral Procedure Application: Stress Incontinence, Urge Incontinence, Mixed Incontinence, Surgical Intervention |
| Companies Covered | Boston Scientific Corporation, Zephyr Surgical Implants, GT Urological, Promedon S.A., Anhui Longterm Medical Products Co., Ltd., Affluent Medical, Uromedica, Inc., RBM-Med, Silimed Medical Devices, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Urinary Sphincters Market Emerging Trajectories
Active compression of postoperative revision rates is reshaping competitive positioning around pressure modulation capabilities rather than initial implant success metrics alone.
Hybrid polymer formulations incorporating surface-modified silicone substrates are collapsing the performance gap between established polydimethylsiloxane and experimental biodegradable alternatives. Academic medical centers in Germany and Japan are piloting these materials in investigator-initiated trials. The structural consequence is collapsing reliance on permanent foreign body response management, shifting value toward resorbable tension elements.
EU Medical Device Regulation clinical evidence requirements are extending post-market surveillance obligations for hydraulic urological implants beyond the previous Medical Device Directive framework. Manufacturers must now fund multi-year patient registries to maintain CE marking validity. Adjustable pressure systems face the steepest compliance burden due to their mechanistic complexity and longer intended dwell times.
Hospital procurement committees are consolidating vendor relationships for implantable urological devices around single-source agreements that bundle device supply with surgeon training and revision coverage. United States health systems are replacing fragmented purchasing across individual urologists with centralized value analysis committees. This concentration is most visible in integrated delivery networks where standardized pressure-regulating balloon specifications reduce inventory complexity.
Artificial Urinary Sphincters Market Segmentation
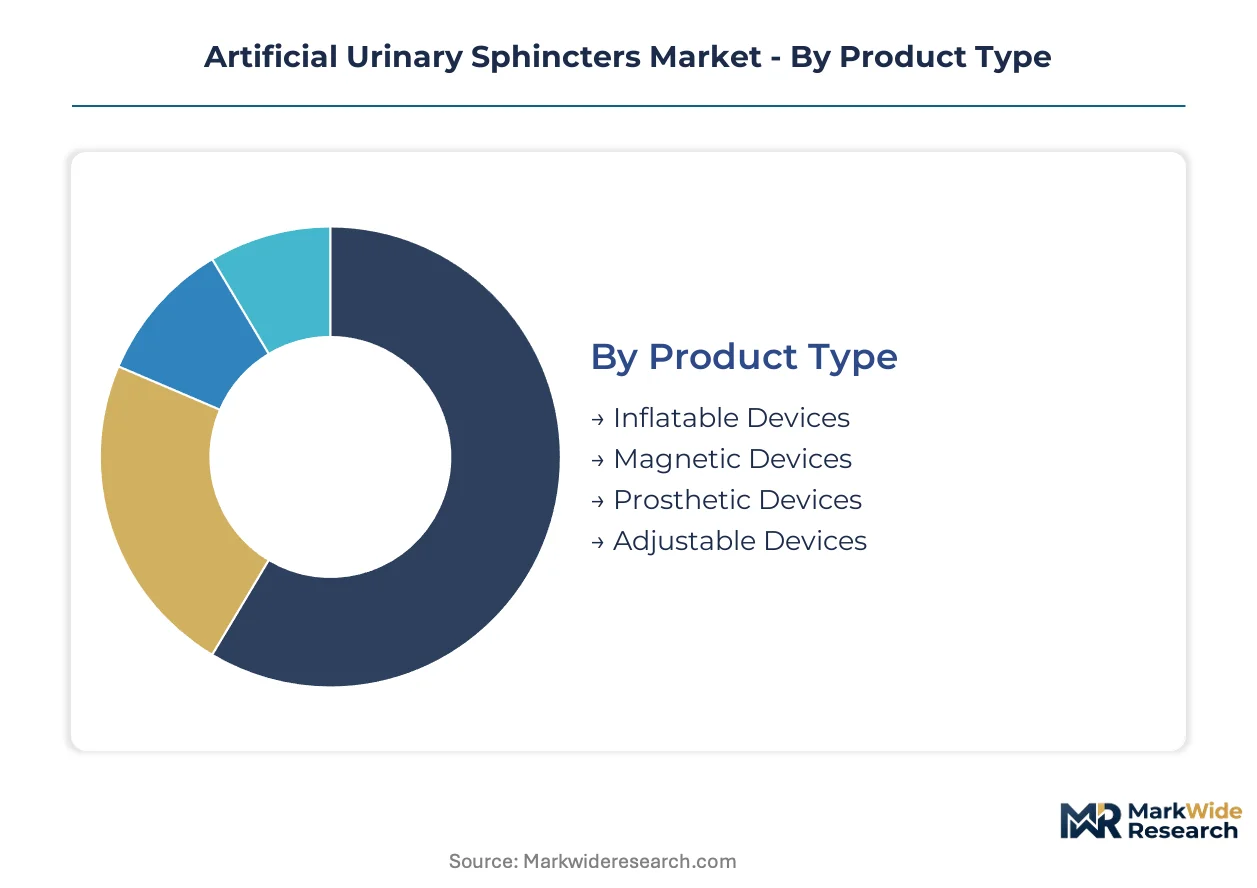
Segmentation in artificial urinary sphincters determines procurement patterns, reimbursement pathways, and surgeon training investments. Each dimension—product architecture, care setting, delivery approach, and clinical indication—carries distinct regulatory and commercial implications that shape manufacturer resource allocation.
Product Type:
After-sales service intensity varies sharply across hydraulic complexity tiers, with pressure-modulating mechanisms demanding specialized technician networks that inflate operational overhead.
- Inflatable Devices:Three-component hydraulic systems combining silicone elastomer cuffs with pressure-regulating balloons and scrotal/labial pumps dominate procedural volume. Demand concentrates in United States academic medical centers where decades of implantation data support standardized training protocols and established revision surgery workflows.
- Adjustable Devices:Postoperative pressure calibration mechanisms eliminate secondary surgical interventions for urethral atrophy management. German and Japanese urology departments prioritize these systems for their super-aged patient populations where tissue compliance changes unpredictably over multi-year implant dwell times.
- Magnetic Devices:Externally actuated closure mechanisms reduce mechanical failure modes but require patient manual dexterity.
- Prosthetic Devices:Non-hydraulic mechanical alternatives compete in price-capped tender environments.
By volume, inflatable devices lead. By growth pace, adjustable devices are ahead.
End User:
Procurement authority concentration determines pricing leverage, with centralized hospital purchasing departments extracting steeper discounts than fragmented specialty practices.
- Hospitals:Integrated delivery networks bundle device supply with surgeon credentialing and complication coverage. United States health systems increasingly mandate fluoroscopic verification capabilities and standardized pressure-regulating balloon specifications to reduce inventory complexity across multiple campuses.
- Urology Clinics:Ambulatory-focused practices drive adoption of minimally invasive delivery modes as case volume shifts from inpatient settings. Reimbursement thresholds for outpatient procedures determine which device configurations achieve scalable deployment in this channel.
- Rehabilitation Centers:Postoperative programming and patient training infrastructure influence device selection for complex cases.
- Specialty Practices:Individual practitioner purchasing retains preference for familiar legacy cuff designs despite next-generation alternatives.
By installed base, hospitals dominate. By preference shift velocity, urology clinics are accelerating fastest.
Delivery Mode:
Margin structures compress as invasiveness decreases, with transurethral approaches commanding premium pricing that reflects technical complexity and limited surgeon supply.
- Minimally Invasive Procedure:Laparoscopic and robotic-assisted implantation techniques expand eligible patient populations to those previously excluded by open surgical risk profiles. Ambulatory surgery centers in the United States capture preference share as payer category definitions evolve to cover same-day discharge protocols.
- Surgical Procedure:Open implantation remains standard for complex revision cases and patients with extensive pelvic radiation history. Academic medical centers maintain proficiency for these technically demanding scenarios where tissue planes are obliterated.
- Outpatient Procedure:Same-day discharge protocols reduce total episode cost but require rigorous patient selection criteria.
- Transurethral Procedure:Endoscopic placement techniques limit market penetration due to restricted device compatibility and narrow surgeon training pipelines.
By procedural volume, surgical approaches lead. By expansion trajectory, minimally invasive procedures are climbing the fastest.
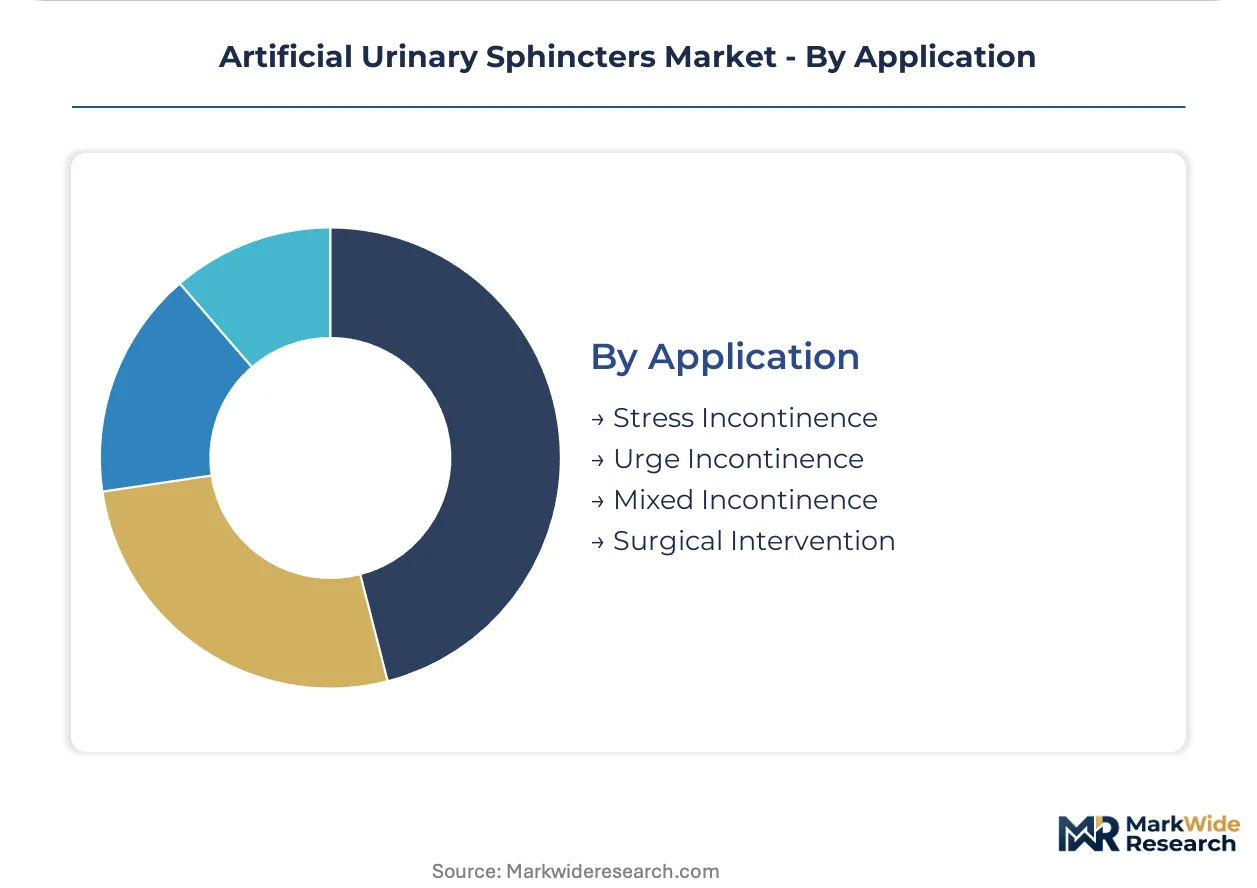
Application:
Diagnostic coding specificity determines reimbursement adequacy, with mixed incontinence presentations facing coverage uncertainty that delays device utilization.
- Stress Incontinence:Sphincter deficiency from radical prostatectomy, trauma, or neurologic conditions represents the core indication with established coverage policies. United States Medicare and commercial payers maintain consistent prior authorization pathways for post-prostatectomy cases.
- Mixed Incontinence:Combined urge and stress components present diagnostic complexity that fragments treatment algorithms. German reimbursement frameworks increasingly recognize device eligibility for this population as urodynamic testing protocols standardize.
- Urge Incontinence:Detrusor overactivity without sphincter deficiency excludes most patients from device candidacy.
- Surgical Intervention:Revision and explantation procedures carry distinct coding and coverage considerations.
By treatment volume, stress incontinence leads. By diagnostic growth rate, mixed incontinence is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in implantable urological devices tilt toward net-importing markets with aging demographics and established reimbursement frameworks. Export capacity concentrates among German, Swiss, and US manufacturers with vertical control over silicone component production. Import dependency shapes procurement timelines in Asia-Pacific and Middle Eastern markets.
United States
Medicare coverage determination for post-prostatectomy incontinence procedures sustains procedural volume at academic medical centers. FDA PMA pathway requirements for Class III urological implants extend development timelines and favor incumbent manufacturers with established regulatory infrastructure. Minneapolis and Boston corridor hospitals anchor demand concentration, with integrated delivery networks consolidating vendor contracts around fluoroscopic verification capabilities.
Germany
Super-aged population demographics and statutory health insurance coverage for adjustable pressure systems drive preference for postoperative modulation technologies. EU Medical Device Regulation clinical evidence standards impose multi-year patient registry obligations on CE-marked manufacturers. Baden-Württemberg and Bavaria industrial clusters host specialized silicone elastomer fabricators supplying balloon reservoir components to device assemblers.
Japan
PMDA biological safety testing protocols for permanent implants create distinct regulatory entry barriers favoring early entrants with localized quality management systems. METI reimbursement pricing for minimally invasive urological procedures expands ambulatory eligibility. Tokyo and Osaka metropolitan medical centers pilot hybrid polymer formulations in investigator-initiated trials, shifting toward resorbable tension elements.
China
NMPA Class III medical device registration requirements and centralized procurement tenders for public hospitals compress pricing for hydraulic implant systems. Dual carbon goals influence domestic manufacturing facility energy compliance costs. Yangtze River Delta medical device industrial parks attract contract manufacturers serving Asia-Pacific price-sensitive markets with cost-optimized mechanical designs.
India
CDSCO medical device rules and import dependency for specialized silicone components constrain domestic assembly capacity. Private hospital chains in Delhi-NCR and Mumbai drive procedural volume for stress incontinence indications among medical tourists. BIS standards adoption for implantable polymers remains limited, fragmenting quality verification across state-level health procurement systems.
Artificial Urinary Sphincters Market Vendor Landscape
On the supply side, the industry is consolidating around manufacturers with captive silicone component production and established regulatory dossiers. Tiered competitive positioning separates premium-tier adjustable systems from standard inflatable devices and economy mechanical alternatives. Strategic archetypes include vertically integrated multinationals with PMA-approved portfolios, European specialists with MDR-compliant adjustable platforms, and Asia-Pacific cost-optimized fabricators. Dominant competitive moves encompass backward integration into balloon reservoir production and geographic expansion through CE-marked distribution networks.
Among North American incumbents, Boston Scientific Corporation exemplifies the vertically integrated archetype with in-house control over critical silicone supply chains. Zephyr Surgical Implants represents the European specialist tier with MDR-anchored adjustable pressure systems. GT Urological occupies the Asia-Pacific cost-optimized position, competing in price-capped tender environments through mechanical design simplification.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Zephyr Surgical Implants |
| GT Urological |
| Promedon S.A. |
| Anhui Longterm Medical Products Co., Ltd. |
| Affluent Medical |
| Uromedica, Inc. |
| RBM-Med |
| Silimed Medical Devices |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese silicone component fabrication is compressing balloon reservoir margins while simultaneously enabling aggressive tender pricing in Asia-Pacific procurement cycles. This utilization asymmetry between German precision manufacturers and Asian volume producers fragments pricing power across regional buyer archetypes.
Pricing Analysis
Hospital procurement committees anchor a three-tier pricing structure across premium, standard, and economy levels, with integrated delivery networks extracting steepest discounts through single-source bundling of device supply with surgeon training. Price differentiation hinges on CE marking tier under EU MDR and fluoroscopic verification capabilities embedded in cuff designs. Cost compression in economy mechanical alternatives is intensifying because NMPA centralized procurement tenders in China cap reimbursement for hydraulic systems. Asia-Pacific public hospital buyers exhibit highest price sensitivity, while United States academic medical centers prioritize clinical validation over unit cost.
Supply Chain Analysis
Extended payment terms from German and Swiss balloon reservoir suppliers are straining working capital for device assemblers lacking captive silicone production. Geographic supply concentration centers on Germany, Switzerland, and the United States for medical-grade polydimethylsiloxane formulations, with China and India hosting cost-optimized mechanical component fabrication. Raw material dependencies include petrochemical-derived silicone elastomers, radio-opaque barium sulfate markers, and surgical-grade titanium connectors. Single-source vulnerability in specialized fatigue testing equipment constrains quality verification throughput. Distribution runs through hospital value analysis committees in integrated delivery networks and centralized procurement authorities in European statutory health insurance systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Artificial urinary sphincter demand is recovering from pandemic-deferred elective procedure backlogs, with cyclical momentum sustained by Japan's super-aged demographic acceleration and Germany's expanding over-65 population requiring sphincter deficiency intervention.
For Market Incumbents: Build regulatory dossier moats through backward integration into balloon reservoir production and PMA pathway infrastructure that deters venture capital from early-stage device development. Incumbent manufacturers should consolidate surgeon training networks around fluoroscopic verification protocols to lock out adjustable device competitors, while expanding CE-marked post-market surveillance registries to satisfy EU MDR multi-year patient tracking obligations that strain smaller European specialists. For New Entrants and Emerging Players: Mid-market urology clinics in United States ambulatory surgery centers represent the most penetrable entry point for minimally invasive delivery modes as payer category definitions evolve toward same-day discharge protocols. New entrants should target Japanese metropolitan medical centers piloting hybrid polymer formulations, leveraging PMDA biological safety testing parallel track advantages for first-mover positioning. A focused go-to-market angle partners with regional GPO contracts managers to bypass consolidated hospital purchasing committees. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across adjustable pressure system manufacturing due to EU MDR clinical evidence requirements and extended cytotoxicity study timelines for novel hybrid polymers. Long-term viability over the next decade favors manufacturers with established silicone elastomer supply chains and MDR-compliant post-market surveillance infrastructure. Acquisition target archetypes include European specialists with CE-marked adjustable platforms and localized Japanese quality management systems. The signal to watch is NMPA tender pricing compression in China triggering consolidation among Asia-Pacific cost-optimized fabricators unable to sustain margin erosion.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evidence requirements accelerate consolidation among manufacturers funding multi-year patient registries. |
| Backward Integration | In-house balloon reservoir production sustains margin control against medical-grade silicone price volatility. |
| Hospital System Partnership | Single-source agreements bundling device supply with revision coverage lock out fragmented specialty practice competitors. |
| Reimbursement Strategy | Prior authorization pathway optimization for post-prostatectomy cases secures Medicare coverage determination stability. |
| Software Companion Development | Pressure modulation calibration applications expand adjustable device adoption among urologists seeking postoperative control. |
Methodological Framework
Initial hypotheses were tested against primary input from urology department heads, hospital purchasing committee members, biomedical engineers specializing in implantable devices, and GPO contracts managers, then refined through secondary validation. FDA PMA filings, CE marking databases under EU MDR, hospital procurement records, and CMS Medicare coverage determinations provided regulatory and commercial context. Bottom-up procedural volume estimates from ambulatory surgery centers and academic medical centers were triangulated against top-down manufacturer revenue segmentation across inflatable, adjustable, and mechanical device categories.
Demand-supply balance modeling anchored projections across the analysis window, with segmentation dimensions including product architecture complexity, care setting procurement authority, delivery mode invasiveness, and clinical indication coding specificity. CAGRs were derived from patient population epidemiology, procedure penetration rates, and reimbursement pathway evolution. Industry-specific forecast inputs incorporated PMDA biological safety testing timeline assumptions and EU MDR post-market surveillance cost burdens on adjustable system manufacturers.
Practitioners should monitor FDA PMA pathway duration extensions, NMPA tender pricing compression, and hybrid polymer fatigue testing breakthroughs for early signals of forecast revision. Macroeconomic deviation in petrochemical feedstock costs, regulatory restriction in permanent implant biological evaluation protocols, or technological displacement from resorbable tension elements would prompt reassessment of market trajectory assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Human Anatomy Model Market
Medical Devices
Telehealth Device Market
Medical Devices
MRI Coils Market
Medical Devices
Americas Wearable Medical Device Market
Medical Devices
France Contraceptive Devices Market
Medical Devices
MRI Motion Tracking Systems Market
Medical Devices
France Respiratory Devices Market
Medical Devices
Global Digital Pathology Systems Market
Medical Devices
Wheelchair and Components Market
Medical Devices
Latin America Breast Biopsy Needle Market
Medical Devices
Neurostimulation Market
Medical Devices
C-Arms Devices Market
Medical Devices
Artificial Implants Market
Medical Devices
Global Intraoral Cameras Market
Medical Devices
Endodontic Devices Market
Medical Devices
Global Syringe Pumps Market