
 Cryoballoon Ablation System Market | 2026-2036
Cryoballoon Ablation System Market Size, Share, and Industry Trends Forecast 2026-2036
Cryoballoon Ablation System Market Outlook
Electrophysiology department procurement is bifurcating between high-volume academic medical centers and mid-tier community hospitals seeking cost-efficient ablation platforms. Medtronic plc leverages its integrated mapping and cryoablation ecosystem to sustain catheter sales across both buyer tiers. Abbott Laboratories anchors its position through specialized balloon designs that navigate anatomical variability in pulmonary vein isolation. Boston Scientific Corporation differentiates via technology leadership in cryothermal energy delivery systems.
A cryoballoon ablation system employs nitrous oxide or similar cryogenic media delivered through a compliant balloon catheter to create circumferential transmural lesions around pulmonary vein ostia, operating at temperatures typically below minus forty degrees Celsius to achieve tissue necrosis while preserving extracellular matrix architecture. The product type dimension shows cryoballoons capturing the dominant margin pool as disposable single-use devices, while catheter introducers represent a mature segment with slower replacement cycles. Application demand concentrates in atrial fibrillation where procedure reimbursement supports capital investment, whereas supraventricular tachycardia occupies a smaller addressable niche with limited cryoballoon utilization.
FDA premarket notification pathways and CE marking under the EU MDR govern device commercialization, with both frameworks mandating clinical evidence for cryoablation safety endpoints that shape trial design budgets and time-to-market. The country's national pharmaceutical regulator in Japan applies supplemental PMDA review standards for cryothermal catheter systems that extend registration timelines relative to conventional radiofrequency devices. Stakeholders must monitor evolving NCD reimbursement determinations for catheter ablation procedures as these directly influence hospital capital allocation toward cryoballoon platform acquisition.
Market Dynamics
Electrophysiology lab consolidation and the migration of atrial fibrillation procedures from academic centers to high-volume community hospitals is compressing equipment procurement cycles and forcing platform standardization decisions.
Growth Catalysts
- FDA Breakthrough Device Designation:Expedited review pathways for next-generation cryoballoon catheters accelerate commercialization timelines and reduce regulatory uncertainty for manufacturers pursuing pulmonary vein isolation indications.
- Japan's aging demographic profile:The country's expanding elderly population drives procedural volume growth for arrhythmia treatment, with cardiac centers in Tokyo and Osaka expanding electrophysiology capacity.
- Real-time contact force sensing:Integrated pressure monitoring technology improves lesion transmurality predictability, reducing procedure time variability and supporting same-day discharge protocols.
Market Restraints
- Nitrous oxide supply concentration:Cryogen production clusters in industrial gas hubs of Germany and the United States create vulnerability to regional supply disruptions and price volatility.
- EU MDR clinical evidence requirements:The expanded scope of post-market surveillance and periodic safety update reports extends certification maintenance costs for CE-marked devices.
- Radiofrequency catheter substitution:Established thermal ablation platforms with lower per-procedure supply costs compete for hospital budget allocation in price-sensitive procurement environments.
Strategic Opportunities
- India's underserved cardiac care infrastructure:Tier-2 cities including Ahmedabad and Chandigarh present greenfield electrophysiology lab development potential as domestic hospital chains expand specialty service lines.
- Hybrid operating room integration:Convergence of surgical and catheter-based ablation capabilities in integrated suites enables concomitant procedures for persistent atrial fibrillation patients.
- Centers for Medicare and Medicaid Services NCD expansion:Broadened national coverage determinations for catheter ablation would unlock procedure reimbursement in previously non-covered patient subpopulations.
Industry Challenges
- Electrophysiologist training pipeline constraints:Fellowship program capacity limitations in the United States and Germany restrict the specialist workforce expansion required to support procedure volume targets.
- Legacy EP recording system interoperability:Cryoballoon platform integration with existing cardiac mapping infrastructure demands costly interface development and validation testing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cryoballoon Ablation System Market |
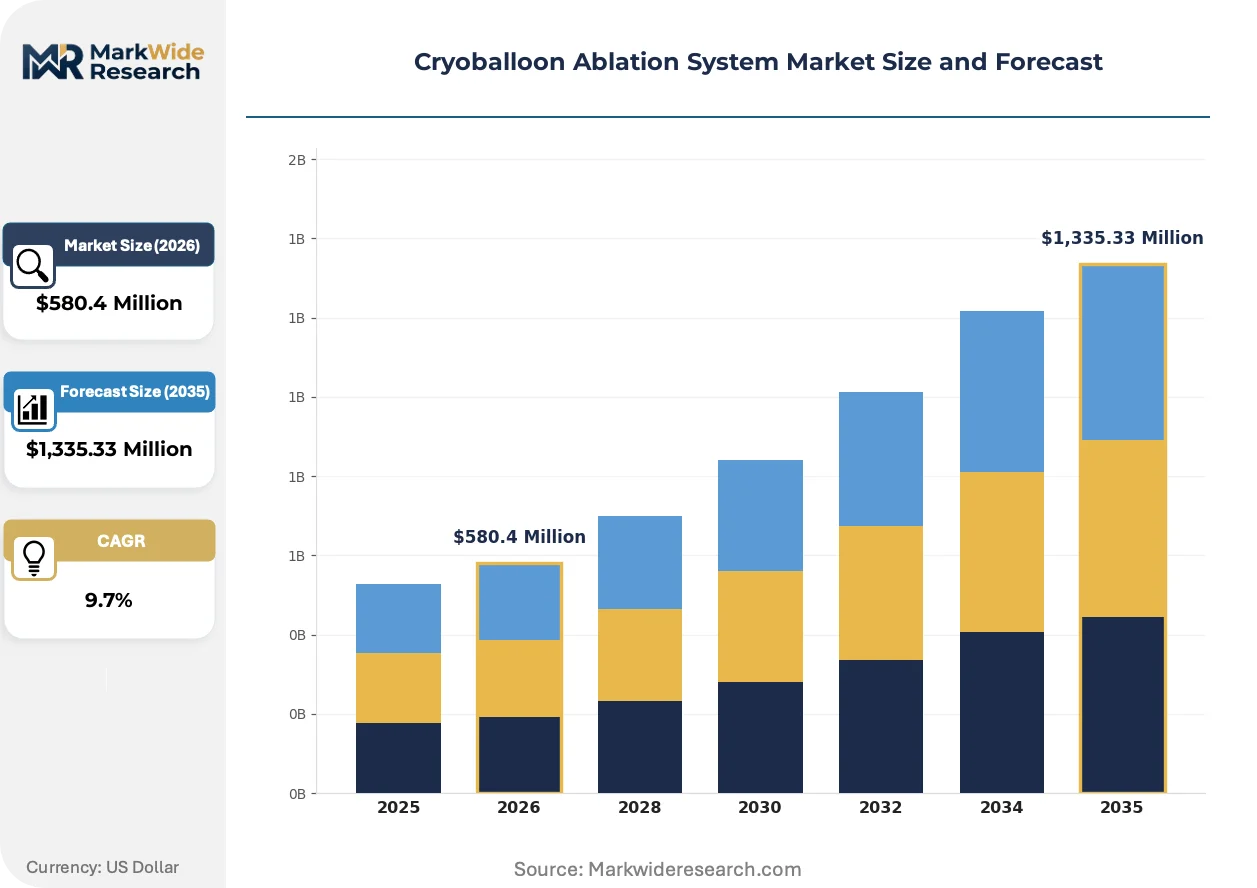
| Market Size in 2026 | $580.4 Million |
| Market Size in 2035 | $1,335.33 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cryoballoons, Catheters, Introducers, Accessories Application: Atrial Fibrillation, Supraventricular Tachycardia, Ventricular Tachycardia, Others End User: Hospitals, Cardiac Centers, Specialized Clinics, Rehabilitation Centers Delivery Mode: Transvenous, Femoral Access, Subclavian Access, Other Techniques |
| Companies Covered | Abbott Laboratories, Adagio Medical Inc., Medtronic plc, Baylis Medical, CardioFocus Inc., Boston Scientific Corporation, AtriCure Inc., MicroPort Scientific Corporation, Johnson & Johnson (Biosense Webster), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cryoballoon Ablation System Market Strategic Shifts
Device manufacturers are racing to differentiate through procedural efficiency gains and integration depth, shifting competitive emphasis from raw efficacy data to total cost-of-ownership optimization in hospital purchasing decisions.
Next-generation cryoballoon catheters incorporating variable compliance balloon materials and multi-electrode temperature monitoring arrays are displacing first-generation single-sensor designs in high-volume academic medical centers. Electrophysiology departments at institutions including Cleveland Clinic and Mayo Clinic have completed platform transitions, compressing average pulmonary vein isolation procedure times and reducing fluoroscopy exposure. The technology shift is displacing conventional cryoballoon systems in competitive tenders where total procedure economics rather than device price alone determine selection.
The European Union Medical Device Regulation's enhanced clinical evaluation requirements and stricter notified body oversight are extending time-to-market for novel cryoablation indications. Manufacturers must now submit comprehensive clinical data packages demonstrating long-term safety endpoints, increasing trial design complexity and regulatory affairs staffing. Small and mid-sized device companies without established European regulatory infrastructure are most affected, driving partnership strategies with larger entities possessing dedicated MDR compliance capabilities.
Hospital value analysis committees are consolidating supplier relationships and demanding multi-year total service contracts that bundle capital equipment, disposable supplies, and preventive maintenance. The traditional device-only procurement model is yielding to performance-guaranteed arrangements where vendors assume utilization risk. This restructuring is most visible in United States integrated delivery networks and German hospital federations, where standardized platform deployment across multiple sites enables volume-based pricing negotiations.
Cryoballoon Ablation System Market Segmentation
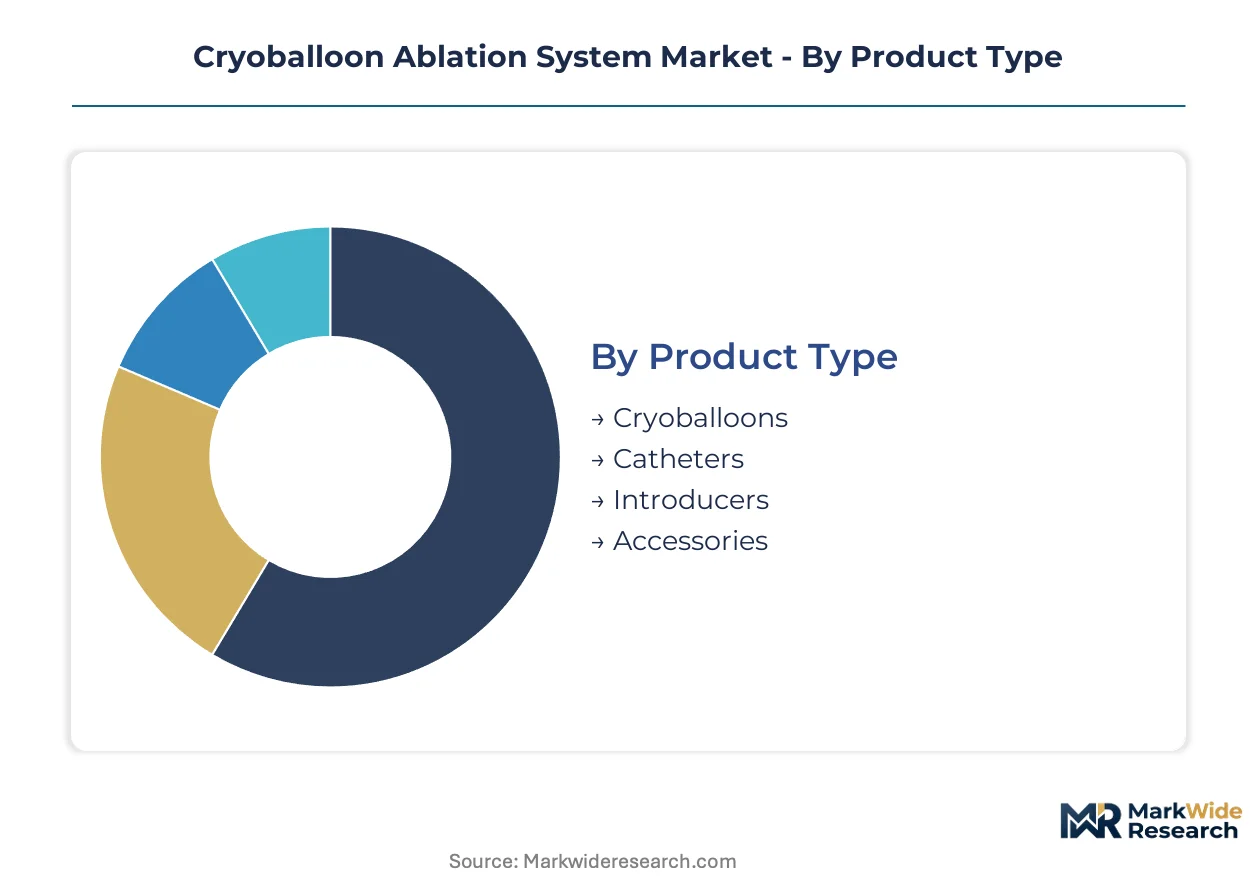
Segmentation in the cryoballoon ablation market determines procurement patterns, regulatory pathways, and margin structures across disposable and capital equipment categories. Device manufacturers align product portfolios with specific clinical workflows and reimbursement environments.
Product Type:
FDA premarket notification and EU MDR classification frameworks impose distinct clinical evidence requirements on balloon-based versus catheter-based devices, shaping development timelines and certification costs.
- Cryoballoons:Compliant balloon catheters deliver nitrous oxide at sub-minus-forty-degree temperatures to create circumferential transmural lesions. Demand concentrates in high-volume cardiac centers across the United States, Germany, and Japan where procedure reimbursement supports premium disposable pricing.
- Catheters:Steerable delivery systems integrate temperature monitoring arrays and pressure sensors for real-time lesion assessment. Academic medical centers in Tokyo and Osaka are upgrading to multi-electrode designs that reduce fluoroscopy exposure and enable same-day discharge protocols.
- Introducers:Sheath systems provide vascular access with hemostatic valve configurations.
- Accessories:Connection tubing, cryogen canisters, and pressure monitoring lines complete procedural setups.
Established volume favors cryoballoons; emerging adoption favors integrated catheter systems with sensing capabilities.
Application:
Reimbursement coding and clinical guideline endorsements determine addressable patient populations and procedure economics across arrhythmia indications.
- Atrial Fibrillation:Pulmonary vein isolation represents the dominant procedural application, with paroxysmal and persistent classifications driving device selection. Centers in Cleveland and Rochester anchor validation studies that support expanded coverage determinations.
- Supraventricular Tachycardia:Accessory pathway ablation and AV nodal modification occupy a narrower clinical niche with limited cryoballoon penetration. German electrophysiology labs in Munich and Hamburg maintain radiofrequency preference for these indications due to established workflow efficiency.
- Ventricular Tachycardia:Substrate-based ablation for ischemic cardiomyopathy patients.
- Others:Atrial flutter and premature ventricular contraction applications.
Reimbursement density favors atrial fibrillation; clinical expansion favors ventricular tachycardia as mapping integration improves.
End User:
Capital investment capacity and procedure volume thresholds segment customers across integrated delivery networks and independent specialty facilities.
- Hospitals:Academic medical centers and community hospital systems deploy hybrid operating rooms and dedicated electrophysiology suites. United States integrated delivery networks in Texas and Florida are consolidating supplier contracts across multi-site deployments.
- Cardiac Centers:Dedicated arrhythmia facilities optimize throughput with standardized cryoballoon platforms. Osaka-based specialty centers are expanding capacity to address Japan's aging demographic and rising atrial fibrillation prevalence.
- Specialized Clinics:Outpatient-focused facilities with limited procedural scope.
- Rehabilitation Centers:Post-procedure monitoring and recovery services.
Procurement scale favors hospital systems; margin expansion favors cardiac centers with focused volume concentration.
Delivery Mode:
Anatomical approach selection influences fluoroscopy requirements, complication profiles, and operator training pathways.
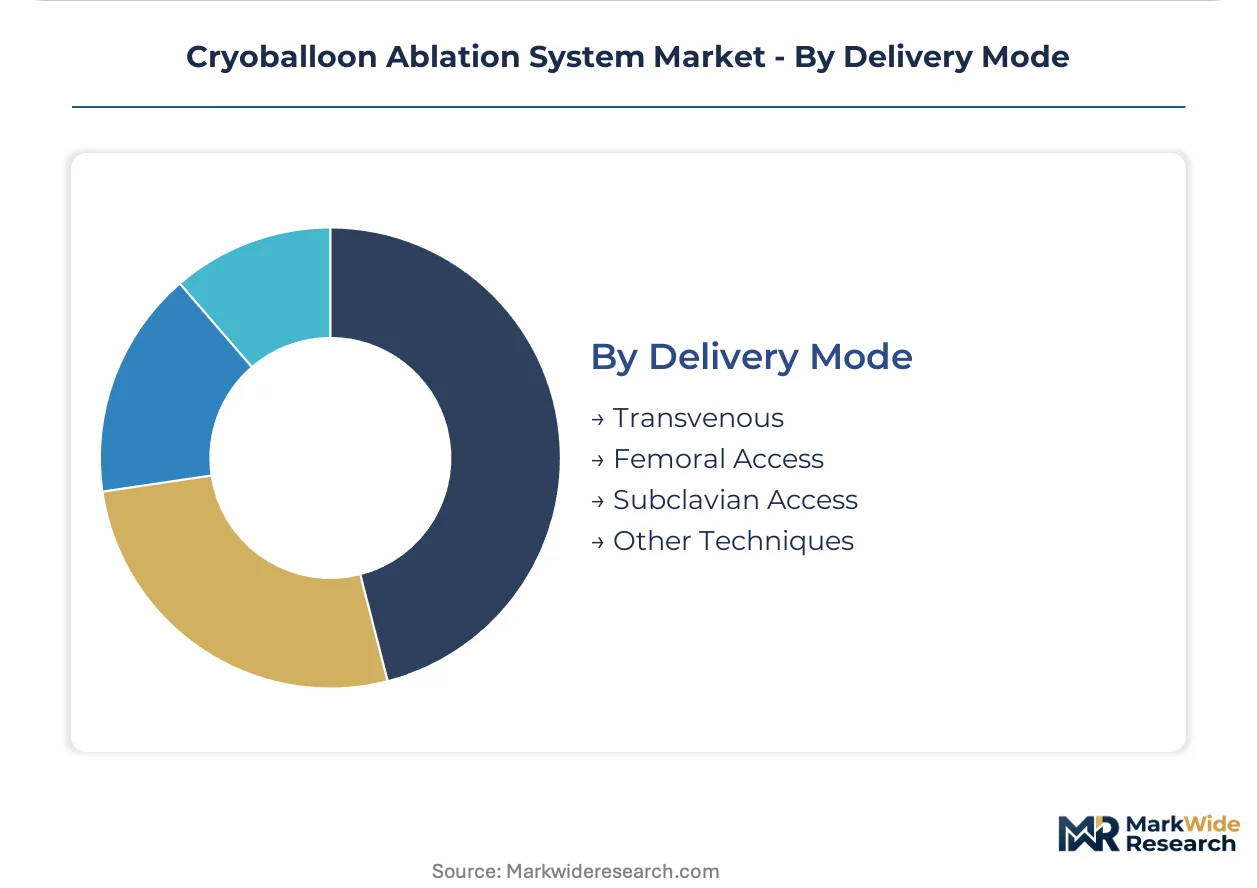
- Transvenous:Standard femoral venous access to the left atrium via transseptal puncture dominates pulmonary vein isolation workflows. German catheterization labs in Berlin and Frankfurt have standardized transvenous protocols that minimize vascular access complications.
- Femoral Access:Common femoral vein entry with variable sheath sizing accommodates balloon catheter diameters. Community hospitals across the United States favor femoral approaches for their compatibility with existing vascular closure device inventories.
- Subclavian Access:Alternative venous entry for patients with femoral occlusion or morbid obesity.
- Other Techniques:Jugular or hybrid surgical-catheter approaches for complex anatomies.
Workflow standardization favors transvenous delivery; patient-specific adaptation favors femoral access flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-speed rail corridors connecting the Rhine-Ruhr industrial belt to Frankfurt's logistics hubs underpin Germany's central role in cryoballoon distribution across continental Europe.
United States
Cleveland Clinic and Mayo Clinic anchor validation studies for next-generation cryoballoon platforms, driving clinical evidence requirements. FDA Breakthrough Device Designation pathways expedite review timelines for pulmonary vein isolation indications. Texas and Florida integrated delivery networks consolidate multi-site supplier contracts across electrophysiology lab expansions.
Germany
Industrial gas production clusters in the Rhine-Ruhr region supply nitrous oxide cryogen for balloon catheter manufacturing. EU MDR clinical evidence mandates extend certification maintenance costs for CE-marked devices. Berlin and Frankfurt catheterization labs standardize transvenous protocols that minimize vascular access complications.
Japan
Tokyo and Osaka cardiac centers expand electrophysiology capacity to address aging demographic-driven arrhythmia prevalence. PMDA review standards for cryothermal catheter systems extend registration timelines relative to conventional radiofrequency devices. METI industrial policy supports domestic hospital chain investment in hybrid operating room infrastructure.
India
Ahmedabad and Chandigarh present greenfield electrophysiology lab development potential as domestic hospital chains expand specialty cardiac service lines. CDSCO medical device registration pathways govern import and local manufacturing approvals for catheter-based cryoablation systems. Tier-2 city infrastructure investments concentrate private equity flows into diagnostic cardiology capacity.
United Kingdom
NHS England specialized commissioning frameworks determine reimbursement eligibility for atrial fibrillation ablation procedures. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR safety standards while streamlining national approval pathways. London and Manchester academic medical centers participate in pan-European cryoballoon efficacy registries.
Cryoballoon Ablation System Market Competitive Environment
Listed leaders compete with private specialists across regulatory compliance capabilities, with publicly traded device conglomerates leveraging dedicated MDR and FDA affairs infrastructure against mid-cap innovators dependent on partnership strategies. The vendor base organizes around three archetypes: integrated mapping-ablation ecosystem providers, specialized balloon design innovators, and diversified cardiovascular platform houses. Consolidation pressures favor acquisition of small cryothermal technology developers by established electrophysiology players. Vertical integration into cryogen supply chains represents a defensive maneuver against nitrous oxide price volatility.
Among diversified medical technology conglomerates, Medtronic plc, Abbott Laboratories, and Boston Scientific Corporation exemplify the ecosystem-provider archetype. Medtronic anchors integrated mapping and cryoablation platform positions across academic and community hospital tiers. Abbott Laboratories occupies specialized balloon design territory addressing anatomical variability in pulmonary vein isolation workflows. Boston Scientific Corporation sits within cryothermal energy delivery technology leadership, representing sustained R&D commitment to procedural efficiency gains. These three listed entities collectively shape competitive dynamics through multi-year total service contracting models that bundle capital equipment, disposable supplies, and preventive maintenance across United States integrated delivery networks and German hospital federations.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Adagio Medical Inc. |
| Medtronic plc |
| Baylis Medical |
| CardioFocus Inc. |
| Boston Scientific Corporation |
| AtriCure Inc. |
| MicroPort Scientific Corporation |
| Johnson & Johnson (Biosense Webster) |
| Others |
Value Chain & Pricing Dynamics
High-volume academic medical centers in the United States and Germany generate scale economies that compress per-procedure supply costs while elevating switching barriers for competing platforms. This concentration of purchasing power among integrated delivery networks and hospital federations simultaneously anchors price floors for premium cryoballoon systems and squeezes margins for mid-tier disposable suppliers.
Pricing Analysis
Volume-discount tiering separates multi-year total service contracts from transactional device-only procurement. Three-tier pricing structure across premium, standard, and economy levels differentiates by catheter generation and sensing capability integration. Cost compression in the standard tier is intensifying because radiofrequency catheter substitution pressures hospital budget allocation. Community hospitals in price-sensitive procurement environments exhibit highest price sensitivity; academic medical centers with established cryoablation workflows demonstrate lowest.
Supply Chain Analysis
Strategic stockpiling of cryogen canisters dominates inventory strategy among cardiac centers managing nitrous oxide supply uncertainty. Cryogen production clusters in Germany and the United States feed balloon catheter manufacturing, with industrial gas hubs in the Rhine-Ruhr region anchoring European supply. Nitrous oxide supply concentration creates single-source vulnerability to regional disruptions. Distribution runs through specialized medical device distributors serving electrophysiology lab networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital value analysis committee consolidation across United States integrated delivery networks and German hospital federations shifts procurement leverage toward buyers. This buyer-power concentration fragments vendor pricing power and forces multi-site contract standardization.
For Market Incumbents: Secure captive supply of nitrous oxide cryogen through backward integration into industrial gas partnerships, mitigating price volatility exposure. Defend installed base positions by accelerating FDA Breakthrough Device Designation pathways for next-generation sensing catheters, neutralizing radiofrequency substitution threats in community hospital tiers.
For New Entrants and Emerging Players: Post-market surveillance service gaps in EU MDR compliance represent the most penetrable white-space, as small device companies lack dedicated regulatory infrastructure. Target tier-2 Indian cities including Ahmedabad and Chandigarh with greenfield electrophysiology lab development partnerships. Pursue GPO contracts manager relationships as the primary go-to-market angle for initial hospital system access.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized cryothermal catheter developers with differentiated balloon compliance materials. Long-term viability hinges on mapping-ablation ecosystem integration depth rather than single-device innovation. Acquisition target archetype: mid-cap innovators with PMDA registration progress and stranded MDR compliance capabilities. The inflection signal to monitor is CMS NCD expansion timing for previously non-covered patient subpopulations.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Expedited review pathways accelerate commercialization timelines for pulmonary vein isolation catheters. |
| EU MDR Compliance Partnership | Regulatory infrastructure sharing reduces certification maintenance costs for CE-marked cryoablation devices. |
| Hybrid Operating Room Integration | Convergence of surgical and catheter capabilities enables concomitant persistent atrial fibrillation procedures. |
| Multi-site Total Service Contracting | Performance-guaranteed arrangements shift utilization risk to vendors across hospital system deployments. |
| Electrophysiologist Training Pipeline Investment | Fellowship program expansion addresses specialist workforce constraints limiting procedure volume targets. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA premarket notifications, EU MDR certification databases, and hospital procurement records. Electrophysiologists, biomedical engineers, GPO contracts managers, and regulatory affairs specialists provided operational perspectives. SEC 10-K filings, CMS Medicare reimbursement data, and clinical trial registries supplied validation benchmarks. Bottom-up procedure volume estimates triangulate with top-down market sizing across product type and application segments.
Segmentation dimensions modeled include product type, application indication, end-user facility tier, and delivery mode approach across the analysis window. CAGRs derive from procedure volume trajectories, reimbursement elasticity assumptions, and technology substitution rates. Cryogen supply concentration indices and electrophysiology lab density metrics inform regional allocation models.
Underlying assumptions cover stable FDA and PMDA review timelines, with deviation risk concentrated in EU MDR notified body capacity constraints and nitrous oxide supply disruptions. Practitioners should keep alternative scenarios live as national coverage determination expansions and hybrid operating room adoption curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Neonatal & Preterm Infant Enteral Feeding Devices Market
Medical Devices
Implantable Neurostimulators Market
Medical Devices
Digital Migraine Treatment Device Market
Medical Devices
Global Pessary Market
Medical Devices
Polyethersulfone Dialyzer Market
Medical Devices
High Frequency Ventilators Market
Medical Devices
Cast Removal Devices Market
Medical Devices
Global Medical Device Cleaning Market
Medical Devices
United States Drug Delivery Devices Market
Medical Devices
Lyophilized Injectable Market
Medical Devices
Global Insulin Pumps Market
Medical Devices
Electric Acupuncture Devices Market
Medical Devices
Cranial Stabilization Devices Market
Medical Devices
Leadless Cardiac Pacemaker Market
Medical Devices
Scoliosis Traction Chairs Market
Medical Devices
Intubation Accessories Market