
 Brain Tumor Diagnosis and Treatments Market | 2026-2036
Brain Tumor Diagnosis and Treatments Market Size, Share, and Industry Trends Forecast 2026-2036
Brain Tumor Diagnosis and Treatments Market Outlook
FDA's breakthrough device designation pathway is realigning the cost-of-entry calculus for diagnostic innovators seeking accelerated market access. F. Hoffmann-La Roche Ltd. leverages its companion diagnostic infrastructure to anchor molecular profiling workflows across major oncology networks. Siemens Healthineers AG sustains imaging modality leadership through integrated MRI-PET platforms that dominate neuroradiology departments. GE Healthcare competes on advanced magnetic resonance spectroscopy sequences that differentiate glioma grades non-invasively.
Brain tumor diagnosis and treatments encompass the clinical detection, histopathological classification, and multimodal therapeutic management of primary and metastatic central nervous system neoplasms, utilizing ionizing radiation, alkylating agents, surgical resection, and receptor-targeted small molecules to extend progression-free survival and preserve neurological function. MRI technology leads structural segment share due to superior soft-tissue contrast and functional imaging sequences that guide biopsy planning and treatment response assessment. Targeted therapy represents the fastest-expanding treatment modality as BRAF inhibitors and IDH1 antagonists shift glioma management toward precision oncology protocols. Diagnostic centers occupy concentrated margin pools by bundling molecular pathology with advanced imaging interpretation services.
FDA oversees premarket approval and clinical trial design for novel neuro-oncology therapeutics, while EMA's MDR framework governs in vitro diagnostic conformity for biomarker assays across European member states. WHO classification standards for central nervous system tumors directly shape reimbursement eligibility and clinical protocol adoption in national health systems. Stakeholders must monitor evolving regulatory convergence between FDA and EMA on adaptive trial endpoints for glioblastoma therapeutics.
Market Dynamics
FDA's breakthrough device designation pathway is compressing commercialization timelines for molecular diagnostics, forcing neuro-oncology departments to restructure procurement workflows around accelerated assay validation cycles.
Growth Catalysts
- MDR Framework Harmonization:EMA's Medical Device Regulation creates standardized conformity pathways for biomarker assays across European member states, reducing multi-market registration friction.
- Proton Therapy Infrastructure Expansion:Academic medical centers in Germany, Japan, and the United States are commissioning particle therapy facilities that require integrated diagnostic-treatment protocols.
- Liquid Biopsy Validation:Circulating tumor DNA protocols for glioma monitoring are achieving clinical utility thresholds that expand addressable testing volumes beyond surgical tissue requirements.
Market Restraints
- Isotope Supply Concentration:Molybdenum-99 production for PET radiopharmaceuticals depends on aging research reactors concentrated in Canada and the Netherlands, creating vulnerability to unplanned outages.
- Specialized Neuroradiologist Scarcity:Fellowship-trained interpreters for advanced MRI sequences remain concentrated at tier-one academic centers, limiting diffusion of functional imaging protocols.
- Reimbursement Compression:CMS physician fee schedule adjustments for molecular pathology services are compressing margin pools at independent diagnostic laboratories.
Strategic Opportunities
- Decentralized Molecular Pathology:Community hospital networks in the United States present white-space demand for IDH mutation testing currently concentrated at regional reference laboratories.
- AI-Augmented Image Analysis:Convolutional neural networks for automated glioma segmentation are converging with cloud-based PACS architectures to enable remote diagnostic interpretation.
- Adaptive Trial Endpoint Acceptance:FDA and EMA convergence on progression-free survival metrics for glioblastoma therapeutics creates regulatory tailwind for novel imaging response criteria.
Industry Challenges
- Biomarker Assay Harmonization:Variable IDH mutation detection sensitivity across PCR, sequencing, and immunohistochemistry platforms complicates multi-site clinical trial enrollment.
- Cold Chain Integrity:Tissue specimen transport for central nervous system tumor banking requires specialized courier networks that fragment supply chain reliability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brain Tumor Diagnosis and Treatments Market |
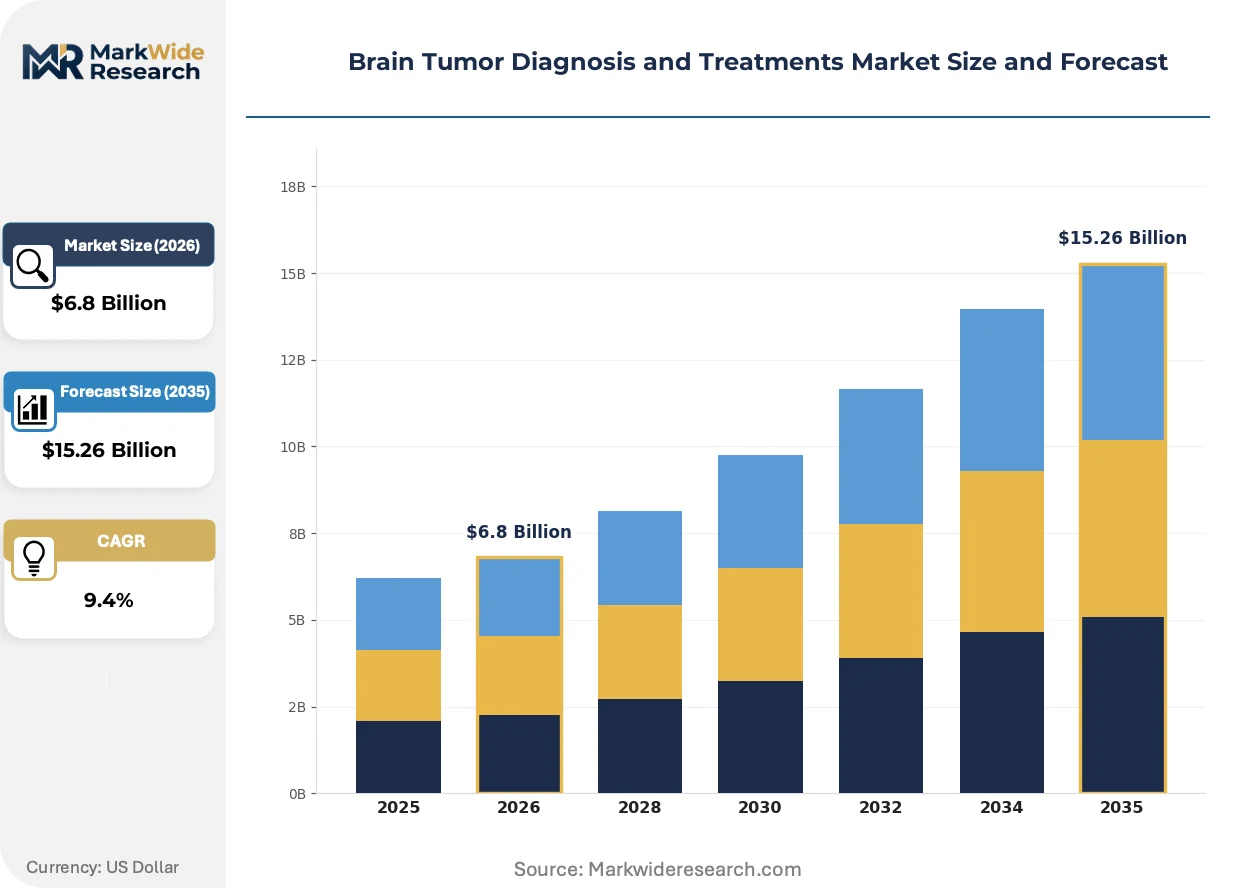
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radiotherapy, Chemotherapy, Surgical Treatment, Targeted Therapy Technology: MRI, CT Scan, PET Scan, Biopsy Techniques End User: Hospitals, Clinics, Research Institutes, Diagnostic Centers Treatment Stage: Diagnosis, Adjuvant Therapy, Palliative Care, Follow-Up |
| Companies Covered | F. Hoffmann-La Roche Ltd., Novartis AG, Merck & Co., Inc., Pfizer Inc., AstraZeneca PLC, Bristol-Myers Squibb Company, GE Healthcare, Siemens Healthineers AG, Elekta AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brain Tumor Diagnosis and Treatments Market Strategic Shifts
Multiparametric MRI protocols are displacing invasive biopsy procedures as the definitive diagnostic standard for certain glioma subtypes, compressing the traditional diagnostic pathway timeline.
Hyperpolarized carbon-13 MRI is electrifying metabolic imaging capabilities by enabling real-time visualization of pyruvate-to-lactate conversion in tumor tissue. Neuroradiology departments at Massachusetts General Hospital and University of California San Francisco are deploying this technology for treatment response assessment. This metabolic imaging modality is electrifying the competitive positioning of academic medical centers seeking to differentiate their neuro-oncology programs.
EMA's MDR framework is mandating clinical evidence requirements for in vitro diagnostic devices that exceed previous CE marking standards. European reference laboratories are consolidating supplier relationships to reduce conformity assessment burden. Germany's national reimbursement authority is adjusting pathology fee schedules to accommodate enhanced documentation requirements.
Centralized tumor board models are displacing institution-specific treatment planning across major oncology networks. University hospital systems are acquiring community practice imaging volumes to feed multidisciplinary case review workflows. This concentration pattern is most visible in the United States, where NCI-designated cancer centers are extending telemedicine tumor board services to affiliate community hospitals.
Brain Tumor Diagnosis and Treatments Market Segmentation
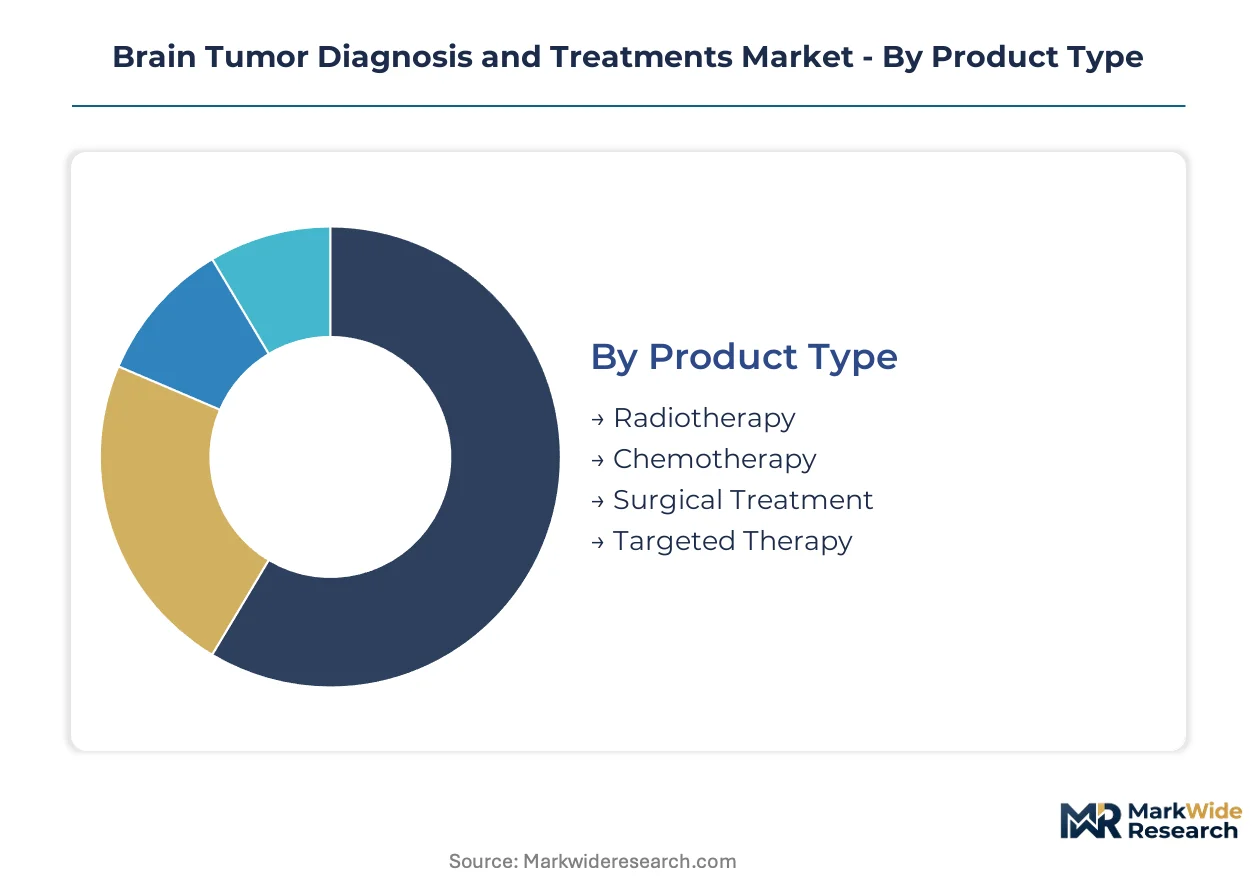
Brain tumor diagnosis and treatments fragment across therapeutic modality, imaging technology, care setting, and clinical stage. Each segmentation axis reveals distinct procurement patterns and margin structures that shape vendor strategy and facility investment priorities.
Product Type:
Treatment modalities span standalone surgical intervention through systemically integrated pharmacological regimens, with varying degrees of embedding within multidisciplinary care pathways.
- Radiotherapy:External beam and stereotactic radiosurgery systems deliver ionizing radiation with millimeter precision to spare healthy neural tissue. Demand clusters at proton therapy centers in Germany, Japan, and the United States where particle accelerator infrastructure justifies capital-intensive equipment procurement.
- Targeted Therapy:Small-molecule inhibitors targeting BRAF mutations and IDH1 alterations enable molecularly stratified treatment selection. Academic medical centers in Boston and Heidelberg anchor adoption curves for companion diagnostic-linked prescribing protocols.
- Chemotherapy:Alkylating agents including temozolomide remain backbone therapy for glioblastoma multiforme across community and tertiary settings.
- Surgical Treatment:Resection with intraoperative MRI guidance and fluorescence-guided techniques dominates curative-intent management at specialized neurosurgical centers.
Volume placements concentrate in surgical treatment and radiotherapy; the faster expansion belongs to targeted therapy.
Technology:
Diagnostic platforms stratify by spatial resolution requirements, metabolic sensitivity, and invasiveness trade-offs that shape neuroradiology department capital allocation.
- MRI:Multiparametric sequences including diffusion-weighted imaging and perfusion mapping deliver superior soft-tissue contrast for glioma grading without ionizing radiation. Massachusetts General Hospital and University of California San Francisco deploy advanced 7 Tesla systems for research-clinical translation.
- Biopsy Techniques:Stereotactic needle biopsy with frameless navigation systems provides histopathological confirmation when imaging remains inconclusive. Tissue acquisition volumes are climbing fastest at European reference laboratories consolidating molecular pathology workflows under EMA MDR conformity requirements.
- CT Scan:Computed tomography serves emergency triage and bone involvement assessment with rapid acquisition protocols.
- PET Scan:Radiolabeled amino acid tracers differentiate tumor recurrence from radiation necrosis in post-treatment surveillance.
Capital deployment tilts toward MRI platforms; biopsy technique volumes are climbing fastest amid molecular diagnostic expansion.
End User:
Care delivery settings fragment by case complexity, reimbursement intensity, and integration with multidisciplinary tumor board infrastructure.
- Hospitals:Tertiary academic medical centers command comprehensive service lines spanning diagnosis through salvage therapy. NCI-designated cancer centers in the United States extend telemedicine tumor board services to affiliate networks, consolidating referral patterns.
- Diagnostic Centers:Independent imaging facilities and molecular pathology laboratories capture concentrated margin pools by bundling advanced interpretation with rapid turnaround. Germany's national reimbursement authority is adjusting pathology fee schedules to accommodate enhanced documentation burdens.
- Clinics:Community oncology practices manage stable patients and treatment monitoring with limited interventional capability.
- Research Institutes:Preclinical and translational facilities drive biomarker discovery and adaptive trial endpoint validation.
Procedure volumes aggregate at hospitals; diagnostic centers are gaining share fastest through molecular pathology bundling.
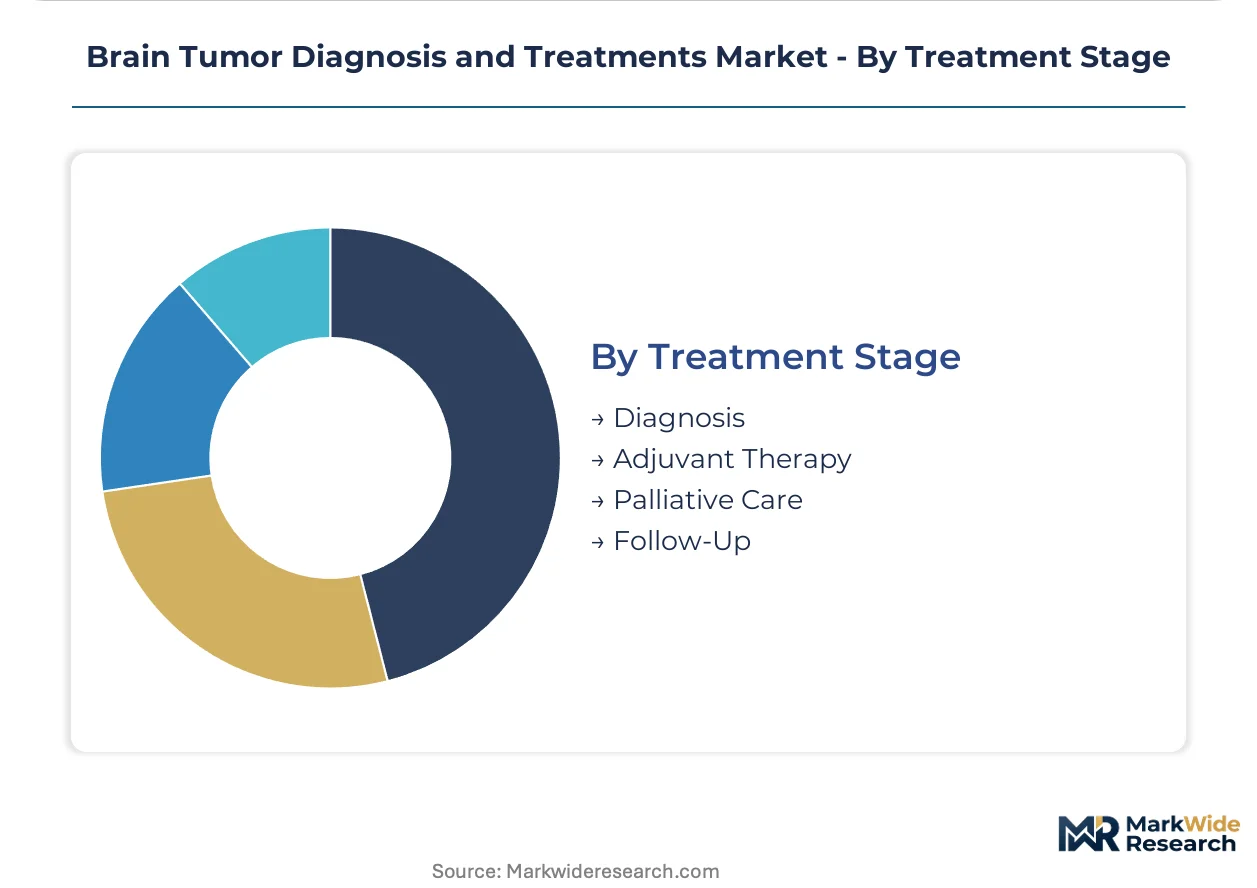
Treatment Stage:
Clinical phases sequence from detection through surveillance, with varying technology intensity and reimbursement profiles across the care continuum.
- Diagnosis:Multiparametric MRI protocols and molecular profiling establish histological classification and actionable mutation status. WHO classification standards directly shape reimbursement eligibility and protocol adoption in national health systems.
- Follow-Up:Surveillance imaging with advanced MRI sequences monitors treatment response and detects recurrence. Liquid biopsy protocols for circulating tumor DNA are achieving clinical utility thresholds that expand testing beyond surgical tissue requirements.
- Adjuvant Therapy:Post-resection chemoradiation protocols reduce recurrence risk in high-grade gliomas.
- Palliative Care:Symptom-focused interventions prioritize neurological function preservation and quality of life endpoints.
Resource intensity peaks at diagnosis; follow-up stage volumes are expanding most quickly through minimally invasive monitoring adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones for biomedical innovation in Singapore and Shenzhen concentrate proton therapy infrastructure investment. Germany's MedTech clusters anchor European molecular diagnostics capacity. Japanese metropolitan hospital networks drive adoption of advanced MRI sequences.
United States
NCI-designated cancer centers in Boston and San Francisco deploy 7 Tesla MRI systems for glioma research translation. FDA breakthrough device designation accelerates commercial timelines for novel biomarker assays. Massachusetts General Hospital anchors hyperpolarized carbon-13 MRI adoption for metabolic tumor imaging.
Germany
Heidelberg University Hospital commissions particle therapy facilities requiring integrated diagnostic protocols. EMA's MDR framework mandates enhanced clinical evidence for in vitro diagnostic conformity. Bavarian reference laboratories consolidate supplier relationships under heightened documentation requirements.
Japan
PMDA fast-track approval pathways compress market entry timelines for companion diagnostics. METI funding targets proton therapy infrastructure expansion at academic medical centers. Tokyo metropolitan hospital networks lead diffusion of functional MRI sequences for treatment response assessment.
United Kingdom
NHS England centralized procurement consolidates molecular pathology service contracts. MHRA post-Brexit regulatory autonomy enables accelerated approval for innovative neuro-oncology devices. London cancer center networks extend telemedicine tumor board services to affiliate community hospitals.
China
NMPA priority review channels expedite registration for imported MRI platforms. National reimbursement catalog expansion includes advanced imaging sequences for glioma diagnosis. Yangtze River Delta hospital systems invest in integrated molecular pathology workflows.
Brain Tumor Diagnosis and Treatments Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across diagnostic imaging and therapeutic modalities. The vendor base stratifies into three tiers: integrated healthcare conglomerates with companion diagnostic infrastructure, imaging modality specialists with MRI-PET platform leadership, and radiotherapy equipment manufacturers with proton therapy expertise. Dominant competitive moves include strategic partnerships between pharmaceutical and diagnostic developers, plus geographic expansion of reference laboratory networks into community hospital systems.
Among Swiss-based healthcare conglomerates, F. Hoffmann-La Roche Ltd. exemplifies the integrated diagnostic-therapeutic archetype through companion diagnostic infrastructure anchoring molecular profiling workflows. German imaging specialists Siemens Healthineers AG and Elekta AB occupy positions at the modality-specific end of the competitive spectrum, with the former representing integrated MRI-PET platform leadership and the latter exemplifying radiotherapy equipment concentration. These three entities collectively illustrate the structural segmentation between pharmaceutical-diagnostic convergence and standalone device manufacturing.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd. |
| Novartis AG |
| Merck & Co., Inc. |
| Pfizer Inc. |
| AstraZeneca PLC |
| Bristol-Myers Squibb Company |
| GE Healthcare |
| Siemens Healthineers AG |
| Elekta AB |
| Others |
Value Chain & Pricing Dynamics
Molybdenum-99 isotope procurement costs cascade through PET radiopharmaceutical production tiers, concentrating pricing power with Canadian and Dutch reactor operators while compressing margins at downstream molecular pathology laboratories facing CMS reimbursement adjustments.
Pricing Analysis
Lead-time premiums for expedited IDH mutation testing separate academic medical center contracts from community hospital spot pricing. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—CAP-accredited laboratories command 15-20% markups over non-accredited competitors. Price erosion runs through independent diagnostic laboratories as bundled imaging-pathology contracts concentrate volume at NCI-designated cancer centers. Community oncology practices exhibit highest price sensitivity due to limited reimbursement capture, while proton therapy centers absorb premium pricing for integrated diagnostic protocols.
Supply Chain Analysis
Fellowship-trained neuroradiologist scarcity in the United States, Germany, and Japan constrains advanced MRI sequence deployment regardless of equipment availability. Hyperpolarized carbon-13 substrate production draws from specialized polarizer manufacturing concentrated in Massachusetts and California. Cold chain integrity for tissue specimen transport rests on specialized courier networks fragmenting supply chain reliability. Distribution runs through consolidated reference laboratory networks extending into community hospital systems, with single-source vulnerability in isotope reactor dependency creating structural risk exposure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EMA's MDR framework erects a compliance moat that rewards laboratories with pre-positioned conformity infrastructure, penalizing late adopters with accelerated supplier consolidation requirements.
For Market Incumbents: Deploy companion diagnostic infrastructure as the anchor lever for molecular profiling workflow lock-in. Siemens Healthineers AG and GE Healthcare should deepen MRI-PET platform integration to defend against AI-augmented image analysis entrants. Roche's vertical integration of IDH testing with targeted therapy prescribing creates switching costs that community hospital networks cannot easily replicate. Counter the threat of decentralized molecular pathology by accelerating cloud-based PACS architecture partnerships. For New Entrants and Emerging Players: Community hospital networks in the United States represent the most penetrable buyer archetype currently underserved by regional reference laboratory concentration. AI-augmented glioma segmentation software vendors should target German diagnostic centers facing EMA MDR documentation burdens as white-space entry points. Liquid biopsy platform developers can exploit reimbursement compression at independent laboratories through SaaS-based remote interpretation models. Position around rapid turnaround guarantees that bundled service incumbents cannot match. For Investors and Strategic Acquirers: FDA breakthrough device designation awards for glioma biomarker assays are the leading indicator that molecular diagnostic consolidation windows are narrowing. Five-to-ten year viability favors laboratories with integrated imaging-pathology workflows over standalone modality players. Acquisition targets should display CAP accreditation, established courier networks, and existing pharmaceutical companion diagnostic partnerships. Monitor PMDA fast-track approvals in Japan as signal for Asia-Pacific expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EMA MDR conformity accelerates European reference laboratory consolidation under enhanced clinical evidence requirements. |
| Hospital System Partnership | NCI-designated cancer centers extend telemedicine tumor board services to affiliate networks, capturing referral volume. |
| Software Companion Development | Convolutional neural networks for automated glioma segmentation converge with cloud-based PACS architectures. |
| Reimbursement Strategy | Germany's national pathology fee schedule adjustments accommodate enhanced EMA MDR documentation burdens. |
| Regulatory Approval Pathway | FDA breakthrough device designation compresses commercialization timelines for novel biomarker assays. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with neuroradiologists, molecular pathologists, hospital procurement committees, and GPO contracts managers. FDA 510(k) submissions, EMA MDR technical documentation, ClinicalTrials.gov glioblastoma trial records, and CMS Medicare reimbursement databases provided validation benchmarks. Bottom-up procedure volume estimates across diagnosis, treatment, and surveillance stages triangulated against top-down market size reconstruction.
Data-stream reconciliation across imaging modality deployment, therapeutic protocol adoption, and molecular testing volume generated consistent outputs over the projection horizon. Segmentation modeling incorporated product type, technology platform, end-user setting, and treatment stage dimensions. CAGRs derived from fitted growth curves applied to procedure volume trajectories, with proton therapy infrastructure buildout schedules and liquid biopsy clinical validation timelines serving as industry-specific forecast inputs.
Revisions become necessary when FDA-EMA regulatory convergence on adaptive trial endpoints accelerates, isotope reactor outages disrupt PET radiopharmaceutical supply, or AI-augmented diagnosis achieves reimbursement parity with specialist interpretation. Material deviation in these named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
UAE Neurology Devices Market
Neurology
Mild Cognitive Impairment Market
Neurology
Chordoma Disease Market
Neurology
Middle-East and Africa Neurology Monitoring Market
Neurology
Cognitive Neuroscience Market
Neurology
Spasticity Treatment Market
Neurology
Neurology Devices Market
Neurology
Transverse Myelitis Treatment Market
Neurology
Spinal Laminoplasty Market
Neurology
Brazil Neurology Devices Market
Neurology
Ulnar Nerve Treatment Market
Neurology
Global Lambert-Eaton Myasthenic Syndrome Treatment Market
Neurology
Canada Neurology Devices Market
Neurology
3D Neuroscience Market
Neurology
North America Neurology Devices Market
Neurology
India Neurology Devices Market