
 Global Ceramic Balls Market | 2026-2036
Global Ceramic Balls Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ceramic Balls Market Foresight
China is narrowing its reliance on imported ceramic ball supply through expanded domestic sintering capacity. Saint-Gobain leverages integrated alumina mining and precision finishing operations across multiple continents. CoorsTek, Inc. anchors North American supply for semiconductor-grade zirconia spheres. SKF competes through captive bearing assembly channels that internalize ceramic ball consumption.
Ceramic balls are dense, inert spheres engineered from silicon nitride, alumina, or zirconia through isostatic pressing and high-temperature sintering, typically achieving hardness values exceeding 1,500 HV and corrosion resistance beyond steel equivalents. They function primarily as rolling elements in high-speed bearings, valve seats, and grinding media where thermal stability and low friction prove critical. Alumina ceramic balls occupy the largest volume share due to mature supply chains and cost efficiency in grinding applications. Silicon nitride variants command premium positioning in aerospace components and precision instruments where fatigue resistance under centrifugal load determines component life. Zirconia balls represent the fastest-growing product category as electronics assemblers adopt them for wire bonding capillaries and dental milling spindles.
FDA scrutiny of implantable medical devices and EPA emissions rules for ceramic firing kilns are elevating batch traceability and clean-energy process requirements across suppliers. ECHA REACH restrictions on raw material impurities constrain European sourcing flexibility while China's GB standards enforce tighter dimensional tolerances for export-grade silicon nitride. Japan's METI promotes domestic ceramic powder refinement under industrial competitiveness frameworks. Stakeholders must monitor evolving cross-border material certification reciprocity and assess captive powder production against outsourced supply reliability.
Market Dynamics
Precision bearing demand from aerospace fabrication clusters is compressing lead times and forcing ceramic ball suppliers to co-locate finishing operations near final assembly sites rather than centralized powder production centers.
Growth Catalysts
- EPA emissions rules:Kiln modernization mandates in the United States are accelerating clean-firing technology adoption among domestic sintering facilities, expanding addressable supply capacity.
- Silicon nitride fatigue resistance:Aerospace OEMs specify ceramic balls for high-speed spindle applications where centrifugal load tolerance determines component replacement cycles.
- Germany:Advanced manufacturing clusters concentrate procurement from REACH-compliant suppliers, creating premium-grade demand pull for batch-traceable alumina spheres.
Market Restraints
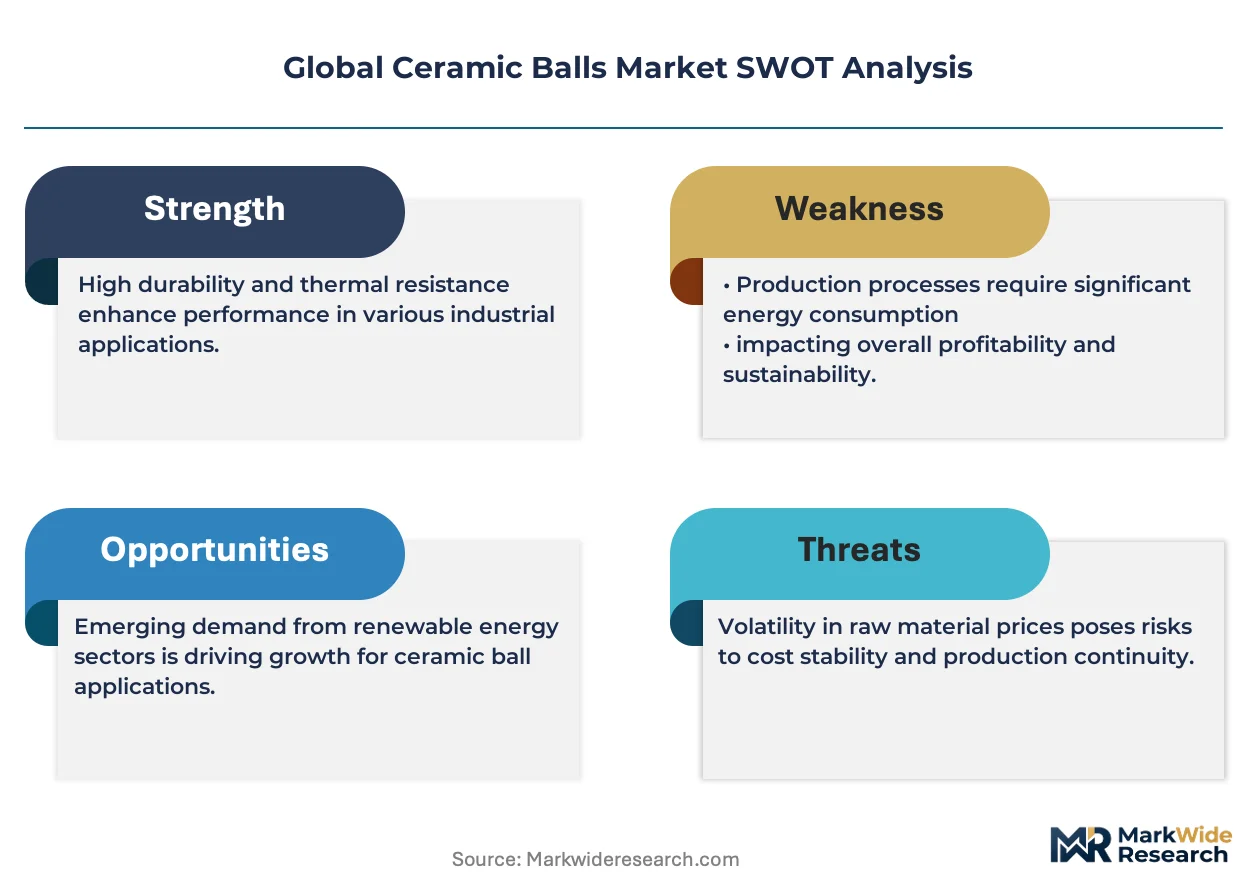
- High-purity alumina feedstock volatility:Mining concentration in select bauxite belts exposes sintering operations to input cost swings and geopolitical supply friction.
- ECHA REACH substance restrictions:Raw material impurity limits constrain European sourcing flexibility and extend qualification timelines for new powder suppliers.
- Steel bearing substitutes:Conventional metal rolling elements retain cost advantage in ambient-temperature, moderate-speed applications where thermal stability offers marginal benefit.
Strategic Opportunities
- India:Domestic semiconductor packaging expansion under PLI scheme incentives creates virgin demand for zirconia wire bonding capillaries.
- ISO 13485 medical device certification:FDA scrutiny of implantable orthopedics opens premium positioning for biocompatible ceramic ball suppliers with batch-level traceability systems.
- Additive manufacturing convergence:Ceramic matrix composite printing is hybridizing with precision finishing to enable near-net-shape sphere production with reduced material waste.
Industry Challenges
- Isostatic pressing technician scarcity:Specialized powder compaction expertise concentrates in aging workforce pools across Japanese and German industrial centers.
- MEE dual carbon compliance:China's clean-energy transition mandates for ceramic firing operations require capital-intensive kiln retrofitting with compressed implementation windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ceramic Balls Market |
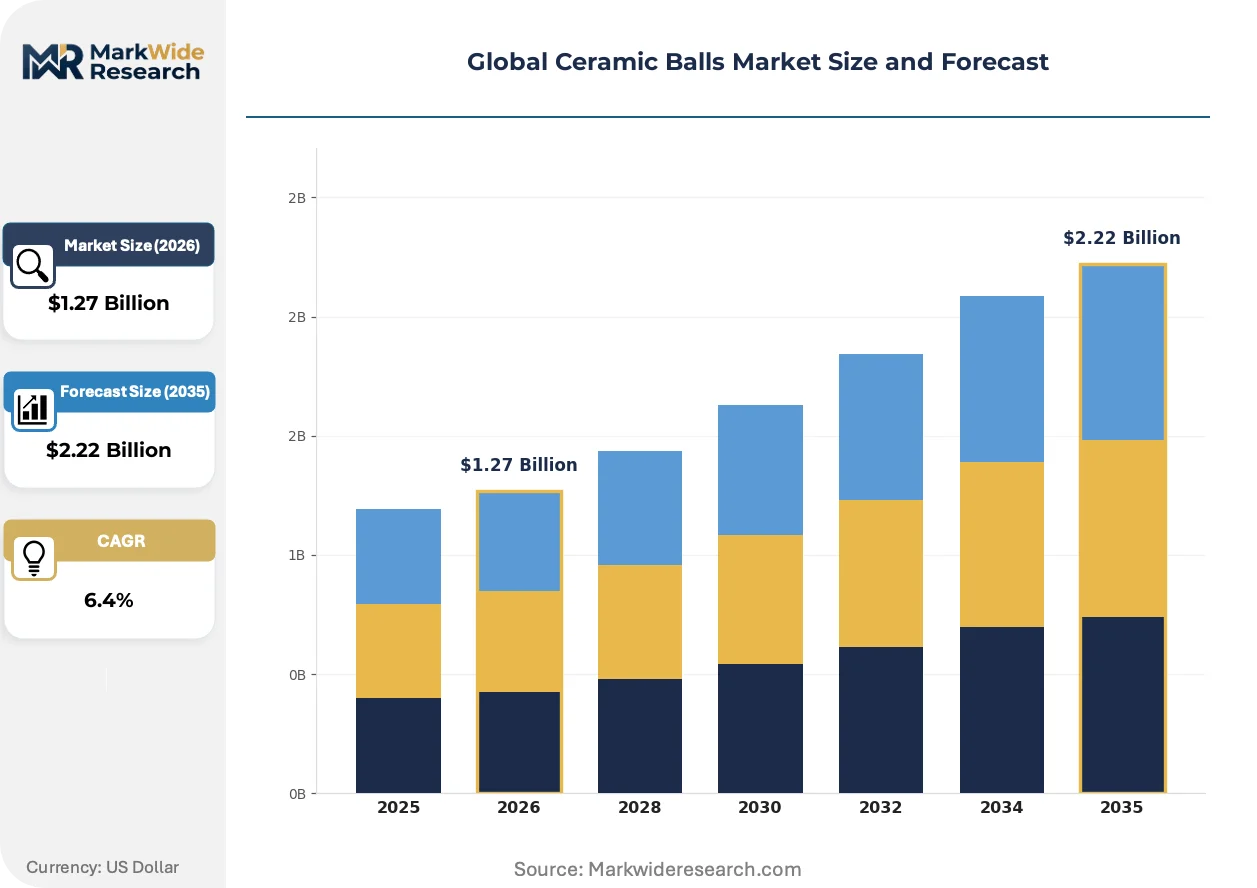
| Market Size in 2026 | $1.27 Billion |
| Market Size in 2035 | $2.22 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicon Nitride, Zirconia, Alumina, Glass Ceramic, Titanium Diboride Application: Bearings, Electronics, Medical Devices, Aerospace Components, Precision Instruments End User Industry: Manufacturing, Medical Equipment Suppliers, Aerospace Fabricators, Electronics Assemblers, Machinery OEMs Distribution Channel: Direct Sales, Distributors, Online Platforms, Industrial Supply Stores, Specialized Dealers |
| Companies Covered | Saint-Gobain, CoorsTek, Inc., SKF, Axens, Toshiba Materials Co., Ltd., Honeywell International Inc., Industrial Tectonics Inc., Devson Catalyst Pvt. Ltd., KYOCERA Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ceramic Balls Market Shifts & Advancements
Material science advances and regulatory precision requirements are compressing traditional manufacturing timelines while opening new specification tiers that reward suppliers with captive powder refinement and in-house metrology capabilities.
Silicon nitride ceramic balls function as rolling elements in high-speed bearings where thermal stability and low friction prove critical. Aerospace OEMs and precision instrument manufacturers specify these components for spindle applications operating under extreme centrifugal loads. The technology is hybridizing sintering processes with advanced surface finishing to enable sub-micron dimensional tolerances previously unattainable through conventional grinding alone.
REACH substance restrictions from ECHA constrain raw material impurity thresholds for ceramic powder imports into European manufacturing zones. Industrial consequence includes extended supplier qualification timelines and elevated batch documentation requirements across the value chain. Semiconductor-grade zirconia ball producers serving Dutch and German electronics clusters are responding by integrating captive alumina refining to secure supply chain autonomy.
Certificate-driven procurement now dominates medical device and aerospace verticals where ISO 13485 and AS9100 documentation determine vendor eligibility. Distributor networks with legacy inventory models face displacement from direct mill relationships that offer lot-level traceability and compressed qualification support. This pattern concentrates most visibly in Swiss and German precision manufacturing corridors where end-users consolidate supplier panels to reduce audit burden.
Global Ceramic Balls Market Segmentation
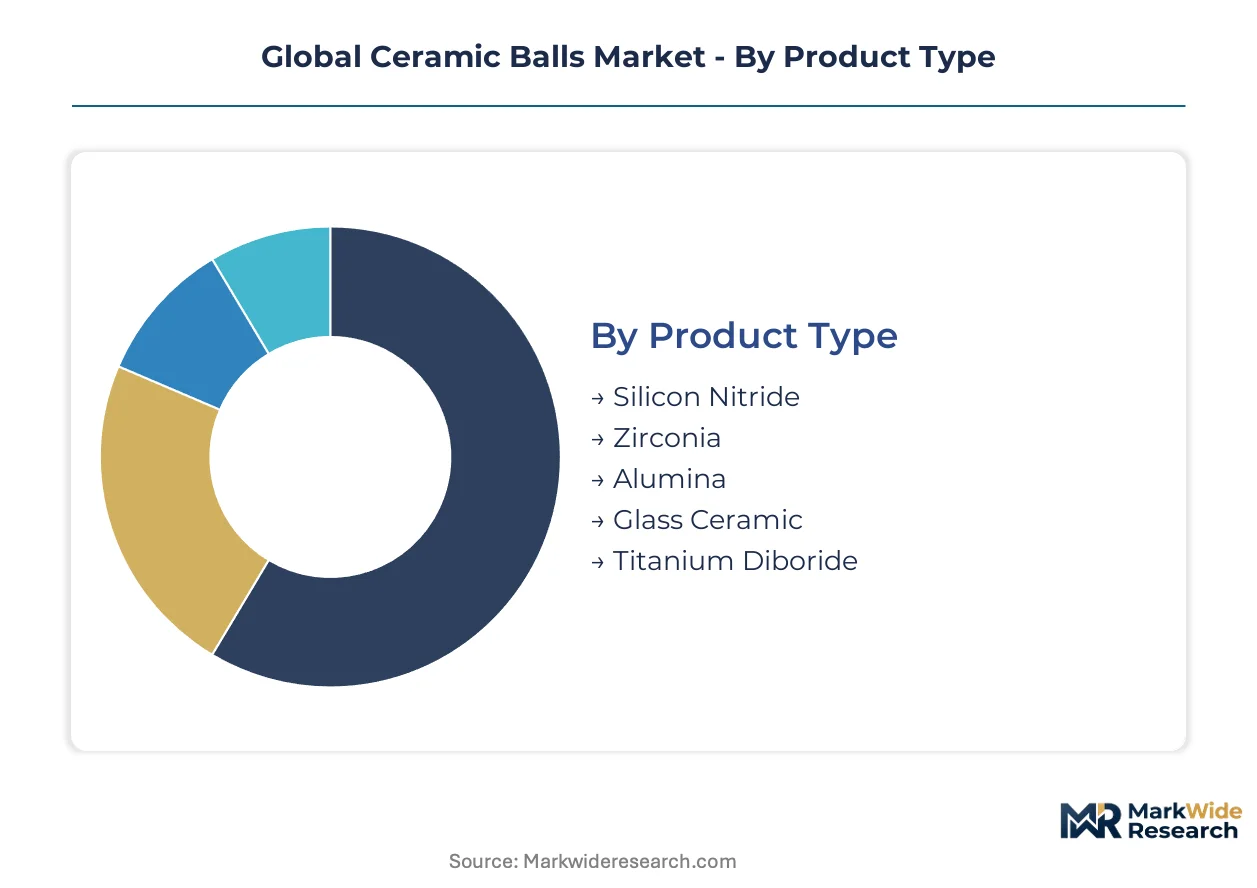
Ceramic ball procurement varies sharply by technical specification and end-use criticality. After-sales service intensity—including lot traceability support, failure analysis, and regulatory documentation—separates premium suppliers from commodity distributors across every segment tier.
Product Type:
After-sales intensity peaks with silicon nitride and zirconia grades, where aerospace and medical OEMs demand batch-level failure analysis and accelerated replacement programs.
- Silicon Nitride:Engineered through gas-pressure sintering to achieve fracture toughness exceeding 6 MPa·m½ and thermal shock resistance above 800°C. Aerospace fabricators in Germany and Japan specify these for high-speed spindle bearings where centrifugal load tolerance determines component replacement cycles. REACH-compliant powder sourcing and AS9100 documentation requirements elevate supplier switching costs.
- Zirconia:Partially stabilized with yttria to attain transformation toughening, delivering hardness near 1,200 HV with exceptional surface finish capability. Electronics assemblers in the Netherlands and South Korea adopt these for wire bonding capillaries and dental milling spindles. Captive powder refinement is expanding among suppliers serving semiconductor-grade specifications.
- Alumina:Cost-efficient workhorse for grinding media and valve applications with mature supply chains across China and India.
- Glass Ceramic:Zero thermal expansion coefficient suits precision instrument applications requiring dimensional stability across temperature swings.
- Titanium Diboride:Extreme hardness and electrical conductivity targets specialized molten metal processing and cathode assemblies.
By volume, alumina leads. By growth pace, zirconia is ahead.
Application:
Cost tier stratification separates specification-heavy medical and aerospace applications from price-sensitive industrial grinding uses.
- Bearings:Rolling elements in high-speed spindles where silicon nitride's low density and thermal stability reduce centrifugal stress and lubrication requirements. SKF and NSK internalize ceramic ball consumption through captive bearing assembly channels. Precision finishing operations are co-locating near final assembly sites in Germany and Japan to compress lead times.
- Electronics:Wire bonding capillaries, probe pins, and milling spindles demand sub-micron dimensional tolerances and surface finishes below 10 nm Ra. Zirconia variants dominate as semiconductor packaging expands in India under PLI scheme incentives.
- Medical Devices:Orthopedic implants and surgical instruments require ISO 13485 certification with batch-level traceability systems. FDA scrutiny of implantable devices elevates documentation burdens.
- Aerospace Components:Landing gear and engine systems specify ceramic balls for extreme temperature cycling and corrosion resistance.
- Precision Instruments:Metrology equipment and optical systems leverage thermal stability for measurement repeatability.
By installed base, bearings dominate. By specification intensity, medical devices command premium positioning.
End User Industry:
Customer type determines procurement rhythm, with machinery OEMs running long-term supply agreements and medical equipment suppliers demanding just-in-time delivery with full regulatory dossiers.
- Manufacturing:Grinding media consumption in mineral processing and chemical synthesis drives volume procurement of standard-grade alumina spheres. Chinese industrial clusters source through distributor networks with limited technical support requirements.
- Medical Equipment Suppliers:Implantable device manufacturers in Switzerland and the United States consolidate supplier panels to reduce audit burden. ISO 13485 and FDA 21 CFR Part 820 compliance determine vendor eligibility.
- Aerospace Fabricators:Precision bearing integration in airframe and propulsion systems demands AS9100 documentation and direct mill relationships replacing legacy distributor models.
- Electronics Assemblers:Semiconductor packaging and printed circuit board manufacturing specify ceramic components for wire bonding and drilling operations.
- Machinery OEMs:Machine tool and automation equipment builders integrate ceramic bearings for high-speed spindle applications.
By contract value, aerospace fabricators lead. By qualification velocity, electronics assemblers move fastest.
Distribution Channel:
Supply concentration favors direct relationships for specification-critical applications, while commodity grades flow through fragmented distributor networks.
- Direct Sales:Aerospace and medical OEMs bypass intermediaries to secure lot-level traceability, compressed qualification support, and collaborative failure analysis. Saint-Gobain and CoorsTek anchor direct relationships with major fabricators across multiple continents.
- Distributors:Industrial supply houses serve mid-tier manufacturing with standard alumina grades and limited technical documentation. Inventory carrying costs and obsolescence risk pressure margins.
- Online Platforms:Emerging procurement channel for R&D quantities and replacement parts with expedited fulfillment.
- Industrial Supply Stores:Local availability for maintenance-repair-operations purchasing of commodity bearing inserts.
- Specialized Dealers:Regional expertise in precision instrument and dental laboratory supply chains.
By transaction volume, distributors handle the most shipments. By margin capture, direct sales extract premium pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA emissions rules for ceramic firing kilns anchor procurement patterns in the United States, while REACH substance restrictions from ECHA reshape European sourcing flexibility. Japan's METI industrial competitiveness frameworks and China's GB standards enforcement create divergent compliance pathways across major manufacturing clusters.
United States
Precision bearing demand from aerospace fabricators in California and Texas compresses supplier lead times. EPA kiln modernization mandates accelerate clean-firing technology adoption among domestic sintering facilities. CoorsTek anchors North American supply chains from Colorado-based operations serving semiconductor-grade specifications.
Germany
Advanced manufacturing clusters in Bavaria and Baden-Württemberg concentrate procurement of REACH-compliant alumina spheres. ECHA substance restrictions on raw material impurities extend qualification timelines for new powder suppliers. Stuttgart-area precision finishing operations co-locate near final aerospace assembly sites to compress logistics cycles.
Japan
Silicon nitride fatigue resistance specifications from aerospace OEMs drive premium-grade demand. METI promotes domestic ceramic powder refinement under industrial competitiveness frameworks. Nagoya and Osaka industrial corridors host aging pools of isostatic pressing technicians whose expertise concentrates in precision instrument supply chains.
China
Domestic semiconductor packaging expansion narrows reliance on imported ceramic ball supply. MEE dual carbon compliance mandates require capital-intensive kiln retrofitting with compressed implementation windows. Yangtze River Delta sintering capacity expansion targets export-grade silicon nitride dimensional tolerances under tightening GB standards.
India
PLI scheme incentives for semiconductor packaging create virgin demand for zirconia wire bonding capillaries. BIS standards enforcement elevates batch traceability requirements for medical device suppliers. Gujarat and Maharashtra industrial corridors attract precision finishing investment to serve domestic electronics assemblers.
Global Ceramic Balls Market Competitive Landscape
Capability concentration sits with integrated mining-to-finishing specialists; scale advantage sits with diversified materials conglomerates. The vendor base organizes into three tiers: captive powder refiners with in-house metrology, regional sintering specialists serving distributor networks, and precision finishers co-located near aerospace clusters. Dominant competitive moves include backward integration into alumina mining and direct mill relationships displacing legacy distribution.
Among diversified materials conglomerates, Saint-Gobain exemplifies integrated mining and finishing operations across multiple continents. CoorsTek, Inc. anchors premium positioning in North American supply chains. SKF occupies a position within captive consumption models that internalize ceramic ball demand through bearing assembly channels. Toshiba Materials Co., Ltd. and KYOCERA Corporation represent Japanese precision ceramic specialists whose expertise concentrates in high-specification aerospace and electronics applications.
| Leading Market Players |
|---|
| Saint-Gobain |
| CoorsTek, Inc. |
| SKF |
| Axens |
| Toshiba Materials Co., Ltd. |
| Honeywell International Inc. |
| Industrial Tectonics Inc. |
| Devson Catalyst Pvt. Ltd. |
| KYOCERA Corporation |
| Others |
Supply & Pricing Matrix
Single-source dependency on high-purity alumina feedstock from concentrated bauxite mining belts determines both the three-tier pricing structure across premium, standard, and economy levels and the geographic clustering of sintering operations near powder refinement centers. REACH compliance costs and EPA kiln modernization mandates widen price spreads between specification-critical aerospace grades and commodity grinding media.
Pricing Analysis
Price spreads between German precision-grade silicon nitride and Chinese standard alumina spheres reflect certification burden differentials and captive powder refinement investments. Three-tier pricing structure across premium, standard, and economy levels separates AS9100-documented aerospace batches from distributor-grade grinding media. Cost compression in standard alumina tiers intensifies as Chinese sintering capacity expansion feeds oversupply conditions. Medical device OEMs exhibit lowest price sensitivity due to ISO 13485 qualification barriers, while mineral processing operators drive hardest bargain on volume contracts.
Supply Chain Analysis
Extended payment terms from aerospace OEMs in Germany and Japan strain working capital for regional sintering specialists without captive mining operations. Supply concentrates in China, Germany, and Japan, with powder refinement expertise concentrating in aging Japanese technician pools. Raw material flows draw from Australian bauxite, Chinese rare earth processing, and Ukrainian titanium feedstock. Tariff exposure on semiconductor-grade zirconia imports into Dutch electronics clusters elevates supply risk. Distribution runs through direct mill relationships for specification-critical tiers and fragmented industrial supply houses for commodity grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across ceramic ball procurement creates entry niches as aerospace OEMs consolidate supplier panels while medical device manufacturers demand just-in-time delivery with full regulatory dossiers.
For Market Incumbents: Pre-empt emerging zirconia specialists by securing captive alumina refining capacity in Yangtze River Delta clusters before MEE dual carbon compliance deadlines compress implementation windows. Anchor direct mill relationships with Stuttgart-area precision finishing operations to defend against distributor displacement. Invest in isostatic pressing technician apprenticeship pipelines to offset aging workforce concentration in Nagoya industrial corridors.
For New Entrants and Emerging Players: Semiconductor packaging facilities in Gujarat and Maharashtra industrial corridors represent the most penetrable entry point for zirconia wire bonding capillary supply under PLI scheme incentives. Target medical device suppliers in Switzerland consolidating supplier panels to reduce ISO 13485 audit burden. Pursue collaborative failure analysis service bundling to differentiate from legacy distributor technical support limitations.
For Investors and Strategic Acquirers: ECHA REACH substance restrictions on raw material impurities reshape the acquisition landscape toward powder refinement specialists with batch traceability systems already operational. Five-to-ten-year viability favors integrated mining-to-finishing specialists over regional sintering operations exposed to feedstock volatility. Monitor cross-border material certification reciprocity negotiations as inflection indicator for supply chain autonomy premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alumina Mining | Saint-Gobain's captive bauxite sourcing secures supply autonomy against feedstock price swings. |
| Precision Finishing Co-location | CoorsTek's Colorado operations compress lead times for Texas aerospace fabricators. |
| ISO 13485 Certification Investment | Batch traceability systems open premium positioning for orthopedic implant suppliers. |
| Clean-Firing Kiln Retrofit | EPA compliance mandates expand addressable domestic sintering capacity in United States. |
| Direct Mill Relationship Expansion | Lot-level documentation displaces legacy distributor networks in German precision corridors. |
Research Methodology
Initial hypotheses were tested against primary input from ceramic powder refinement specialists, aerospace procurement directors, medical device quality assurance leads, and industrial distributor network managers and refined through secondary validation. Primary fieldwork combined structured interviews with sintering facility operators and precision finishing technicians across German, Japanese, and Chinese industrial clusters. Secondary sources included ECHA REACH substance restriction filings, EPA emissions compliance databases, SEMI semiconductor packaging forecasts, and customs trade data on high-purity alumina flows. Bottom-up volume modeling triangulated against top-down industry spend analysis.
Demand-supply balance framing anchored the analytical framework across the analysis window, modeling ceramic ball consumption by material grade, application criticality, end-use industry procurement rhythm, and regional regulatory cluster. Segmentation dimensions included silicon nitride versus zirconia versus alumina product tiers, bearing versus electronics versus medical device applications, and direct sales versus distributor channel structures. CAGRs derived from regression analysis of historical procurement patterns adjusted for known regulatory implementation timelines. Forecast inputs incorporated semiconductor packaging capacity buildout schedules and aerospace OEM supplier consolidation roadmaps.
Practitioners should monitor ECHA substance restriction expansion, MEE dual carbon enforcement intensity, and cross-border certification reciprocity negotiations for early signals of supply chain reconfiguration. Forecasts reflect assumptions on regulatory implementation pace, feedstock price stability, and technician workforce replacement rates. Macroeconomic contraction in precision manufacturing clusters, abrupt tariff regime shifts, or breakthroughs in additive manufacturing sphere production would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Europe Ceramic Coatings Market
Ceramics
Magnesia Carbon Bricks Market
Ceramics
Pottery Ceramics Market
Ceramics
Boiler Refractory Material Market
Ceramics
Calcite Market
Ceramics
Refractories Market
Ceramics
China Ceramic Market
Ceramics
Egypt Ceramic Tiles Market
Ceramics
Polymer-Derived Ceramics Market
Ceramics
Ceramics Packaging Market
Ceramics
Feldspar and Nepheline Syenite Market
Ceramics
Vaterite Market
Ceramics
Ceramic Injection Molding Market
Ceramics
Barium Carbonate Powder Market
Ceramics
Global Ceramic and Porcelain Tiles Market
Ceramics
Global Wollastonite Powder Market