
 Co-Fired Ceramic Market | 2026-2036
Co-Fired Ceramic Market Size, Share, and Industry Trends Forecast 2026-2036
Co-Fired Ceramic Market Analysis
High-temperature co-fired ceramic (HTCC) specifications are redrawing competitive boundaries as aerospace and defense contractors demand alumina purity above 96 percent. Kyocera Corporation leverages captive powder processing to sustain margin control across substrate tiers. CoorsTek Inc. anchors North American supply through vertically integrated crucible-to-substrate manufacturing. Murata Manufacturing Co., Ltd. differentiates via ultra-thin lamination expertise for RF front-end modules.
Co-fired ceramic denotes a multilayer ceramic structure formed by stacking tape-cast sheets, printing conductive traces with tungsten or molybdenum-manganese pastes, and sintering above 1500°C in a reducing atmosphere to create hermetic, high-density interconnect packages. Substrates dominate product-type value pools because thermal management requirements in gallium nitride amplifiers command premium pricing. Automotive electronics leads application growth as 800V EV architectures multiply ceramic capacitor counts per inverter. Thick-film technology occupies the volume base, though thin-film lines gain share where sub-micron trace resolution serves millimeter-wave circuits.
Japan's METI sets efficiency benchmarks that filter substrate imports through JIS-certified thermal conductivity testing. The EPA and OSHA jointly govern US fabrication facilities, with NESHAP standards pushing kiln emission controls that raise capital barriers for new entrants. REACH registration in Europe constrains tungsten paste formulations, redirecting some OEM qualification work toward alternative metallization. Stakeholders must track how dual-use export classifications from the Bureau of Industry and Security reshape cross-border substrate shipments before committing capacity expansions.
Market Dynamics
Japan's METI energy-efficiency standards for electronic components are tightening material specifications across substrate tiers, forcing manufacturers to recalibrate powder formulations and sintering protocols to maintain qualification access.
Growth Catalysts
- EV Powertrain Electrification:Automotive electronics manufacturers are expanding procurement of multilayer ceramic substrates for 800V inverter architectures. Gallium nitride amplifier thermal management requirements command premium substrate pricing.
- REACH Registration Constraints:European tungsten paste formulation restrictions are redirecting OEM qualification work toward alternative metallization chemistries, creating first-mover advantages for compliant suppliers.
- 5G Infrastructure Deployment:Domestic substrate production in China scales to serve base station rollouts, concentrating demand for high-frequency, low-loss ceramic packages.
Market Restraints
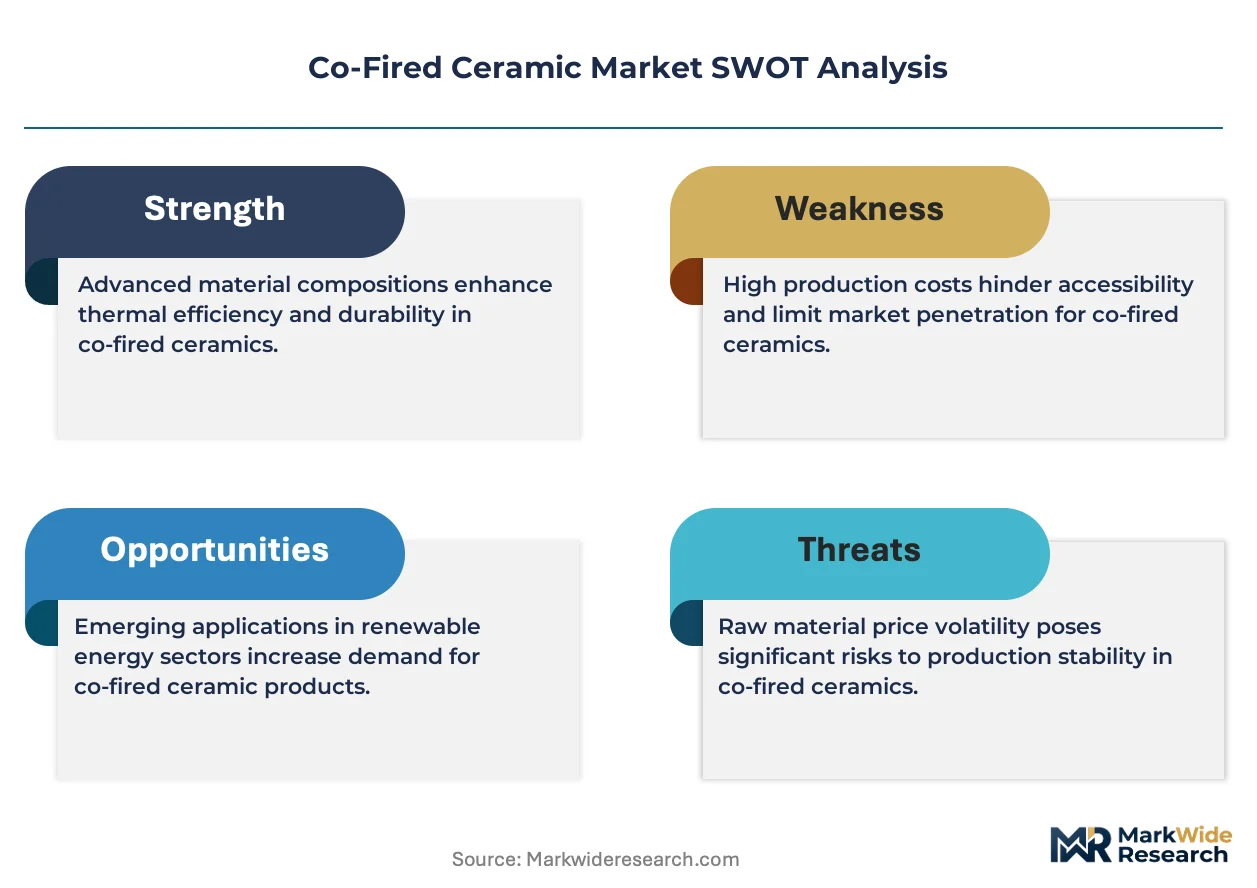
- Raw Material Concentration:High-purity alumina supply concentrates among Japanese and German specialty chemical producers, exposing substrate fabricators to input cost volatility and allocation risk.
- Capital Intensity Barriers:NESHAP-compliant kiln emission controls raise capital barriers for new entrants in US fabrication, consolidating capacity among incumbent operators.
- Technical Substitution Pressure:Organic substrate alternatives advance in lower-frequency RF applications, compressing addressable volume for co-fired ceramics in consumer electronics.
Strategic Opportunities
- Millimeter-Wave Defense Applications:Aerospace and defense contractors demand alumina purity above 96 percent for radar and satellite communications, opening premium substrate tiers.
- Thin-Film Convergence:Sub-micron trace resolution capabilities enable hybrid thick-thin film processes for next-generation RF front-end modules.
- India Electronics Manufacturing:PLI scheme incentives for semiconductor packaging attract substrate qualification programs from multinational OEMs seeking geographic diversification.
Industry Challenges
- Specialized Sintering Expertise Gap:Reducing atmosphere process control and tungsten-molybdenum paste rheology optimization require scarce metallurgical engineering talent.
- Dual-Use Export Classification Complexity:Bureau of Industry and Security substrate shipment controls create compliance overhead and qualification timeline uncertainty for cross-border capacity commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Co-Fired Ceramic Market |
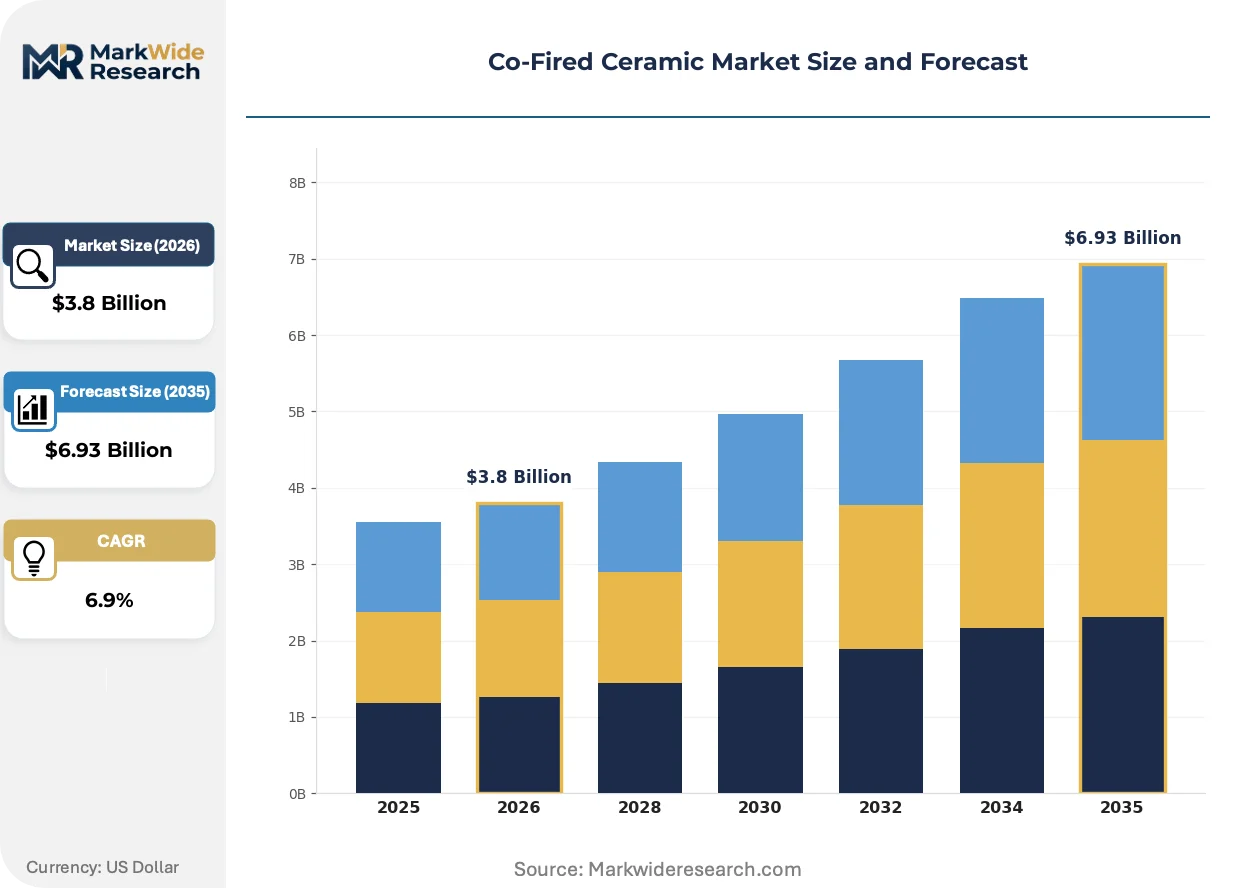
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.93 Billion |
| CAGR (2026 – 2036) | 6.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capacitors, Resistors, Inductors, Substrates Application: Telecommunications, Automotive Electronics, Consumer Devices, Industrial Equipment End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Distributors Technology: Thick Film, Thin Film, Hybrid, Others |
| Companies Covered | Maruwa Co., Ltd., CoorsTek Inc., Kyocera Corporation, KOA Corporation, TDK Corporation, Murata Manufacturing Co., Ltd., CeramTec GmbH, Yokowo Co., Ltd., NGK Spark Plug Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Co-Fired Ceramic Market Emerging Trajectories
Process convergence between ceramic substrate fabrication and semiconductor packaging is compressing development cycles and redefining equipment supplier relationships across the value chain.
Ultra-thin lamination technology is supplanting conventional thick-film stacking in RF front-end module production. Smartphone OEMs and base station manufacturers are accelerating adoption of sub-100-micron ceramic layers for 5G millimeter-wave circuits. This transition is supplanting legacy alumina-titanate formulations with low-temperature co-fired ceramic alternatives that integrate passive components at reduced firing temperatures.
EPA and OSHA joint governance of US fabrication facilities intensifies under NESHAP standards pushing kiln emission controls. Capital expenditure requirements for scrubber systems and continuous monitoring equipment are restructuring facility economics. Smaller North American substrate producers are responding through shared service arrangements for environmental compliance rather than standalone infrastructure investment.
Buyer concentration among automotive Tier-1 electronics suppliers compresses qualification timelines and unbundles after-sales technical support from unit pricing. Korean and German automotive electronics procurement teams now specify dedicated substrate engineering liaison resources as contract requirements. This pattern is most visible in inverter module sourcing for 800V EV platforms where thermal cycling reliability guarantees extend to fifteen-year vehicle lifespans.
Co-Fired Ceramic Market Segmentation
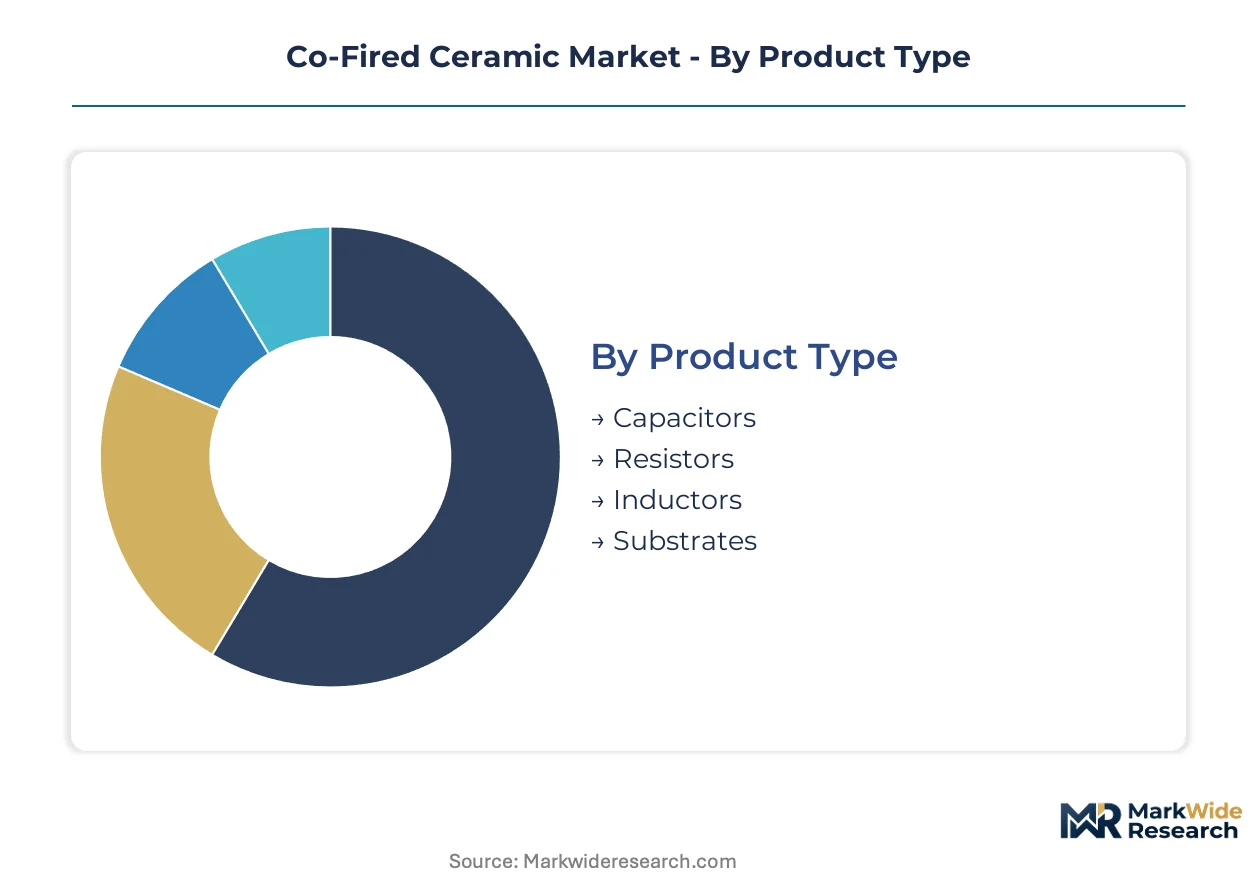
Channel architecture in co-fired ceramics diverges sharply by product complexity. Substrates and RF components flow through direct OEM qualification programs, while passive components reach volume markets via distributor networks with shorter technical validation cycles.
Product Type:
Capacitors and resistors dominate unit volume through electronics distributor channels. Substrates command premium positioning via direct sales teams serving automotive and defense OEMs with embedded application engineering.
- Substrates:Multilayer ceramic interconnect platforms fabricated from alumina or aluminum nitride with tungsten-molybdenum metallization. Automotive inverter procurement for 800V EV architectures in Germany and China concentrates demand for thermally stable packages. Gallium nitride amplifier thermal management requirements sustain premium pricing tiers.
- Capacitors:Dielectric ceramic components formed through tape casting and co-firing with internal electrode structures. 5G base station rollouts across China drive procurement of high-voltage multilayer chip capacitors. METI efficiency standards in Japan filter import access through JIS-certified thermal conductivity testing protocols.
- Resistors:Precision resistive elements printed on ceramic bases for high-temperature stability.
- Inductors:Ferrite-ceramic composite structures for power filtering and RF impedance matching.
By volume, capacitors lead. By growth pace, substrates are expanding most quickly.
Application:
Cost tier stratification separates qualification-intensive automotive programs from high-volume consumer electronics procurement. Defense and telecommunications applications occupy premium pricing bands with extended technical validation timelines.
- Automotive Electronics:Powertrain inverter modules, onboard chargers, and DC-DC converters for electrified vehicles. Korean and German Tier-1 suppliers specify dedicated substrate engineering liaison resources as contract requirements. Thermal cycling reliability guarantees now extend to fifteen-year vehicle lifespans under procurement terms.
- Telecommunications:5G base station RF front-ends, satellite communications, and millimeter-wave infrastructure. China's domestic substrate production scales to serve base station rollouts with high-frequency, low-loss ceramic packages. Ultra-thin lamination below 100 microns displaces legacy alumina-titanate formulations.
- Consumer Devices:Smartphones, wearables, and portable electronics with constrained thermal budgets.
- Industrial Equipment:Motor drives, power supplies, and automation systems requiring hermetic packaging.
Automotive electronics generates the steepest margin expansion. Telecommunications offers the deepest volume base.
End User:
Customer type determines contract structure and technical support bundling. OEM direct relationships unbundle engineering services from unit pricing, while aftermarket channels compete on availability and lead time compression.
- OEMs:Original equipment manufacturers in automotive, aerospace, and telecommunications with captive qualification laboratories. Boeing and Lockheed Martin specify alumina purity above 96 percent for radar and satellite communications substrates. Dual-use export classifications from the Bureau of Industry and Security create compliance overhead for cross-border shipments.
- Tier-1 Suppliers:Bosch, Denso, and Continental procure ceramic substrates for inverter module integration. Korean automotive electronics procurement teams compress qualification timelines to match EV platform launch schedules. Technical support requirements now include resident engineering at manufacturing sites.
- Aftermarket Providers:Independent distributors and repair networks serving replacement demand.
- Distributors:Arrow, Avnet, and regional specialists managing inventory for passive component volume.
Tier-1 suppliers command the tightest technical integration. OEMs retain the highest pricing authority.
Technology:
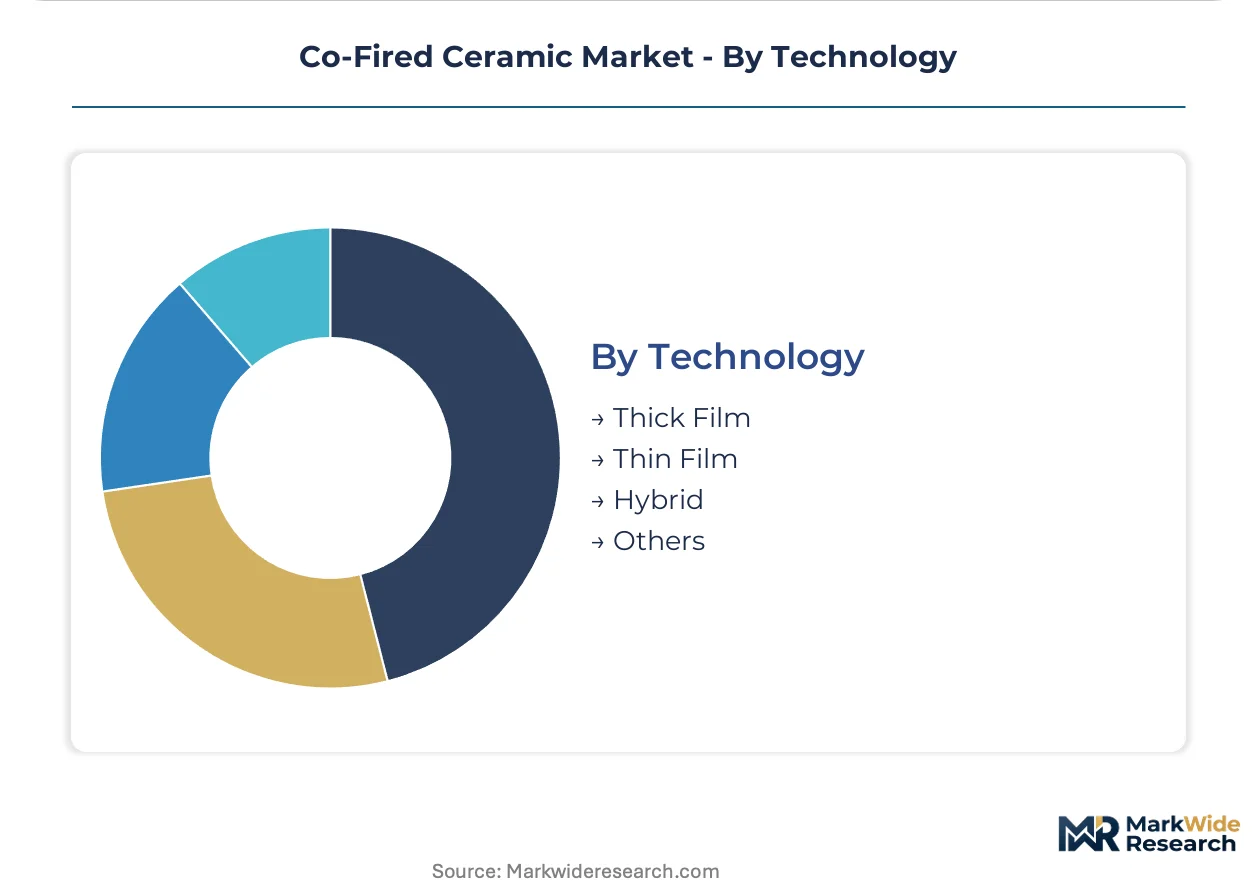
Maturity gradients separate established thick-film volume production from emerging thin-film capability investments. Hybrid processes capture intermediate applications requiring both cost efficiency and trace resolution.
- Thick Film:Screen-printed conductive pastes on ceramic substrates with 10-20 micron line resolution. Dominates cost-sensitive power electronics and automotive sensor packages. Murata Manufacturing leverages ultra-thin lamination expertise to extend thick-film economics into RF front-end modules.
- Thin Film:Photolithographic patterning achieving sub-micron trace resolution for millimeter-wave circuits. Aerospace and defense contractors in the United States demand thin-film capability for radar frequency synthesis. Capital intensity for sputtering and electroplating equipment restricts supplier base.
- Hybrid:Combined thick-film power handling with thin-film signal routing on unified ceramic platforms.
- Others:Emerging direct-write and additive manufacturing approaches for prototyping and low-volume defense programs.
Thick film holds volume dominance. Thin film is climbing the fastest as 5G millimeter-wave deployment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese substrate fabricators export multilayer ceramic packages to German automotive Tier-1 suppliers and Chinese telecommunications OEMs, establishing the dominant trade-flow corridor in this market.
United States
Aerospace and defense contractors in Arizona and California drive demand for high-purity alumina substrates above 96 percent. EPA NESHAP standards govern kiln emissions at fabrication facilities, raising capital barriers for new entrants. CoorsTek Inc. anchors North American supply through vertically integrated manufacturing from crucible production through finished substrates.
Germany
Automotive electronics procurement teams at Bosch and Continental specify ceramic substrates for 800V EV inverter architectures. ECHA REACH registration constrains tungsten paste formulations, redirecting qualification work toward alternative metallization. Bavarian industrial clusters around Munich concentrate precision ceramics expertise serving powertrain electrification programs.
Japan
Murata Manufacturing Co., Ltd. and Kyocera Corporation leverage ultra-thin lamination expertise for RF front-end modules in 5G base stations. METI energy-efficiency standards tighten material specifications through JIS-certified thermal conductivity testing. Kansai region fabrication facilities sustain captive powder processing to control margins across substrate tiers.
China
Domestic substrate production scales to serve MIIT-directed 5G infrastructure rollouts with high-frequency, low-loss ceramic packages. GB standards govern electronic component quality certification for base station procurement. Yangtze River Delta manufacturing clusters in Jiangsu and Shanghai concentrate multilayer ceramic capacity for telecommunications OEMs.
South Korea
Automotive electronics procurement teams at Hyundai Mobis and LG Innotek compress qualification timelines to match EV platform launch schedules. MFDS chemical registration requirements influence paste formulation selections for local production. Seoul Capital Area fabrication facilities specialize in thermal cycling reliability guarantees extending to fifteen-year vehicle lifespans.
Co-Fired Ceramic Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity and technology licensing dimensions. The vendor base concentrates among Japanese and German conglomerates with captive materials processing, while mid-scale fabricators compete on application engineering for specific end-use verticals. Three archetypes dominate: vertically integrated conglomerates controlling powder-to-substrate value chains, thin-film specialists commanding premium RF positioning, and regional champions serving automotive qualification programs. Competitive moves center on capacity expansion for EV powertrain substrates and strategic partnerships for millimeter-wave defense applications.
Within the conglomerate tier, Kyocera Corporation and TDK Corporation represent integrated manufacturing archetypes with in-house powder processing capabilities. CoorsTek Inc. anchors North American positioning through captive supply chain control. Murata Manufacturing Co., Ltd. exemplifies the thin-film specialist archetype for RF front-end applications. CeramTec GmbH occupies a position bridging European automotive and industrial equipment demand. Maruwa Co., Ltd. and Yokowo Co., Ltd. sit within the Japanese specialist cluster serving telecommunications and sensor packaging segments.
| Leading Market Players |
|---|
| Maruwa Co., Ltd. |
| CoorsTek Inc. |
| Kyocera Corporation |
| KOA Corporation |
| TDK Corporation |
| Murata Manufacturing Co., Ltd. |
| CeramTec GmbH |
| Yokowo Co., Ltd. |
| NGK Spark Plug Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Ninety-day alumina powder inventory cycles concentrate purchasing leverage among Japanese and German specialty chemical producers, tethering substrate fabricator margins to upstream allocation decisions while amplifying price volatility transmission into multilayer ceramic package quotations.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure with three-tier pricing differentiation across premium, standard, and economy levels. Price differentiation rests on JIS-certified thermal conductivity grades and volume scale commitments from automotive Tier-1 suppliers. Cost compression in standard-tier substrates is intensifying because Korean procurement teams unbundle after-sales technical support from unit pricing. Aftermarket distributors exhibit the highest price sensitivity, while aerospace contractors demonstrate the lowest due to fifteen-year reliability guarantees.
Supply Chain Analysis
Forty-five-day tungsten-molybdenum paste lead times expose fabricators to single-source vulnerability when Japanese metallization suppliers allocate capacity toward semiconductor targets. Geographic supply concentration centers on Japan, Germany, and China for high-purity alumina, tungsten paste formulations, and tape-casting equipment respectively. The supply chain draws from captive powder processing, specialty refractory metals, and precision lamination machinery as critical inputs. Distribution runs through direct OEM qualification programs for substrates and distributor networks for passive components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Co-fired ceramics occupy an early-cycle expansion trajectory as 800V EV architectures multiply ceramic capacitor counts per inverter and 5G millimeter-wave deployment accelerates substrate qualification programs.
For Market Incumbents: Shield margin structures by deepening backward integration into alumina powder processing and securing JIS-certified thermal conductivity testing capabilities before METI standards tighten further. Prioritize resident engineering deployments at Korean and German automotive Tier-1 manufacturing sites to compress qualification timelines and lock out alternative substrate technologies.
For New Entrants and Emerging Players: Lead with thin-film sputtering capability for millimeter-wave defense applications where aerospace contractors demand sub-micron trace resolution and incumbent capacity remains constrained. Target India's PLI scheme incentives for semiconductor packaging qualification programs, positioning hybrid thick-thin film processes as the technical wedge for RF front-end module sourcing.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across thin-film equipment lines as sputtering and electroplating infrastructure requirements restrict supplier bases. Five-to-ten year viability favors acquisition targets with captive powder processing and established automotive qualification records. Watch Bureau of Industry and Security dual-use export classification announcements as the inflection signal for cross-border capacity commitment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alumina Powder Processing | Kyocera's captive supply control sustains margin defense across substrate tiers against input volatility. |
| Thin-Film Sputtering Capacity Expansion | Sub-micron trace resolution captures millimeter-wave defense procurement from Arizona and California contractors. |
| JIS Thermal Conductivity Certification Investment | METI compliance gates filter import access and concentrate qualification leverage among certified fabricators. |
| Resident Engineering Deployment at Tier-1 Sites | Korean automotive procurement teams now specify dedicated liaison resources as contract requirements. |
| India PLI Scheme Qualification Program | Geographic diversification incentives attract multinational OEM substrate sourcing away from concentrated Asian supply. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of SEC filings, customs trade records, and METI regulatory bulletins through structured interviews with substrate fabrication plant managers, automotive Tier-1 procurement leads, aerospace defense contractor engineers, and ceramics R&D directors. Bottom-up demand modeling from EV inverter content per vehicle and 5G base station substrate counts triangulates against top-down value chain analysis of alumina powder through finished package production.
Segmentation dimensions modeled include product type, application vertical, end-user category, and technology maturity tier across the projection horizon. CAGRs derive from unit economics analysis of gallium nitride amplifier thermal management requirements and automotive electrification content trajectories, cross-referenced with capacity expansion announcements from Japanese and German conglomerates.
The analysis sits within stated boundaries; outcomes outside sustained 800V EV platform rollout velocity and MIIT-directed 5G infrastructure deployment schedules would require recalibration. Forecasts reflect assumptions regarding tungsten paste REACH registration compliance timelines and NESHAP kiln emission control capital expenditure patterns. Revision becomes warranted when Bureau of Industry and Security dual-use export classification thresholds cross actionable levels for cross-border substrate shipments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Asia-Pacific Ceramic Tiles Market
Ceramics
ME K-Feldspar Market
Ceramics
Wollastonite Market
Ceramics
Liquid Sodium Silicate Market
Ceramics
Egypt Ceramic Tiles Market
Ceramics
Southeast Asia Melamine Market
Ceramics
Industrial Ceramics Market
Ceramics
Cerium Carbonate Market
Ceramics
Sodium Aluminum Silicate Market
Ceramics
Refractory Material Market
Ceramics
China Ceramic Tiles Market
Ceramics
Ceramic and Natural Stone Tiles Market
Ceramics
Calcined Kaolin Market
Ceramics
Potassium Silicate Market
Ceramics
Refractories Market
Ceramics
Ceramic Binders Market