
 North America Battery Market | 2026-2036
North America Battery Market Size, Share, and Industry Trends Forecast 2026-2036
North America Battery Market Outlook
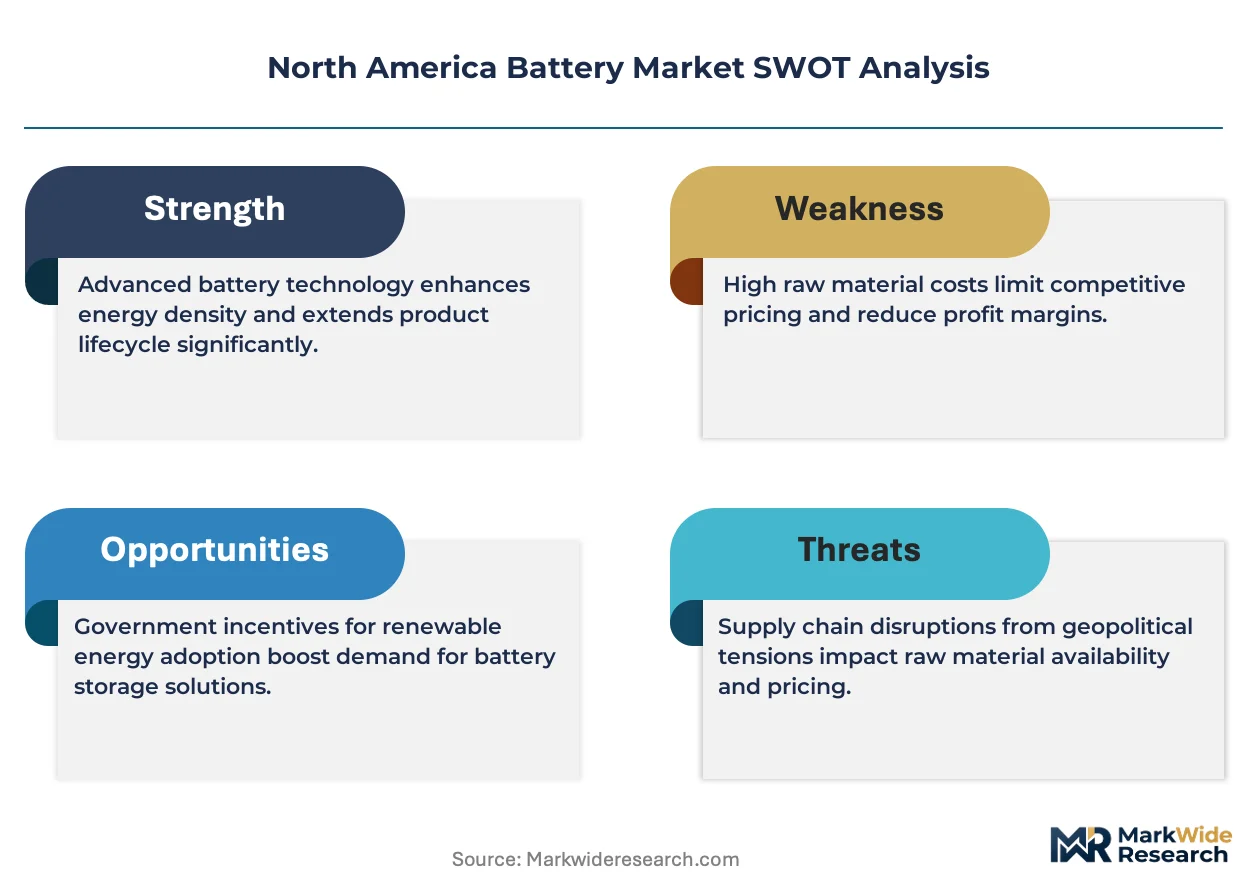
Multi-source cathode procurement is decoupling from legacy single-source cobalt dependence across the North America battery supply base. Tesla Inc. leverages vertical integration into lithium refining and cell production to control cost structures. LG Energy Solution anchors its Michigan and Arizona operations with dedicated capacity for US automotive OEMs. Panasonic Corporation sustains technology leadership through high-nickel cylindrical cell formats at its Kansas facility.
A battery is an electrochemical device storing and releasing energy through reversible redox reactions between electrodes separated by an electrolyte, with energy density typically measured in watt-hours per kilogram and cycle life defining commercial viability. Its primary purpose is to provide portable or stationary power for transportation, electronics, and grid stabilization. Lithium-ion chemistry dominates value capture due to superior energy density and declining cost curves, while solid-state formats represent the fastest-growing technology segment as manufacturers resolve ceramic electrolyte manufacturing yields. Lead-acid technology occupies mature industrial and automotive starting applications where cost sensitivity outweighs performance requirements.
The US Inflation Reduction Act and EPA vehicle emissions standards tighten domestic content thresholds and accelerate zero-emission fleet transitions, directly conditioning cell factory location decisions and qualification timelines. NHTSA safety protocols and UL certification requirements govern thermal runaway containment and system-level validation for automotive and stationary deployments. Stakeholders must monitor how IRA credit phase-out schedules and state-level utility interconnection standards reshape project economics across the renewable energy storage segment.
Market Dynamics
US Inflation Reduction Act domestic content thresholds are forcing battery manufacturers to reconfigure supply chains around North American-sourced critical minerals and electrode materials.
Growth Catalysts
- IRA Manufacturing Tax Credits:The Inflation Reduction Act's Section 45X advanced manufacturing credit covers electrode active materials and cell production, drawing capital to Michigan and Tennessee corridors.
- Zero-Emission Fleet Mandates:California's Advanced Clean Trucks regulation and EPA vehicle emissions standards compel commercial logistics operators to electrify heavy-duty vehicle fleets.
- Solid-State Electrolyte Maturation:Ceramic electrolyte manufacturing yield improvements are accelerating pilot production timelines for next-generation cells with enhanced energy density.
Market Restraints
- Lithium Carbonate Volatility:Concentrated South American brine and Australian spodumene supply exposes North American cell producers to input cost swings that compress margin structures.
- Cathode Precursor Import Dependence:Limited domestic nickel sulfate and cobalt hydroxide refining capacity forces reliance on Asian intermediate suppliers, creating qualification bottlenecks.
- Thermal Runaway Engineering Constraints:NHTSA safety protocols mandate complex cell-to-pack thermal management systems that extend development cycles and raise system-level costs.
Strategic Opportunities
- Grid-Scale Storage Underpenetration:Texas and California ISO interconnection queues show massive backlogs of solar-plus-storage projects awaiting utility approval, representing latent demand for multi-hour duration systems.
- Battery-as-a-Service Models:Commercial fleet operators are adopting pay-per-mile or lease structures that transfer residual value risk from vehicle purchasers to cell manufacturers or financial intermediaries.
- Recycling Feedstock Integration:Emerging pyrometallurgical and direct recycling infrastructure in Nevada and Ohio creates closed-loop material recovery pathways that satisfy IRA domestic content requirements.
Industry Challenges
- Electrochemical Engineering Talent Scarcity:Cell design and manufacturing process engineering roles outpace supply from North American university programs, forcing competitive compensation wars.
- UL 9540A Certification Timelines:Thermal runaway propagation testing for utility-scale battery energy storage systems extends qualification schedules by 12-18 months, delaying project revenue recognition.
- Legacy Automotive Integration Complexity:Established OEMs face friction retrofitting century-old assembly architectures around skateboard battery platforms and wireless battery management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Battery Market |
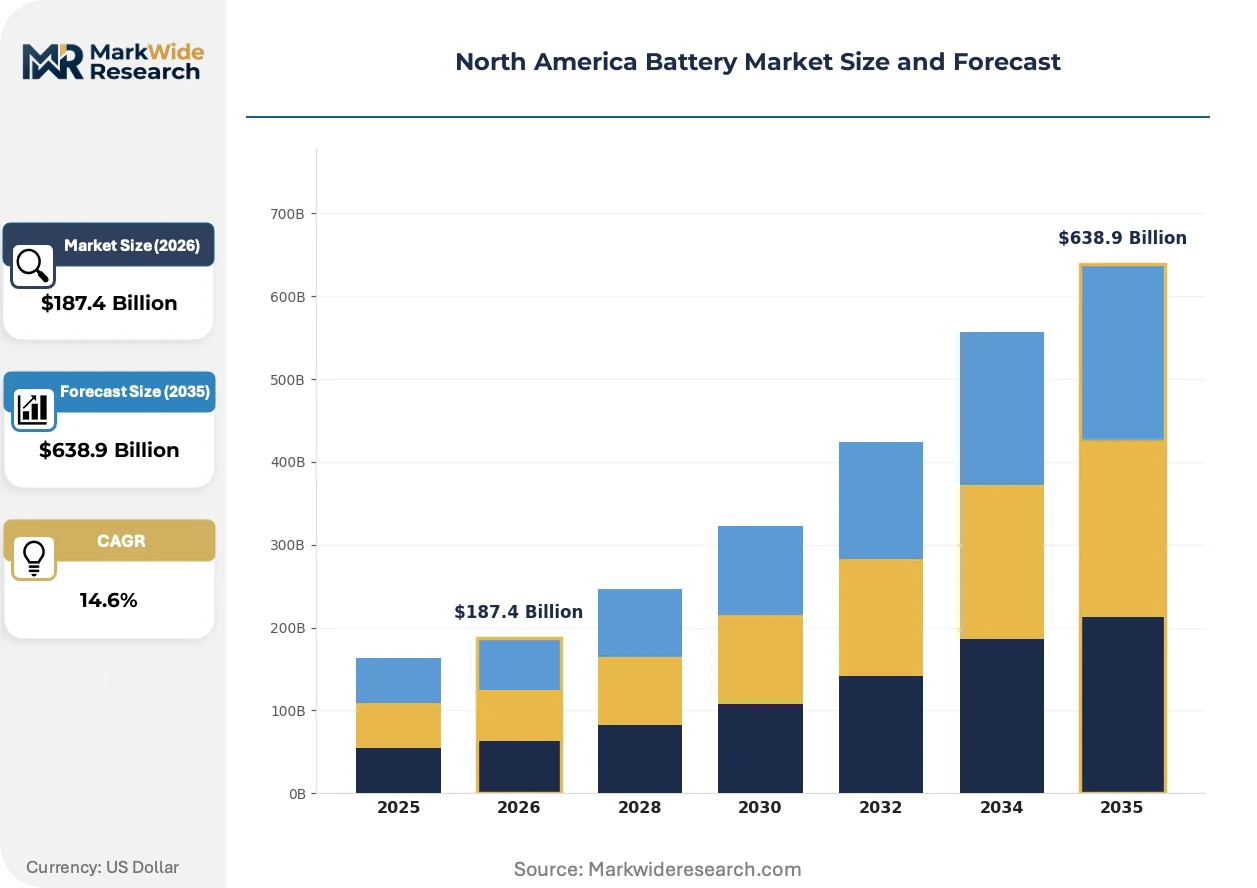
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $638.9 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Nickel-metal Hydride, Lead-acid, Solid-state Application: Electric Vehicles, Consumer Electronics, Renewable Energy Storage, Industrial Machinery Technology: Portable, Stationary, Grid-scale, Hybrid End User: Aerospace, Automotive, Telecommunication, Healthcare |
| Companies Covered | Tesla Inc., LG Energy Solution, Panasonic Corporation, EnerSys, East Penn Manufacturing Co., A123 Systems LLC, Exide Technologies, Johnson Controls International plc, Samsung SDI Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Battery Market Strategic Shifts
Silicon-anode chemistries and dry electrode coating processes are compressing manufacturing energy intensity while pushing energy density boundaries for automotive applications.
Solid-state battery architectures with sulfide and oxide electrolyte systems are electrifying next-generation electric vehicle platforms. Automotive OEMs in Michigan and Tennessee manufacturing corridors are locking in offtake agreements for pilot volumes. This technology is compressing conventional liquid electrolyte cell qualification timelines as incumbents accelerate roadmap investments.
The Inflation Reduction Act's foreign entity of concern provisions are tightening mineral sourcing traceability requirements. Cell producers must document supply chain provenance through blockchain-enabled tracking systems to secure tax credit eligibility. Battery manufacturing investments in Arizona and Kansas are accelerating to meet 2024-2025 domestic content phase-in thresholds.
Fleet procurement teams are consolidating supplier relationships around vertically integrated cell producers capable of guaranteeing IRA-compliant material flows. Direct OEM-to-miner offtake agreements are displacing traditional trading house intermediaries in lithium and nickel markets. This concentration is most visible among commercial vehicle operators in California and Texas seeking long-term price stability.
North America Battery Market Segmentation
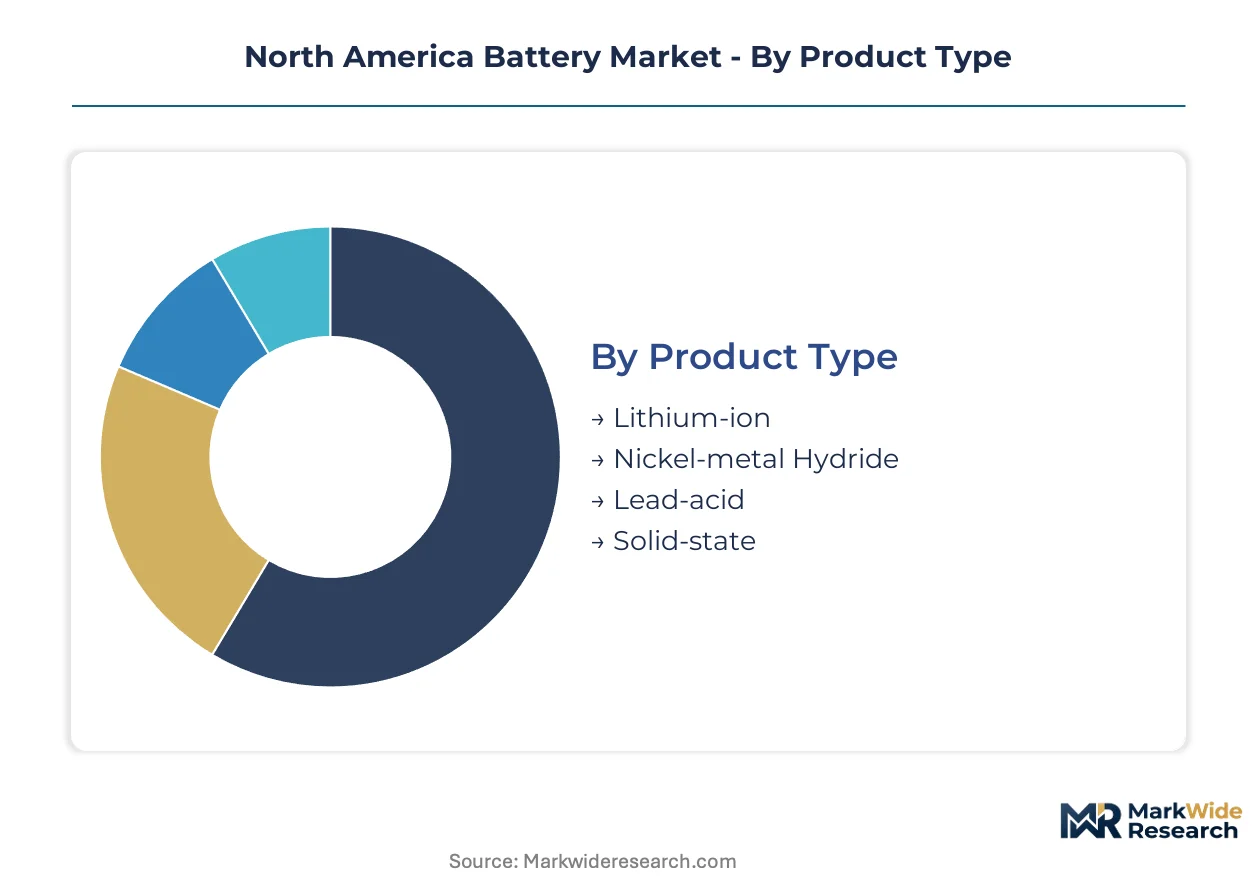
Segmentation in the North America Battery Market reveals how chemistry choices, deployment scale, and end-use requirements reshape procurement patterns. Manufacturers configure production lines around specific voltage windows and cycle-life specifications that match customer operating profiles. Understanding these divides clarifies where IRA domestic content credits concentrate and which technology platforms attract capital investment.
Product Type:
Integration depth varies sharply across chemistries, with some formats designed for standalone swap-out replacement and others engineered as embedded subsystems sealed within larger assemblies.
- Lithium-ion:Intercalation chemistry using graphite anodes and layered oxide cathodes delivers 250-300 Wh/kg energy density. Demand concentrates in Michigan and Tennessee automotive corridors where IRA manufacturing credits support cell-to-pack integration for electric vehicle platforms. NHTSA thermal runaway protocols extend qualification timelines but lock in long-term supply agreements.
- Solid-state:Ceramic or sulfide electrolyte architectures eliminate flammable liquid components while enabling lithium-metal anodes. Pilot production in Arizona and Kansas targets premium automotive applications where energy density thresholds justify unit cost premiums. Manufacturing yield improvements are compressing commercialization timelines.
- Nickel-metal Hydride:Mature hybrid electric vehicle chemistry retains cost advantages in power-assist applications. Toyota and Honda continue sourcing for legacy hybrid platforms.
- Lead-acid:Flooded and absorbed glass mat formats dominate automotive starting-lighting-ignition functions. Industrial backup power in Texas and California data centers sustains volume.
Lithium-ion leads volumes today; solid-state is gaining share fastest.
Application:
Cost tier segmentation separates capital-intensive long-duration assets from high-volume consumer goods with compressed replacement cycles.
- Electric Vehicles:Battery electric and plug-in hybrid platforms require 60-100 kWh packs with 8-year cycle life warranties. California's Advanced Clean Trucks regulation and EPA vehicle emissions standards compel fleet electrification among commercial logistics operators. IRA Section 45X credits offset cell factory capital intensity.
- Renewable Energy Storage:Solar-plus-storage and standalone grid assets demand 4-8 hour discharge duration with daily cycling tolerance. Texas and California ISO interconnection queues show massive project backlogs awaiting utility approval. UL 9540A thermal runaway propagation testing extends qualification schedules.
- Consumer Electronics:Smartphone and laptop applications prioritize volumetric energy density and form factor flexibility. Supply chains source cylindrical and pouch formats from established Asian producers.
- Industrial Machinery:Forklifts, mining equipment, and material handling systems convert from lead-acid to lithium-ion for opportunity charging. Warehouse operators in Tennessee and Ohio manufacturing corridors drive replacement demand.
Electric vehicles anchor revenue concentration; renewable energy storage is expanding most quickly.
Technology:
Volume segmentation distinguishes mass-produced mobile units from fixed infrastructure requiring site-specific engineering and civil works.
- Grid-scale:Containerized megawatt-hour systems integrate power conversion, thermal management, and fire suppression for utility interconnection. ERCOT and CAISO market participation rules shape dispatch optimization software requirements. IRA standalone storage credits improve project returns.
- Portable:Handheld power tools, medical devices, and recreational applications leverage standardized cylindrical formats. Milwaukee and DeWalt battery platforms create ecosystem lock-in through proprietary form factors.
- Stationary:Commercial and industrial behind-the-meter systems provide peak shaving and backup power. C&I customers in California and New York navigate state-specific incentive structures.
- Hybrid:Dual chemistry architectures combine high-power and high-energy cells for pulsed duty cycles. Military and aerospace specifications drive niche development.
Grid-scale dominates capital deployment; portable maintains shipment volume leadership.
End User:
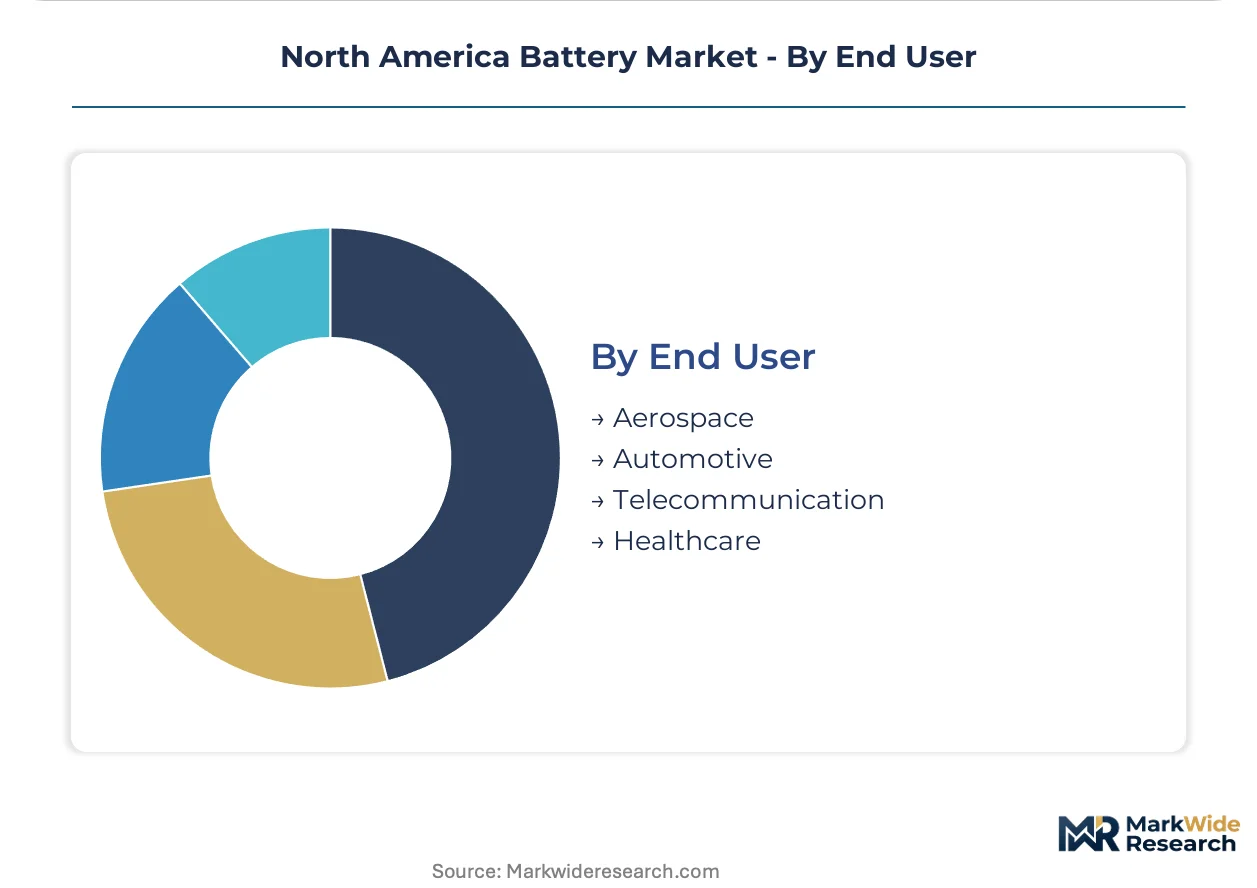
Customer type segmentation separates regulated safety-critical applications from price-sensitive commercial procurement.
- Automotive:OEM qualification protocols demand 3-5 year validation cycles including abuse testing and thermal propagation containment. Detroit Three and Tesla Inc. lock in multi-year offtake agreements with Michigan and Arizona cell producers. NHTSA safety protocols govern pack-level crashworthiness.
- Healthcare:Implantable and portable medical devices require FDA 510(k) clearance with biocompatibility and electromagnetic compatibility validation. Boston Scientific and Medtronic source from dedicated medical battery lines.
- Aerospace:FAA certification for lithium-ion in aircraft systems mandates rigorous thermal runaway containment. Boeing and Airbus qualification timelines extend 5-7 years.
- Telecommunication:5G base station backup power and rural broadband infrastructure sustain lead-acid and lithium-ion demand. Tower operators prioritize total cost of ownership over upfront capital.
Automotive leads absolute consumption; healthcare shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Michigan and Tennessee manufacturing corridors concentrate North American cell production capacity, with IRA Section 45X credits conditioning investment location decisions across the United States, Canada, and Mexico.
United States
Electric vehicle fleet electrification at commercial logistics operators drives procurement volume. EPA vehicle emissions standards and California's Advanced Clean Trucks regulation tighten zero-emission mandates. Arizona and Kansas cell factories accelerate production ramps to meet 2024-2025 domestic content phase-in thresholds.
Canada
Critical mineral extraction in Quebec and Ontario underpins cathode precursor supply strategies. Federal critical minerals strategy aligns with IRA foreign entity of concern provisions to secure North American battery supply chains. British Columbia recycling infrastructure develops closed-loop material recovery pathways.
Mexico
Automotive OEM assembly integration creates demand for cell-to-pack module supply. USMCA trade rules and IRA domestic content requirements shape cross-border component qualification protocols. Baja California and Nuevo León industrial zones attract electrode material processing investments.
North America Battery Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue solid-state electrolyte commercialization and recycling feedstock integration. Market structure concentrates around vertically integrated automotive suppliers and dedicated cell producers serving industrial and stationary applications. Three archetypes dominate: captive automotive cell producers, independent Tier 1 suppliers, and industrial battery specialists. Competitive moves center on backward integration into lithium refining and multi-year offtake agreements with mining operators.
Among US-based producers, Tesla Inc. and EnerSys anchor distinct competitive positions. Tesla Inc. exemplifies the captive automotive archetype through upstream control over refining and cell production. EnerSys occupies the industrial specialist tier serving motive power and energy systems. LG Energy Solution and Panasonic Corporation represent Asia-headquartered producers with substantial North American manufacturing footprints.
| Leading Market Players |
|---|
| Tesla Inc. |
| LG Energy Solution |
| Panasonic Corporation |
| EnerSys |
| East Penn Manufacturing Co. |
| A123 Systems LLC |
| Exide Technologies |
| Johnson Controls International plc |
| Samsung SDI Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Lithium carbonate spot volatility feeds through cathode precursor costs to compress margin structures across automotive and stationary storage tiers. IRA domestic content thresholds force producers to absorb qualification premiums for North American-sourced nickel sulfate and cobalt hydroxide, creating pricing stratification between compliant and non-compliant supply lanes.
Pricing Analysis
Input-cost pass-through from South American brine and Australian spodumene concentrates governs cell pricing dynamics. Contract-based long-term offtake agreements dominate automotive procurement, with price differentiation anchored in UL certification grade and volume scale commitments. Cost compression in standard lithium-ion packs is intensifying as Chinese producers expand cylindrical cell exports. Commercial fleet operators exhibit highest price sensitivity due to total cost of ownership calculations, while aerospace and medical device buyers tolerate premiums for abuse-tested formats.
Supply Chain Analysis
IRA Section 45X and foreign entity of concern provisions are reshaping sourcing protocols around documented North American mineral provenance. Cathode active material production draws from Chinese, South Korean, and Japanese precursor refiners, with limited domestic nickel sulfate capacity creating single-source vulnerability for Michigan and Tennessee cell factories. Lithium spodumene concentrates, cobalt hydroxide intermediates, and ceramic electrolyte precursors constitute critical input dependencies. Distribution runs through dedicated automotive Tier 1 integrators and direct OEM offtake structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on silicon-anode yield improvements and solid-state premium tier capture. Dry electrode coating adoption compresses manufacturing energy intensity while enabling higher energy density pricing.
For Market Incumbents: Anticipate solid-state pilot production timelines accelerating competitive pressure on liquid electrolyte roadmaps. Lock in multi-year lithium offtake agreements to defend against feedstock volatility. Prioritize UL 9540A certification investment for utility-scale storage qualification. Backward integration into Nevada and Quebec recycling infrastructure secures IRA-compliant material loops.
For New Entrants and Emerging Players: Solid-state electrolyte manufacturing yield improvements offer a technology-first wedge into premium automotive platforms. Grid-scale storage in Texas and California ISO backlogs represents the most penetrable white-space target. Battery-as-a-Service commercial fleet structures provide a capital-light go-to-market angle bypassing upfront pack purchase barriers.
For Investors and Strategic Acquirers: Consolidation pressure builds where IRA credit phase-out schedules intersect with stranded asset risk in non-compliant capacity. Five-to-ten year viability favors vertically integrated producers with captive lithium refining and cathode precursor supply. Acquisition target archetype: mid-cap cell producers with qualified automotive pipelines and underutilized Arizona or Kansas manufacturing footprints. Watch NHTSA thermal runaway protocol amendments as inflection signal for pack-level engineering spend requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lithium Refining | Tesla's Nevada operations demonstrate captive spodumene processing securing IRA credit eligibility. |
| Solid-State Pilot Production Scale-Up | Panasonic's Kansas facility targets ceramic electrolyte yield improvements for automotive offtake. |
| Recycling Feedstock Infrastructure | Nevada and Ohio pyrometallurgical plants create closed-loop cathode material recovery pathways. |
| Multi-Year Automotive Offtake Agreements | LG Energy Solution's Michigan capacity locks in Detroit Three platform qualification timelines. |
| UL 9540A Certification Investment | Utility-scale project revenue recognition depends on thermal runaway propagation test completion. |
Study Parameters
Bottom-up electric vehicle fleet modeling reconciled against top-down cell production capacity tracking forms the analytical core. Primary interviews with cathode precursor procurement leads, cell factory process engineers, utility-scale project developers, and automotive platform integration specialists combined with secondary validation from EPA vehicle emissions filings, FERC interconnection queue data, EIA battery storage deployment statistics, and SEC 10-K supply chain disclosures. Triangulation across these sources ensures coverage of both demand-side adoption patterns and supply-side manufacturing constraints.
Historical trendline analysis of lithium-ion cost curves and solid-state pilot production announcements informed projection parameters. The forecast framework segments by chemistry format, application voltage window, and IRA credit qualification status across the projection horizon. CAGRs derive from installed capacity buildout trajectories and fleet electrification mandates. Silicon-anode adoption rates and ceramic electrolyte manufacturing yields constitute battery-specific forecast sensitivity inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to lithium carbonate price volatility, NHTSA safety protocol amendments, and IRA foreign entity of concern enforcement revisions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Japan Mobile Battery Market
Batteries
Forklift Battery Market
Batteries
United Kingdom Electric Vehicle Battery Electrolyte Market
Batteries
Lithium Thionyl Chloride Battery Market
Batteries
Bio Based Battery Market
Batteries
East Europe Battery Market
Batteries
Middle-East and Africa Consumer Battery Market
Batteries
Grid-Scale Battery Market
Batteries
High Voltage Battery Market
Batteries
Wireless Power Bank Market
Batteries
PVT Battery Panel Market
Batteries
Iron Salt Battery Market
Batteries
Primary Lithium Battery for Industrial Market
Batteries
West Africa Battery Market
Batteries
Marine Powerboat Battery Market
Batteries
Global Industrial Lead Acid Battery Market