
 Primary Lithium Battery Market | 2026-2036
Primary Lithium Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Primary Lithium Battery Market Intelligence
A widening capital-intensity gap between integrated cell manufacturers and assembly-only operators is redrawing competitive boundaries in primary lithium batteries. Saft Groupe S.A. leverages its vertically integrated French production base to supply military-grade lithium thionyl chloride cells under long-term defense contracts. Energizer Holdings, Inc. sustains broad consumer channel control through retail partnerships spanning North American and European markets. Tadiran Batteries specializes in extended-life bobbin cell architectures for industrial IoT deployments.
Primary lithium batteries are non-rechargeable electrochemical cells utilizing metallic lithium anodes paired with cathode materials such as manganese dioxide or thionyl chloride, delivering nominal voltages of 3.0–3.6 V with specific energies reaching 250–700 Wh/kg depending on chemistry. These cells serve critical functions where replacement access is impractical: medical implants, remote sensors, and tactical military equipment requiring decade-long operational lifespans. Lithium manganese dioxide chemistry dominates consumer-facing applications due to its cost-positioning and manufacturing maturity, while lithium thionyl chloride occupies premium industrial and defense niches where energy density and temperature tolerance command price premiums. Cylindrical and button cell formats lead volume production, though prismatic designs are gaining traction in space-constrained wearable electronics and next-generation smart metering hardware.
The EU Battery Regulation mandates carbon footprint declarations and recycled content thresholds for cells placed on the European market, directly affecting import competitiveness for non-European producers. IEC 60086-4 and UN 38.3 testing protocols govern transport safety and short-circuit resilience, shaping product development roadmaps and qualification timelines for manufacturers targeting cross-border distribution. In the United States, the Department of Defense's domestic sourcing preferences under the Berry Amendment restrict certain military battery procurements to U.S.-manufactured cells, creating geographic supply constraints. Stakeholders must track evolving chemistry-specific recycling mandates and defense localization requirements to anticipate shifts in qualified supplier pools and regional manufacturing investment patterns.
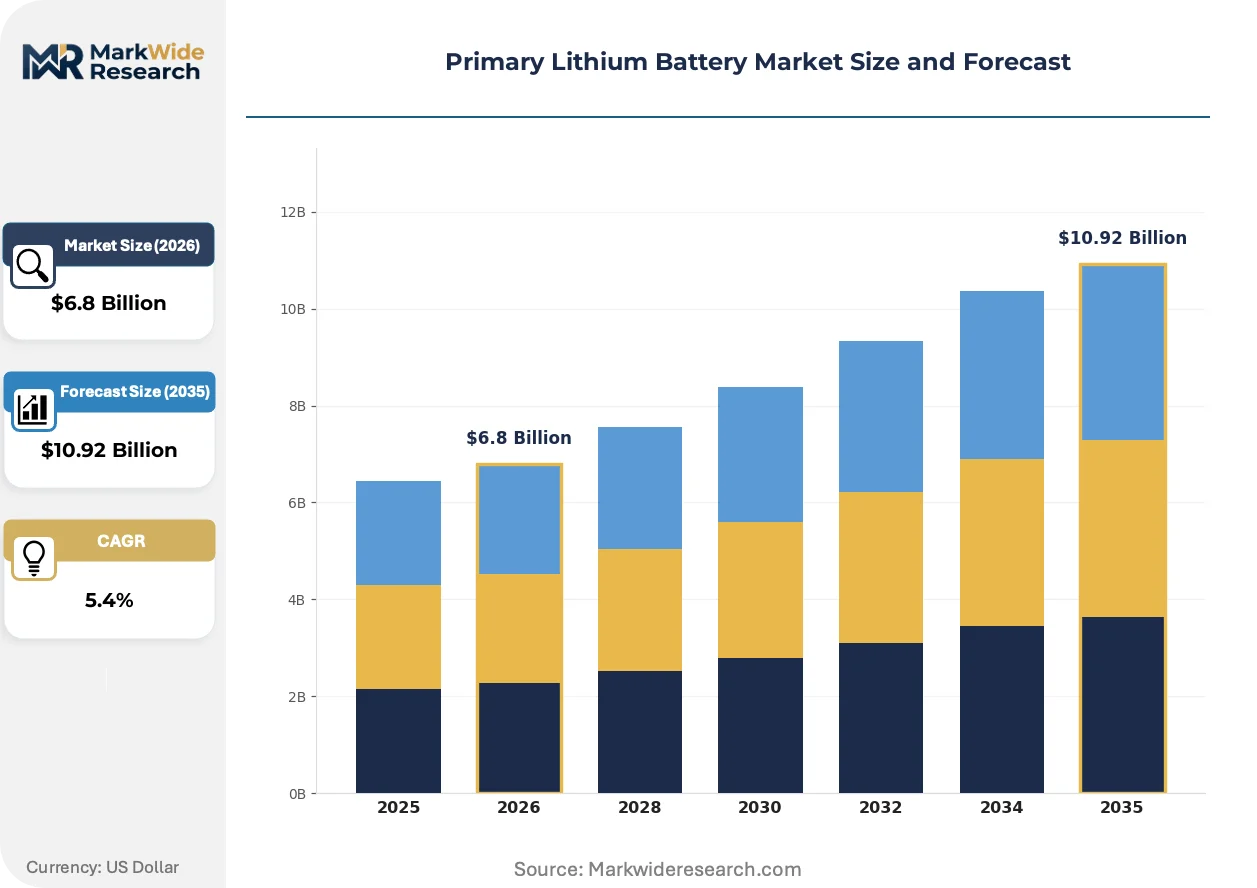
Market Dynamics
Defense procurement consolidation and EU Battery Regulation carbon-footprint mandates are compressing supplier pools while rewarding vertically integrated cell manufacturers with qualified military supply chains.
Growth Catalysts
- Defense Electrification:Tactical military equipment modernization programs in Germany, Japan, and the United States are expanding long-term contracts for high-energy-density lithium thionyl chloride cells with decade-plus operational requirements.
- Smart Metering Mandates:Utility infrastructure upgrades across industrialized markets are displacing alkaline backup cells with extended-life primary lithium architectures for AMI communication modules.
- IEC 60086-4 Certification:Enhanced safety testing protocols are filtering out marginal suppliers and concentrating procurement relationships with qualified cell manufacturers holding validated transport and short-circuit resilience documentation.
Market Restraints
- Lithium Metal Volatility:Raw material price swings and concentrated South American brine supply chains expose cell producers to input cost instability absent long-term offtake agreements.
- Transport Classification Burden:UN 38.3 testing requirements and Class 9 hazardous material shipping restrictions add compliance overhead that disadvantages smaller assembly-only operators lacking in-house certification laboratories.
- Rechargeable Substitution:Solid-state secondary cell advances in medical implant and consumer wearable segments threaten premium primary lithium positioning where replacement access is technically feasible.
Strategic Opportunities
- Industrial IoT Sensor Networks:Remote environmental monitoring deployments in Nordic and Alpine regions favor bobbin cell architectures capable of sub-zero temperature performance without maintenance access.
- EU Green Deal Alignment:Carbon footprint declaration requirements create first-mover advantage for European cell manufacturers with renewable-powered production and documented recycled content streams.
- Medical Implant Miniaturization:Cardiac rhythm management device downsizing trends favor prismatic and button cell formats with volumetric energy density optimization.
Industry Challenges
- Electrolyte Formulation Expertise:Scarce chemist talent pools specializing in thionyl chloride and sulfur dioxide electrolyte systems constrain R&D throughput for next-generation cell architectures.
- Qualification Timeline Compression:Defense and aerospace OEM validation cycles spanning 18-36 months delay revenue recognition and strain working capital for contract manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Primary Lithium Battery Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lithium Manganese Dioxide, Lithium Thionyl Chloride, Lithium Carbon Monofluoride, Lithium Iron Disulfide End Use Industry: Consumer Electronics, Military Devices, Automotive Sensors, Smart Metering, Industrial Equipment Application: Wearable Electronics, Medical Instruments, Remote Controls, Security Systems, Environmental Monitoring Packaging Type: Button Cell, Coin Cell, Cylindrical Cell, Prismatic Cell, Pouch Cell |
| Companies Covered | Panasonic Corporation, Duracell, Energizer Holdings, Inc., Saft Groupe S.A., Tadiran Batteries, EVE Energy Co., Ltd., Ultralife Corporation, GP Batteries International Limited, Maxell Holdings, Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Primary Lithium Battery Market Strategic Shifts & Innovations
Electrochemical architecture refinements and regulatory disclosure mandates are reshaping competitive differentiation away from commodity capacity toward certified performance documentation and chemistry-specific safety engineering.
Prismatic lithium manganese dioxide cells are displacing cylindrical formats in space-constrained wearable electronics and next-generation smart metering hardware. Medical device OEMs in Switzerland and Japan are adopting these flattened geometries for cardiac monitors and drug delivery patches. The format shift is miniaturizing power subsystem footprints while maintaining 3.0 V nominal output across temperature extremes.
REACH substance restrictions and EU Battery Regulation recycled content thresholds are forcing cathode material suppliers to document supply chain provenance and carbon intensity. Non-European cell manufacturers face competitive headwinds without European production bases or renewable energy sourcing certifications. German and French industrial buyers are prioritizing suppliers with validated environmental product declarations and closed-loop recycling partnerships.
Long-term service agreements are displacing spot procurement for utility and defense battery fleets. Buyers in the United States and Japan are consolidating supplier relationships around cell manufacturers offering decade-plus performance warranties and predictive failure monitoring. This contractual evolution concentrates procurement volumes with vertically integrated producers capable of traceable manufacturing records and field failure analysis capabilities.
Primary Lithium Battery Market Segmentation
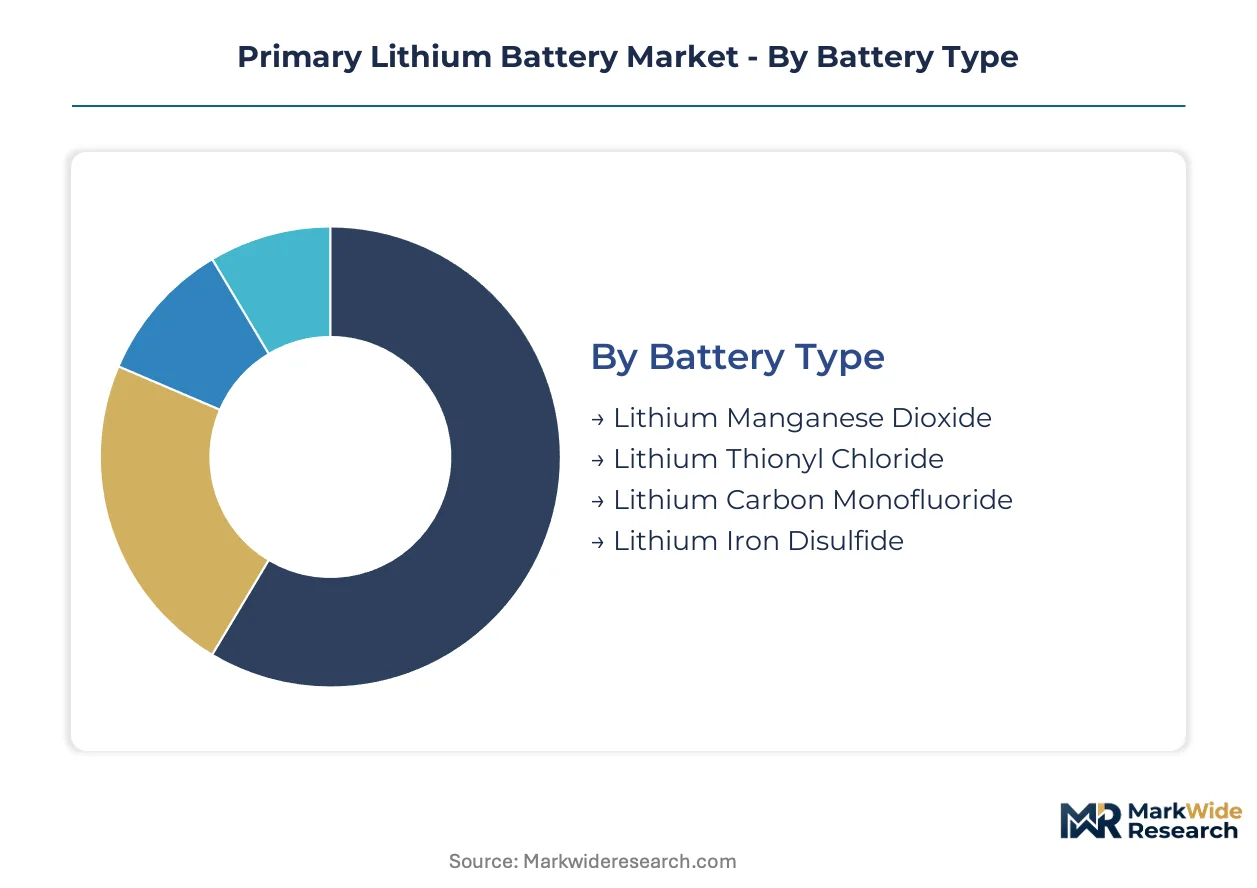
Primary lithium battery procurement patterns diverge sharply across chemistry, application, and form factor dimensions. Defense and industrial buyers prioritize IEC 60086-4 certified lithium thionyl chloride cells, while consumer channels favor cost-optimized lithium manganese dioxide alternatives.
Battery Type:
REACH substance restrictions and UN 38.3 transport classifications create divergent compliance burdens across chemistries, filtering supplier participation.
- Lithium Thionyl Chloride:Delivers the highest specific energy among commercial primary lithium systems, with nominal voltages of 3.6 V and decade-plus shelf stability. German defense contractors and Japanese industrial sensor manufacturers specify this chemistry for sub-zero temperature performance where replacement access is impossible.
- Lithium Manganese Dioxide:Dominates consumer-facing volume through manufacturing maturity and cost positioning at 3.0 V nominal output. Smart metering deployments in the United States and wearable electronics producers in Switzerland are standardizing on this chemistry for moderate-drain applications with predictable discharge profiles.
- Lithium Carbon Monofluoride:Delivers superior energy density for cardiac implantable devices requiring sub-millimeter form factors.
- Lithium Iron Disulfide:Serves high-pulse applications in digital cameras and tactical flashlights requiring 1.5 V compatibility.
Established volume favors Lithium Manganese Dioxide; emerging adoption favors Lithium Thionyl Chloride.
End Use Industry:
Customer procurement timelines stretch from 18-month defense qualification cycles to quarterly consumer electronics replenishment.
- Military Devices:Berry Amendment compliance and decade-plus operational lifespans define procurement criteria. U.S. defense contractors require domestic cell manufacturing with traceable lot records and predictive failure monitoring capabilities.
- Smart Metering:Utility infrastructure mandates across industrialized markets are displacing alkaline backup architectures. German and Japanese AMI communication module suppliers specify extended-life primary lithium cells with 20-year service intervals.
- Consumer Electronics:Retail channel velocity and cost-per-watt-hour dominate supplier selection.
- Automotive Sensors:Tire pressure monitoring and keyless entry systems favor wide-temperature-range performance.
- Industrial Equipment:Remote asset tracking and predictive maintenance sensors drive bobbin cell demand.
Defense contracts deliver margin stability; smart metering delivers volume expansion.
Application:
Device miniaturization and maintenance-inaccessibility determine format and chemistry selection across use cases.
- Medical Instruments:Cardiac rhythm management devices and drug delivery patches require prismatic and button cell formats with volumetric energy density optimization. Swiss and Japanese medical device OEMs are adopting flattened geometries to miniaturize power subsystem footprints.
- Environmental Monitoring:Nordic and Alpine remote sensor networks favor bobbin cell architectures capable of sub-zero temperature performance without maintenance access. EU Green Deal carbon footprint declarations are prioritizing European cell manufacturers with renewable-powered production.
- Wearable Electronics:Fitness trackers and hearing aids drive demand for ultra-thin prismatic formats.
- Remote Controls:Standard cylindrical formats dominate replacement battery markets.
- Security Systems:Smoke detectors and access control panels favor long shelf-life chemistries.
Medical instruments command premium pricing; environmental monitoring is climbing the fastest.
Packaging Type:
Form factor selection trades volumetric efficiency against manufacturing automation and cell stacking flexibility.
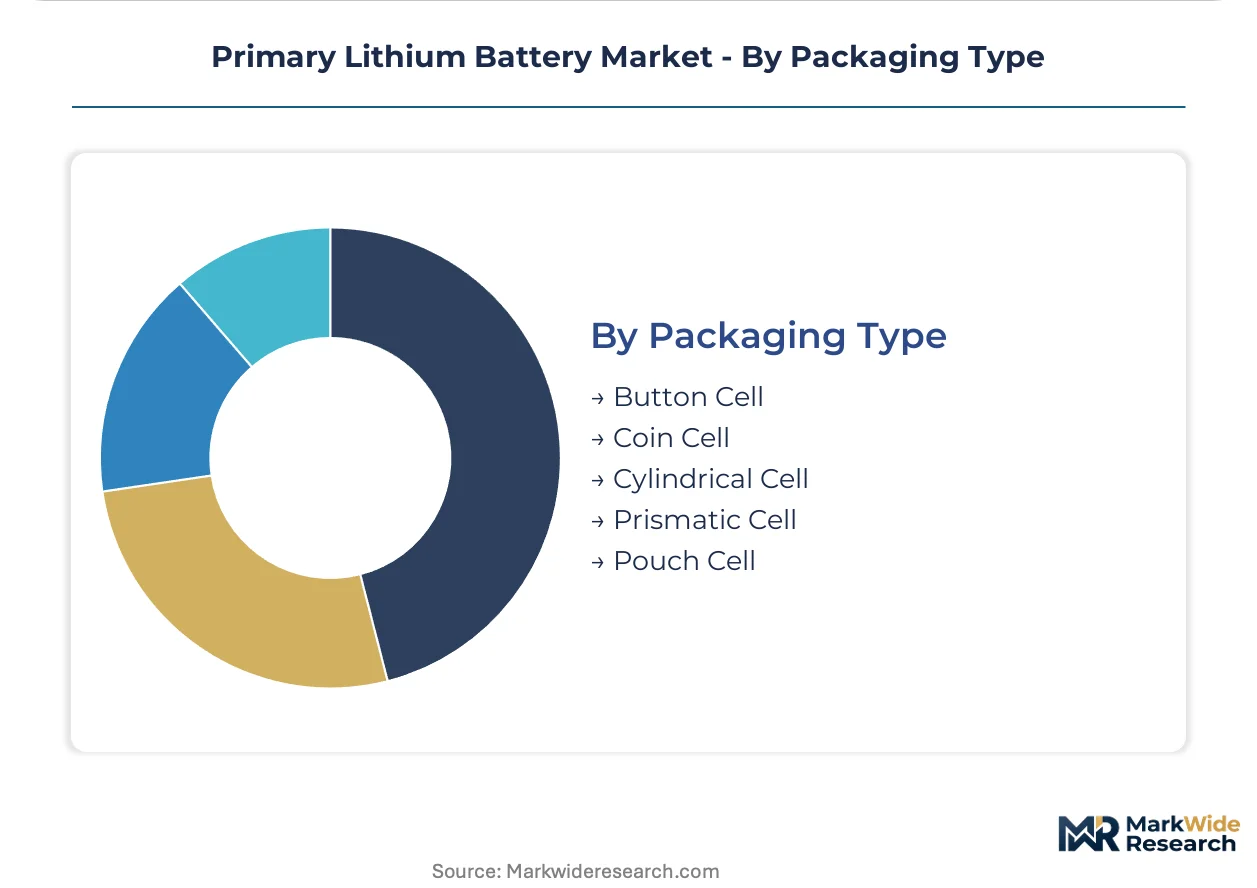
- Cylindrical Cell:Maintains dominant volume production through established winding equipment and standardized dimensions. Industrial IoT deployments and military field equipment continue specifying this format for mechanical robustness and thermal management.
- Prismatic Cell:Gaining traction in space-constrained wearable electronics and next-generation smart metering hardware through flattened geometries that maximize packing density in rectangular enclosures.
- Button Cell:Serves medical implants and compact consumer electronics requiring sub-centimeter thickness.
- Coin Cell:Dominates backup power applications in real-time clocks and memory retention circuits.
- Pouch Cell:Emerging in flexible electronics and conformable medical patches requiring bend radius tolerance.
Cylindrical formats retain manufacturing scale; prismatic formats gain design flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Primary lithium battery trade flows tilt toward net importers with concentrated defense and industrial demand, while established manufacturing bases in France and Japan sustain export competitiveness through chemistry specialization and military qualification protocols.
United States
Defense electrification programs and Berry Amendment domestic sourcing mandates drive procurement consolidation around qualified suppliers. The Department of Defense restricts certain military battery contracts to U.S.-manufactured cells, creating geographic supply constraints. Boston-area defense contractors and California-based industrial sensor developers anchor demand for high-reliability lithium thionyl chloride architectures.
Germany
Smart metering infrastructure mandates and industrial automation investments expand extended-life cell procurement. EU Battery Regulation carbon footprint declarations and REACH substance restrictions filter supplier participation. Bavarian utility equipment manufacturers and Baden-Württemberg industrial automation clusters specify IEC 60086-4 certified cells with documented recycled content streams.
Japan
Medical device miniaturization and remote sensor network deployments favor prismatic and bobbin cell formats. METI industrial standards and PMDA medical device regulations shape qualification timelines for implantable power systems. Tokyo-Osaka medical technology corridors and Nagoya-area industrial sensor producers drive premium chemistry adoption.
China
Industrial IoT scale deployment and consumer electronics manufacturing sustain volume demand across cylindrical and button cell formats. MIIT battery safety standards and GB certification protocols govern domestic market access. Shenzhen electronics manufacturing clusters and Shanghai industrial automation hubs concentrate assembly capacity for regional supply.
Switzerland
Cardiac implantable device production and precision instrumentation manufacturing command sub-millimeter form factor specialization. Swissmedic medical device regulations and EU Battery Regulation alignment requirements prioritize suppliers with environmental product declarations. Zurich-Geneva medical technology corridors anchor European demand for lithium carbon monofluoride chemistries.
Primary Lithium Battery Market Key Industry Players
Concentration sits with vertically integrated cell manufacturers holding qualified military supply chains and in-house electrolyte formulation capabilities. The competitive structure tiers between defense-industrial specialists with decade-plus performance warranties and consumer-channel operators optimizing retail velocity. Three archetypes dominate: chemistry-specialized defense contractors, broad-channel consumer brands, and industrial IoT-focused bobbin cell architects. Capacity expansion and strategic partnerships constitute the primary competitive moves, with European producers leveraging renewable-powered production for EU Green Deal alignment.
Within the defense-industrial tier, Saft Groupe S.A. and Tadiran Batteries exemplify vertically integrated specialists with captive electrolyte systems and long-term service agreement capabilities. Energizer Holdings, Inc. occupies a position spanning consumer and industrial segments through retail channel control and brand equity. These three anchors illustrate the market's divergence between premium qualified supply and volume-optimized distribution.
| Leading Market Players |
|---|
| Panasonic Corporation |
| Duracell |
| Energizer Holdings, Inc. |
| Saft Groupe S.A. |
| Tadiran Batteries |
| EVE Energy Co., Ltd. |
| Ultralife Corporation |
| GP Batteries International Limited |
| Maxell Holdings, Ltd. |
| Others |
Cost & Logistics Intelligence
Eighteen-to-thirty-six-month defense qualification cycles concentrate pricing power with vertically integrated cell manufacturers holding validated IEC 60086-4 documentation and captive electrolyte production. This extended validation timeline filters out assembly-only operators and rewards qualified suppliers with decade-plus service contract premiums.
Pricing Analysis
The customization-premium spread between configured-to-order lithium thionyl chloride cells and standard lithium manganese dioxide alternatives reaches multiples based on certification grade and military qualification status. Contract-based long-term offtake agreements dominate defense procurement, while consumer channels operate on per-unit transactional pricing. Price differentiation hinges on IEC 60086-4 certification tier and Berry Amendment compliance status. Cost compression in consumer-grade cylindrical cells is intensifying because of rechargeable substitution threats. Industrial IoT buyers exhibit lowest price sensitivity due to maintenance-inaccessibility requirements.
Supply Chain Analysis
Inventory buffers for lithium metal anodes and thionyl chloride electrolytes extend lead-time exposure beyond standard electronic component cycles. Raw material supply concentrates in Chile and Argentina for lithium brine, with cathode active material production centered in China and Japan. Cell manufacturing draws from concentrated South American brine supply chains and specialized electrolyte precursor streams. Single-source vulnerability in thionyl chloride electrolyte formulation creates qualification risk for defense contractors. Distribution runs through qualified military supply chains and industrial OEM direct procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Defense electrification programs and EU Battery Regulation carbon-footprint mandates are disrupting procurement patterns toward qualified, traceable supply chains. This regulatory-technological inflection compresses supplier pools while extending contract durations.
For Market Incumbents: Shield established military supply relationships through accelerated IEC 60086-4 certification renewal and predictive failure monitoring capabilities. Deepen backward integration into lithium metal processing to offset raw material volatility. Berry Amendment compliance and in-house electrolyte formulation constitute critical defensive moats against Asian cost competitors.
For New Entrants and Emerging Players: Certification fast-track partnerships with German TÜV or Swiss testing laboratories accelerate market entry timelines. Industrial IoT sensor networks in Nordic regions offer the most penetrable white space due to temperature-performance requirements and fragmented incumbent presence. Target utility AMI communication module suppliers with carbon-footprint-declaration-ready product lines.
For Investors and Strategic Acquirers: Long-term, this sits as a defense-industrial consolidation play because procurement concentration and qualification barriers favor scaled, vertically integrated specialists. Acquisition targets should exhibit captive electrolyte systems and existing military contract vehicles. Watch for EU Battery Regulation recycled-content threshold enforcement as the signal for European manufacturing asset repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Electrolyte Formulation Acquisition | Captive thionyl chloride expertise secures defense contract eligibility against qualified competitors. |
| EU Carbon Footprint Certification | Renewable-powered production documentation unlocks German and French utility procurement channels. |
| Prismatic Cell Capacity Expansion | Flattened geometries address Swiss medical device OEM miniaturization requirements. |
| Long-Term Service Agreement Rollout | Predictive failure monitoring capabilities extend contract durations with Japanese industrial buyers. |
| Berry Amendment Production Footprint | U.S. domestic cell manufacturing qualifies for Department of Defense restricted procurement pools. |
Research Approach
A spread of perspectives from defense procurement officers, utility asset managers, medical device reliability engineers, and industrial sensor OEMs converged on the working assumptions for chemistry-specific demand trajectories. Primary fieldwork with these stakeholders combined with secondary validation against IEC certification databases, UN 38.3 transport classification records, EU Battery Regulation implementation guidance, and customs trade flow data. Bottom-up cell shipment analysis and top-down end-use equipment production estimates were triangulated for convergence.
Segmentation dimensions modeled span battery chemistry, end-use industry, application, and packaging format across the projection horizon. CAGRs were derived from equipment installation forecasts and replacement cycle analysis. Chemistry-specific energy density improvements and regulatory qualification timeline compression served as key forecast inputs for military and medical segments.
Decision-makers should treat outputs as directional under stable defense procurement budgets and EU regulatory implementation timelines; material deviation in lithium metal supply disruptions or solid-state secondary cell advances would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
South America Micro Battery Market
Batteries
Redox Flow Battery Market
Batteries
Sweden Rechargeable Battery Market
Batteries
Europe Battery Systems for Electric Vehicles Market
Batteries
Absorbent Glass Mat (AGM) Battery Market
Batteries
Iron-Chromium Flow Battery Market
Batteries
Portable Battery Market
Batteries
Portable Battery Powered Products Market
Batteries
Battery Plate Market
Batteries
Japan Mobile Battery Market
Batteries
Asia-Pacific Consumer Battery Market
Batteries
Lithium Starters Market
Batteries
Aluminum Wire Battery Market
Batteries
Seawater Battery Market
Batteries
Vanadium Redox Batteries Market
Batteries
Sodium Nickel Chloride Battery Market