
 Printable Battery Market | 2026-2036
Printable Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Printable Battery Market Analysis
Zinc is realigning printable battery economics as manufacturers substitute lithium-ion architectures with aqueous-compatible chemistries that cut processing costs and eliminate thermal runaway risks. Imprint Energy leverages proprietary zinc-polymer formulations to dominate flexible cell prototyping for IoT sensor networks. Enfucell Oy Ltd anchors Nordic medical device supply chains with printed power sources integrated into disposable diagnostic patches. Samsung SDI competes through scaled roll-to-roll manufacturing lines that bridge consumer electronics volumes with solid-state thin-film research.
A printable battery is an electrochemical energy storage device fabricated through additive deposition techniques such as screen printing, inkjet dispensing, or gravure coating onto flexible substrates, typically achieving cell thicknesses below one millimeter and operating voltages between 1.5V and 3.7V depending on cathode chemistry. These devices power distributed electronics where conventional cylindrical or pouch cells impose unacceptable form-factor penalties. Flexible batteries currently capture the largest revenue pool across product types due to their penetration in wearable technology and smart packaging, while solid-state printed architectures represent the fastest-growing technology segment as graphene-based electrolyte inks mature toward commercial ionic conductivity thresholds. Energy harvesting applications sustain premium pricing through integration with printed thermoelectric or photovoltaic layers, whereas IoT device deployments drive volume scale through standardized cell footprints.
The EPA governs hazardous substance reporting for zinc-manganese and silver-oxide inks used in domestic manufacturing, while REACH restricts phthalate plasticizers and volatile organic compounds in European-sourced electrolyte formulations, and the EU Battery Regulation mandates recycled content disclosures that reshape material procurement strategies for export-oriented producers. FDA device classification rules for printed power sources integrated into diagnostic wearables create parallel compliance pathways that favor established medical battery suppliers over consumer-electronics entrants. Stakeholders must monitor convergence between chemical safety mandates and performance certification standards to anticipate which formulation platforms will secure cross-border market access.
Market Dynamics
Zinc-polymer chemistry is displacing lithium-ion architectures in flexible cell manufacturing, eliminating thermal runaway risks while cutting processing costs through aqueous-compatible deposition methods. This materials pivot is restructuring supplier hierarchies and prototyping priorities across wearable electronics and medical device supply chains.
Growth Catalysts
- Wearable technology integration:Smartwatch and fitness band manufacturers are embedding printed cells directly into flexible substrates, eliminating form-factor penalties from cylindrical alternatives. Medical device OEMs in Germany drive prototyping volumes for diagnostic patch applications.
- REACH material disclosure mandates:European electrolyte formulation rules are accelerating substitution of phthalate plasticizers with bio-based alternatives, creating first-mover advantages for compliant ink suppliers.
- Roll-to-roll manufacturing scale:Scaled deposition lines are bridging consumer electronics volumes with solid-state thin-film research, compressing unit economics for standardized IoT footprints.
Market Restraints
- Zinc-manganese ink supply concentration:Domestic EPA hazardous substance reporting requirements constrain qualified suppliers for aqueous-compatible anode formulations, creating procurement bottlenecks.
- Ionic conductivity thresholds:Graphene-based electrolyte inks remain below commercial performance thresholds for high-drain applications, limiting addressable device categories.
- EU Battery Regulation compliance costs:Recycled content disclosure mandates are reshaping material procurement strategies for export-oriented producers, elevating working capital requirements.
Strategic Opportunities
- Underpenetrated Nordic medical supply chains:Disposable diagnostic patch manufacturers in Finland and Sweden seek qualified printed power sources for single-use applications with integrated disposability.
- Energy harvesting convergence:Printed thermoelectric and photovoltaic layer integration commands premium pricing in industrial sensor networks requiring autonomous operation.
- IRA domestic manufacturing incentives:US-based additive deposition facilities qualify for clean energy production credits, attracting capital for regional supply chain localization.
Industry Challenges
- Formulation-to-device certification timelines:FDA device classification rules for printed power sources integrated into diagnostic wearables create parallel compliance pathways that extend product launch cycles.
- Cross-functional talent scarcity:Electrochemical engineering expertise must combine with additive manufacturing process knowledge, a skill intersection rarely found in single candidates.
- Legacy pouch cell integration complexity:System architects face redesign burdens when substituting printed architectures into existing battery management systems optimized for conventional geometries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Printable Battery Market |
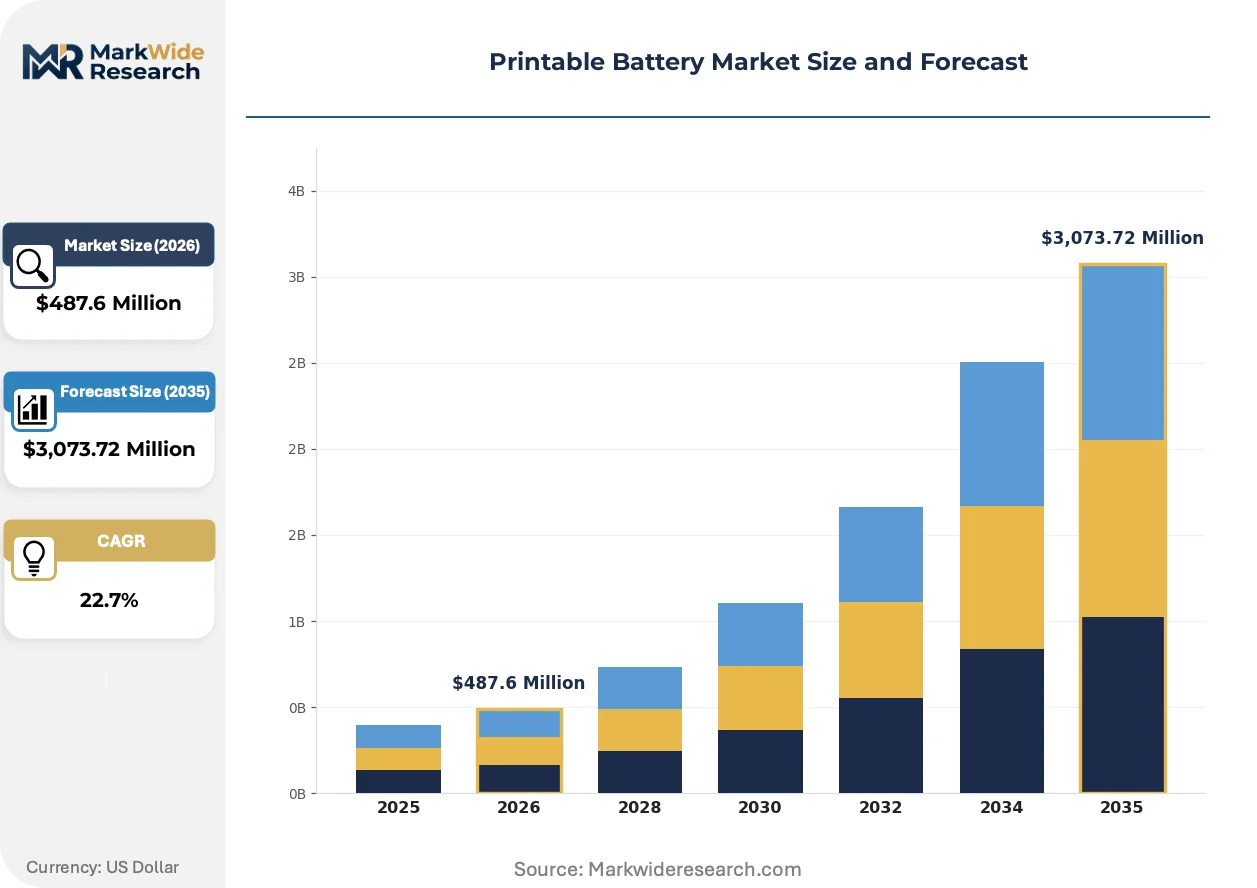
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $3,073.72 Million |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Batteries, Rollable Batteries, Thin-film Batteries, Solid-state Batteries Technology: Printed Electronics, Organic Photovoltaics, Nanotechnology, Graphene-based End User: Consumer Electronics, Medical Devices, Automotive, Wearable Technology Application: Energy Harvesting, Smart Packaging, IoT Devices, Wireless Sensors |
| Companies Covered | Imprint Energy, Enfucell Oy Ltd, BrightVolt Inc, Printed Energy, Blue Spark Technologies, Ultralife Corporation, Samsung SDI, LG Chem Ltd, VARTA AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Printable Battery Market Emerging Trajectories
Materials science breakthroughs and regulatory convergence are compressing development cycles for flexible energy storage. Formulation platforms that satisfy both performance and compliance thresholds are securing disproportionate market access.
Solid-state printed architectures are rewriting competitive positioning in wearable power. Graphene-based electrolyte inks achieve ionic conductivity thresholds previously reserved for liquid electrolytes. Medical device OEMs in Germany and consumer electronics manufacturers in South Korea are accelerating qualification timelines. This technology is compressing the performance gap between thin-film deposition and conventional cell architectures.
EU Battery Regulation recycled content mandates are forcing material provenance documentation across European-sourced supply chains. Cathode ink suppliers must establish certified recycling streams for zinc and manganese feedstocks. Export-oriented producers in Asia-Pacific are restructuring procurement strategies to maintain continental market access, prioritizing partnerships with European metal recovery facilities.
Diagnostic wearable manufacturers are unbundling power source procurement from device assembly contracts. Medical OEMs now specify printed cell performance independently of system integrator preferences, creating direct supplier relationships with specialized battery formulators. This pattern is most visible in German industrial automation clusters and Nordic disposable diagnostic supply chains.
Printable Battery Market Segmentation
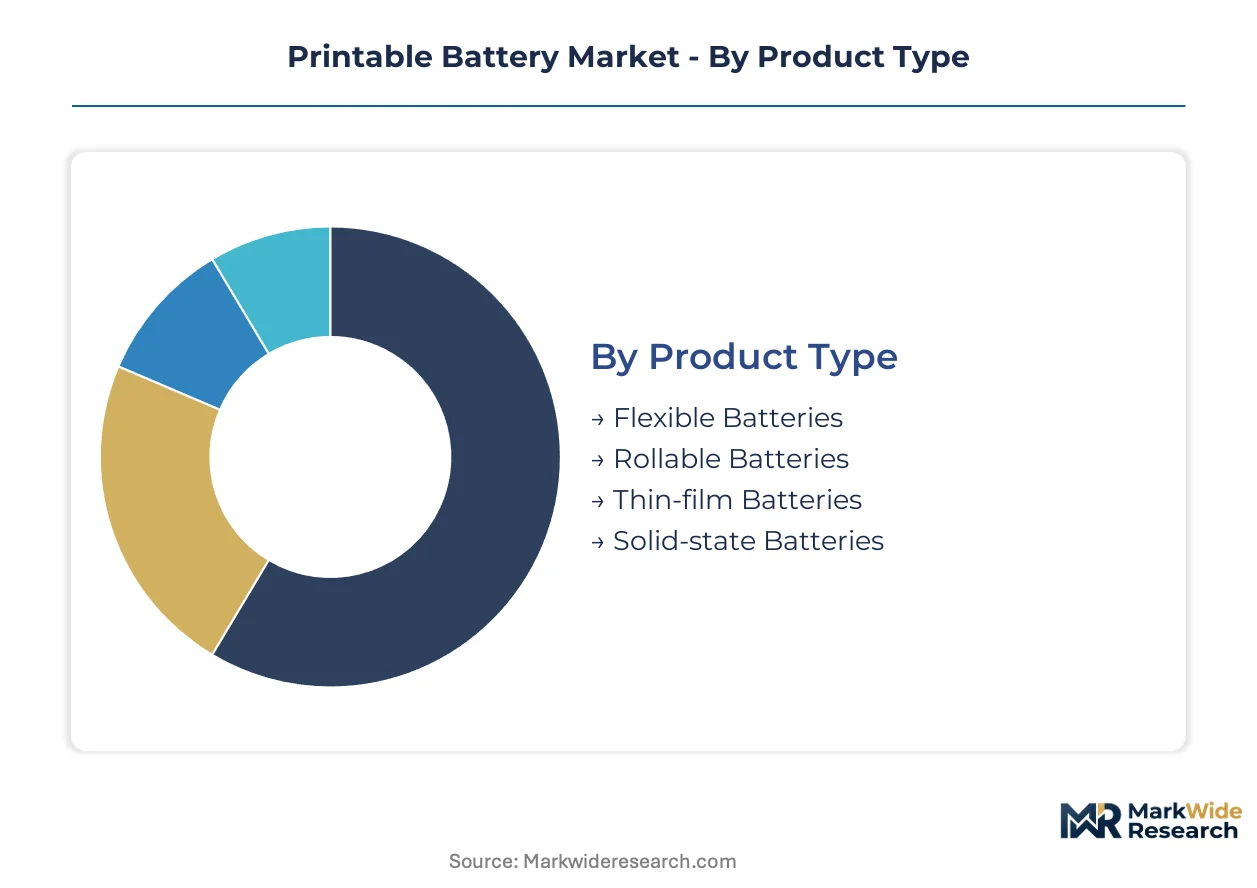
Printable battery architectures diverge sharply across form-factor and chemistry dimensions, with each segment commanding distinct tooling investments and regulatory pathways. Supply chain positioning for additive deposition equipment and specialty ink formulations varies dramatically by product category and target application.
Product Type:
Flexible cell manufacturing concentrates capacity among German industrial automation clusters and South Korean roll-to-roll facilities, creating tiered supply access for medical and consumer electronics OEMs.
- Flexible Batteries:Polymer-substrate architectures achieve sub-millimeter thickness through screen-printed zinc-polymer stacks. Demand clusters in German medical device prototyping for diagnostic patches where conformal power integration eliminates rigid cell constraints.
- Thin-film Batteries:Vacuum-deposited solid-state layers deliver highest energy density per unit area. South Korean consumer electronics manufacturers drive qualification volumes for smartwatch integration, though ionic conductivity thresholds limit high-drain applications.
- Rollable Batteries:Cylindrical wound configurations printed onto flexible substrates for deployable antenna and temporary power applications.
- Solid-state Batteries:Ceramic or glass-ceramic electrolyte architectures eliminating liquid components entirely.
Today's leader: Flexible Batteries. Tomorrow's challenger: Solid-state Batteries.
Technology:
Cost tiers separate mature deposition methods from emerging nano-engineered approaches, with equipment amortization schedules determining viable production scales.
- Printed Electronics:Established screen and inkjet deposition onto polymer substrates using aqueous zinc-manganese formulations. REACH-compliant electrolyte suppliers in Finland and Sweden anchor Nordic medical device supply chains with bio-based plasticizer alternatives.
- Graphene-based:Two-dimensional carbon electrolyte inks achieving ionic conductivity thresholds approaching liquid systems. German research clusters and South Korean electronics conglomerates compress commercialization timelines for wearable power integration.
- Organic Photovoltaics:Solution-processed active layers enabling integrated energy harvesting-printed storage devices.
- Nanotechnology:Engineered nanostructured electrodes and separators for enhanced electrochemical performance.
Mature platforms dominate volume; nano-engineered approaches command premium positioning.
End User:
Application-specific certification requirements create divergent customer acquisition costs, with medical and automotive pathways demanding extended validation cycles.
- Medical Devices:FDA device classification rules for printed power sources in diagnostic wearables mandate parallel compliance pathways. German OEMs specify cell performance independently of system integrators, creating direct supplier relationships with qualified formulators.
- Wearable Technology:Smartwatch and fitness band manufacturers embed cells directly into flexible substrates, eliminating form-factor penalties. South Korean and German consumer electronics clusters drive standardization efforts for IoT footprints.
- Consumer Electronics:Portable device manufacturers seeking thin-profile power solutions.
- Automotive:Interior sensing and temporary power applications for connected vehicle architectures.
Medical certification barriers protect margin; wearables scale through design-in partnerships.
Application:
Volume concentration versus value capture splits across standardized IoT deployments and premium energy harvesting integrations.
- IoT Devices:Standardized cell footprints for distributed sensor networks drive scale economics through roll-to-roll manufacturing. EPA hazardous substance reporting for zinc-manganese inks constrains domestic US supplier qualification, creating procurement bottlenecks for high-volume deployments.
- Energy Harvesting:Printed thermoelectric and photovoltaic layer integration commands premium pricing in industrial sensor networks requiring autonomous operation. German automation clusters and Nordic disposable diagnostic manufacturers sustain niche demand.
- Smart Packaging:Single-use power sources for authentication and freshness monitoring in consumer goods.
- Wireless Sensors:Distributed environmental and structural monitoring applications with extended deployment lifetimes.
Volume scales through IoT standardization; value concentrates in harvesting convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial automation clusters anchor printable battery demand through medical device prototyping and diagnostic patch integration. REACH compliance mandates and EU Battery Regulation recycled content rules are restructuring material procurement across European supply chains. Roll-to-roll manufacturing investments in South Korea and aqueous chemistry scale-up in the United States complete the tripolar production map.
Germany
Medical device OEMs in Baden-Württemberg and Bavaria drive qualification volumes for flexible zinc-polymer cells in disposable diagnostic applications. EU Battery Regulation mandates recycled content disclosures for zinc and manganese cathode feedstocks, forcing ink suppliers to certify metal recovery partnerships. Stuttgart and Munich industrial clusters concentrate thin-film prototyping capacity for wearable integration.
United States
IoT sensor network deployments and clean energy manufacturing incentives attract roll-to-roll deposition investment. EPA hazardous substance reporting requirements for zinc-manganese inks constrain qualified anode suppliers, creating procurement bottlenecks for high-volume deployments. California and Massachusetts research corridors anchor graphene electrolyte commercialization programs.
South Korea
Consumer electronics conglomerates accelerate solid-state thin-film qualification for smartwatch power integration. MFDS medical device regulations create parallel compliance pathways for diagnostic wearable applications. Seoul and Suwon manufacturing belts concentrate scaled deposition lines bridging consumer volumes with research-stage architectures.
Finland
Disposable diagnostic patch manufacturers seek REACH-compliant printed power sources with bio-based plasticizer alternatives. ECHA restrictions on phthalate formulations favor Nordic ink suppliers with certified electrolyte platforms. Tampere and Helsinki medical device clusters sustain niche demand for single-use conformal batteries.
Japan
Materials science consortia advance nano-engineered electrode architectures for enhanced electrochemical performance. METI technology roadmaps prioritize solid-state thin-film convergence with existing electronics manufacturing infrastructure. Tokyo and Osaka industrial districts host qualification programs for graphene-based electrolyte integration.
Printable Battery Market Vendor Landscape
Global majors compete with regional champions across deposition scale and chemistry specialization. The vendor base stratifies into three tiers: diversified electronics conglomerates with captive battery divisions, mid-scale flexible cell specialists, and niche ink formulators serving medical certification pathways. Two strategic archetypes dominate competitive positioning: aqueous zinc-polymer platforms eliminating thermal runaway risks, and solid-state graphene architectures compressing performance gaps with conventional cells. Capacity expansion and strategic partnerships represent the dominant competitive moves, with producers securing metal recovery partnerships to satisfy EU Battery Regulation compliance.
Within the flexible cell specialist tier, Imprint Energy and Enfucell Oy Ltd exemplify chemistry-first positioning. Samsung SDI anchors the diversified conglomerate archetype with integrated roll-to-roll manufacturing scale. BrightVolt Inc and Blue Spark Technologies occupy positions between niche medical certification and consumer electronics volume. VARTA AG and LG Chem Ltd represent European and Asian battery incumbents extending legacy expertise into additive deposition methods. Ultralife Corporation and Printed Energy sit within the defense and industrial sensor application segments where extended operating lifetimes command premium positioning.
| Leading Market Players |
|---|
| Imprint Energy |
| Enfucell Oy Ltd |
| BrightVolt Inc |
| Printed Energy |
| Blue Spark Technologies |
| Ultralife Corporation |
| Samsung SDI |
| LG Chem Ltd |
| VARTA AG |
| Others |
Supply Flow & Price Mechanics
EU Battery Regulation recycled content mandates are forcing cathode ink suppliers to certify metal recovery partnerships, compelling supply chain restructuring that elevates working capital requirements and compresses margin structures for export-oriented producers. REACH-compliant electrolyte formulators in Nordic markets command premium positioning as medical device OEMs substitute phthalate-based alternatives.
Pricing Analysis
Input-cost pass-through from zinc and manganese feedstock volatility shapes cell economics, with aqueous-compatible anode formulations experiencing sharper cost swings than solid-state alternatives. Three-tier pricing structure across medical-grade, industrial-grade, and consumer-grade certification levels separates segments, with FDA-cleared diagnostic wearable cells sustaining the widest spreads. Cost compression in consumer electronics tiers intensifies because Samsung SDI and LG Chem scale roll-to-roll deposition capacity. Medical device OEMs exhibit lowest price sensitivity due to qualification timelines and liability exposure, while IoT sensor network deployers drive hardest bargain on per-unit economics.
Supply Chain Analysis
Certification gating through EPA hazardous substance reporting and REACH material disclosure creates qualified supplier scarcity for zinc-manganese anode inks and bio-based electrolyte formulations. Manufacturing concentrates in Germany, South Korea, and the United States, with Baden-Württemberg medical device clusters, Seoul-Suwon consumer electronics belts, and California-Massachusetts research corridors anchoring distinct capability pools. Raw material dependencies rest on zinc metal feedstocks, polymer substrate films, and graphene nanoplatelet supplies. Single-source vulnerability runs through qualified anode ink formulators meeting domestic EPA reporting thresholds. Distribution runs through direct OEM supply agreements for medical applications and tiered distributor networks for industrial IoT deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where diagnostic wearable manufacturers unbundling power source procurement from device assembly contracts signal demand-shift toward independently certified, premium-specification cells.
For Market Incumbents: Hedge thermal runaway liability exposure by accelerating zinc-polymer platform R&D while securing backward integration into certified zinc metal recovery streams for EU Battery Regulation compliance. Defend margin position against solid-state graphene entrants by embedding cells deeper into German medical OEM specification processes.
For New Entrants and Emerging Players: Capture underpenetrated Nordic disposable diagnostic patch supply chains where Enfucell's established relationships leave room for REACH-compliant alternatives with faster qualification timelines. Target Finland and Sweden medical device clusters with bio-based plasticizer formulations that preempt ECHA restriction expansion.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale flexible cell specialists possessing medical certification pathways and captive ink formulation capabilities. Long-term viability hinges on chemistry-platform durability across regulatory regime shifts. Watch for FDA breakthrough device designation announcements as inflection indicator for premium-tier demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Medical Certification Investment | FDA device classification expertise accelerates diagnostic wearable procurement unbundling. |
| Metal Recovery Partnership | Certified zinc and manganese recycling streams secure EU Battery Regulation market access. |
| Roll-to-Roll Capacity Expansion | Scaled deposition lines bridge consumer electronics volumes with solid-state research. |
| Graphene Electrolyte Commercialization | Ionic conductivity threshold achievement rewrites competitive positioning in wearable power. |
| REACH-Compliant Formulation Platform | Bio-based plasticizer alternatives create first-mover advantage in Nordic medical supply chains. |
Methodological Framework
Bottom-up IoT device and medical wearable modeling reconciled against top-down roll-to-roll manufacturing capacity tracking forms the analytical core. Primary interviews with biomedical engineers at German diagnostic OEMs, GPO contracts managers at Nordic hospital systems, thin-film R&D directors at South Korean electronics conglomerates, and EPA compliance officers at US ink formulators combined with secondary validation. Secondary sources span SEC 10-K filings from diversified battery producers, ECHA substance restriction updates, FDA 510(k) clearance databases, and EU Battery Regulation implementation guidance. Top-down and bottom-up triangulation isolates volume-price intercepts across certification tiers.
Input-output matrices mapping cathode ink formulation costs against deposition throughput rates by technology platform structure the forecast framework. Segmentation dimensions span product type, chemistry platform, end-use certification grade, and regional regulatory cluster across the analysis window. CAGRs derive from segment-level volume trajectories weighted by pricing tier concentration. Industry-specific forecast inputs include graphene electrolyte ionic conductivity improvement curves and EU Battery Regulation recycled content compliance timelines.
Regulatory enforcement variance, graphene commercialization delays, and medical device OEM procurement centralization are the dominant revision risks. Forecasts reflect documented assumptions on chemistry transition rates and certification pathway durations. Deviation in EU Battery Regulation implementation strictness would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Power Tool Batteries Market
Batteries
Middle East and Africa Solar and Motorcycle Battery Market
Batteries
Lithium Starters Market
Batteries
Automotive AGM Battery Market
Batteries
Battery Swapping Market
Batteries
Aluminum Wire Battery Market
Batteries
North Africa Battery Market
Batteries
Atomic Battery Market
Batteries
Li-Mno2 Button Battery Market
Batteries
Smart Battery Charger Market
Batteries
Global Bio Compatible Battery Market
Batteries
Semi-Solid Flow Battery Market
Batteries
Tubular GEL Battery Market
Batteries
Lithium-Fluorinated Graphite Batteries Market
Batteries
Iron-Chromium Flow Battery Market
Batteries
3D-Printed Battery Market