
 Non-Rechargeable Battery Market | 2026-2036
Non-Rechargeable Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Rechargeable Battery Market Insights
East Asian cylindrical cell producers is restructuring capacity allocation toward lithium thionyl chloride and alkaline formats for industrial IoT and medical telemetry. Duracell leverages its brand strength and retail channel control across North American and European mass-market segments. Energizer Holdings sustains R&D intensity in long-duration lithium chemistry for critical military and aerospace applications. Panasonic Corp. anchors high-volume alkaline production for consumer electronics while competing in specialized medical battery supply.
Non-rechargeable batteries are primary electrochemical cells designed for single-use discharge, typically employing zinc-manganese dioxide, lithium-iron disulfide, or lithium thionyl chloride chemistries with nominal voltages ranging from 1.5V to 3.6V, manufactured through precision winding, crimp sealing, and electrolyte filling processes to deliver predictable capacity output for devices requiring reliable standalone power. Alkaline cells dominate consumer-facing volume through supermarket and online retail channels, though margin pools concentrate in lithium thionyl chloride for industrial equipment where extended shelf life and wide temperature tolerance command premium positioning. Medical device applications represent the fastest-growing demand segment as portable diagnostic and implantable equipment requires hermetically sealed primary cells with zero self-discharge leakage risk.
The EU Battery Regulation and REACH compliance frameworks in Europe, alongside FDA device-level battery safety requirements in the United States, are elevating traceability standards and restricting hazardous substance thresholds in primary cell manufacturing. China's GB standards and MIIT circular economy directives are similarly tightening production waste protocols and material recovery obligations for domestic battery makers. Stakeholders must monitor how diverging regional certification requirements affect cross-border product platform strategies and supplier qualification timelines.
Market Dynamics
East Asian cell manufacturers are consolidating lithium thionyl chloride capacity to serve industrial IoT and medical telemetry demand, while EU Battery Regulation disclosure mandates force supply chain requalification across European distribution channels.
Growth Catalysts
- EU Battery Regulation material disclosure:The framework mandates recycled content thresholds and supply chain traceability for single-use cells, accelerating formal recycling infrastructure development across Germany, France, and the Netherlands.
- Industrial IoT sensor deployment:Remote monitoring equipment for oil and gas infrastructure, smart agriculture, and predictive maintenance systems requires lithium primary cells with 10-20 year operational lifespans.
- Medical device electrification:Implantable cardioverter defibrillators, continuous glucose monitors, and portable diagnostic equipment specify hermetically sealed lithium manganese dioxide cells with zero leakage tolerance.
Market Restraints
- Lithium metal price volatility:Primary cell margins compress when battery-grade lithium carbonate and lithium metal feedstock costs spike, particularly affecting thionyl chloride chemistry production economics.
- East Asian supply concentration:Cylindrical cell winding and electrolyte filling capacity clusters in China and South Korea, creating single-source vulnerability for European and North American battery pack assemblers.
- Rechargeable substitution in consumer electronics:USB-C rechargeable lithium-ion cells displace alkaline and lithium-iron disulfide formats in high-drain devices including gaming peripherals and professional audio equipment.
Strategic Opportunities
- Indian medical device manufacturing:CDSCO regulatory harmonization with FDA and CE marking standards enables domestic production of implantable primary cells for cardiac rhythm management devices targeting South Asian and Middle Eastern markets.
- Green hydrogen sensor networks:Safety monitoring systems for electrolyzer facilities and hydrogen refueling stations require intrinsically safe lithium thionyl chloride cells with ATEX/IECEx certification.
- Direct-to-industrial distribution platforms:Specialized cell distributors are bypassing traditional electronics component channels to serve OEM procurement teams with lot-traceable, long-shelf-life inventory.
Industry Challenges
- Hermetic sealing technician scarcity:Precision crimp sealing and laser welding for medical-grade cells requires specialized cleanroom operators, with training pipelines lagging demand in European manufacturing hubs.
- UN 38.3 certification timeline compression:Transportation safety testing for lithium metal cells creates 8-12 week qualification bottlenecks, delaying product launches for seasonal industrial equipment cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Rechargeable Battery Market |
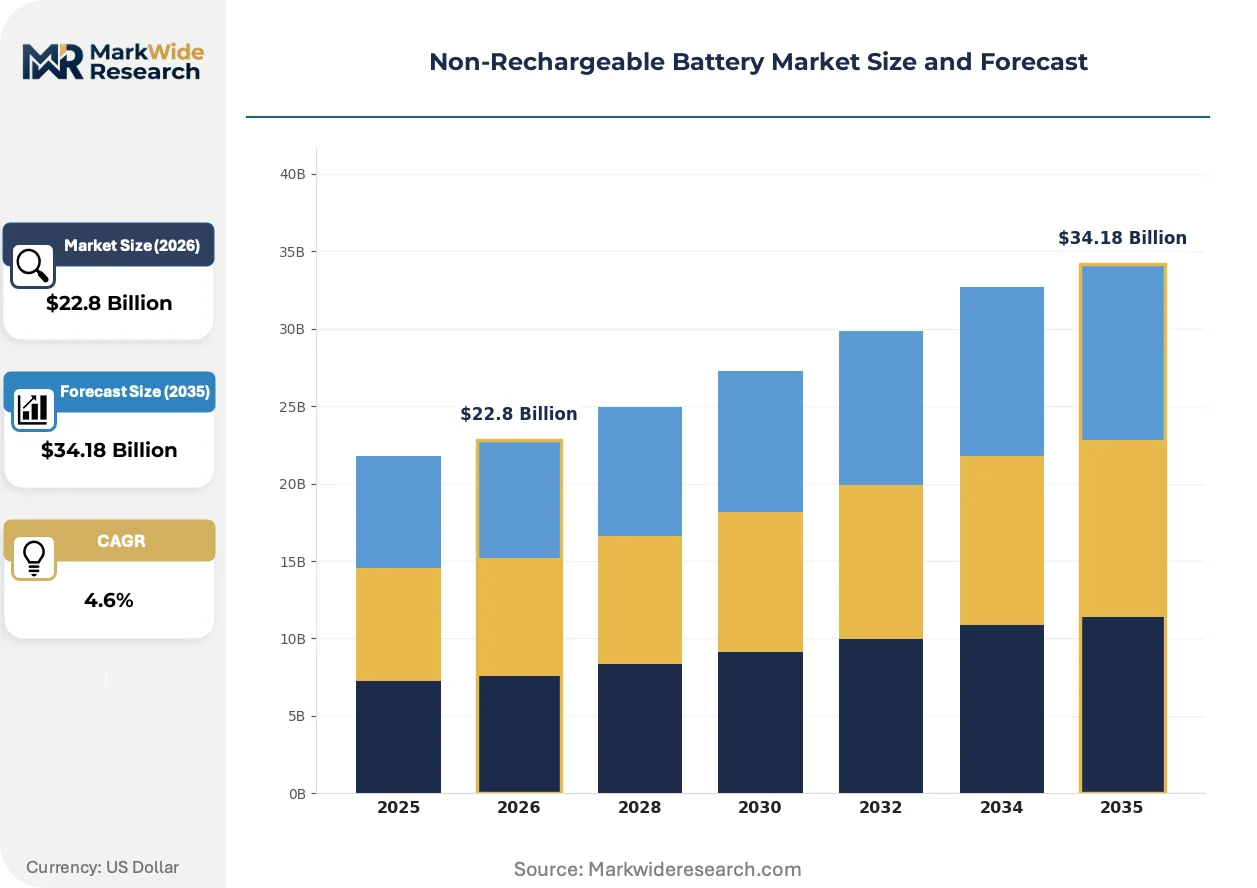
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $34.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alkaline, Lithium, Zinc Carbon, Lithium Thionyl Chloride Application: Consumer Electronics, Medical Devices, Automotive, Industrial Equipment End User: Manufacturers, Retailers, Distributors, Households Distribution Channel: Online Retail, Supermarkets, Wholesale, Convenience Stores |
| Companies Covered | Duracell, Energizer Holdings, Panasonic Corp., VARTA AG, EVE Energy Co., Ltd., Maxell Holdings, Ltd., Saft Groupe S.A., Tadiran Batteries, Renata S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Rechargeable Battery Market Trends and Innovations
Automated winding and electrolyte dosing systems are compressing production variance for high-reliability cells, while regulatory disclosure requirements and direct procurement models reshape how specifications reach end-equipment designers.
Precision winding equipment with machine vision feedback is automating electrode alignment and separator placement in cylindrical cell assembly. Medical device OEMs in Switzerland and Germany are qualifying these lines for implantable-grade production. The technology is automating quality documentation for FDA and EMA submission packages, reducing lot release cycle times from weeks to days.
REACH substance restrictions and RoHS hazardous substance thresholds are tightening cadmium and mercury prohibitions in battery manufacturing. European pack assemblers must now document full material composition through supply chain tiers. Industrial IoT equipment manufacturers in Scandinavia are responding by specifying lithium thionyl chloride cells with pre-certified compliance dossiers.
Consolidated procurement by medical device OEMs is displacing fragmented distributor purchasing for critical cell specifications. Original equipment manufacturers in Minnesota and Massachusetts now negotiate directly with Japanese and South Korean cell producers for multi-year supply agreements. This concentration is most visible in cardiac implantable electronic device supply chains, where single-source qualification locks in volume commitments.
Non-Rechargeable Battery Market Segmentation
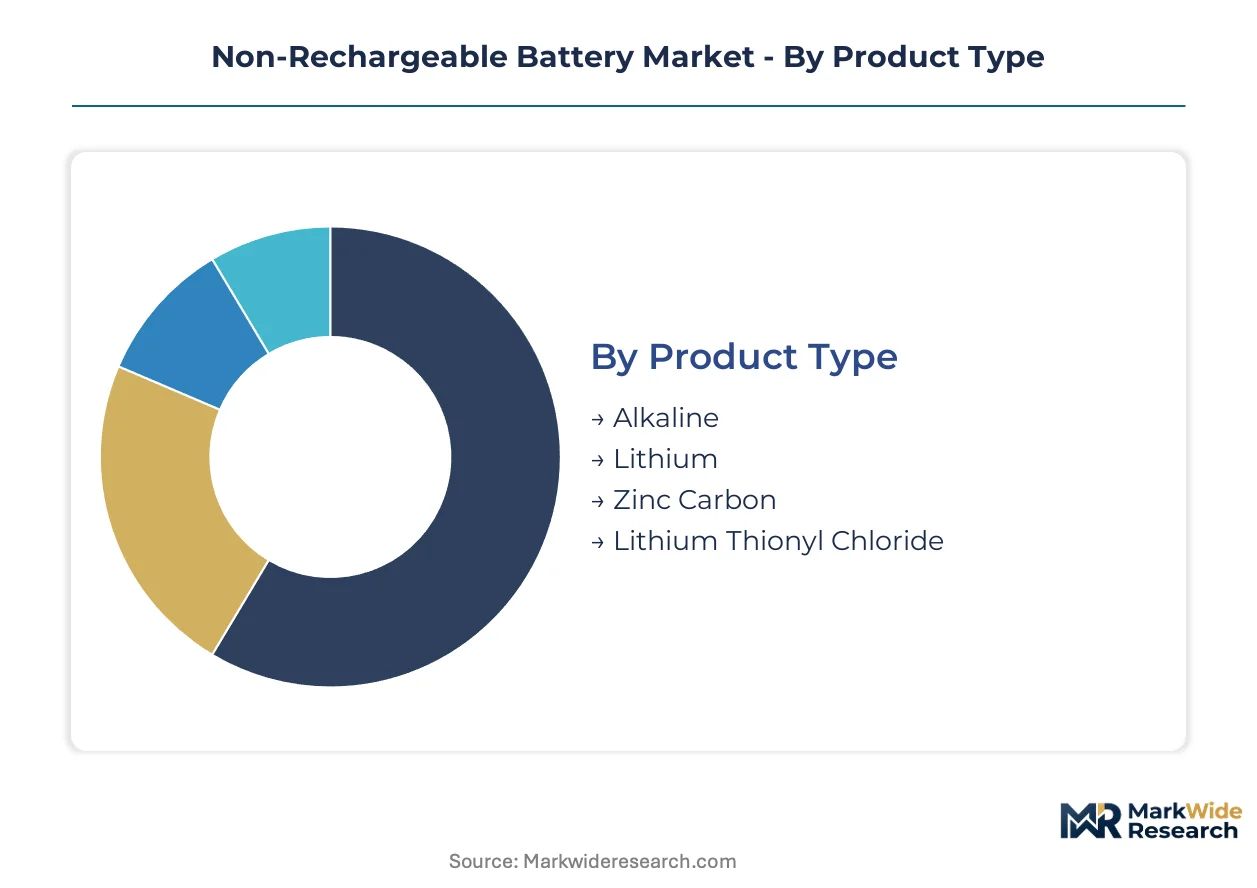
Segmentation in non-rechargeable batteries reveals how chemistry selection, application requirements, and procurement channels create distinct margin pools and technical specifications. Understanding these divisions helps suppliers align capacity investments with end-use reliability demands and regulatory exposure.
Product Type:
Integration depth varies sharply across chemistries, with some formats designed for standalone consumer replacement and others engineered for embedded industrial systems with decade-long service intervals.
- Alkaline:Zinc-manganese dioxide chemistry delivering 1.5V nominal voltage through precision-wound cylindrical construction. Volume concentrates in German and US household retail channels where supermarket placement and brand recognition drive repeat purchase patterns against rechargeable substitution pressure.
- Lithium:Primary lithium metal systems including lithium-iron disulfide and lithium-manganese dioxide variants with 1.5V to 3V output ranges. Demand clusters in Japanese and Swiss medical device manufacturing where hermetic sealing and zero self-discharge specifications command qualification-intensive procurement processes.
- Zinc Carbon:Leclanché-derived electrochemical systems with lower energy density and cost positioning for price-sensitive applications. Chinese manufacturers dominate production for Southeast Asian and African markets where basic flashlight and remote control demand persists.
- Lithium Thionyl Chloride:3.6V cylindrical and button cells with the highest energy density and widest temperature tolerance among primary chemistries. South Korean producers are scaling capacity for Norwegian and German industrial IoT sensor networks requiring ATEX-certified intrinsically safe power sources.
Volume placements concentrate in Alkaline; the faster expansion belongs to Lithium Thionyl Chloride.
Application:
Cost tier differentiation separates commodity replacement markets from specification-driven embedded supply chains with multi-year qualification horizons.
- Consumer Electronics:Portable audio, gaming peripherals, and digital cameras requiring standardized cylindrical or prismatic formats. Chinese OEMs and contract manufacturers in Shenzhen and Dongguan specify alkaline and lithium-iron disulfide cells for devices targeting European and North American retail distribution.
- Medical Devices:Implantable cardioverter defibrillators, continuous glucose monitors, and portable diagnostic equipment demanding hermetically sealed primary cells with documented lot traceability. Swiss and Massachusetts-based device manufacturers enforce FDA and EMA submission packages requiring automated production line validation.
- Automotive:Tire pressure monitoring systems, keyless entry fobs, and emergency call units specifying wide temperature range operation. German Tier 1 suppliers qualify Japanese and South Korean cell producers for platform-level supply agreements spanning vehicle model cycles.
- Industrial Equipment:Remote monitoring sensors, safety systems, and predictive maintenance hardware requiring 10-20 year operational lifespans. Scandinavian oil and gas operators and German chemical processors specify lithium thionyl chloride with pre-certified REACH and RoHS compliance dossiers.
Revenue concentration sits with Medical Devices; Industrial Equipment is climbing the fastest.
End User:
Customer type determines whether procurement flows through fragmented retail channels or consolidated direct negotiations with multi-year volume commitments.
- Manufacturers:OEM and contract manufacturers integrating cells into finished equipment with specification-controlled supply agreements. Japanese automotive electronics producers and Swiss medical device makers negotiate directly with cell producers, bypassing traditional distribution.
- Retailers:Mass-market chains and specialty electronics stores managing inventory turnover and private label sourcing. French and British supermarket operators control shelf placement for alkaline brands while facing rechargeable substitution in high-drain categories.
- Distributors:Industrial component and electronics wholesale channels serving MRO procurement and small-batch OEM requirements. German and Dutch distributors are developing lot-traceable inventory systems to serve medical and industrial IoT customers with documented chain of custody.
- Households:End consumers purchasing replacement cells for existing device installed bases. US and German household demand shows channel shift toward online retail while convenience store placement captures emergency purchase occasions.
Procurement scale clusters with Manufacturers; Distributors are gaining share fastest as direct-to-industrial platforms expand.
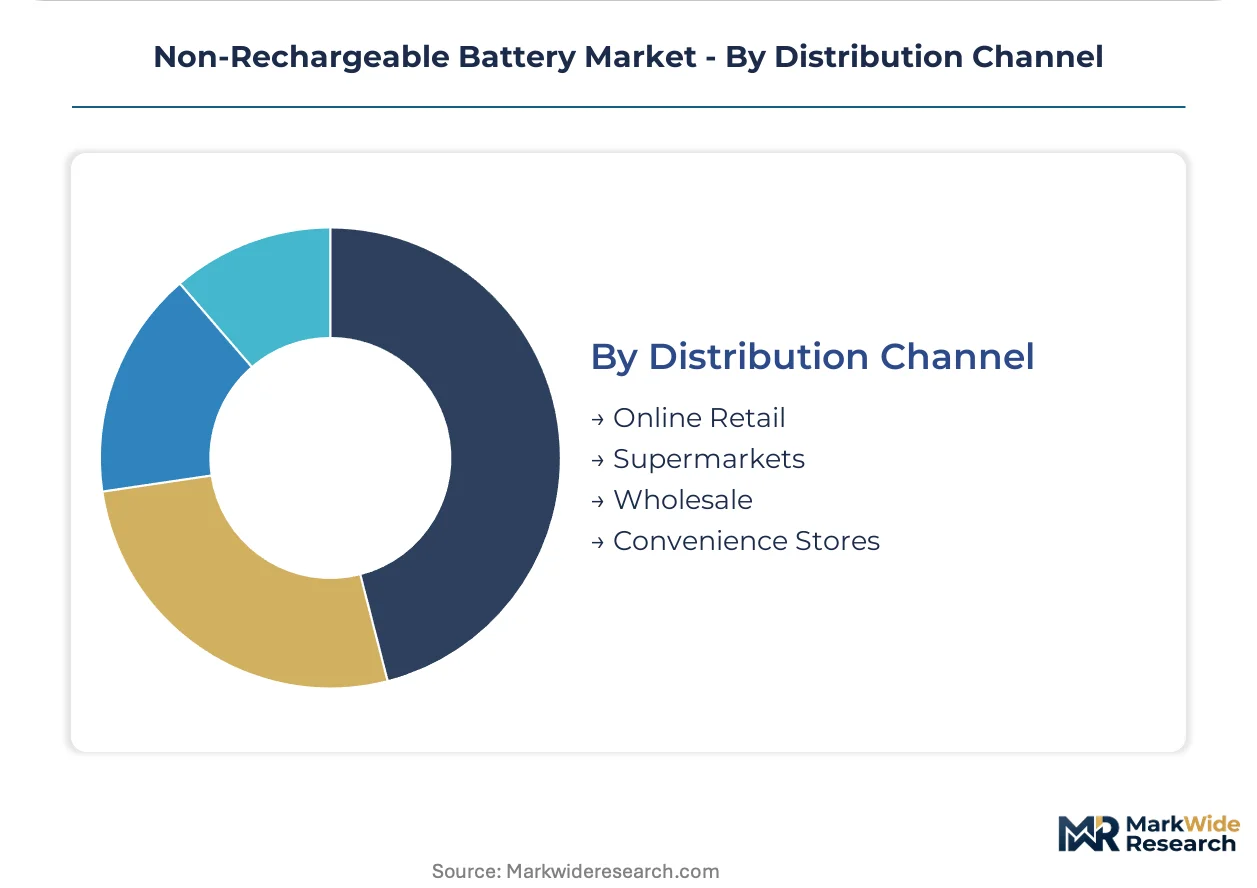
Distribution Channel:
Supply concentration and margin structure diverge between centralized fulfillment platforms and geographically dispersed physical retail networks.
- Online Retail:E-commerce platforms and direct manufacturer storefronts enabling specification comparison and bulk procurement. Amazon and specialized industrial marketplaces serve German and US customers with long-shelf-life inventory and documented compliance certifications.
- Supermarkets:Mass-market retail chains with high-frequency foot traffic and impulse purchase dynamics. UK and French supermarket operators leverage private label alkaline programs against branded competitors while facing margin pressure from rechargeable alternatives.
- Wholesale:Industrial distributors and electronics component specialists serving OEM procurement with volume pricing and technical support. German and Japanese wholesalers maintain regional inventory positions to serve just-in-time manufacturing requirements.
- Convenience Stores:Small-format retail with limited SKU breadth targeting immediate replacement needs. Urban convenience networks in Japan and South Korea stock standardized alkaline formats for consumer electronics emergencies.
Transaction volume concentrates in Supermarkets; Online Retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium carbonate deposits in Chile's Atacama Desert and cobalt mining operations in the Democratic Republic of Congo anchor raw material flows for primary cell manufacturing. These feedstocks reach East Asian processing hubs before conversion into finished electrochemical cells.
United States
Medical device OEMs in Massachusetts and Minnesota specify hermetically sealed lithium manganese dioxide cells for implantable cardiac equipment. FDA device-level battery safety requirements mandate documented lot traceability through supply chain tiers. Boston-area manufacturers negotiate directly with Japanese cell producers for multi-year supply agreements.
Germany
Industrial IoT sensor networks for chemical processing and oil and gas infrastructure drive lithium thionyl chloride procurement. REACH substance restrictions and RoHS hazardous substance thresholds tighten cadmium prohibitions in battery manufacturing. Stuttgart-based automotive Tier 1 suppliers qualify South Korean cell producers for tire pressure monitoring systems.
China
Consumer electronics contract manufacturers in Shenzhen and Dongguan specify alkaline and lithium-iron disulfide cells for devices targeting European retail distribution. MIIT circular economy directives tighten production waste protocols and material recovery obligations for domestic battery makers. Yangtze River Delta cell winding facilities scale cylindrical capacity for industrial applications.
South Korea
Industrial IoT and medical telemetry demand concentrates lithium thionyl chloride capacity expansion. MFDS medical device regulations align with FDA and CE marking standards for implantable cell qualification. Busan-Ulsan manufacturing clusters serve Norwegian and German sensor network operators with ATEX-certified power sources.
Switzerland
Cardiac rhythm management device manufacturers enforce EMA submission packages requiring automated production line validation. Swissmedic medical device regulations mandate hermetic sealing documentation for implantable primary cells. Zurich-area OEMs qualify precision winding equipment with machine vision feedback for FDA-compliant lot release.
Non-Rechargeable Battery Market Competitive Landscape
Global majors compete with regional champions across chemistry specialization and distribution channel control. The vendor base organizes into three tiers: mass-market alkaline producers with retail shelf dominance, lithium chemistry specialists serving medical and industrial qualification-intensive segments, and East Asian volume manufacturers capturing industrial IoT scale opportunities. Competitive moves center on direct procurement platform development and automated production line validation for regulatory submission packages.
Within the mass-market alkaline tier, Duracell and Energizer Holdings occupy positions defined by retail channel control and brand recognition across North American and European supermarket networks. Panasonic Corp. represents the diversified industrial conglomerate archetype, spanning consumer alkaline volume and specialized medical supply. Among lithium chemistry specialists, Saft Groupe S.A. and Tadiran Batteries exemplify the qualification-intensive segment serving military, aerospace, and industrial IoT applications with extended operational lifespan specifications.
| Leading Market Players |
|---|
| Duracell |
| Energizer Holdings |
| Panasonic Corp. |
| VARTA AG |
| EVE Energy Co., Ltd. |
| Maxell Holdings, Ltd. |
| Saft Groupe S.A. |
| Tadiran Batteries |
| Renata S.A. |
| Others |
Pricing and Supply Chain Analysis
Battery-grade lithium carbonate spot indices cascade through cylindrical cell production economics, compressing margins for lithium thionyl chloride formats while alkaline zinc-manganese dioxide cells absorb volatility through volume scale and retail channel absorption.
Pricing Analysis
Warranty-backed lot traceability commands premium positioning in medical-grade procurement, while unbundled commodity cells compete on shelf-turn velocity. Three-tier pricing structure across premium, standard, and economy levels separates hermetically sealed implantable cells with FDA submission packages from industrial IoT formats with ATEX pre-certification and mass-market alkaline with basic shelf-life guarantees. Pricing pressure stems from rechargeable lithium-ion substitution in high-drain consumer devices. Retail households exhibit highest price sensitivity; cardiac implantable electronic device OEMs demonstrate lowest elasticity due to qualification lock-in.
Supply Chain Analysis
Reverse-logistics flows for spent lithium primary cells remain underdeveloped outside German and Dutch formal recycling infrastructure, creating compliance cost accumulation for EU pack assemblers. Cylindrical winding and electrolyte filling capacity concentrates in China, South Korea, and Japan. Production draws from Chilean lithium carbonate and DRC cobalt feedstocks processed through East Asian chemical conversion facilities. Single-source vulnerability clusters in Yangtze River Delta cell winding operations. Distribution runs through direct procurement platforms for medical OEMs and fragmented wholesale channels for industrial MRO.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where EU Battery Regulation material disclosure mandates erect barrier-to-entry moats favoring incumbents with pre-certified supply chain documentation.
For Market Incumbents: Deploy automated production line validation to compress FDA and EMA lot release cycles from weeks to days. Fortify position by securing multi-year direct supply agreements with Massachusetts and Swiss cardiac device OEMs before qualification windows close. Counter rechargeable substitution threats through extended shelf-life guarantees in industrial IoT segments. For New Entrants and Emerging Players: The premium-to-economy price gap in lithium thionyl chloride industrial formats offers white-space entry for ATEX-certified specialists. Target Indian medical device manufacturing as CDSCO-FDA harmonization enables domestic implantable cell production for South Asian markets. Pursue direct-to-industrial distribution platforms with lot-traceable inventory systems as the primary go-to-market angle. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision winding equipment manufacturers with machine vision capabilities in German and Swiss manufacturing hubs. Long-term viability across the projection horizon rests on regulatory compliance infrastructure rather than commodity scale. Monitor UN 38.3 certification timeline compression as inflection signal for supply-constrained seasonal demand cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Production Line Validation | Swiss and German medical OEMs compress FDA submission packages from weeks to days. |
| Direct Procurement Platform Development | Industrial distributors bypass traditional electronics channels to serve Norwegian sensor networks. |
| ATEX Pre-Certification Investment | South Korean producers capture German chemical processor safety system specifications. |
| Backward Integration into Lithium Feedstock | Cell manufacturers secure Chilean carbonate offtake to buffer price volatility exposure. |
| REACH Compliance Dossier Consolidation | European pack assemblers document full material composition through supply chain tiers. |
Research Methodology
SEC 10-K filings, EU Battery Regulation implementation guidance, and customs trade data formed the secondary backbone, cross-referenced with primary interviews across cell production engineers, medical device procurement managers, industrial IoT OEM technical directors, and German distributor inventory planners. Bottom-up cell production capacity tallies triangulated against top-down application demand estimates.
Historical trendline analysis tracked lithium carbonate price volatility patterns and cylindrical cell production scale trajectories across the analysis window. Segmentation dimensions modeled include chemistry format, application reliability tier, procurement channel structure, and regional regulatory cluster. CAGRs derived from slope-intercept projection of validated demand inflection points, incorporating medical device electrification rates and industrial IoT sensor deployment curves.
Inputs from South Korean MFDS filings and Swissmedic device registrations were available through the study window; gaps in Chinese MIIT circular economy enforcement data introduce uncertainty bands around domestic production waste protocol estimates. Forecasts reflect documented assumptions on regulatory timeline adherence and raw material price trajectory stability. Practitioners should monitor EU Battery Regulation recycled content threshold implementation and UN 38.3 certification queue lengths for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Redox Flow Battery Market
Batteries
East Africa Battery Market
Batteries
Automotive Starting Battery Market
Batteries
Alkaline Battery Market
Batteries
Bio Based Battery Market
Batteries
North Europe Battery Market
Batteries
Vanadium Redox Batteries Market
Batteries
Middle East and Africa Rechargeable Battery Market
Batteries
South America Consumer Battery Market
Batteries
Proton Battery Market
Batteries
Military Battery Market
Batteries
Portable Battery Station Market
Batteries
Nuclear Battery Sales Market
Batteries
Battery Light Towers Market
Batteries
Disposable Batteries Market
Batteries
Lithium Carbon Monofluoride Battery Market