
 Global Marine Battery Market | 2026-2036
Global Marine Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Global Marine Battery Market Foresight
Passenger ferry electrification is restructuring procurement patterns across coastal shipping networks. Corvus Energy dominates Nordic retrofit programs with its liquid-cooled lithium-ion architecture. Wärtsilä Oyj Abp leverages its hybrid integration expertise to anchor large-vessel contracts in the Mediterranean basin. Saft Groupe S.A. sustains defense-sector relationships through specialized nickel-cadmium systems for naval submarines.
Marine batteries are electrochemical energy storage systems engineered for saltwater environments, typically featuring IP67-rated enclosures and vibration-resistant cell packaging to survive hull-mounted installation. These systems power electric propulsion, hotel loads, and dynamic positioning across vessels ranging from 10-meter harbor craft to 150-meter ro-pax ferries. Lithium-ion chemistry leads installed capacity due to its energy density advantage over lead-acid alternatives in weight-sensitive applications. Sealed AGM technology occupies the aftermarket retrofit segment where crew familiarity and charging infrastructure compatibility matter more than cycle-life optimization. Nickel-cadmium cells persist in naval specifications where NATO STANAG compliance and deep-discharge tolerance override cost considerations.
The International Maritime Organization's Carbon Intensity Indicator is forcing fleet operators to document propulsion efficiency gains, while the EU Green Deal's Fit for 55 package extends emissions trading to maritime routes calling at European ports. The EPA's marine diesel engine standards in the United States create parallel pressure for harbor craft electrification in California and Washington state ports. Stakeholders must track how battery safety regulations evolve at the flag-state level, as classification societies rewrite rules for thermal runaway containment in below-deck installations.
Market Dynamics
The EU Green Deal's maritime emissions mandates are compressing fleet procurement timelines, forcing harbor authorities to mandate shore power and zero-emission propulsion standards across European coastal shipping corridors.
Growth Catalysts
- EU Green Deal Fit for 55:The EU Green Deal extends emissions trading to maritime routes calling at European ports, compelling ferry operators to accelerate battery-electric retrofits on Baltic Sea and Norwegian fjord routes.
- Lithium-ion energy density gains:Advances in liquid-cooled lithium-ion architecture enable longer route electrification for 150-meter ro-pax ferries previously constrained by weight and volume limitations.
- Harbor craft electrification:EPA marine diesel engine standards in California and Washington state ports are driving demand for battery systems in tugboats and pilot vessels operating in emission-controlled zones.
Market Restraints
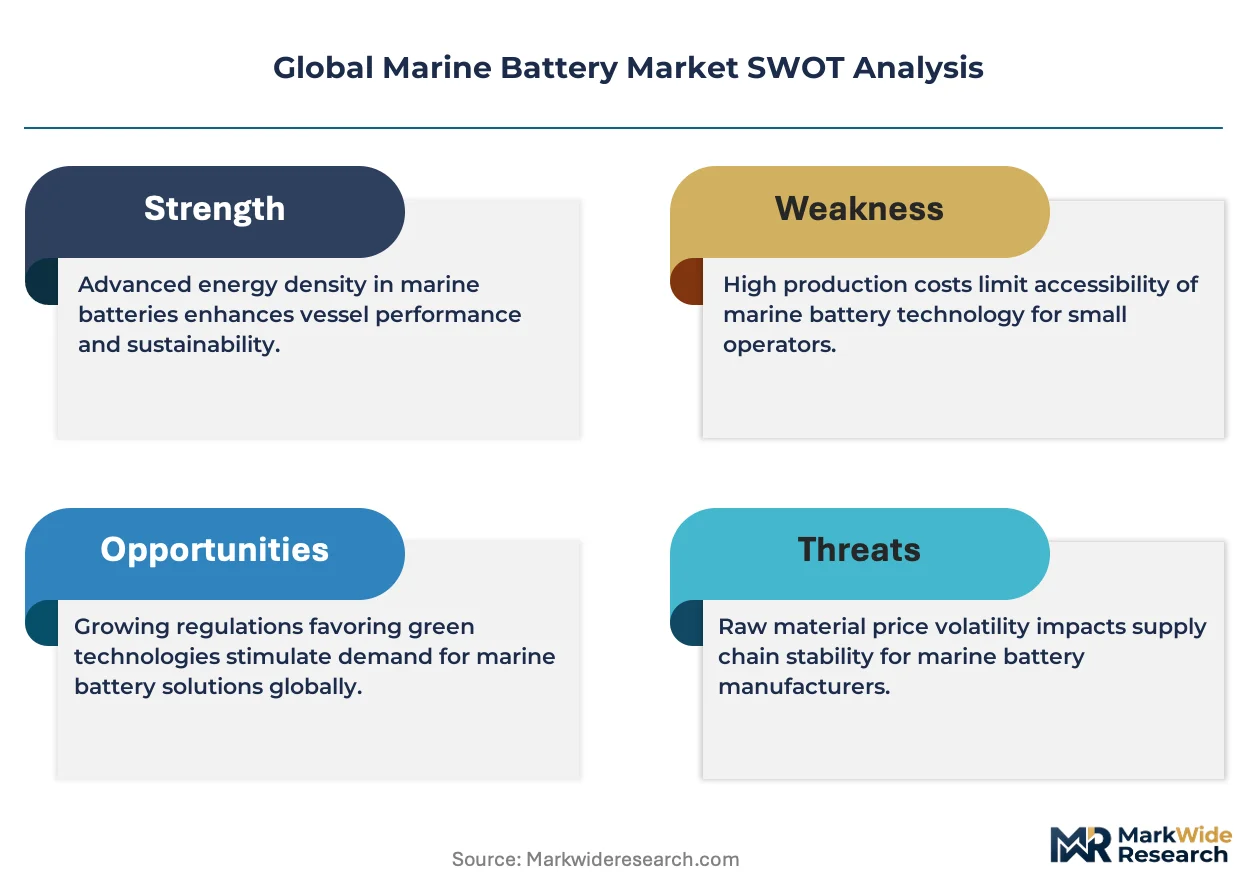
- Cathode material cost volatility:Lithium carbonate and nickel price swings inflate battery pack costs, squeezing margins for shipyards bidding on fixed-price electrification contracts.
- Cell supplier concentration:Production of high-grade marine lithium cells clusters in East Asian manufacturing hubs, exposing European and North American integrators to logistics bottlenecks and tariff exposure.
- Thermal runaway containment standards:Classification societies have yet to harmonize below-deck battery installation rules, forcing redundant engineering and delaying flag-state approvals.
Strategic Opportunities
- Indian coastal shipping electrification:The country's national shipping regulator is evaluating emission norms for short-sea routes connecting Gujarat and Tamil Nadu ports, creating first-mover potential for battery system providers.
- Hybrid-tugboat applications:Converging dynamic positioning automation with high-cycle battery systems opens a specialized segment in offshore support vessel fleets.
- Shore power infrastructure mandates:EU port authority regulations requiring cold-ironing capability are integrating battery storage into terminal electrical systems, expanding addressable market beyond vessel propulsion.
Industry Challenges
- Marine electrical engineering talent scarcity:Shipyards lack sufficient naval architects trained in high-voltage DC system integration, extending project timelines and inflating labor costs.
- Classification society certification timelines:Bureau Veritas and DNV type-approval processes for novel battery chemistries stretch 18-24 months, misaligning with fleet operators' compressed retrofit schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Marine Battery Market |
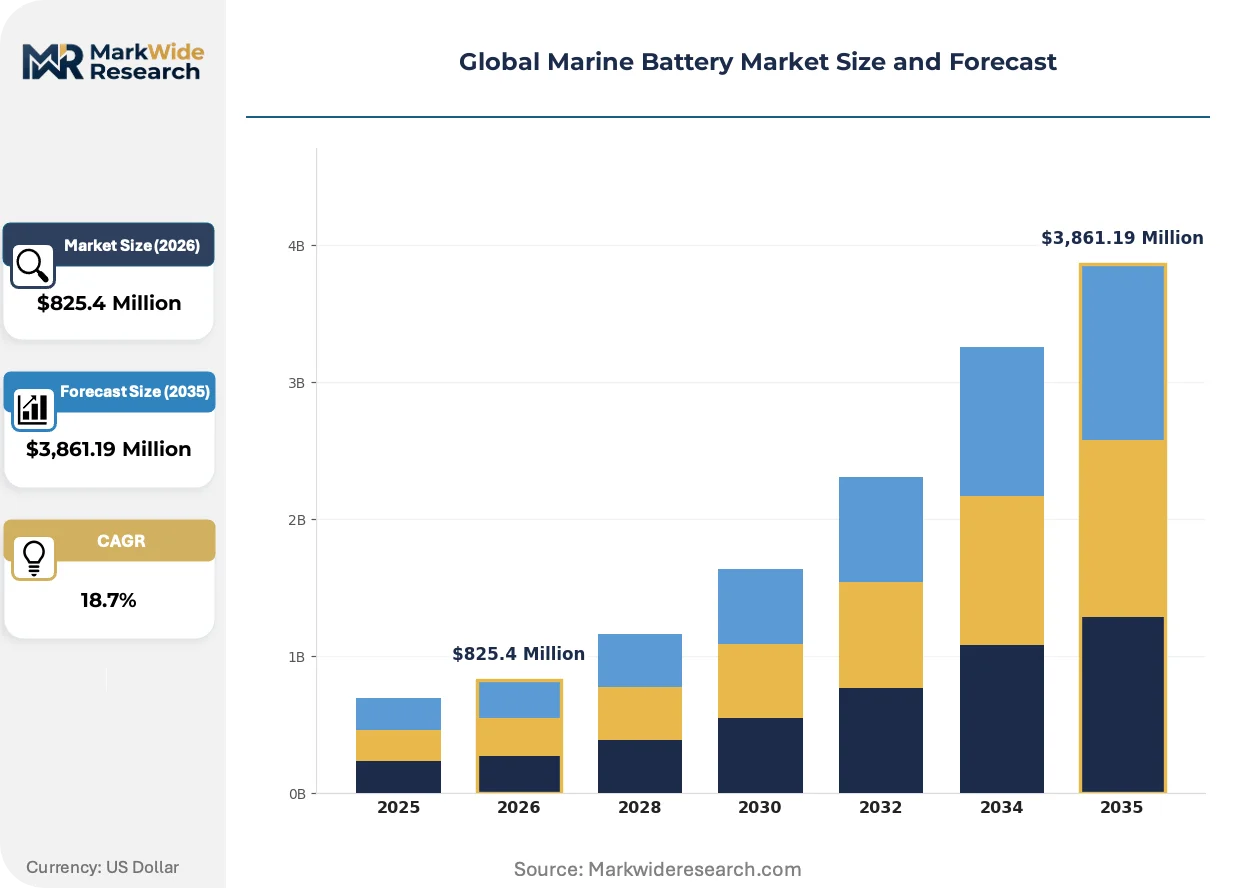
| Market Size in 2026 | $825.4 Million |
| Market Size in 2035 | $3,861.19 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lead Acid, Lithium Ion, Nickel Cadmium, Zinc Air, Silver Zinc Application: Recreational Boats, Commercial Fishing, Naval Vessels, Passenger Ferries, Survey Vessels Technology: Flooded Battery, Sealed AGM, Gel Cell, Lithium Polymer, Enhanced Flooded Battery End User: Marine Operators, Boat Builders, Ship Repair Yards, Offshore Service Providers, Leasing Companies |
| Companies Covered | Corvus Energy, EnerSys, Leclanché SA, Siemens Energy, Akasol AG, Saft Groupe S.A., GS Yuasa Corporation, Toshiba Corporation, Wärtsilä Oyj Abp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Marine Battery Market Shifts & Advancements
Solid-state and sodium-ion chemistries are entering marine qualification pipelines, while digital twin technology is reshaping how battery performance gets validated before hull installation.
Solid-state battery architectures are integrating ceramic electrolyte layers that eliminate flammable liquid components, satisfying classification society fire-safety thresholds for below-deck installations. Norwegian ferry operators are piloting these systems on 50-meter harbor craft to compress insurance premium differentials against conventional lithium-ion. The technology is integrating thermal management simplification that reduces auxiliary system weight by fifteen percent versus liquid-cooled alternatives.
REACH chemical substance restrictions are forcing cell manufacturers to reformulate electrolyte solvents and binder materials, triggering supply chain requalification across European battery assembly plants. The regulation is compressing approval timelines for imported battery packs that cannot demonstrate full material disclosure. Mediterranean ferry operators are responding by sourcing from EU-based integrators with established substance compliance documentation.
Leasing-based battery service models are displacing outright purchase in Nordic ferry fleets, transferring cycle-life risk and residual value exposure to system providers. Corvus Energy and Wärtsilä are anchoring this shift through power-by-the-hour contracts on Oslofjord commuter routes. Shipowners in Norway's coastal network are consolidating vendor relationships around integrators offering bundled maintenance and shore power compatibility guarantees.
Global Marine Battery Market Segmentation
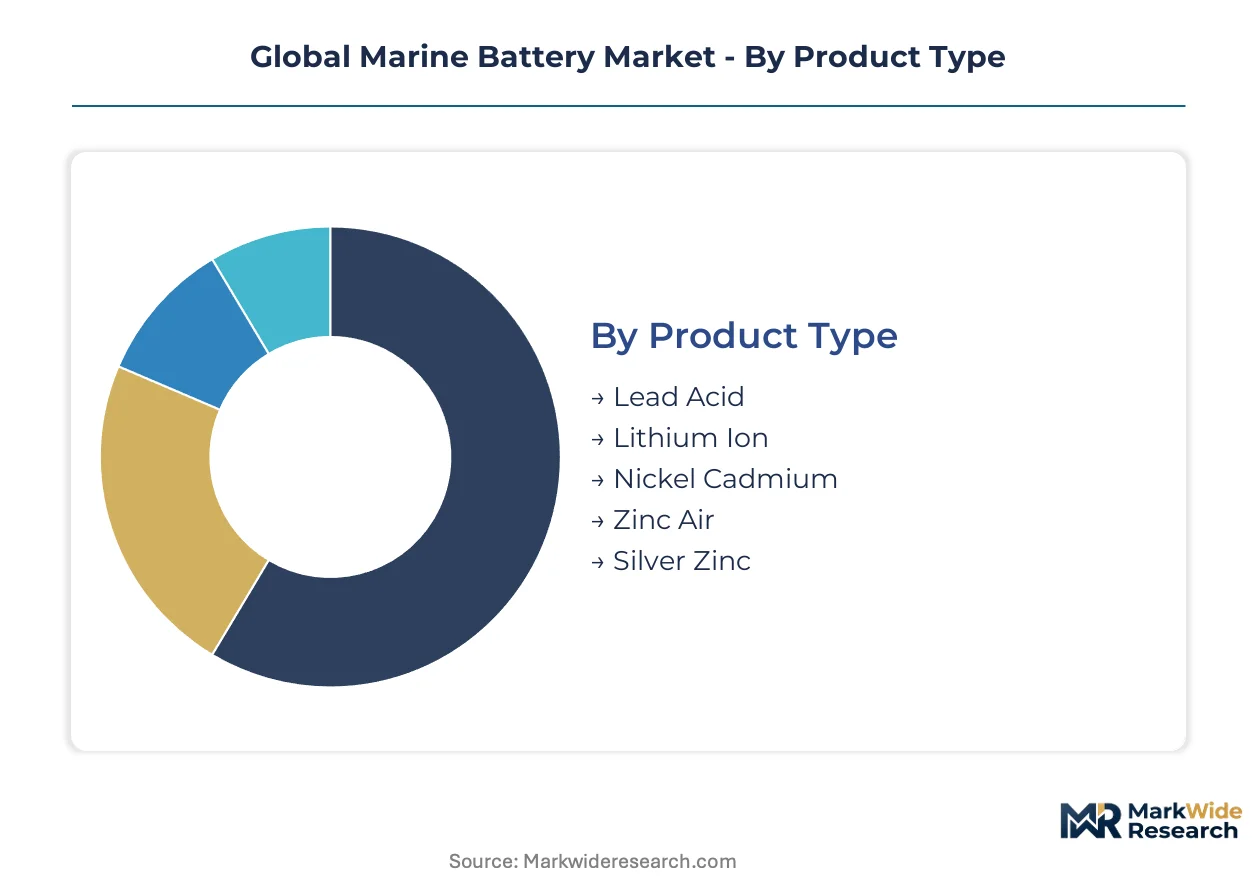
Marine battery procurement diverges sharply between retrofit operators seeking chemistry swaps and newbuild yards specifying integrated energy systems. Understanding these segment boundaries clarifies where margin concentrates versus where price competition dominates.
Product Type:
Standalone battery systems dominate harbor craft and small-vessel retrofits, while embedded lithium-ion architectures anchor integrated hybrid propulsion on newbuild ferries.
- Lithium Ion:Liquid-cooled NMC and LFP chemistries deliver 150-250 Wh/kg energy density for weight-sensitive electric propulsion. Norwegian fjord ferries and Baltic Sea short-sea routes are concentrating procurement here, driven by EU Green Deal emissions mandates and route electrification feasibility studies.
- Lead Acid:Flooded and sealed AGM variants persist in cost-driven aftermarket replacement cycles for harbor tugs and pilot boats. Demand clusters in Mediterranean and Southeast Asian ports where charging infrastructure remains limited and crew familiarity outweighs cycle-life advantages.
- Nickel Cadmium:NATO STANAG-compliant deep-discharge tolerance sustains naval submarine specifications despite cadmium toxicity restrictions under REACH.
- Zinc Air:Experimental marine variants target ultra-long-duration auxiliary power for oceanographic survey platforms with infrequent port calls.
- Silver Zinc:Premium energy density for torpedo and underwater vehicle propulsion in defense applications with single-use mission profiles.
Lithium ion leads volumes today; zinc air is gaining share fastest among emerging chemistries.
Application:
Route predictability determines electrification economics, with fixed-schedule operations outpacing irregular deployment patterns in battery adoption.
- Passenger Ferries:Fixed-route operations with predictable duty cycles enable precise battery sizing for 50-150 meter ro-pax vessels. Electrification concentrates on Norway's coastal network and Finland-Estonia corridors where shore power infrastructure and government subsidies align.
- Naval Vessels:Silent running requirements and combat system redundancy specifications drive nickel-cadmium and silver-zinc procurement for submarines and surface combatants. Procurement cycles extend 8-12 years with classified performance thresholds.
- Commercial Fishing:Variable trip durations and limited deck space constrain battery economics; hybrid installations concentrate in North Sea freezer trawlers subject to port emissions regulations.
- Recreational Boats:Weekend usage patterns favor drop-in lithium retrofits for sailing yachts and cabin cruisers in Mediterranean charter fleets.
- Survey Vessels:Low-noise requirements for seismic and hydrographic operations favor battery-diesel hybrid configurations in offshore energy exploration.
Passenger ferries anchor current revenue; naval vessels sustain the longest contract visibility.
Technology:
Cell packaging and electrolyte immobilization separate marine-grade systems from automotive hand-me-downs, with thermal management architecture driving total system cost.
- Sealed AGM:Absorbent glass mat construction eliminates spillage risk and enables 360-degree installation orientation for engine-room retrofits. Mediterranean and Black Sea operators favor this technology for crew familiarity and existing charger compatibility.
- Lithium Polymer:Pouch-cell architectures enable custom form factors for constrained hull compartments in high-performance racing yachts and military special operations craft.
- Flooded Battery:Lowest capital cost for backup power on cargo vessels with ample ventilation and maintenance crew capacity.
- Gel Cell:VRLA construction with silica-thickened electrolyte resists vibration in planing hulls and rigid inflatable boats.
- Enhanced Flooded Battery:Carbon-additive plates improve partial state-of-charge cycling for start-stop hybrid applications on coastal patrol craft.
Sealed AGM dominates installed base; lithium polymer shows steepest expansion trajectory in specialized applications.
End User:
Procurement authority fragmentation—between vessel owners, charterers, and repair yards—creates multiple decision nodes with divergent technical priorities.
- Boat Builders:Newbuild specifications lock in battery chemistry for 15-20 year vessel lifecycles, with Nordic yards integrating shore power compatibility as standard.
- Marine Operators:Fleet managers balance capital constraints against fuel savings, with state-owned ferry corporations in Scandinavia and British Columbia leading electrification commitments.
- Ship Repair Yards:Retrofit demand concentrates in ports with drydock capacity and classification society surveyor presence; Hamburg, Singapore, and Vancouver clusters dominate.
- Offshore Service Providers:Dynamic positioning redundancy requirements drive battery specifications for platform supply vessels in North Sea and Gulf of Mexico markets.
- Leasing Companies:Power-by-the-hour contracts transfer residual value risk to integrators, with Corvus Energy and Wärtsilä anchoring this model in Nordic commuter routes.
Boat builders capture highest-margin newbuild specifications; leasing companies are restructuring procurement fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping marine battery manufacturing footprints as integrators relocate assembly to jurisdictions with streamlined classification society approvals and subsidized shore power infrastructure. Cost-of-compliance gaps between flag states are accelerating contract migration toward Nordic and Baltic Sea jurisdictions.
Norway
Oslofjord commuter routes and Geiranger fjord cruise corridors are driving procurement for liquid-cooled lithium-ion retrofits. The Norwegian Maritime Authority mandates zero-emission operation in UNESCO World Heritage waterways by 2026. Bergen and Stavanger shipyards are concentrating battery system integration capacity for ro-pax ferries serving Denmark and Germany.
Germany
Baltic Sea short-sea shipping operators face EU Green Deal emissions trading compliance deadlines for routes calling at Rostock and Lübeck. The Federal Maritime and Hydrographic Agency enforces IMO Carbon Intensity Indicator documentation requirements. Hamburg's drydock cluster is anchoring retrofit demand for harbor tugs and pilot vessels operating in North Sea emission-controlled zones.
United States
California Air Resources Board regulations are compressing procurement timelines for harbor craft electrification in Los Angeles and Long Beach ports. Washington state's Department of Ecology mandates shore power connection for vessels at Seattle and Tacoma terminals. Pacific Northwest shipyards are integrating battery-diesel hybrid systems for offshore support vessels serving Gulf of Alaska fisheries.
China
Yangtze River Delta port authorities are piloting battery-electric container feeders for Shanghai-Ningbo shuttle routes. The Ministry of Ecology and Environment enforces domestic emission control area standards for coastal shipping. Zhoushan and Ningbo shipbuilding clusters are scaling lithium cell assembly for export to Southeast Asian ferry operators.
India
Gujarat and Tamil Nadu port connectivity is attracting feasibility studies for short-sea route electrification. The Directorate General of Shipping evaluates emission norms for coastal vessels under the Sagarmala port modernization program. Mumbai and Cochin repair yards are positioning for battery retrofit contracts on offshore supply vessels operating in Arabian Sea oilfields.
Global Marine Battery Market Competitive Landscape
Strategic partnerships dominate the current landscape as battery integrators align with shipyards and classification societies to compress certification timelines. The vendor base clusters around three tiers: Nordic specialists with proven fjord ferry deployments, diversified industrial conglomerates leveraging hybrid propulsion expertise, and Asian cell manufacturers supplying standardized packs to regional integrators. Geographic expansion and technology licensing represent the primary competitive vectors as players seek flag-state approval reciprocity.
Among Nordic specialists, Corvus Energy anchors the liquid-cooled lithium-ion segment with established Oslofjord commuter route presence. Wärtsilä Oyj Abp occupies a position bridging marine engine heritage with hybrid integration capabilities across Mediterranean newbuild contracts. Saft Groupe S.A. exemplifies the defense-sector archetype through NATO STANAG-compliant nickel-cadmium systems for naval submarine specifications.
| Leading Market Players |
|---|
| Corvus Energy |
| EnerSys |
| Leclanché SA |
| Siemens Energy |
| Akasol AG |
| Saft Groupe S.A. |
| GS Yuasa Corporation |
| Toshiba Corporation |
| Wärtsilä Oyj Abp |
| Others |
Supply & Pricing Matrix
EU Green Deal maritime emissions mandates gate qualified supply for premium-tier battery systems, compressing procurement timelines for ferry operators while elevating certification costs that separate DNV-approved integrators from commodity pack assemblers. Shipyards bidding on Baltic Sea and Norwegian fjord retrofits face margin compression where cathode material volatility meets fixed-price contract structures.
Pricing Analysis
Direct-to-OEM discount structures dominate large-vessel contracts, with project-based pricing anchoring integrated hybrid propulsion systems for 150-meter ro-pax ferries. Price differentiation hinges on DNV type-approval status and liquid-cooled architecture performance guarantees. Cost compression in standard-grade lithium packs is intensifying because East Asian cell oversupply is feeding into European integrator margins. Harbor craft operators in Mediterranean ports exhibit highest price sensitivity, while state-owned Scandinavian ferry corporations absorb premium pricing for shore power compatibility guarantees.
Supply Chain Analysis
DNV and Bureau Veritas certification timelines stretch 18-24 months, gating supply access for novel solid-state chemistries and compressing vendor qualification pipelines. High-grade marine lithium cell production concentrates in China, South Korea, and Japan, drawing from lithium carbonate, nickel sulfate, and electrolyte solvent feedstocks. Single-source vulnerability runs through East Asian cathode active material suppliers, exposing European integrators to logistics bottlenecks and tariff exposure. Distribution runs through Hamburg, Singapore, and Vancouver shipyard clusters where drydock capacity and classification society surveyor presence anchor retrofit demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marine battery procurement operates as a geographic-arbitrage play where EU Green Deal compliance costs in Nordic waters diverge sharply from emerging-market regulatory lag in Indian coastal shipping corridors.
For Market Incumbents: Anticipate sodium-ion and solid-state chemistry disruption by accelerating DNV pre-qualification for ceramic electrolyte architectures before classification society rules harmonize. Defensive consolidation through backward integration into cell assembly in Poland or Estonia reduces tariff exposure and compresses approval timelines for REACH-compliant packs.
For New Entrants and Emerging Players: Launch via power-by-the-hour leasing models in Gujarat-Tamil Nadu short-sea corridors where India's Sagarmala port modernization program is evaluating emission norms without mature incumbent presence. Target survey vessel hybrid applications where low-noise requirements and infrequent port calls favor experimental zinc-air auxiliary systems with minimal certification baggage.
For Investors and Strategic Acquirers: Roll-up economics work for Nordic battery service specialists because fragmented ferry operator ownership concentrates vendor consolidation pressure around bundled maintenance and shore power compatibility guarantees. Acquisition target archetype: mid-cap integrators with established Oslofjord route presence and DNV type-approval reciprocity in Germany. Signal to watch: Indian Directorate General of Shipping emission norm finalization triggering first-mover capacity commitments.
| Strategic Initiative | Industry Significance |
|---|---|
| DNV Type-Approval Acceleration | Compresses 18-24 month certification timelines for solid-state marine chemistries before rules harmonize. |
| Backward Integration into Cell Assembly | Captures margin and reduces East Asian logistics exposure for European integrators serving Baltic routes. |
| Power-by-the-Hour Leasing Expansion | Transfers cycle-life risk to providers while locking in Oslofjord and Mediterranean ferry operator relationships. |
| Shore Power Infrastructure Bundling | Integrates battery storage into terminal electrical systems beyond vessel propulsion in EU port mandates. |
| Indian Coastal Route Pilot Programs | Positions first-mover advantage ahead of Sagarmala emission norm finalization in Gujarat-Tamil Nadu corridors. |
Research Methodology
Direct dialogue with ferry fleet managers, shipyard procurement directors, classification society surveyors, and port authority electrification planners grounded qualitative findings in operational constraints across Norwegian fjord routes and Baltic Sea corridors. Secondary validation drew from DNV maritime reports, EU Green Deal implementation documents, EPA marine diesel engine standards, and customs trade data for lithium cell imports. Bottom-up vessel-by-vessel retrofit pipeline analysis triangulated against top-down regulatory mandate timelines.
Installed capacity and revenue projections across the analysis window reflect segment-level modeling of lithium-ion, lead-acid, and emerging chemistry adoption curves by vessel class and route predictability. Segmentation dimensions included propulsion architecture, battery chemistry tier, thermal management approach, and regional regulatory cluster. CAGRs derived from weighted scenario analysis of EU emissions trading phase-in schedules and shore power infrastructure deployment curves.
Several conditions sit outside the modeled scope, including unannounced solid-state chemistry breakthroughs, abrupt REACH substance restriction expansions, and flag-state battery safety rule divergences beyond current DNV-Bureau Veritas misalignment. A model refresh is warranted upon material change in EU Green Deal maritime emissions trading implementation timelines or Indian coastal shipping emission norm finalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Custom Battery Pack Market
Batteries
Modular Battery Pack Platforms for Skateboard EVs Market
Batteries
Indonesia and Malaysia Lead Acid Battery Market
Batteries
Sodium Nickel Chloride Battery Market
Batteries
Japan Mobile Battery Market
Batteries
Asia-Pacific Consumer Battery Market
Batteries
South America Primary Battery Market
Batteries
South America Battery Cell Market
Batteries
Netherlands Rechargeable Battery Market
Batteries
High Voltage Battery Market
Batteries
Thin Film and Printed Battery Market
Batteries
Zinc-Manganese Oxide Batteries Market
Batteries
Battery Cell Market
Batteries
All-In-One Solar Storage Battery Market
Batteries
South Asia Battery Market
Batteries
Battery Binders Market