
 Lithium-Ion Manganese Oxide Battery Market | 2026-2036
Lithium-Ion Manganese Oxide Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium-Ion Manganese Oxide Battery Market Insights
Subscription-based battery health monitoring is broadening what suppliers monetize beyond cell sales. BASF leverages its global precursor network to sustain cathode material supply across multiple continents. POSCO Future M anchors Korean manganese oxide production through integrated refining and pCAM capabilities. Shenzhen Dynanonic specializes in high-voltage spinel formulations that differentiate its offering for power-tool and e-bike segments.
Lithium-ion manganese oxide batteries employ a cathode composed of LiMn₂O₄ spinel structures, typically operating at nominal voltages near 3.7-4.0 V with manganese constituting the primary transition metal. These cells serve applications demanding thermal stability, cost efficiency, and reduced cobalt content relative to NMC alternatives. Pouch and prismatic formats capture expanding share in automotive modules where pack-level energy density and form-factor flexibility determine design outcomes. Cylindrical cells retain established positions in consumer electronics and select power-tool lines where manufacturing scale and standardization sustain margin pools.
EU Battery Regulation mandates carbon footprint declarations and recycled content thresholds that reshape material sourcing obligations for suppliers accessing European automotive OEMs. China's NMPA enforces GB standards for thermal runaway propagation, directly influencing cell design and separator specifications in manganese oxide systems. The US IRA domestic content provisions create compliance complexity for cathode producers without North American upstream integration. Stakeholders must monitor how evolving chemistry patents and solid-state hybrid architectures alter manganese oxide's competitive standing against lithium iron phosphate and high-nickel alternatives.
Market Dynamics
The shift from cobalt-dependent cathodes toward manganese-rich formulations is compressing supply chain timelines and forcing cathode producers to secure upstream manganese refining capacity ahead of automotive qualification cycles.
Growth Catalysts
- EU Battery Regulation:Carbon footprint declarations and recycled content mandates are accelerating OEM demand for traceable, low-carbon manganese oxide cathodes in European electric vehicle supply chains.
- Power-tool electrification:Professional-grade cordless equipment manufacturers are specifying high-voltage spinel cells for thermal stability under sustained discharge loads.
- Korean cathode clusters:Integrated refining-to-precursor capabilities in Gwangyang and Pohang are reducing qualification barriers for automotive cell suppliers.
Market Restraints
- Manganese sulfate price volatility:Battery-grade manganese sulfate concentrates in Chinese refining capacity, exposing cathode producers to input cost swings and export quota uncertainty.
- Energy density ceiling:LiMn₂O₄ spinel structures plateau near 120 Wh/kg at cell level, limiting penetration into premium electric vehicle segments where range targets exceed 500 kilometers.
- US IRA domestic content:North American automotive OEMs face compliance complexity sourcing qualifying manganese oxide cathodes without established US-based pCAM or refining infrastructure.
Strategic Opportunities
- India's PLI scheme:Advanced chemistry cell manufacturing incentives are attracting cathode material investments for two-wheeler and stationary storage applications.
- Solid-state hybrid architectures:Manganese oxide cathodes paired with sulfide or oxide solid electrolytes are enabling safer, higher-voltage cell designs for aviation and marine propulsion.
- Subscription-based health monitoring:Battery management system data monetization is creating recurring revenue streams independent of cell hardware sales for fleet operators.
Industry Challenges
- Automotive qualification timelines:Cell-to-pack validation cycles for manganese oxide systems extend 18-24 months, compressing window for chemistry updates within model-year cadences.
- Patent thickets around doping formulations:Intellectual property disputes over nickel-substituted spinel structures are delaying commercialization of next-generation high-voltage variants.
- Separator specification mismatches:Thermal runaway propagation testing under China's GB standards requires ceramic-coated separator investments that strain mid-tier cell producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium-Ion Manganese Oxide Battery Market |
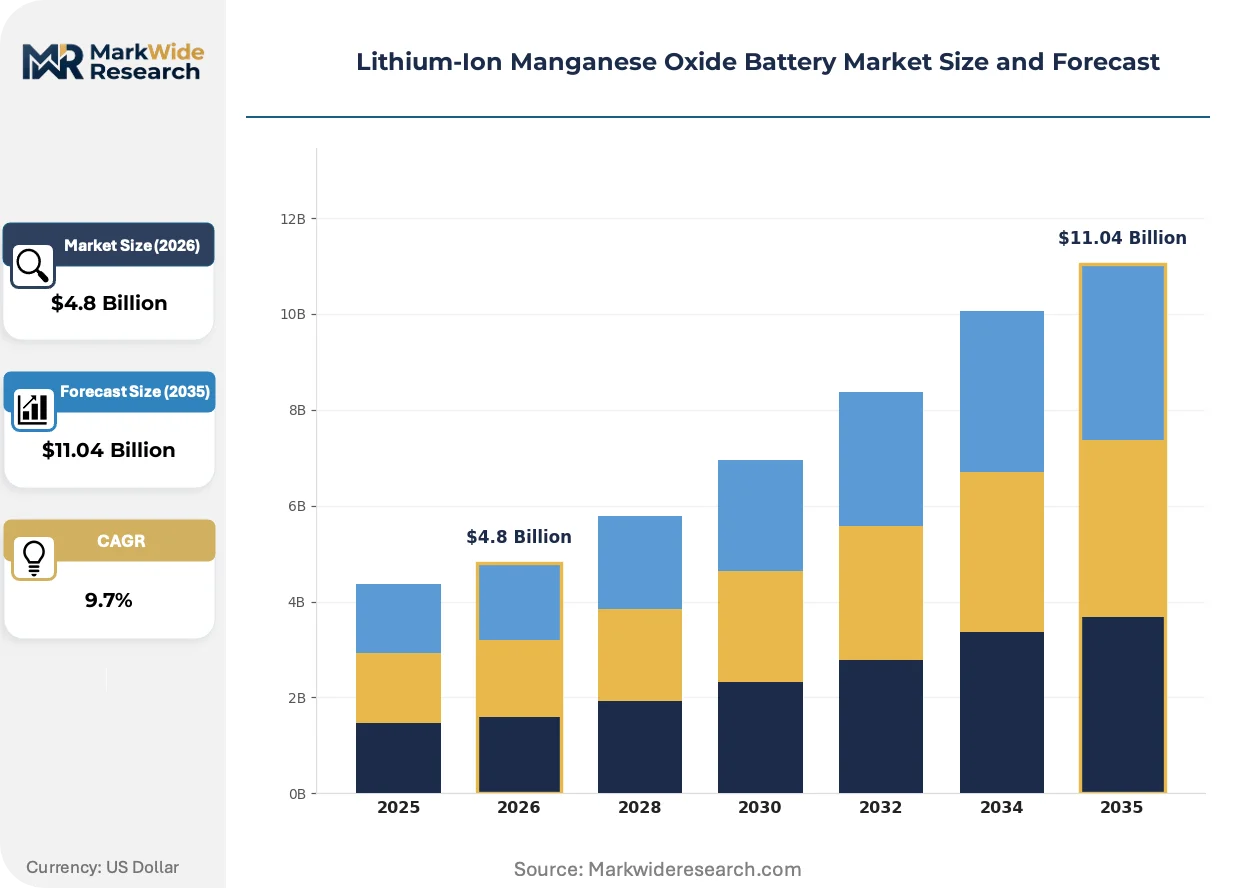
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prismatic, Cylindrical, Coin, Pouch Application: Automotive, Consumer Electronics, Renewable Energy Storage, Medical Devices End User: OEMs, Retail Manufacturers, System Integrators, Energy Utilities Technology: Battery Management System, Thermal Management, Fast Charging, Recycling |
| Companies Covered | LAND CORP., POSCO Future M, BASF, XTC New Energy Materials, Shenzhen Dynanonic, Hunan Yuneng New Energy Battery Materials, Morrow Batteries, Topsoe, 6K Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium-Ion Manganese Oxide Battery Market Trends and Innovations
Active materials engineering and regulatory compliance architectures are converging to redefine how manganese oxide cathodes compete against lithium iron phosphate and high-nickel alternatives across mobility and stationary applications.
High-voltage LiMn₂O₄ spinel doped with nickel or titanium is expanding into premium power-tool and e-bike segments where cycle life requirements exceed 1,000 cycles. Milwaukee Tool and Bosch Professional are qualifying these formulations for 20V and 36V platforms. The chemistry is expanding into niches previously dominated by nickel-manganese-cobalt cells by undercutting cobalt content while matching thermal stability benchmarks.
China's NMPA enforcement of GB 38031 thermal runaway propagation standards is mandating multi-layer separator architectures and cell-level fuse designs in manganese oxide systems. Domestic OEMs including BYD and CATL are redesigning module layouts to contain thermal events within five minutes. The regulation is most compressing design cycles for pouch-format cells in passenger electric vehicles where pack density targets conflict with safety margins.
Fleet operators and energy storage developers are unbundling battery procurement from long-term service contracts, separating hardware ownership from performance guarantees. Independent asset managers are emerging to underwrite cell degradation risk, displacing traditional OEM captive financing in European and North American utility-scale deployments. Germany's KfW green loan programs and US tax equity structures are accelerating this model for grid-scale manganese oxide installations.
Lithium-Ion Manganese Oxide Battery Market Segmentation
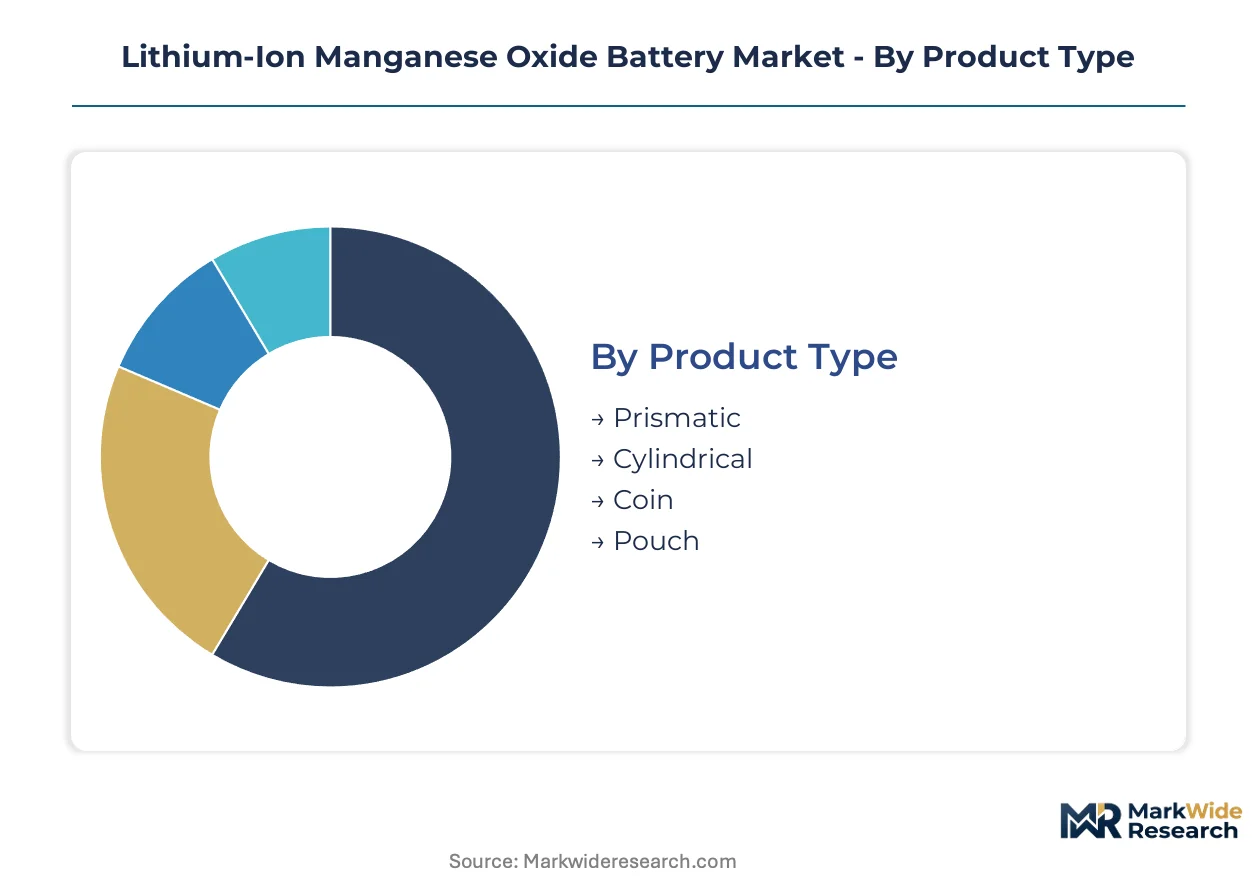
Cell geometry and application requirements dictate procurement patterns across manganese oxide battery supply chains. Automotive qualification cycles and thermal runaway standards are compressing format selection windows for cathode producers.
Product Type:
Manufacturing equipment and electrode coating lines concentrate around prismatic and cylindrical formats, with Asian cell producers anchoring capacity expansion in these geometries.
- Prismatic:Flat rectangular cells with stacked or wound electrode configurations enable high packing efficiency in automotive modules. Korean and Chinese battery makers are scaling prismatic manganese oxide output for European electric vehicle platforms seeking pack-level energy density above 180 Wh/kg.
- Cylindrical:Rolled electrode assemblies in metal cans deliver manufacturing scale and thermal management consistency. Japanese producers retain dominant positions in 18650 and 21700 formats for power-tool and industrial applications where automated assembly lines sustain cost positions.
- Coin:Thin disc-shaped cells with limited capacity serve backup power and memory retention functions in medical and industrial electronics. Swiss and German precision manufacturers specialize in sub-500mAh coin formats where hermetic sealing requirements exceed commodity cell standards.
- Pouch:Flexible laminated foil enclosures maximize volumetric efficiency for space-constrained designs. Chinese cell makers are expanding pouch manganese oxide capacity for e-bike and scooter segments where pack shape adaptability outweighs structural rigidity needs.
Prismatic cells absorb the bulk of installed capacity; pouch formats are expanding most quickly.
Application:
End-use performance requirements fragment cathode procurement across voltage stability, cycle life, and cost tiers.
- Automotive:Module and pack designs for electric vehicles demand manganese oxide cathodes with enhanced thermal stability under sustained high-rate discharge. Korean automotive OEMs are qualifying nickel-doped spinel variants for urban delivery vehicles where range targets stay below 400 kilometers.
- Consumer Electronics:Portable computing and communication devices prioritize volumetric energy density and low self-discharge. Japanese and Taiwanese electronics brands specify high-voltage spinel cells for laptop battery packs where cobalt content reduction supports sustainability marketing claims.
- Renewable Energy Storage:Grid-connected battery systems require manganese oxide cells with calendar life exceeding 15 years and minimal capacity fade. German and Italian utility developers are deploying containerized manganese oxide installations for frequency regulation services where capital cost sensitivity exceeds energy density requirements.
- Medical Devices:Implantable and portable diagnostic equipment mandates exceptional reliability and biocompatibility certification. FDA and European MDR compliance pathways restrict supplier pools to established Japanese and Swiss cell producers with dedicated medical-grade production lines.
Automotive applications command the largest cathode volume commitments; renewable energy storage is climbing the fastest.
End User:
Procurement authority and technical specification control vary sharply across downstream business models.
- OEMs:Original equipment manufacturers with captive cell engineering teams define cathode chemistry and format requirements directly. Korean and German automotive OEMs are consolidating manganese oxide supplier bases to three qualified partners per region to streamline qualification overhead.
- Retail Manufacturers:Third-party battery pack assemblers serving aftermarket and specialty equipment channels source cells through distributor networks. Chinese and Vietnamese pack makers are expanding manganese oxide procurement for replacement power-tool batteries where price positioning determines market access.
- System Integrators:Turnkey energy storage and microgrid developers specify complete battery systems including thermal and power conversion equipment. Indian and Australian integrators are tendering manganese oxide-based storage for rural electrification projects where import logistics favor established Asian cell suppliers.
- Energy Utilities:Regulated power companies with long-term asset ownership models prioritize degradation warranties and operational service agreements. French and Spanish utilities are structuring 10-year performance contracts for grid-scale manganese oxide installations with guaranteed capacity retention thresholds.
OEMs concentrate the highest cathode specification authority; system integrators are gaining procurement influence fastest.
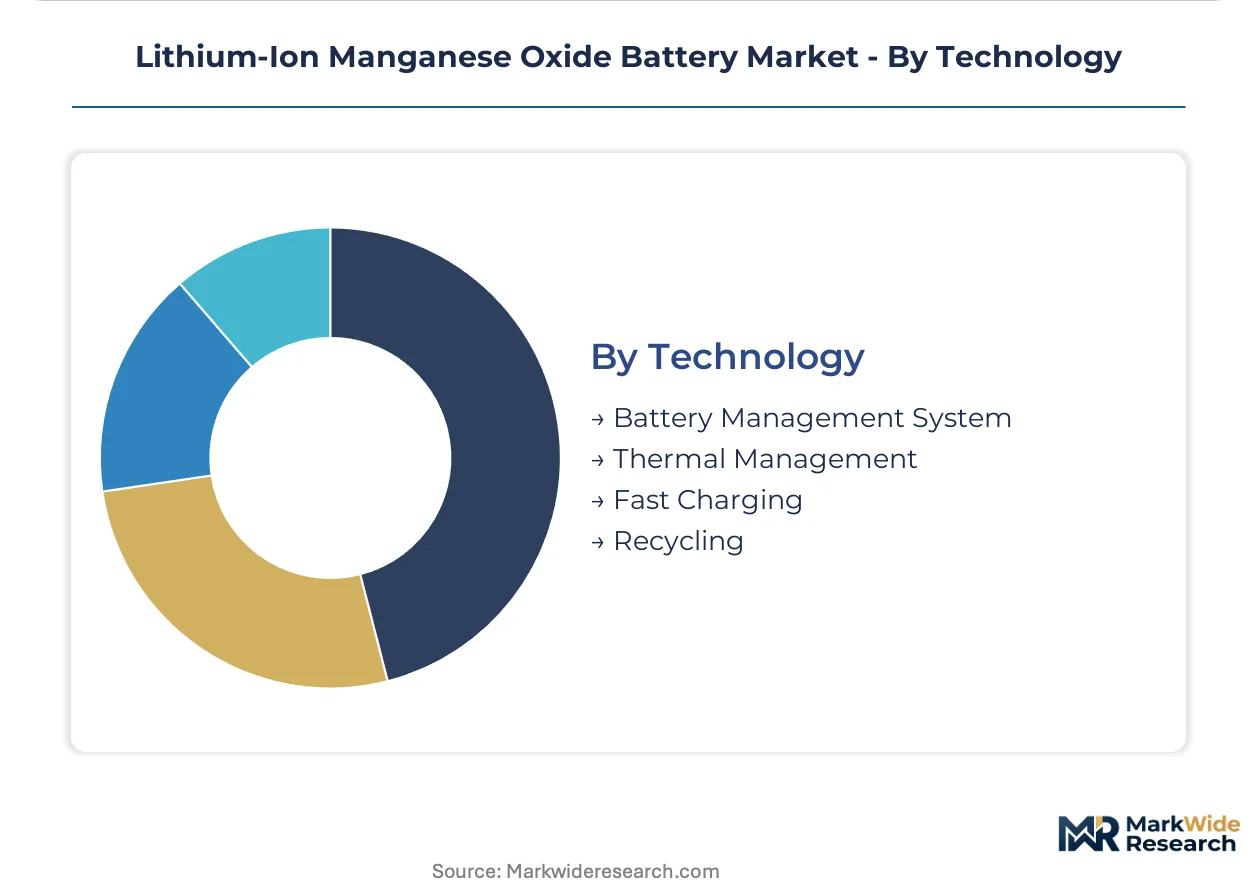
Technology:
Intellectual property and engineering talent pools concentrate in battery management and thermal control subsystems.
- Battery Management System:Cell monitoring and balancing electronics determine manganese oxide pack safety margins and usable lifetime. Korean semiconductor specialists are integrating AI-driven state-of-health prediction into automotive BMS platforms to extend warranty coverage.
- Thermal Management:Active cooling and heating architectures maintain manganese oxide cells within safe operating temperature windows. Chinese and German thermal engineering firms are developing immersion cooling systems for high-power automotive modules where fast charging generates localized hot spots.
- Fast Charging:Electrode and electrolyte modifications enable rapid lithium intercalation without manganese dissolution. Israeli and American startups are commercializing pulse-charging algorithms that mitigate capacity fade in high-voltage spinel cells.
- Recycling:Hydrometallurgical and pyrometallurgical recovery processes reclaim manganese and lithium from end-of-life cells. Belgian and Canadian recyclers are scaling direct recycling pathways that preserve cathode crystal structure for second-life material streams.
Battery Management System technology absorbs the bulk of R&D investment; recycling is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gwangyang anchors Korean manganese oxide cathode production through POSCO Future M's integrated refining complex, while Chinese refining clusters in Guangxi and Guizhou provinces concentrate battery-grade manganese sulfate capacity serving domestic cell makers.
China
Domestic EV manufacturers BYD and CATL are scaling procurement of manganese-rich cathodes for urban delivery fleets. NMPA enforcement of GB 38031 thermal runaway standards is mandating ceramic-coated separators and cell-level fuse designs. Guangxi Zhuang Autonomous Region hosts concentrated manganese sulfate refining corridors supplying precursor material to cathode plants in Fujian and Jiangsu.
South Korea
Automotive OEMs Hyundai and Kia are qualifying nickel-doped spinel variants for compact electric vehicles with sub-400 kilometer range targets. The Ministry of Trade, Industry and Energy's battery R&D subsidies are accelerating domestic pCAM capacity expansion. Gwangyang and Pohang industrial complexes integrate manganese refining with cathode precursor production, reducing qualification barriers for cell suppliers.
Japan
Power-tool manufacturers Makita and Panasonic are specifying high-voltage LiMn₂O₄ cells for professional-grade cordless platforms. METI's battery supply chain resilience programs are funding domestic cathode material pilot lines. Osaka-based chemical conglomerates maintain specialized production for medical-grade coin cells requiring hermetic sealing and biocompatibility certification.
Germany
BMW and Volkswagen procurement teams are evaluating manganese oxide cathodes for entry-level electric vehicle segments where cost sensitivity exceeds range requirements. EU Battery Regulation carbon footprint declarations and recycled content mandates are reshaping material sourcing obligations for suppliers accessing European OEMs. North Rhine-Westphalia's chemical corridor hosts precursor development facilities serving automotive qualification programs.
United States
Utility developers in California and Texas are tendering containerized manganese oxide installations for grid frequency regulation services. IRA domestic content provisions create compliance complexity for cathode producers without North American upstream integration. Michigan and Ohio automotive clusters are exploring partnerships with Korean and Japanese suppliers to establish qualifying pCAM capacity.
Lithium-Ion Manganese Oxide Battery Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the manganese oxide cathode value chain. Integrated mining-to-precursor specialists command supply security advantages, while technology licensors monetize doping formulations and process patents. The market structures around three archetypes: diversified chemical conglomerates with global precursor networks, regional cathode specialists with captive refining, and battery makers with backward integration into active materials. Dominant competitive moves include capacity expansion in battery-grade manganese sulfate and strategic partnerships bridging refining gaps in North America and Europe.
Among diversified chemical conglomerates, BASF leverages its multinational precursor infrastructure to sustain cathode material supply across multiple continents. POSCO Future M anchors Korean manganese oxide production through integrated refining and pCAM capabilities in the Gwangyang complex. Shenzhen Dynanonic occupies a specialist position in high-voltage spinel formulations, differentiating its offering for power-tool and e-bike applications where cycle life requirements exceed 1,000 cycles.
| Leading Market Players |
|---|
| LAND CORP. |
| POSCO Future M |
| BASF |
| XTC New Energy Materials |
| Shenzhen Dynanonic |
| Hunan Yuneng New Energy Battery Materials |
| Morrow Batteries |
| Topsoe |
| 6K Inc. |
| Others |
Pricing and Supply Chain Analysis
Battery-grade manganese sulfate concentrate flows from Chinese refining corridors in Guangxi and Guizhou through three distinct pricing tiers downstream. Cathode producers purchasing spot volumes absorb the steepest volatility, while automotive OEMs with multi-year offtake agreements lock in cost predictability at the premium tier.
Pricing Analysis
Throughput guarantees anchor value-based pricing for fleet operators subscribing to battery health monitoring services rather than purchasing cells outright. Automotive qualification tiers separate premium cathode grades qualified for Korean and German OEM platforms from standard grades serving power-tool assemblers and economy grades for aftermarket replacement packs. Cost compression in the economy tier intensifies as Vietnamese pack makers enter the replacement power-tool battery segment. Retail manufacturers exhibit the highest price sensitivity, while energy utilities with long-term asset ownership models prioritize degradation warranties over unit cost.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Los Angeles buffer cathode material flows between Asian production clusters and European and North American cell plants. Battery-grade manganese sulfate production concentrates in China, with Korean integrated refining-to-precursor complexes at Gwangyang and Pohang providing secondary supply security. The supply chain draws from manganese ore deposits in South Africa, Gabon, and Australia, with refining capacity tethered to Chinese chemical processing corridors. Single-source vulnerability around Chinese manganese sulfate refining exposes cathode producers to export quota uncertainty. Distribution runs through hub-and-spoke patterns anchored by POSCO Future M's Gwangyang complex serving Korean automotive OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery-grade manganese sulfate refining capacity constraints in North America and Europe prop pricing premiums for qualified cathode material, creating a supply-constrained market structure favoring integrated producers.
For Market Incumbents: Hedge against lithium iron phosphate substitution by accelerating nickel-doped spinel qualification cycles with Korean and German automotive OEMs. Secure captive manganese refining capacity through joint ventures in Australia or South Africa to reduce Chinese sulfate dependency. Prioritize ceramic-coated separator investments to maintain NMPA GB 38031 compliance access. For New Entrants and Emerging Players: Capture the India PLI scheme window for two-wheeler and stationary storage cathode supply before Korean and Chinese incumbents consolidate positions. Target Australian and Canadian utility developers seeking non-Chinese supply chains for grid-scale installations. Lead with direct recycling partnerships that preserve cathode crystal structure for second-life material streams. For Investors and Strategic Acquirers: Korean automotive OEM qualification announcements for nickel-doped spinel variants are the leading indicator that manganese oxide cathodes are securing model-year slots previously reserved for NMC chemistries. Five-to-ten year viability hinges on solid-state hybrid architecture adoption rates in aviation and marine propulsion. Acquisition candidates include Belgian and Canadian recyclers scaling hydrometallurgical recovery pathways.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Manganese Refining | POSCO Future M's Gwangyang complex demonstrates how captive sulfate production secures automotive qualification timelines. |
| High-Voltage Spinel Formulation Licensing | Shenzhen Dynanonic's patent position in 4.4V+ doped spinels creates differentiation in power-tool and e-bike segments. |
| Ceramic-Coated Separator Partnership | Chinese cell makers redesigning pouch formats for NMPA compliance are locking in separator supply agreements. |
| Subscription-Based Health Monitoring Launch | Fleet operators unbundling hardware from service contracts create recurring revenue independent of cell sales. |
| Direct Recycling Scale-Up | Belgian recyclers preserving cathode crystal structure offer second-life material streams with lower carbon intensity. |
Research Methodology
Multi-period observation of cathode material procurement volumes, automotive qualification timelines, and manganese sulfate price spreads anchored the trend analysis, supplemented by interviews with cathode plant managers, automotive cell procurement directors, battery management system engineers, and utility-scale storage developers. Secondary validation drew from NMPA GB standard filings, EU Battery Regulation implementation guidance, Korean Ministry of Trade battery R&D subsidy disclosures, and customs trade data for battery-grade manganese sulfate flows. Bottom-up cell production estimates triangulated against top-down automotive OEM platform deployment targets.
Segment-weighting applied product type, application, and technology dimensions across the projection horizon, with prismatic and pouch format splits calibrated to Korean and Chinese cell maker capacity announcements. Automotive, consumer electronics, renewable energy storage, and medical device end-use shares were modeled against OEM platform roadmaps and utility tender pipelines. CAGRs derived from installed capacity buildout curves and chemistry substitution elasticity assumptions, with solid-state hybrid architecture adoption rates and IRA domestic content compliance pathways treated as scenario variables.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to manganese sulfate price volatility, patent litigation around nickel-substituted spinel structures, and thermal runaway testing standard harmonization between China's NMPA and EU regulatory frameworks. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Global Next Generation Batteries Market
Lithium-ion Battery
Lithium-Sulfur Battery Market
Lithium-ion Battery
Lithium-Ion Polymer Batteries Market
Lithium-ion Battery
Lithium Hydroxide Market
Lithium-ion Battery
Lithium-Ion Battery Rechargeable Hearing Aids Market
Lithium-ion Battery
Italy Electric Vehicle Battery Materials Market
Lithium-ion Battery
France SLI Battery Market
Lithium-ion Battery
Prismatic Lithium Cobalt Oxide (LiCoO2) Battery Market
Lithium-ion Battery
United Kingdom Electric Vehicle Battery Anode Market
Lithium-ion Battery
Lawn Mower Lithium Battery Market
Lithium-ion Battery
Lithium-Ion Battery Pack for Consumer Market
Lithium-ion Battery
Lithium-Ion Forklift Battery Market
Lithium-ion Battery
Lithium Battery in Myanmar Market
Lithium-ion Battery
Global Lithium Mining Market
Lithium-ion Battery
Ultra Low Temperature Lithium Battery Market
Lithium-ion Battery
South America Lithium-Ion Battery for Electric Vehicle Market