
 Inverter Battery Market | 2026-2036
Inverter Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Inverter Battery Market Intelligence
India's BIS certification for inverter batteries is hardening quality thresholds and pushing unorganized manufacturers toward compliance investments. Exide Industries leverages its nationwide distribution network to sustain volume leadership in lead-acid segments. Luminous Power Technologies anchors premium positioning through deep rural penetration and service infrastructure. Microtek International competes on price-accessible lithium-ion variants for residential buyers.
An inverter battery is an electrochemical storage device paired with power conversion electronics to deliver alternating current during grid interruptions, typically employing lead-acid or lithium-ion chemistries with nominal capacities between 100 Ah and 300 Ah. Its primary purpose is ensuring uninterrupted power for residential, commercial, and telecommunications loads where grid stability is unreliable. Lead-acid batteries still occupy the largest share of installed base due to first-cost advantages, though lithium-ion segments are expanding fastest as energy density requirements intensify for solar-hybrid installations. Residential end users generate the deepest volume pool, while telecommunications applications command superior margins through stringent uptime contracts.
BIS mandates in India, EPA guidelines in the United States, and REACH compliance in Europe collectively govern material composition, recycling obligations, and safety testing protocols for inverter batteries. These frameworks elevate entry barriers for new suppliers while rewarding established players with certified laboratories and traceable supply chains. Stakeholders must monitor chemistry transitions and certification lead times as decisive variables for capacity planning and market access.
Market Dynamics
Chemistry transitions are fragmenting established supply chains as lithium-ion systems displace lead-acid dominance in solar-hybrid installations, forcing manufacturers to rebuild certification pathways and distribution partnerships around fundamentally different cell architectures.
Growth Catalysts
- Telecommunications uptime contracts:Tower operators across India and Nigeria mandate 99.99% availability, driving premium battery procurement for backup power systems.
- BIS safety mandates:India's Bureau of Indian Standards certification requirements for deep-cycle performance are filtering substandard products from formal distribution channels.
- Lithium iron phosphate adoption:Residential buyers in tier-2 Indian cities are selecting LFP chemistry for solar-hybrid configurations despite higher first costs.
Market Restraints
- Lead price volatility:Smelter capacity constraints in China and Mexico are compressing margins for lead-acid manufacturers dependent on recycled feedstock.
- Cobalt supply concentration:Lithium-ion cell producers face input risk from DRC mining concentration, limiting chemistry flexibility for NMC formulations.
- Deep-cycle degradation:Flooded lead-acid systems suffer accelerated capacity fade under partial state-of-charge operation, shortening replacement cycles.
Strategic Opportunities
- Indonesia residential solar:Archipelago geography and weak inter-island grid connectivity create distributed storage demand across 17,000 islands.
- Second-life EV batteries:Retired automotive lithium-ion packs are entering stationary backup applications at 60-70% remaining capacity.
- Direct-to-installer channels:E-commerce platforms serving electricians and solar integrators are bypassing traditional distributor markups in tier-3 Indian markets.
Industry Challenges
- BIS laboratory capacity:Certification backlogs extending 14-18 weeks are delaying product launches and freezing working capital in test samples.
- Electrolyte handling protocols:Flooded battery assembly requires sulfuric acid management infrastructure that lithium-ion lines cannot repurpose.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inverter Battery Market |
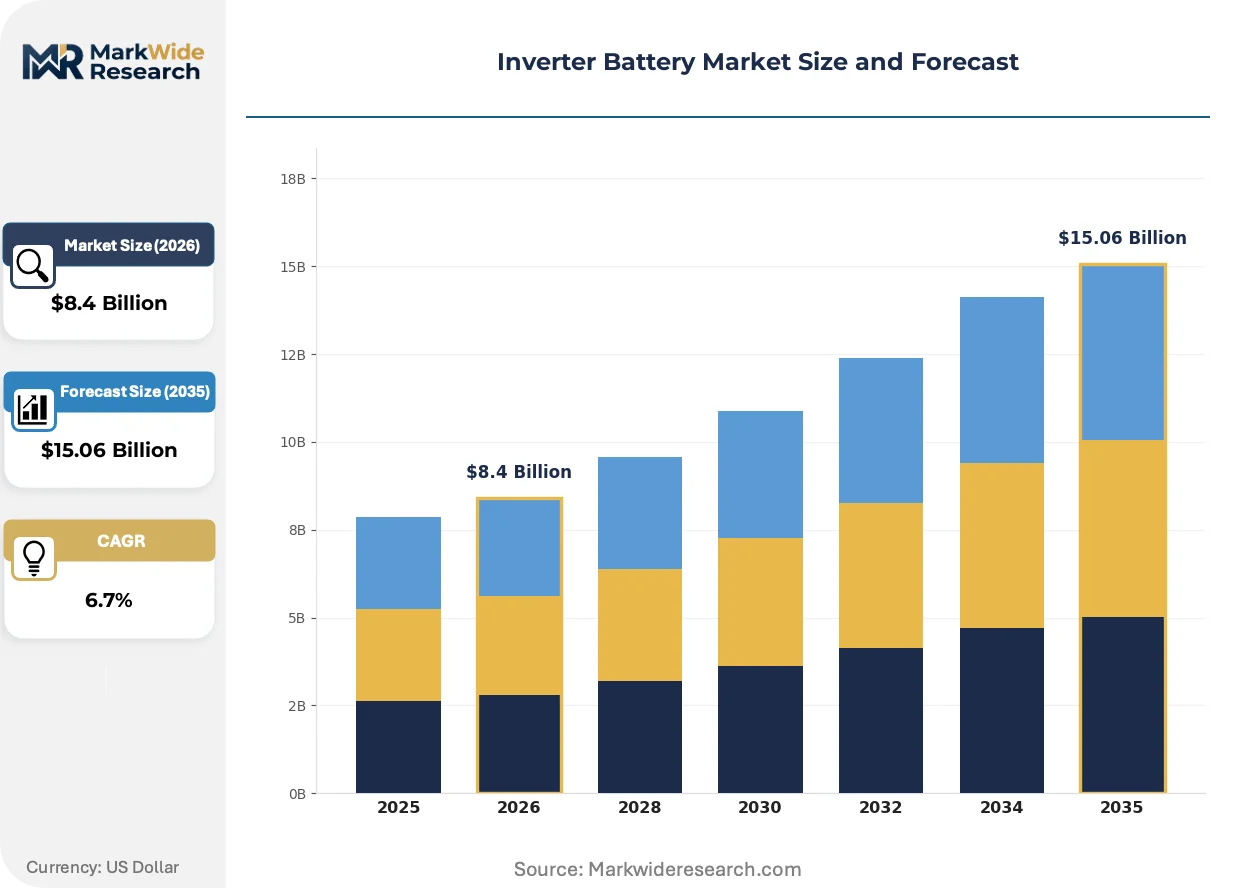
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.06 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lead Acid, Lithium Ion, Nickel Cadmium, Gel Technology: Hybrid, Off-Grid, Grid-Tie, Smart Inverter Capacity: 100 Ah, 150 Ah, 200 Ah, 300 Ah End User: Residential, Commercial, Industrial, Telecommunications |
| Companies Covered | Su-Kam Power Systems, Genus Power Infrastructures, Exide Industries, Tubewell, Microtek International, Amaron, Okaya Power, SunGarner, Luminous Power Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inverter Battery Market Strategic Shifts & Innovations
Battery management intelligence and chemistry diversification are collapsing the traditional separation between power electronics and electrochemical storage, creating integrated system architectures that redefine supplier value capture.
Lithium iron phosphate cells paired with active balancing battery management systems are unifying energy storage and power conversion into single-enclosure residential units. Solar installers in Gujarat and Maharashtra are specifying these integrated systems for rooftop deployments. This convergence is compressing the addressable market for standalone inverter manufacturers and forcing them toward white-label partnerships or exit.
India's BIS certification expansion to cover lithium-ion safety testing under IS 16046 is tightening market access for uncertified imports. Domestic laboratories in Bengaluru and Pune are building IEC 62619 testing capability to serve exporters. Tier-1 manufacturers with captive certification resources are widening their compliance lead over trading houses dependent on third-party testing.
Service bundling is replacing transactional battery sales as the dominant commercial model. Luminous Power Technologies and Exide Industries are attaching annual maintenance contracts to premium lithium-ion installations. This shift is most visible in Delhi-NCR and Bengaluru, where residential buyers prioritize uptime guarantees over lowest first cost.
Inverter Battery Market Segmentation
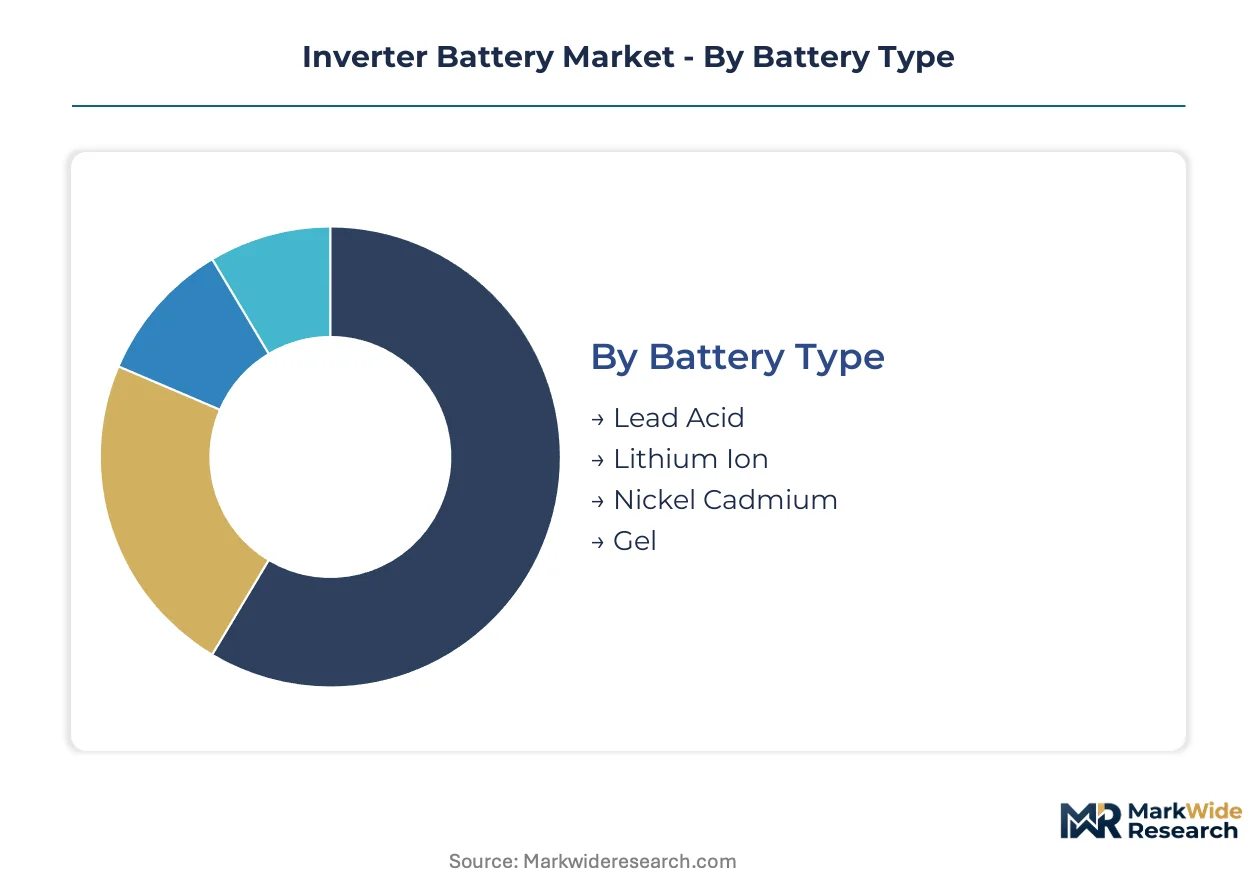
Inverter battery segmentation reveals divergent upgrade economics across chemistries and capacities. Replacement cycles vary dramatically between flooded lead-acid systems requiring 3-year swaps and lithium-ion installations lasting 8-10 years, reshaping manufacturer revenue recognition and service attach strategies.
Battery Type:
Upgrade cycles and chemistry switching costs define competitive positioning across battery types, with first-cost sensitivity clashing against total ownership economics in residential procurement decisions.
- Lead Acid:Flooded and VRLA configurations dominate existing installed base through 100-200 Ah residential deployments. India's tier-2 cities sustain volume demand where grid outages remain frequent but solar-hybrid penetration stays limited.
- Lithium Ion:LFP and NMC chemistries enable deeper discharge cycles and faster recharge rates essential for solar-hybrid configurations. Maharashtra and Gujarat residential buyers absorb 40-60% price premiums to eliminate acid maintenance and extend replacement intervals.
- Nickel Cadmium:Aviation and railway backup applications exploit Ni-Cd tolerance for extreme temperature swings and mechanical abuse. Regulatory pressure from REACH cadmium restrictions confines growth to specialized industrial niches.
- Gel:Immobilized electrolyte construction suits vibration-prone telecom tower installations across Nigeria and Indonesia. Higher material costs limit residential penetration despite superior cycle life in partial state-of-charge operation.
Lead Acid sits at the top of the volume ranking, with Lithium Ion climbing the fastest.
Technology:
System architecture choices determine margin capture between standalone battery suppliers and integrated power electronics manufacturers, with convergence pressures reshaping vendor boundaries.
- Hybrid:Combined grid-tie and backup functionality enables seamless solar self-consumption with outage protection. Indian solar installers in Delhi-NCR specify hybrid inverters with bundled LFP storage to maximize rooftop generation economics.
- Off-Grid:Standalone systems serve archipelago geography and remote industrial sites lacking grid infrastructure. Indonesian residential demand across 17,000 islands drives diesel displacement through solar-plus-storage configurations.
- Grid-Tie:Export-focused inverters without backup capability dominate grid-stable urban markets. Net metering policy uncertainty in several Indian states has stalled procurement decisions for pure grid-tie installations.
- Smart Inverter:Embedded monitoring and predictive maintenance algorithms command 15-25% price premiums in commercial segments. Telecom tower operators mandate remote diagnostics integration for 99.99% uptime contract compliance.
Hybrid captures the dominant revenue share, with Smart Inverter expanding most quickly as digital service bundling penetrates premium residential tiers.
Capacity:
Capacity selection tracks load profiling sophistication, with urban residential buyers oversizing systems for air-conditioning surge demands while rural deployments optimize for lighting and fan loads.
- 100 Ah:Entry-level configurations serve single-room backup requirements and small commercial establishments. Price-sensitive buyers in India's tier-3 markets prioritize this segment despite limited runtime for motor loads.
- 150 Ah:The workhorse specification balances first cost against 4-6 hour backup for standard residential appliances. Bengaluru apartment complexes standardize on 150 Ah VRLA banks for common area emergency lighting.
- 200 Ah:Mid-premium tier absorbs solar-hybrid buyers seeking overnight autonomy without air-conditioning loads. Gujarat rooftop solar adopters favor 200 Ah LFP systems for 8-10 hour backup during monsoon cloud cover.
- 300 Ah:Heavy-duty specification serves commercial establishments and telecom shelters with sustained high-current demands. Nigerian tower operators specify 300 Ah gel battery banks for 48-hour diesel-free autonomy.
150 Ah maintains volume leadership across replacement cycles, with 200 Ah gaining share fastest as solar-hybrid adoption accelerates in grid-unreliable urban corridors.
End User:
End-use segmentation separates price-sensitive transactional buyers from contract-driven procurement with stringent uptime guarantees and multi-year service obligations.
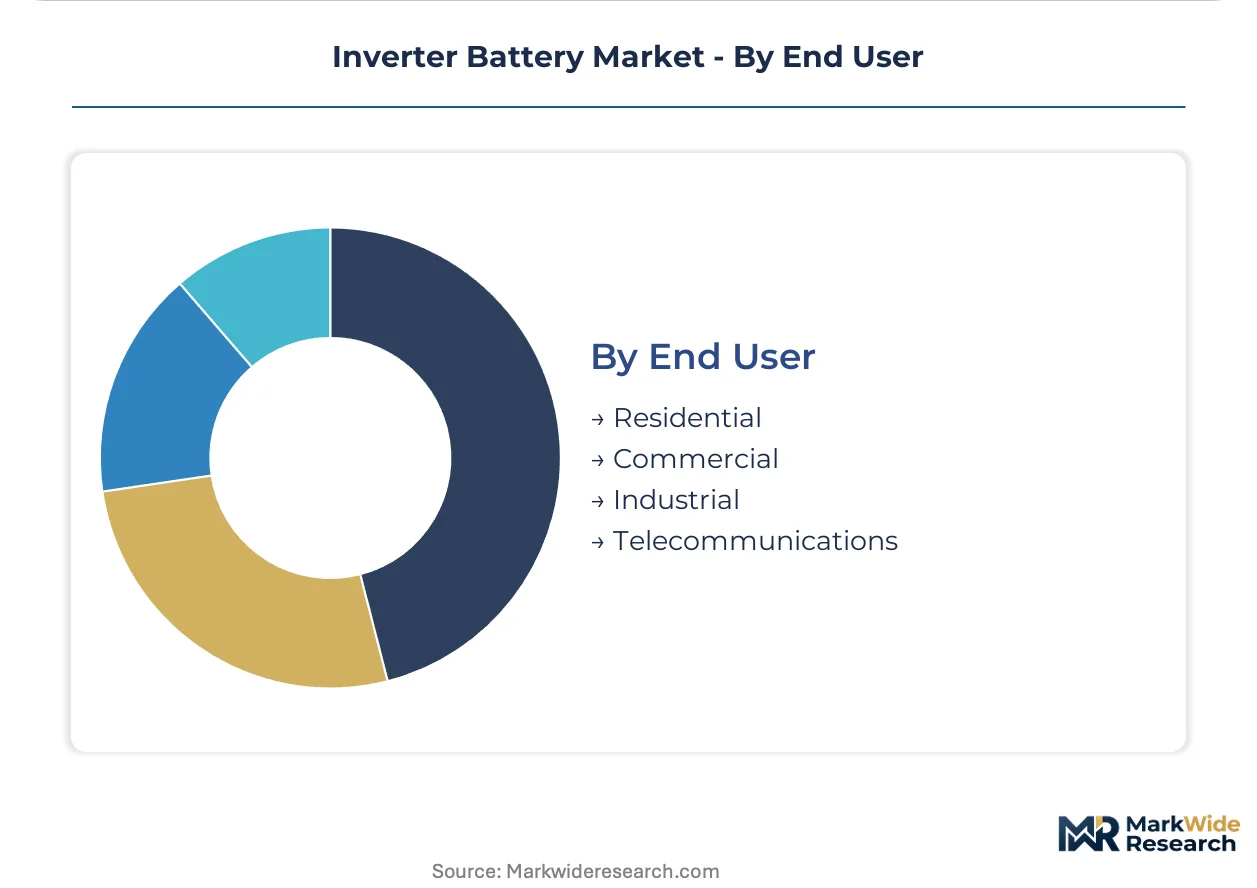
- Residential:Individual households drive absolute unit volumes through 100-200 Ah lead-acid replacement cycles. Tier-2 Indian cities generate concentrated demand where daily power cuts exceed 4 hours.
- Commercial:Small businesses and retail establishments prioritize 4-6 hour backup for billing systems and refrigeration. Mumbai and Delhi commercial complexes increasingly specify lithium-ion for space-constrained installations.
- Industrial:Manufacturing continuity requirements demand heavy-duty 300 Ah+ configurations with rapid recharge capability. Textile and pharmaceutical units in Tamil Nadu and Maharashtra absorb premium pricing for zero-downtime guarantees.
- Telecommunications:Tower operators and data centers impose 99.99% availability contracts with penalty clauses driving premium battery procurement. Indus Towers and American Tower Corporation in India mandate 10-year service bundles with predictive replacement scheduling.
Residential commands the deepest unit volumes, with Telecommunications delivering the steepest margin expansion through outcome-based contracting models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Inverter battery manufacturing first scaled in Japan and Germany during the 1970s as industrial automation demanded reliable backup power. Production subsequently migrated toward emerging economies with unreliable grid infrastructure. Today, demand concentrates in South Asia, Southeast Asia, and select African markets where distributed storage solves fundamental electrification gaps.
India
Tier-2 cities including Lucknow, Indore, and Coimbatore drive replacement demand for 150-200 Ah lead-acid systems. BIS certification under IS 16046 now governs lithium-ion safety testing, extending compliance timelines for importers. The Delhi-NCR corridor hosts the densest concentration of certified testing laboratories and integrated manufacturing facilities serving residential solar-hybrid deployments.
Indonesia
Archipelago geography across 17,000 islands necessitates off-grid solar-plus-storage configurations for 17 million unelectrified households. The Ministry of Energy and Mineral Resources prioritizes rural electrification through village-level microgrids. Java and Sumatra industrial zones absorb premium gel battery volumes for telecommunications towers requiring diesel displacement.
Nigeria
Telecommunications tower operators mandate 99.99% uptime contracts, forcing premium procurement of 300 Ah deep-cycle batteries. The Nigerian Communications Commission enforces backup power standards for critical infrastructure. Lagos and Kano serve as distribution hubs where diesel generator dependence creates the steepest total-cost-of-ownership case for lithium-ion conversion.
Vietnam
Rapid manufacturing expansion in Bac Ninh and Hai Phong industrial zones drives heavy-duty backup demand for textile and electronics assembly. The Ministry of Industry and Trade implements net metering pilots that accelerate solar-hybrid adoption. Ho Chi Minh City residential buyers increasingly specify LFP chemistry despite 50% price premiums over lead-acid alternatives.
Brazil
Grid instability in northern states and Amazon basin isolation sustain off-grid inverter battery demand. ANEEL regulatory frameworks govern distributed generation interconnection standards. São Paulo and Minas Gerais manufacturing clusters source lithium-ion systems for commercial installations prioritizing space constraints over first-cost minimization.
Inverter Battery Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification tiering and service bundling dimensions. The vendor base organizes into three strata: integrated manufacturers with captive BIS laboratories, trading houses dependent on third-party testing, and regional assemblers serving price-sensitive tier-3 markets. Two dominant competitive moves are reshaping positioning: backward integration into cell manufacturing to secure lithium-ion supply, and attachment of 10-year maintenance contracts to escape transactional battery pricing.
Among India-based integrated manufacturers, Exide Industries, Luminous Power Technologies, and Microtek International exemplify the certification-advantaged tier. Exide Industries occupies a position anchored in lead-acid volume leadership and nationwide distribution density. Luminous Power Technologies represents the service-bundling archetype through rural penetration infrastructure. Microtek International sits within the chemistry-transition vanguard, occupying a position associated with lithium-ion accessibility for residential buyers. These three entities collectively illustrate how compliance capability and service infrastructure separate sustainable competitors from trading-dependent challengers.
| Leading Market Players |
|---|
| Su-Kam Power Systems |
| Genus Power Infrastructures |
| Exide Industries |
| Tubewell |
| Microtek International |
| Amaron |
| Okaya Power |
| SunGarner |
| Luminous Power Technologies |
| Others |
Cost & Logistics Intelligence
Lead price volatility on the London Metal Exchange cascades through inverter battery manufacturing into three distinct procurement tiers. Smelter capacity constraints in China and Mexico compress margins for lead-acid producers while lithium-ion cell costs hinge on cobalt and lithium carbonate benchmarks from the DRC and Chilean salares.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement decisions. Certification grade under BIS IS 16046 and service bundling duration separate premium lithium-ion offerings from transactional lead-acid sales. Cost compression in economy lead-acid tiers is intensifying because recycled feedstock competition limits margin recovery. Residential buyers in India's tier-3 markets exhibit the steepest price sensitivity, while telecommunications operators absorbing 10-year service contracts show minimal elasticity.
Supply Chain Analysis
Reverse-logistics flows for end-of-life batteries are consolidating around certified recyclers in India and China. Cell manufacturing concentrates in China, South Korea, and Japan, while lead-acid assembly clusters in India and Mexico serve regional demand. Raw material sourcing rests on lithium spodumene from Australia, refined cobalt from the DRC, and recycled lead from Chinese smelters. Single-source vulnerability around DRC cobalt concentrates chemistry flexibility for NMC formulations. Distribution runs through national distributor networks in India and direct-to-installer e-commerce platforms in Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The inverter battery market functions as a geographic-arbitrage play between India's tightening BIS certification costs and Indonesia's underdeveloped laboratory infrastructure. Manufacturers can exploit this differential by routing certified production through India while capturing margin in archipelago markets lacking equivalent compliance overhead.
For Market Incumbents: Deploy captive certification resources to widen compliance gaps against trading-house competitors. Exide Industries and Luminous Power Technologies should expand Bengaluru and Pune laboratory capacity to capture BIS backlog demand from smaller importers. Backward integration into LFP cell production secures supply continuity against Chinese export restriction risks. Channel control through exclusive electrician partnerships in tier-2 Indian cities locks in replacement cycle visibility. For New Entrants and Emerging Players: Battery management system intelligence offers entry into residential solar-hybrid configurations where incumbent inverter manufacturers lack electrochemical expertise. Indonesia's 17,000-island geography presents the most penetrable geography for off-grid solar-plus-storage deployments. Nigerian telecommunications tower operators represent a contract-rich segment with standardized 300 Ah specifications and diesel displacement mandates. Direct-to-installer digital platforms bypass traditional distributor markups in tier-3 Indian markets. For Investors and Strategic Acquirers: Asymmetric upside sits with certified testing laboratories and second-life battery aggregators. Long-term viability across the analysis window favors assets with BIS accreditation and traceable recycling partnerships. Acquisition targets should demonstrate captive laboratory capacity or exclusive offtake agreements with retired EV battery suppliers. Practitioners should monitor BIS certification queue lengths and lithium carbonate price trajectories for early signals of margin inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into LFP Cell Manufacturing | Captive supply secures chemistry transition timing against Chinese export controls. |
| BIS Certification Laboratory Expansion | Bengaluru and Pune capacity captures 14-18 week backlog demand from importers. |
| Second-Life EV Battery Aggregation | Retired automotive packs at 60-70% capacity enter stationary backup at discount. |
| Direct-to-Installer E-Commerce Platform | Bypasses traditional distributor markups in tier-3 Indian and Indonesian markets. |
| 10-Year Service Contract Bundling | Telecommunications operators in Nigeria and India mandate uptime guarantees with penalty clauses. |
Research Approach
Multiple input streams — primary interviews with battery plant managers and solar installer procurement leads, trade data from India's DGFT and customs authorities, and BIS certification registry analysis — were reconciled through bottom-up and top-down triangulation. Secondary validation drew from SEC filings of listed manufacturers, EIA energy storage deployment data, and telecommunications tower operator procurement disclosures. Conversations with distribution channel partners in Lucknow and Coimbatore supplied ground-level pricing intelligence.
Data-stream reconciliation across chemistry transitions, capacity tier migrations, and regional regulatory clusters produced volume and value estimates. Segmentation modeling tracked battery type, technology architecture, capacity band, and end-use vertical throughout the forecast period. CAGRs emerged from replacement cycle analysis and solar-hybrid penetration curves. Industry-specific inputs included BIS laboratory queue lengths, lead smelter capacity utilization, and lithium carbonate contract pricing.
The model holds under stable BIS enforcement and continued grid unreliability in target geographies; deviation in certification timeline compression or lithium supply disruption would shift manufacturer positioning. Forecasts reflect these base assumptions and documented replacement cycle patterns. Practitioners should monitor BIS queue lengths and DRC cobalt export policy for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Leisure Battery Market
Batteries
Drone Lithium Battery Charger Market
Batteries
Cobalt-Free Battery Market
Batteries
South and Central America Battery Market
Batteries
Lead Carbon Battery Market
Batteries
United States SLI Battery Market
Batteries
Middle East and Africa Solar and Motorcycle Battery Market
Batteries
Portable Battery Market
Batteries
Printed Batteries Market
Batteries
Mobile Battery Market
Batteries
Seawater Battery Market
Batteries
Echelon Utilization of Power Battery Market
Batteries
Bangladesh Lead Acid Battery Market
Batteries
Europe Lead-Acid Battery Market
Batteries
N-Type Battery Market
Batteries
Vanadium Redox Flow Batteries (VRFB) Market