
 Saudi Arabia Renewable Energy Market | 2026-2036
Saudi Arabia Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Renewable Energy Market Outlook
Specialized engineering talent for utility-scale solar and wind integration is bifurcating the competitive landscape between firms that build in-house capability and those dependent on foreign contractors. ACWA Power dominates project development through its captive development pipeline and long-term offtake agreements with government entities. EDF Renewables leverages European technical protocols to differentiate on grid-stability engineering for complex desert installations. Alfanar Group anchors local manufacturing of photovoltaic components and inverters, sustaining cost advantages on domestic content requirements.
Saudi Arabia renewable energy encompasses solar photovoltaic, concentrated solar power, onshore wind, and emerging green hydrogen systems designed to convert abundant solar irradiance exceeding 2,000 kWh per square meter annually into dispatchable electricity and industrial feedstock. The primary purpose is displacing crude oil combustion in power generation to preserve hydrocarbon export capacity while meeting domestic load growth. Solar technology leads deployment volumes through the National Renewable Energy Program's competitive auction structure, while wind occupies niche positions in the northern and western highlands. Desalination applications represent a concentrated margin pool where renewable-powered reverse osmosis commands premium offtake terms from the Saline Water Conversion Corporation.
Saudi Arabia's regulatory architecture centers on the Ministry of Energy's National Renewable Energy Program, the Electricity and Cogeneration Regulatory Authority's grid codes, and the Saudi Standards, Metrology and Quality Organization's technical specifications for equipment certification. These frameworks mandate local content thresholds and prioritize project bankability through sovereign-backed offtake guarantees. SFDA oversight of industrial safety intersects with renewable construction standards through workplace hazard protocols. Stakeholders must monitor how the kingdom's green hydrogen export strategy reallocates solar and wind capacity between domestic grid supply and industrial off-take commitments.
Market Dynamics
The Saudi Arabia renewable energy market is experiencing structural compression between domestic grid supply obligations and emerging green hydrogen export commitments, forcing developers to reallocate solar and wind capacity between competing offtake streams.
Growth Catalysts
- National Renewable Energy Program auctions:Competitive tendering mechanisms under the Ministry of Energy's framework accelerate utility-scale deployment through bankable sovereign-backed offtake structures.
- Industrial desalination demand:The Saline Water Conversion Corporation's procurement of renewable-powered reverse osmosis creates concentrated margin pools for developers with integrated water-energy capabilities.
- Solar irradiance endowment:Desert regions exceeding 2,000 kWh per square meter annually provide fundamental cost advantages for photovoltaic and concentrated solar power economics.
Market Restraints
- Specialized engineering scarcity:Bifurcation between firms with in-house utility-scale integration capability and those dependent on foreign contractors limits execution bandwidth for complex desert installations.
- Grid code compliance costs:Electricity and Cogeneration Regulatory Authority stability requirements impose capital-intensive inverter and control system specifications on project developers.
- Local content thresholds:Saudi Standards, Metrology and Quality Organization certification mandates create supply bottlenecks where domestic manufacturing capacity lags procurement timelines.
Strategic Opportunities
- Green hydrogen industrial feedstock:Conversion of solar capacity into hydrogen export streams opens alternative revenue channels beyond domestic power purchase agreements.
- Northern highlands wind development:Underexploited onshore wind resources in western mountain corridors offer diversification from solar-dominated generation portfolios.
- Riyadh-Jeddah corridor industrial zones:Concentrated clean baseload demand from manufacturing clusters supports dedicated renewable supply contracts with premium terms.
Industry Challenges
- Desert installation engineering:Sand abrasion, thermal cycling, and soiling management require specialized module mounting and cleaning protocols that extend commissioning timelines.
- SFDA workplace safety intersection:Industrial construction standards for renewable projects must reconcile with occupational hazard protocols, creating compliance complexity during peak installation periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Renewable Energy Market |
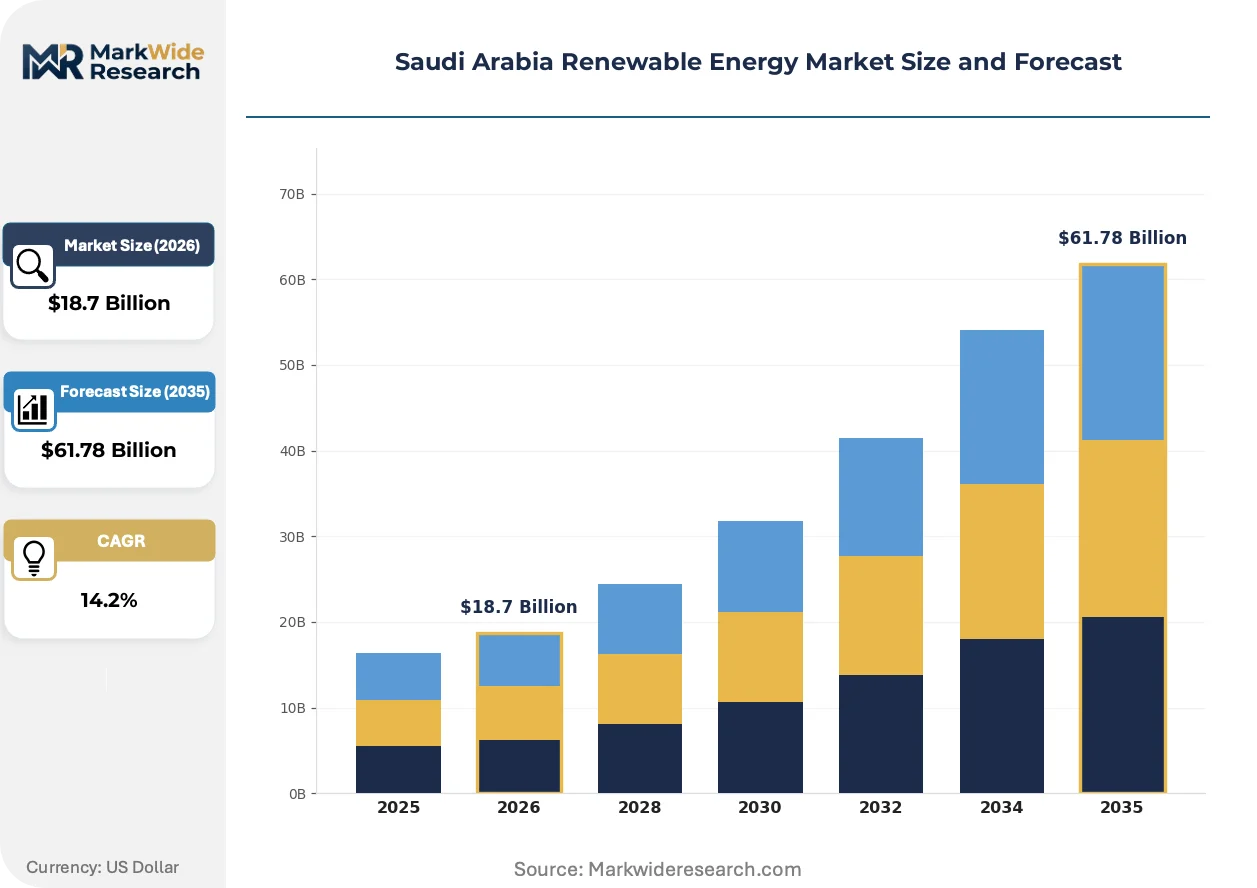
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Solar, Wind, Biomass, Geothermal End User: Residential, Commercial, Industrial, Government Energy Source: Solar Power, Wind Energy, Hydropower, Tidal Energy Application: Power Generation, Heating, Desalination, Transportation |
| Companies Covered | EDF Renewables, Enel SpA, ACWA Power, Saudi Electricity Company, Riyadh Renewable Energy Co, Alfanar Group, Engie SA, Saudi Aramco, Abu Dhabi Future Energy Company (Masdar), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Renewable Energy Market Strategic Shifts
Technology convergence and procurement model evolution are restructuring competitive advantage in Saudi Arabia's renewable sector, favoring developers with integrated manufacturing, engineering, and long-term asset management capabilities over pure project origination plays.
Bifurcation is reshaping photovoltaic module supply strategies as domestic manufacturers under Alfanar Group's anchor position compete with imported tier-one products. Industrial offtakers in the Eastern Province are prioritizing modules with verified desert performance warranties. This technology split is compressing margins for traders lacking manufacturing depth or installation track records.
SFDA oversight protocols are intersecting with renewable construction standards through mandatory workplace hazard documentation for high-voltage electrical installations. Project developers must now integrate occupational safety management systems into engineering, procurement, and construction contracts. The affected segment is utility-scale solar where foreign engineering, procurement, and construction contractors face extended compliance onboarding.
Long-term offtake contracting is displacing merchant exposure as the dominant revenue model for Saudi project developers. ACWA Power's captive pipeline structure has established template power purchase agreements that downstream competitors must match to secure financing. This shift is most visible in the 25-year sovereign-backed contracts dominating the National Renewable Energy Program's recent auction rounds.
Saudi Arabia Renewable Energy Market Segmentation
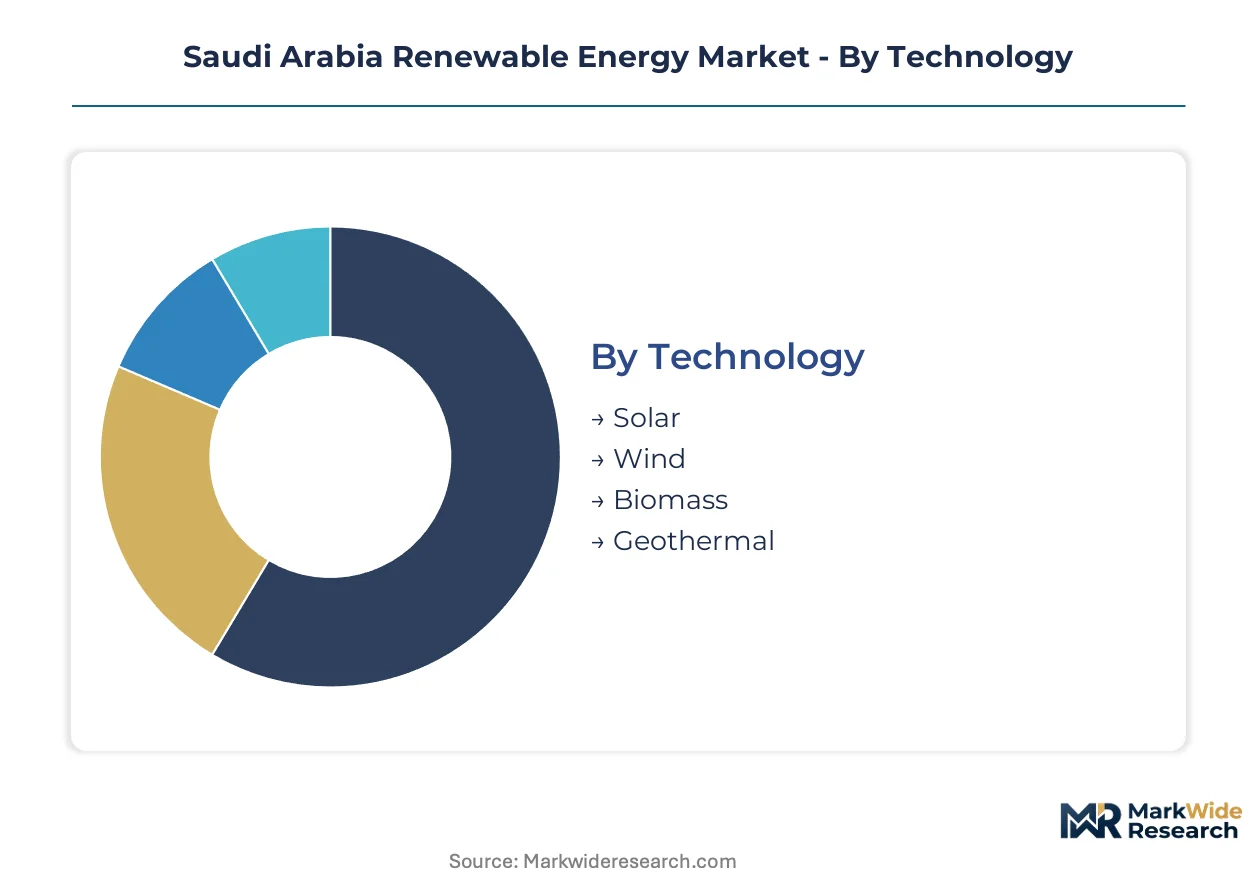
Technology choice determines project bankability and offtake structure in Saudi Arabia's renewable procurement. Segment boundaries shift as green hydrogen export commitments compete with domestic grid supply for solar and wind capacity allocation.
Technology:
Solar dominates procurement volumes through Ministry of Energy auctions, while wind occupies niche development corridors requiring distinct engineering capabilities and equipment supply chains.
- Solar:Photovoltaic and concentrated solar power systems exploit desert irradiance exceeding 2,000 kWh per square meter annually. Utility-scale tenders under the National Renewable Energy Program concentrate demand in the Riyadh-Jeddah corridor where industrial zones seek clean baseload supply.
- Wind:Onshore installations in northern and western highlands face terrain complexity and lower capacity factors than solar. The segment attracts developers pursuing portfolio diversification beyond photovoltaic dependence.
- Biomass:Limited feedstock availability constrains deployment to waste-to-energy pilots near urban centers.
- Geothermal:Exploration-stage resources in volcanic zones lack commercial-scale development timelines.
By volume, Solar leads. By growth pace, Wind is climbing the fastest as developers secure mountain corridor leases.
End User:
Customer type shapes contract duration, pricing mechanisms, and local content compliance intensity across the procurement landscape.
- Industrial:Manufacturing clusters in Jubail, Yanbu, and the Riyadh-Jeddah corridor drive concentrated demand for 24/7 renewable supply. Saline Water Conversion Corporation procurement of renewable-powered desalination creates premium margin pools for integrated water-energy developers.
- Government:Ministry of Energy and sovereign entities anchor long-term offtake through 25-year power purchase agreements with bankable sovereign guarantees. ACWA Power's captive pipeline structure has established template contracts that competitors must match.
- Commercial:Retail and office load centers pursue corporate renewable procurement under Saudi Green Initiative targets.
- Residential:Distributed solar adoption remains constrained by grid interconnection protocols and financing access.
Industrial offtakers command the steepest expansion trajectory as export manufacturing capacity expands.
Energy Source:
Source classification reflects final energy form rather than prime mover technology, affecting grid code compliance and storage integration requirements.
- Solar Power:Utility-scale photovoltaic arrays and concentrated solar power towers constitute the dominant supply source. Desert installation engineering demands specialized module mounting and soiling management protocols.
- Wind Energy:Northern highlands development requires grid-stability engineering for variable output integration. EDF Renewables leverages European technical protocols to differentiate on complex desert-wind installations.
- Hydropower:Minimal resource base limits deployment to small-scale run-of-river projects in western mountain wadis.
- Tidal Energy:Red Sea coastal potential remains pre-commercial with no active procurement mechanisms.
Solar Power holds volume leadership. Wind Energy is gaining share fastest as green hydrogen export projects anchor offtake.
Application:
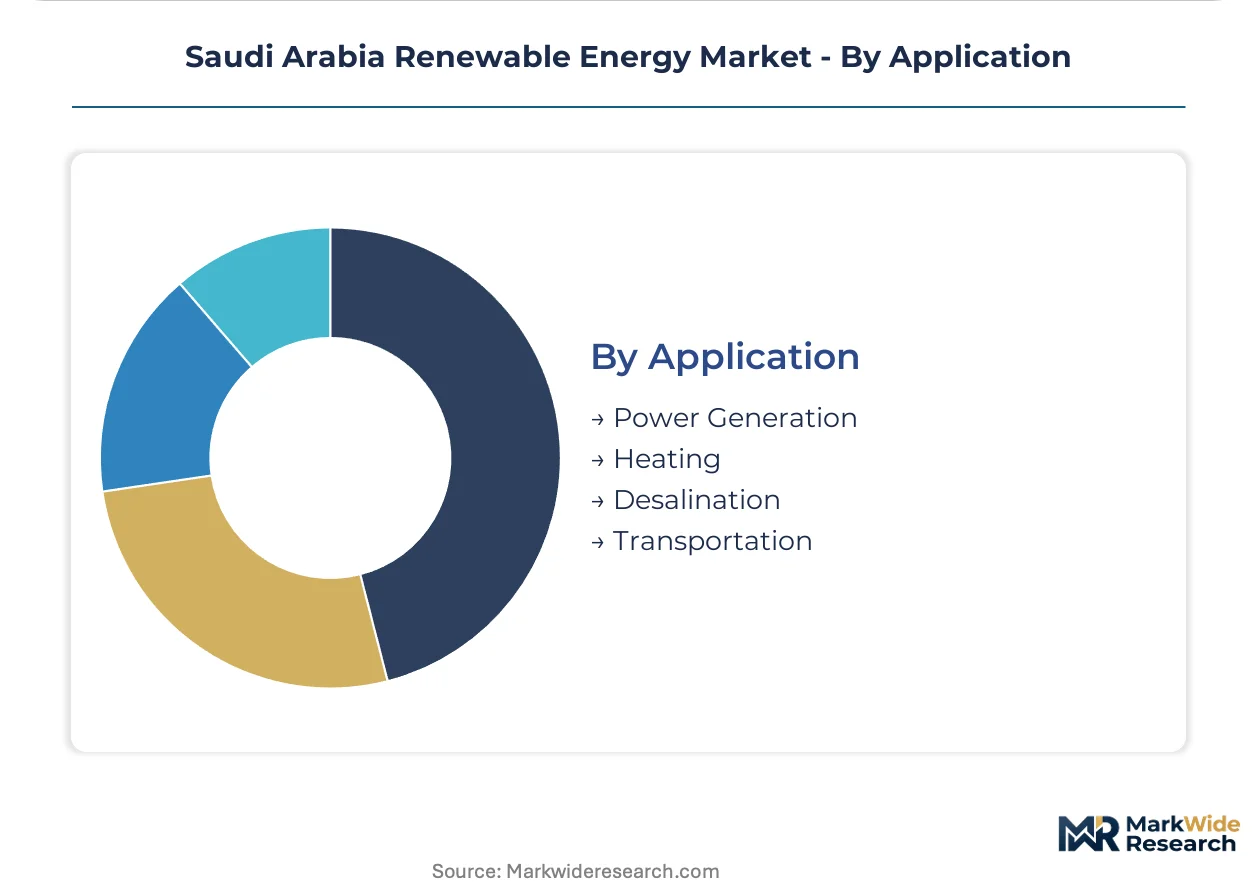
Use case determines technology configuration, storage pairing, and regulatory oversight intensity across project development.
- Desalination:Renewable-powered reverse osmosis commands premium offtake terms from Saline Water Conversion Corporation. Integrated water-energy projects require specialized engineering for load matching between intermittent supply and continuous desalination demand.
- Power Generation:Grid-connected supply dominates procurement through National Renewable Energy Program auctions. Electricity and Cogeneration Regulatory Authority stability requirements impose capital-intensive inverter specifications.
- Heating:Industrial process heat applications remain nascent with limited commercial deployment.
- Transportation:Green hydrogen for mobility and shipping represents emerging demand from NEOM and Red Sea Project developments.
Power Generation leads by installed capacity. Desalination shows the steepest margin expansion as water-energy integration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Renewable energy deployment patterns diverge sharply across Saudi Arabia's economic geography, with industrial corridors consuming clean power for baseload manufacturing while planned export zones prioritize hydrogen feedstock production over grid injection.
Riyadh
The capital corridor anchors utility-scale solar procurement through National Renewable Energy Program auctions serving cement, steel, and petrochemical clusters. Electricity and Cogeneration Regulatory Authority grid codes mandate stability-compliant inverters for all new interconnections. King Abdullah Financial District and surrounding industrial parks host corporate renewable procurement under Saudi Green Initiative targets.
Eastern Province
Jubail and Yanbu manufacturing complexes drive concentrated demand for 24/7 renewable supply to power desalination and refining operations. Saline Water Conversion Corporation procurement of renewable-powered reverse osmosis creates premium margin pools for integrated water-energy developers. Saudi Aramco's power procurement diversification concentrates project development activity in this zone.
Western Region
Jeddah and Mecca load centers combine pilgrimage-season demand spikes with year-round industrial consumption from Red Sea port logistics. The region's coastal wind resources remain underexploited relative to solar dominance. King Abdullah Port and associated manufacturing zones are negotiating dedicated renewable supply contracts.
NEOM Northwest
The planned megacity zone reallocates solar and wind capacity toward green hydrogen export commitments rather than domestic grid supply. NEOM Green Hydrogen Company anchors offtake structures that compete with traditional power purchase agreements for project developer attention. Oxagon industrial city and The Line development create concentrated demand for renewable-powered construction and eventual operations.
Northern Highlands
Tabuk and Al-Jawf provinces host the kingdom's most viable onshore wind resources, with terrain complexity requiring distinct engineering capabilities from solar-dominated portfolios. Developers pursue portfolio diversification through mountain corridor leases despite lower capacity factors than desert solar installations. The region's grid integration challenges favor firms with European technical protocols for variable output management.
Saudi Arabia Renewable Energy Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with captive development pipelines and sovereign-backed offtake relationships determining competitive position. The market structure bifurcates between firms with in-house utility-scale integration capability and those dependent on foreign engineering contractors. Strategic archetypes include captive developers with government equity stakes, European technical specialists leveraging grid-stability protocols, and local manufacturers exploiting domestic content thresholds. Dominant competitive moves center on long-term offtake contracting and backward integration into component manufacturing.
Within the captive developer tier, ACWA Power and Saudi Electricity Company exemplify the integrated model through sovereign-backed power purchase agreement templates that competitors must match to secure financing. Among European technical specialists, EDF Renewables and Engie SA occupy positions distinguished by grid-stability engineering capabilities for complex desert installations. Local manufacturing representation includes Alfanar Group, which anchors domestic photovoltaic component supply chains under Saudi Standards, Metrology and Quality Organization certification mandates.
| Leading Market Players |
|---|
| EDF Renewables |
| Enel SpA |
| ACWA Power |
| Saudi Electricity Company |
| Riyadh Renewable Energy Co |
| Alfanar Group |
| Engie SA |
| Saudi Aramco |
| Abu Dhabi Future Energy Company (Masdar) |
| Others |
Value Chain & Pricing Dynamics
Photovoltaic module substitution for concentrated solar power equipment is redrawing manufacturing geography toward Southeast Asian assembly hubs while compressing project-level pricing through standardized component sourcing. This input shift simultaneously weakens premium positioning for custom-engineered thermal systems and elevates price competition among tier-one module suppliers.
Pricing Analysis
Long-term offtake contracts under 25-year sovereign-backed power purchase agreements dominate developer revenue models, displacing merchant exposure and compressing spot market liquidity. Price differentiation stems from local content certification tiers under Saudi Standards, Metrology and Quality Organization mandates and verified desert performance warranties that industrial offtakers in Jubail and Yanbu prioritize. Cost compression in utility-scale solar is intensifying as ACWA Power's template agreements set financing benchmarks that downstream competitors must match. Government offtakers show lowest price sensitivity given sovereign guarantee structures, while commercial and residential segments face constrained financing access that amplifies capital cost sensitivity.
Supply Chain Analysis
Red Sea port congestion on the Jeddah-Islamic Maghreb trade lane and container availability fluctuations are elevating inbound logistics costs for imported photovoltaic modules and inverter systems. Manufacturing concentrates in China, Vietnam, and Malaysia for cell and module assembly, with domestic Saudi production under Alfanar Group anchoring inverter and mounting system supply. Polysilicon, silver paste, and tempered glass constitute critical input dependencies, with polysilicon pricing volatility transmitting directly to module cost curves. Single-source vulnerability concentrates in high-efficiency cell technology licensed from tier-one Chinese manufacturers. Distribution runs through engineering, procurement, and construction contractors with established Saudi project execution track records, linking component procurement to installation capability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's renewable energy sector represents a high-growth disruption anchored by the Ministry of Energy's National Renewable Energy Program auction cadence and the kingdom's green hydrogen export pivot. The regulatory inflection at the Electricity and Cogeneration Regulatory Authority, tightening grid code stability requirements, is accelerating capability bifurcation between integrated developers and foreign contractor-dependent firms.
For Market Incumbents: Shield captive development pipelines through backward integration into photovoltaic component manufacturing under Saudi Standards, Metrology and Quality Organization certification thresholds. Prioritize long-term offtake contract extensions with Saline Water Conversion Corporation before green hydrogen export commitments absorb available solar and wind capacity. The threat of European technical specialists like EDF Renewables capturing complex desert-wind installations demands in-house grid-stability engineering investment.
For New Entrants and Emerging Players: Saudi Standards, Metrology and Quality Organization certification fast-tracks unlock project eligibility for National Renewable Energy Program auctions, creating a regulatory moat against import-dependent competitors. Northern highlands wind development in Tabuk and Al-Jawf provinces offers the most penetrable geography given lower incumbent saturation and terrain complexity that favors specialized engineering capabilities. A go-to-market angle targeting integrated water-energy desalination projects with renewable-powered reverse osmosis expertise commands premium offtake terms.
For Investors and Strategic Acquirers: The market sits at a capacity-buildout phase that favors developers with sovereign-backed offtake relationships and in-house engineering capabilities over pure project origination plays. Long-term viability over the next decade hinges on successful reallocation of solar capacity between domestic grid supply and green hydrogen industrial feedstock commitments. Acquisition targets should display captive pipeline structures with government equity stakes and established power purchase agreement templates. The signal to watch is Ministry of Energy auction round allocation splits between traditional grid-connected supply and hydrogen export-dedicated capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout | Utility-scale solar deployment under National Renewable Energy Program auctions anchors sovereign-backed revenue streams. |
| Power Purchase Agreement | Long-term offtake structures with government entities establish financing benchmarks competitors must match. |
| Technology Licensing | High-efficiency cell technology access from tier-one manufacturers determines module cost competitiveness. |
| Backward Integration into Storage | Battery pairing with intermittent solar generation meets Electricity and Cogeneration Regulatory Authority stability requirements. |
| Green Certification Program | Saudi Standards, Metrology and Quality Organization local content thresholds unlock auction eligibility and financing access. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of Ministry of Energy auction documentation, Electricity and Cogeneration Regulatory Authority grid code filings, and project finance databases. Primary interviews engaged utility planning officers at Saudi Electricity Company, independent power project developers with active Saudi pipelines, EPC contractors specializing in desert installations, and grid operators managing renewable interconnection queues. Secondary validation drew from International Energy Agency renewable market reports, FERC-style regulatory filings adapted to Saudi frameworks, and customs data tracking photovoltaic module import flows. Bottom-up project-level capacity aggregation and top-down macroeconomic scenario modeling were cross-referenced for triangulation.
Segmentation dimensions modeled span technology type, end-user category, energy source classification, and application use case across the projection horizon. Technology splits capture photovoltaic, concentrated solar power, and onshore wind deployment with distinct engineering and equipment supply chains. End-user segmentation distinguishes industrial, government, commercial, and residential procurement patterns with varying contract duration and pricing mechanisms. Analytical framework outputs reflect compound annual growth rate derivation from project pipeline visibility, auction round commitments, and green hydrogen export capacity allocation scenarios. Forecast inputs incorporate solar irradiance resource assessments, wind capacity factor measurements from northern highlands meteorological stations, and desalination load growth projections from Saline Water Conversion Corporation planning documents.
Underlying assumptions cover sovereign offtake guarantee continuity, local content threshold stability, and green hydrogen export market development, with deviation risk concentrated in Ministry of Energy auction allocation shifts between domestic supply and hydrogen feedstock commitments. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
China Solar Energy Market
Renewable Energy
Hybrid Solar Wind Diesel Market
Renewable Energy
Israel Renewable Energy Market
Renewable Energy
Uzbekistan Renewable Energy Market
Renewable Energy
Solar Bicycle Shed Market
Renewable Energy
South Africa Solar Energy Market
Renewable Energy
Wind Turbine Foundation Market
Renewable Energy
Switzerland Renewable Energy Market
Renewable Energy
Norway Renewable Energy Market
Renewable Energy
Tidal Energy Generation Systems Market
Renewable Energy
Wind Turbine Inspection Drones Market
Renewable Energy
Algeria Renewable Energy Market
Renewable Energy
New Zealand Renewable Energy Market
Renewable Energy
Canada Renewable Energy Market
Renewable Energy
Romania Power Market
Renewable Energy
Ethiopia Renewable Energy Market