
 Turkey Renewable Energy Market | 2026-2036
Turkey Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Turkey Renewable Energy Market Outlook
Grid-code compliance tier upgrades is reorganizing procurement standards across Turkey's renewable energy sector. Borusan EnBW Enerji leverages its German-Turkish joint venture structure to sustain high-efficiency wind turbine deployment across the Marmara region. Kalyon Enerji anchors domestic solar module manufacturing through integrated photovoltaic cell production in Ankara. Akfen Renewables competes on utility-scale project development, securing long-term power purchase agreements with industrial offtakers.
Turkey renewable energy encompasses electricity generation systems harnessing solar irradiance, wind kinetic energy, hydrological flow, and geothermal heat through photovoltaic cells, horizontal-axis turbines, run-of-river plants, and binary-cycle geothermal facilities operating at conversion efficiencies between 15% and 45% depending on resource quality and technology configuration. Solar PV dominates capacity additions across the Technology Type dimension, driven by declining module costs and favorable irradiation profiles in Central Anatolia. Wind Turbines capture premium margins along the Aegean and Marmara coastlines where capacity factors exceed national averages. Geothermal maintains stable baseload contribution from the Aegean graben systems near Aydın and Denizli.
Turkey's Energy Market Regulatory Authority enforces licensing frameworks under Law No. 5346, while the Turkish Standards Institution certifies equipment compliance with TS EN standards adapted from IEC and EN baselines. The Ministry of Environment, Urbanization and Climate Change mandates environmental impact assessments for projects exceeding 50 MW capacity thresholds, shaping development timelines and site selection criteria. Stakeholders must monitor pending revisions to the Renewable Energy Resources Support Mechanism tariff structure and localization requirements for turbine and solar component sourcing.

Market Dynamics
Feed-in tariff recalibration under Turkey's Renewable Energy Resources Support Mechanism is compressing project IRRs and forcing developers toward merchant power exposure. Grid-code compliance tier upgrades are simultaneously raising capital barriers for new entrants while rewarding incumbent fleet modernization.
Growth Catalysts
- Localization mandates:The Turkish Ministry of Energy and Natural Resources requires domestic content thresholds for solar modules and wind components, stimulating captive manufacturing investments across Ankara and Izmir industrial zones.
- Industrial offtake surge:Energy-intensive manufacturers in the Konya automotive cluster and Izmir chemicals corridor are executing direct power purchase agreements to hedge volatile TRY-denominated grid tariffs.
- Geothermal baseload stability:Binary-cycle plants in the Aydın-Denizli graben systems provide non-intermittent capacity, attracting aluminum smelters and cement producers seeking 24/7 clean power.
Market Restraints
- Currency volatility exposure:Equipment imports denominated in EUR and USD create margin compression for developers with TRY-revenue power purchase agreements.
- Land use conflicts:Agricultural protection zones in the Konya Plain block utility-scale solar siting, redirecting projects toward lower-irradiance marginal lands.
- Grid absorption limits:Transmission congestion in the Aegean wind corridor forces curtailment during high-generation periods, degrading capacity factor economics.
Strategic Opportunities
- Hybrid plant configurations:Co-located solar-plus-storage systems in Central Anatolia capture peak shaving revenues and ancillary service payments from TEİAŞ.
- Green hydrogen off-take:The Ministry of Energy's hydrogen roadmap creates demand anchors for renewable power in ammonia and steel decarbonization pilots.
- Behind-the-meter C&I:Unmet rooftop solar potential across Istanbul and Bursa manufacturing estates offers distributed generation plays bypassing licensing queues.
Industry Challenges
- Turkish Standards Institution certification bottlenecks:TS EN 61400 and TS IEC 61215 testing queue delays stretch equipment approval timelines, freezing project financial close.
- Skilled commissioning engineer scarcity:Grid-code compliance expertise for inverter synchronization and SCADA integration concentrates among a handful of Ankara-based technical consultancies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Turkey Renewable Energy Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Energy Source: Solar, Wind, Hydropower, Biomass Technology Type: Solar PV, Wind Turbines, Hydro Electric, Geothermal Application: Power Generation, Heating, Transportation, Off-Grid Solutions End User: Utilities, Residential, Commercial, Industrial |
| Companies Covered | Borusan EnBW Enerji, Sanko Energy Group, Enerjisa Üretim, İÇ İçtaş Energy Investment Holding, Galata Wind Enerji, Kalyon Enerji, Zorlu Enerji, Polat Enerji Yatirimlari A.Ş., Akfen Renewables, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Turkey Renewable Energy Market Strategic Shifts
Bifacial photovoltaic module deployment and floating solar pilots are redrawing project economics across Turkey's renewable energy sector. Technology convergence and procurement model evolution are compressing traditional development cycles.
Agrivoltaic arrays combining solar generation with protected crop cultivation are decomposing the land-use tradeoff that constrained Konya Plain expansion. Agricultural cooperatives in Karaman province are leasing plots beneath elevated bifacial structures, capturing dual revenue streams while maintaining soil productivity. This configuration is decomposing the zero-sum competition between food security and energy targets that previously stalled permitting.
TEİAŞ grid connection queue reforms under Energy Market Regulatory Authority directive EMRA-2023-48 are accelerating project energization timelines. The centralized pre-licensing portal reduces interconnection study periods from 18 months to 9 months for sub-50 MW solar facilities. Developers in the Aegean region are restructuring project finance assumptions around these compressed regulatory milestones.
Corporate buyers in the Marmara manufacturing belt are abandoning traditional feed-in tariff enrollment for sleeved direct agreements with independent generators. Automotive suppliers in Bursa are contracting 10-year baseload swaps with wind portfolios, transferring volume risk to aggregators. This bilateral contracting surge concentrates most visibly among export-oriented firms seeking RE100 compliance for EU customer audits.
Turkey Renewable Energy Market Segmentation
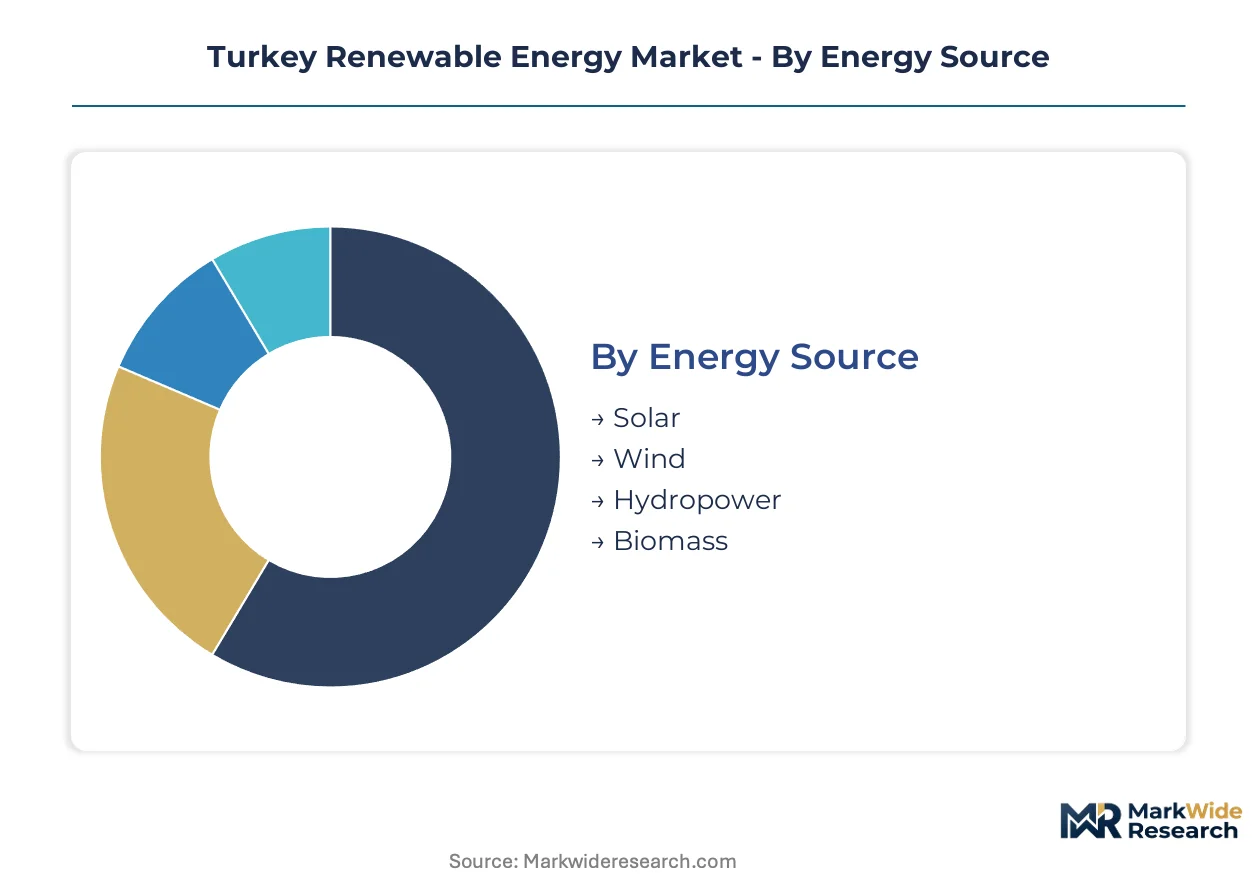
Turkey's renewable energy market segments reflect distinct regulatory treatment, technology maturity, and capital intensity profiles. Understanding these divisions clarifies where feed-in tariff adjustments and localization mandates concentrate competitive pressure.
Energy Source:
The Turkish Ministry of Energy and Natural Resources applies differentiated tariff bands and domestic content requirements across primary energy categories.
- Solar:Photovoltaic installations dominate capacity additions, with crystalline-silicon modules capturing the Konya Plain's high irradiance. Industrial offtakers in the Anatolian automotive corridor are contracting direct solar supply to hedge lira-denominated grid volatility.
- Wind:Onshore turbines along the Aegean and Marmara coastlines achieve capacity factors exceeding national averages. Borusan EnBW Enerji leverages its German-Turkish joint venture structure to deploy high-efficiency units despite currency exposure on imported nacelles.
- Hydropower:Run-of-river plants in the Eastern Anatolia region provide seasonal peaking capacity. Aging dam infrastructure requires rehabilitation investment to maintain grid stability contributions.
- Biomass:Agricultural residue-fired facilities concentrate in the Black Sea coastal zones. Feedstock logistics constraints limit project scale below utility-scale thresholds.
Established volume favors wind; emerging adoption favors solar.
Technology Type:
Capital deployment patterns cluster around conversion efficiency benchmarks and equipment localization feasibility.
- Solar PV:Bifacial module deployment is redrawing project economics across Central Anatolia. Kalyon Enerji's integrated cell production in Ankara satisfies domestic content thresholds for premium tariff eligibility.
- Wind Turbines:Horizontal-axis units face grid-code compliance tier upgrades that raise capital barriers for new entrants. Incumbent fleet modernization captures enhanced ancillary service revenues from TEİAŞ.
- Hydro Electric:Small-scale run-of-river configurations avoid the environmental impact assessment thresholds that delay large reservoir projects. Permitting timelines compress development cycles for sub-50 MW facilities.
- Geothermal:Binary-cycle plants in the Aydın-Denizli graben systems deliver non-intermittent baseload. Aluminum smelters and cement producers contract 24/7 clean power from these resources.
Technology maturity concentrates investment in solar PV; grid stability premiums sustain geothermal.
Application:
End-use configuration determines interconnection study complexity and revenue stream diversification.
- Power Generation:Utility-scale projects queue for TEİAŞ grid connection under EMRA-2023-48 directive reforms. Pre-licensing portal compression from 18 to 9 months accelerates financial close assumptions.
- Heating:Geothermal district heating networks serve residential zones in Western Anatolia. Seasonal demand curves mismatch electricity generation profiles, requiring separate tariff treatment.
- Transportation:Electrolyzer pilots for green hydrogen production anchor renewable power demand under the Ministry of Energy's hydrogen roadmap. Ammonia and steel decarbonization projects provide demand visibility.
- Off-Grid Solutions:Distributed solar-plus-storage systems in Eastern provinces bypass transmission congestion. Agricultural cooperatives deploy these where grid extension economics fail.
Grid-connected volume dominates power generation; electrification tailwinds favor transportation applications.
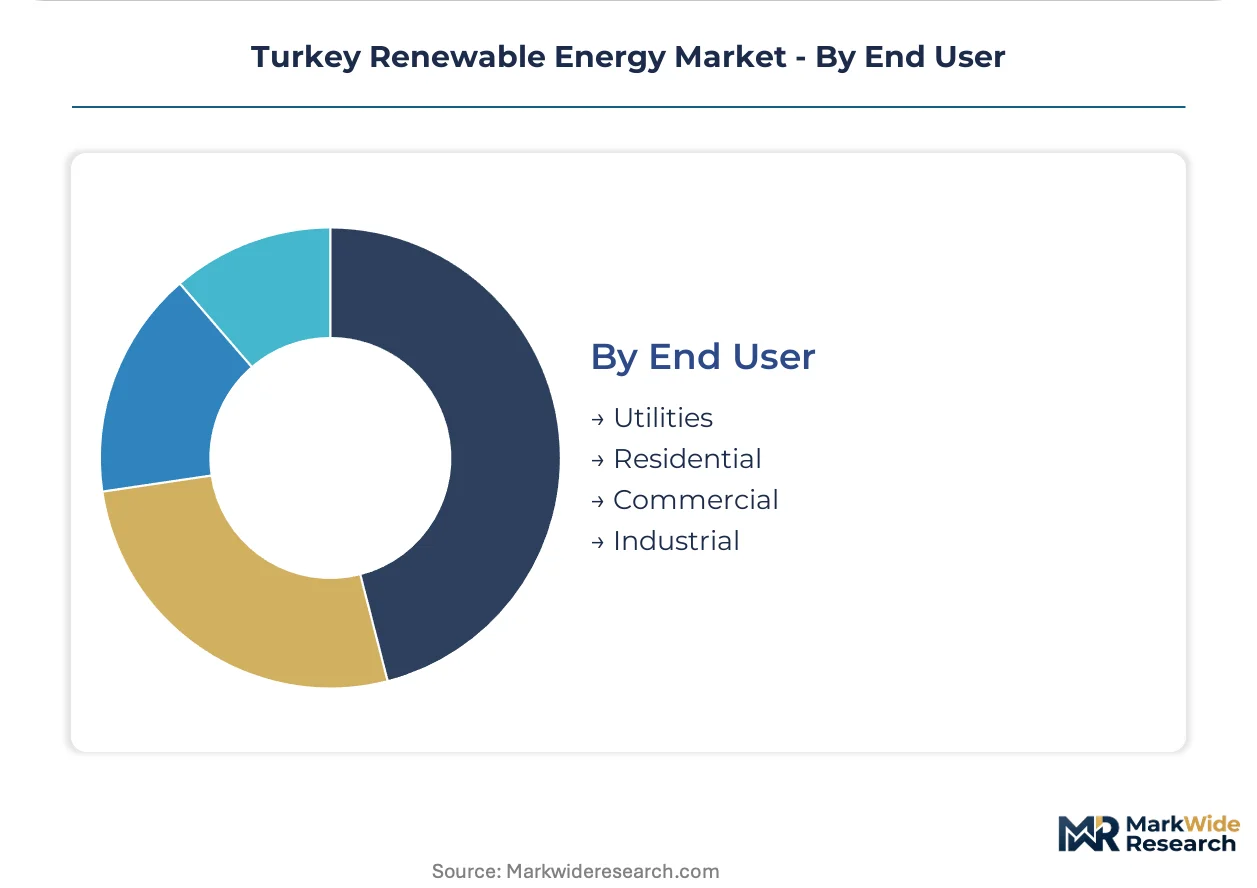
End User:
Procurement sophistication and contract tenure vary sharply across customer categories.
- Utilities:State-owned generation companies aggregate renewable output for regulated tariff pools. Feed-in tariff recalibration compresses project IRRs and forces merchant power exposure.
- Residential:Rooftolar potential across Istanbul and Bursa manufacturing estates remains underdeveloped. Net metering frameworks lack the revenue certainty that attracts private capital.
- Commercial:Behind-the-meter installations bypass licensing queues and capture avoided grid tariffs. Retail chains and logistics facilities prioritize payback periods under five years.
- Industrial:Energy-intensive manufacturers execute sleeved direct agreements with independent generators. Export-oriented firms seek RE100 compliance for EU customer audits through 10-year baseload swaps.
Contract scale favors utilities; margin expansion favors industrial offtakers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Turkey's renewable energy trade balance tilts toward equipment imports, with TRY-denominated revenues exposing developers to currency mismatch against EUR and USD procurement costs. Regional deployment concentrates where transmission infrastructure, industrial load centers, and resource quality intersect.
Marmara Region
Wind corridors along the Çanakkale and Tekirdağ coastlines attract utility-scale turbine deployment. EMRA licensing reforms compress pre-authorization timelines for sub-50 MW facilities. Borusan EnBW Enerji leverages its German-Turkish joint venture structure to deploy high-efficiency units across Bandırma and Karacabey industrial zones.
Aegean Region
Geothermal baseload from Aydın-Denizli graben systems serves aluminum smelters and cement producers requiring 24/7 clean power. The Ministry of Environment mandates environmental impact assessments for plants exceeding 50 MW thresholds. Binary-cycle facilities in Germencik and Salihli anchor industrial decarbonization contracts.
Central Anatolia
The Konya Plain's irradiance profiles drive crystalline-silicon photovoltaic expansion despite agricultural land-use conflicts. Kalyon Enerji's integrated cell production in Ankara satisfies domestic content requirements for premium tariff eligibility. Agrivoltaic pilots in Karaman province decompose food-energy competition through elevated bifacial structures.
Black Sea Region
Run-of-river hydropower in the Eastern Anatolia zone provides seasonal peaking capacity. Aging dam infrastructure requires rehabilitation investment to maintain grid stability contributions. Small-scale configurations below 50 MW bypass extended permitting timelines that delay reservoir projects.
Southeastern Anatolia
Distributed solar-plus-storage systems bypass transmission congestion where grid extension economics fail. Agricultural cooperatives deploy off-grid solutions for irrigation pumping in Şanlıurfa and Mardin provinces. TEİAŞ interconnection queues redirect capital toward behind-the-meter configurations.
Turkey Renewable Energy Market Competitive Environment
Listed energy conglomerates compete with private development specialists across project origination and offtake contracting. Market structure tilts toward vertically integrated players controlling manufacturing, development, and power marketing functions. Three archetypes dominate: German-Turkish joint ventures leveraging technology transfer, domestic integrated manufacturers satisfying localization mandates, and independent power producers securing long-term industrial contracts. Competitive intensity concentrates on feed-in tariff queue positioning and grid-code compliance tier upgrades.
Within the joint-venture tier, Borusan EnBW Enerji represents cross-border technology transfer models. Among domestic integrated manufacturers, Kalyon Enerji occupies a position exemplifying captive module production. At the independent developer end, Akfen Renewables anchors utility-scale project origination capabilities. These three entities collectively illustrate how Turkish renewable energy competitive dynamics fragment across capital structure, supply chain control, and customer segmentation dimensions.
| Leading Market Players |
|---|
| Borusan EnBW Enerji |
| Sanko Energy Group |
| Enerjisa Üretim |
| İÇ İçtaş Energy Investment Holding |
| Galata Wind Enerji |
| Kalyon Enerji |
| Zorlu Enerji |
| Polat Enerji Yatirimlari A.Ş. |
| Akfen Renewables |
| Others |
Value Chain & Pricing Dynamics
TS EN certification gates under the Turkish Standards Institution simultaneously filter equipment suppliers and stratify price tiers across module and turbine procurement. Developers bearing TS IEC 61215 or TS EN 61400 compliance costs pass these premiums through to offtake contracts, while non-certified equipment faces exclusion from feed-in tariff eligibility entirely.
Pricing Analysis
Industrial OEM buyers anchor long-term power purchase agreements that compress developer margins against TRY-denominated revenue exposure. Pricing stratifies across premium, standard, and economy tiers based on domestic content ratios and grid-code compliance tier levels. Cost compression in the standard tier intensifies because currency volatility on imported inverters and nacelles erodes project IRRs. Export-oriented manufacturers seeking RE100 compliance show least price sensitivity, while utilities aggregating for regulated tariff pools drive hardest bargain terms.
Supply Chain Analysis
Container availability fluctuations on the Asia-Europe trade lane through Mersin and Izmir ports inflate inbound logistics costs for crystalline-silicon wafers and power electronics. Manufacturing concentration centers on China for photovoltaic cells, Germany for turbine nacelles, and South Korea for inverter components. Polysilicon and rare-earth magnet dependencies create single-source vulnerability during trade restriction episodes. Distribution runs through EPC contractors with TEİAŞ grid connection mandates, bypassing direct developer-procurement channels for utility-scale projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Turkey's renewable energy incumbents must defend against natural gas-fired generation substitutes that retain cost advantages during lira depreciation cycles. Feed-in tariff recalibration and merchant power exposure demand strategic repositioning across three stakeholder archetypes.
For Market Incumbents: Fortify domestic content ratios through backward integration into module assembly and inverter manufacturing. Borusan EnBW Enerji's German-Turkish joint venture structure demonstrates how technology transfer agreements preserve turbine supply access during currency volatility. Captive production of bifacial cells satisfies localization mandates and secures premium tariff eligibility against merchant power exposure. For New Entrants and Emerging Players: Anchor in behind-the-meter commercial and industrial rooftop solar across Istanbul and Bursa manufacturing estates, where licensing queue bypass and avoided grid tariffs create immediate payback visibility. The Konya automotive cluster's unmet demand for direct power purchase agreements offers a penetrable offtake segment. Go-to-market execution should emphasize 10-year baseload swaps with export-oriented firms facing RE100 compliance audits. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across distributed solar-plus-storage configurations as battery costs compress and TEİAŞ ancillary service payments materialize. Acquisition targets should display hybrid plant development capabilities with integrated storage engineering. The signal to watch is EMRA directive implementation speed for pre-licensing portal compression timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Content Compliance Program | Captive module production secures premium tariff eligibility under Renewable Energy Resources Support Mechanism localization thresholds. |
| Hybrid Plant Configuration Buildout | Co-located solar-plus-storage systems capture peak shaving revenues and TEİAŞ ancillary service payments in Central Anatolia. |
| Direct Power Purchase Agreement Portfolio | Sleeved bilateral contracts with industrial offtakers transfer volume risk and hedge TRY-denominated grid tariff volatility. |
| Grid-Code Compliance Tier Upgrade | Modernized inverter synchronization capabilities unlock enhanced ancillary service revenue streams from TEİAŞ dispatch. |
| Agrivoltaic Development Pipeline | Elevated bifacial structures in Karaman province decompose land-use conflicts while maintaining agricultural productivity beneath arrays. |
Study Parameters
Initial hypotheses were tested against primary input from IPP project developers, EPC contractors, utility planning officers at TEİAŞ, and industrial offtake procurement leads, then refined through secondary validation against EMRA licensing databases, Ministry of Energy tariff circulars, and TEİAŞ grid connection queue records. Bottom-up project pipeline aggregation triangulated against top-down macroeconomic scenario modeling to constrain forecast variance.
Variance decomposition across the projection horizon isolates technology cost curves, currency volatility regimes, and regulatory timeline uncertainty as primary forecast drivers. Segmentation dimensions span energy source, technology type, application, and end user, with additional modeling of domestic content ratio tiers and grid-code compliance levels. CAGRs derive from installed capacity buildout trajectories, capacity factor assumptions by region, and merchant power price evolution under lira depreciation scenarios.
Underlying assumptions cover feed-in tariff stability, TEİAŞ interconnection queue reform implementation, and localization mandate enforcement continuity, with deviation risk concentrated in currency volatility spikes and agricultural land-use policy reversals in the Konya Plain. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Spain Renewable Energy Market
Renewable Energy
LAMEA Wave and Tidal Energy Market
Renewable Energy
United States Renewable Energy Market
Renewable Energy
Zimbabwe Renewable Energy Market
Renewable Energy
Tidal Energy Generation Systems Market
Renewable Energy
Philippines Power Market
Renewable Energy
Solar Thermal Water Heater Market
Renewable Energy
China Wind Energy Market
Renewable Energy
South Africa Renewable Energy Market
Renewable Energy
Global Green Energy Market
Renewable Energy
Biogas Upgrading Technology Market
Renewable Energy
United Arab Emirates Renewable Energy Market
Renewable Energy
Biogas Plant Market
Renewable Energy
South Africa Distributed Solar Energy Market
Renewable Energy
Kazakhstan Renewable Energy Market
Renewable Energy
Solar Balloon Market