
 Solar Tree Market | 2026-2036
Solar Tree Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Tree Market Analytics
Direct-to-municipality procurement channels is fragmenting as solar tree vendors bypass traditional EPC contractors to bid on smart-city infrastructure packages. OmniVolt Solar leverages its rotating-tracker intellectual property to anchor premium projects in European public spaces. Illumetric competes through integrated energy-storage configurations that extend deployment flexibility for off-grid installations. SmartHelio differentiates via AI-driven sun-tracking algorithms that optimize photovoltaic surface exposure throughout diurnal cycles.
A solar tree is a vertically oriented photovoltaic assembly mounted on a single trunk-like support structure, typically incorporating 1-3 kW of monocrystalline or bifacial panel capacity with integrated wiring conduits and optional battery storage at the base. The design maximizes energy generation within constrained footprints, serving commercial purposes ranging from electric vehicle charging to off-grid lighting in dense urban corridors. Fixed-structure products dominate current municipal procurement volumes due to lower capital outlay and reduced maintenance complexity, while rotating configurations capture accelerating interest from private developers seeking optimized yield-per-square-meter. Charging station applications concentrate margin pools where corporations negotiate power-purchase agreements tied to employee and fleet electrification programs.
Germany's KBA certifies structural safety for roadway-adjacent solar tree installations, while India's BIS mandates photovoltaic module efficiency thresholds under its PLI scheme for domestic manufacturing. The EU Green Deal and associated F-Gas Regulation indirectly shape demand by accelerating municipal decarbonization timelines that favor distributed renewable assets. Stakeholders must monitor evolving grid-interconnection standards and storage-integration requirements as hybrid solar tree configurations enter broader commercialization.
Market Dynamics
Bifacial photovoltaic cell technology is collapsing the energy-yield gap between fixed and rotating solar tree configurations, forcing municipal buyers to recalibrate procurement criteria around lifetime output rather than upfront capital expenditure.
Growth Catalysts
- EU Green Deal decarbonization timelines:Municipalities across Germany and France accelerate distributed renewable asset deployment to meet binding emission reduction targets.
- Electric vehicle charging infrastructure:Corporations negotiate power-purchase agreements for employee and fleet electrification programs, anchoring margin pools in urban corridor installations.
- Bifacial cell efficiency thresholds:India's PLI scheme mandates domestic manufacturing standards that improve module performance for public plaza deployments.
Market Restraints
- Polysilicon input cost volatility:Raw material price swings compress project margins for fixed-structure products dominating municipal procurement volumes.
- Grid-interconnection standards fragmentation:Divergent technical requirements across KBA-certified German installations and BIS-mandated Indian configurations increase engineering overhead.
- Conventional rooftop solar substitution:Lower-cost flat-panel alternatives capture budget-constrained urban renewable procurement outside premium public-space applications.
Strategic Opportunities
- Off-grid lighting applications:Integrated energy-storage configurations unlock deployment flexibility in dense urban corridors lacking reliable grid access.
- AI-driven sun-tracking convergence:Algorithmic optimization of photovoltaic surface exposure enables rotating configurations to capture private developer interest in yield-per-square-meter optimization.
- Smart-city infrastructure packages:Direct-to-municipality procurement channels allow vendors to bypass traditional EPC contractors and anchor premium projects in European public spaces.
Industry Challenges
- Structural safety certification timelines:KBA roadway-adjacent approval processes and BIS efficiency testing create extended validation cycles for new product introductions.
- Storage-integration technical complexity:Hybrid solar tree configurations require specialized electrical engineering talent scarce in traditional solar installation workforces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Tree Market |
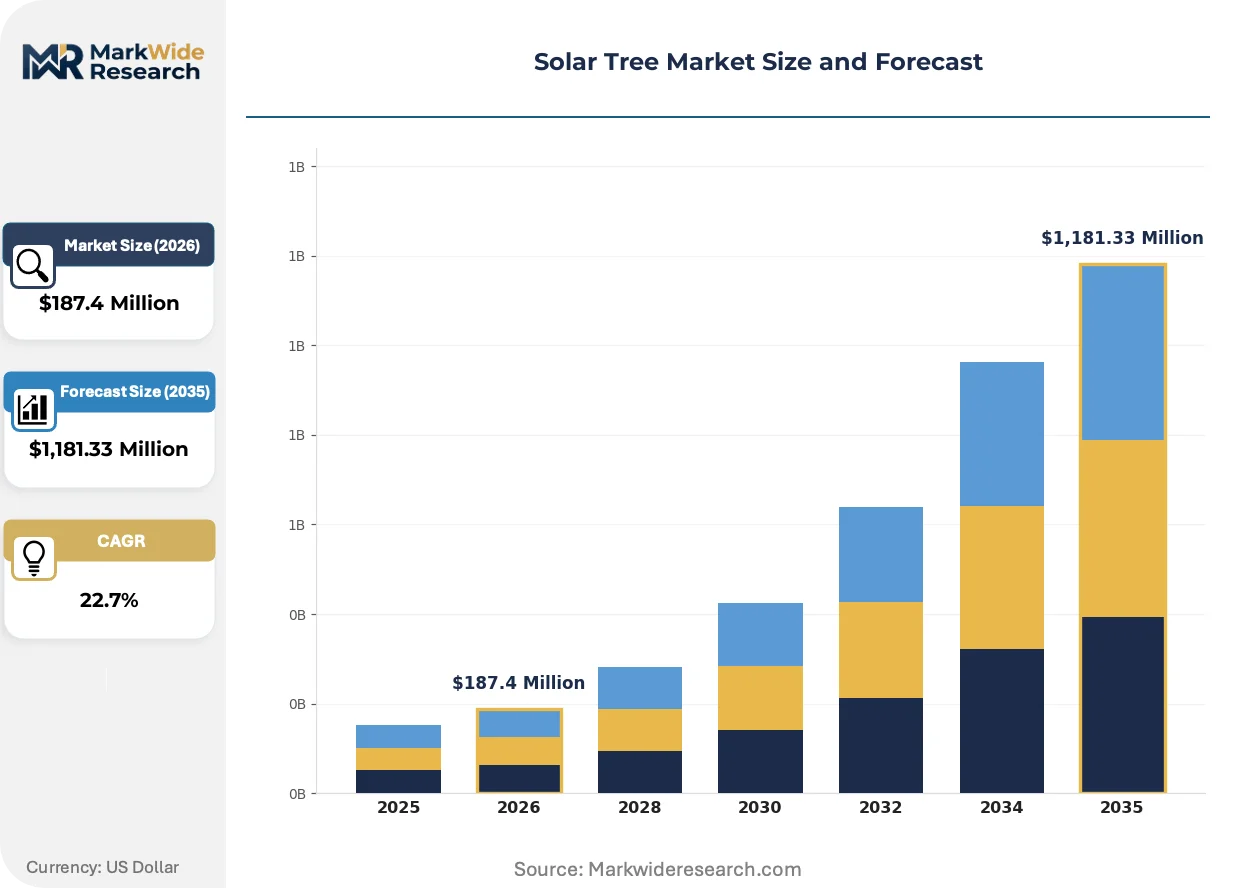
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,181.33 Million |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed, Rotating, Hybrid, Portable Application: Urban Development, Renewable Energy, Public Spaces, Charging Stations Material: Aluminum, Stainless Steel, Composite, Glass End User: Municipalities, Private Developers, Educational Institutions, Corporations |
| Companies Covered | Illumetric, OmniVolt Solar, Solar Tree Company, SunTree Innovations, Tree Energy Solutions, SmartHelio, Green Venture Solar, Photon Harvest, SEED Solar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Tree Market Evolving Landscape
Active differentiation is shifting from hardware specifications to software-layer optimization, with algorithmic control systems and integrated storage management emerging as the primary vectors of competitive advantage.
Bifacial photovoltaic technology is collapsing the performance premium previously commanded by rotating-tracker systems. Municipal buyers in Germany and France now evaluate fixed-structure products on comparable lifetime yield metrics, compressing the addressable market for mechanical tracking solutions. Private developers in South Korea nonetheless pursue rotating configurations where land constraints maximize the value of optimized surface exposure.
The EU F-Gas Regulation indirectly shapes demand by accelerating municipal decarbonization timelines that favor distributed renewable assets over centralized generation retrofits. Grid-interconnection standards and storage-integration requirements are evolving in parallel, forcing manufacturers to engineer modular base configurations capable of accommodating future battery expansion without structural redesign. France's ANSM and Germany's KBA are coordinating technical safety protocols for hybrid installations.
Direct vendor engagement with municipal procurement offices is displacing traditional EPC contractor intermediation in smart-city infrastructure packages. Transit hub and public plaza deployments in India and South Korea increasingly originate from integrated technology-and-service bids rather than component supply contracts. This channel compression concentrates margin capture with manufacturers possessing in-house installation and maintenance capabilities.
Solar Tree Market Segmentation
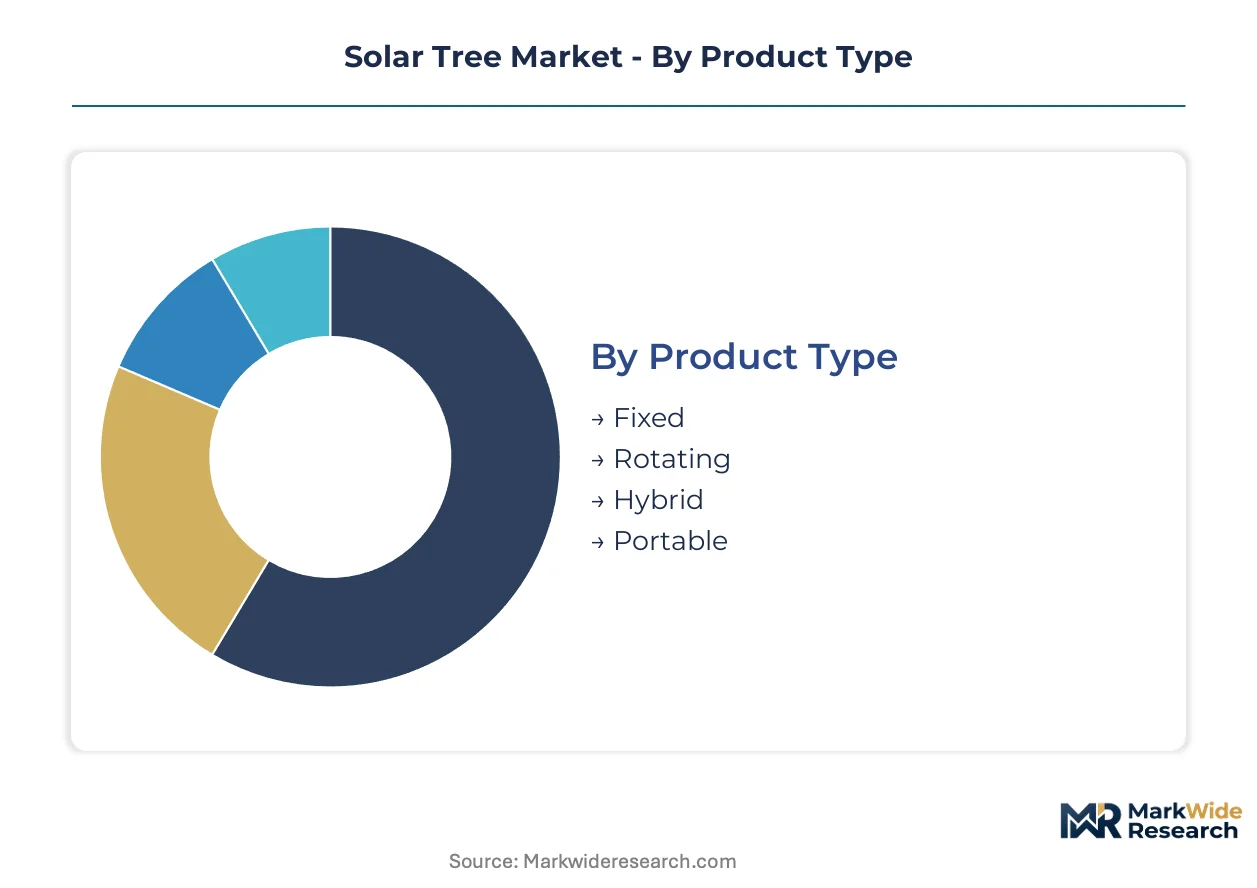
Solar tree configurations vary dramatically in mechanical complexity, material cost, and deployment flexibility. Procurement officers weigh structural permanence against yield optimization when matching product categories to specific urban infrastructure requirements.
Product Type:
Fixed structures anchor municipal budgets with predictable performance, while rotating and hybrid systems target yield-maximizing private investments.
- Fixed:Stationary monocrystalline or bifacial panel assemblies mounted on reinforced concrete foundations dominate public plaza and transit hub installations. Municipalities across Germany and India favor this configuration for charging station corridors where maintenance simplicity outweighs marginal energy gains.
- Rotating:Mechanical tracker systems adjust photovoltaic surface orientation throughout diurnal cycles using single-axis or dual-axis drives. Private developers in South Korea deploy these where land constraints maximize value per square meter, though KBA structural certification extends procurement timelines.
- Hybrid:Combines fixed primary arrays with limited tracking elements or integrated storage base units. Illumetric and similar vendors engineer modular configurations accommodating future battery expansion without structural redesign.
- Portable:Lightweight aluminum or composite structures designed for temporary deployment at events, construction sites, or disaster relief operations. Educational institutions pilot these for off-grid campus lighting before committing to permanent infrastructure.
Established volume favors Fixed; emerging adoption favors Hybrid.
Application:
Revenue concentration shifts from aesthetic public installations toward functional electrification infrastructure as fleet electrification accelerates.
- Charging Stations:Corporations negotiate power-purchase agreements for employee and fleet electrification programs, anchoring margin pools where energy yield directly correlates with vehicle throughput. France and South Korea concentrate procurement in urban corridor clusters.
- Urban Development:Integrated into smart-city infrastructure packages combining lighting, surveillance, and digital signage. Direct vendor engagement with municipal procurement offices displaces traditional EPC contractor intermediation.
- Public Spaces:Transit hubs and pedestrian plazas in Germany and India prioritize visual integration and structural safety certification over maximum energy output.
- Renewable Energy:Grid-interconnection projects treating solar trees as distributed generation assets rather than amenity infrastructure. EU Green Deal decarbonization timelines accelerate this application category.
Margin capture concentrates in Charging Stations; deployment scale concentrates in Urban Development.
Material:
Cost tiers separate premium corrosion-resistant specifications from economy-grade urban deployments.
- Aluminum:Lightweight extrusions dominate portable and hybrid configurations where transportation and installation labor represent significant project cost. India's PLI scheme encourages domestic aluminum fabrication for public plaza deployments.
- Stainless Steel:Marine-grade specifications anchor coastal installations and high-salinity environments where structural longevity justifies material premium.
- Composite:Fiber-reinforced polymers enable complex aesthetic geometries for premium public space installations. BIS efficiency testing protocols currently exclude certain composite structural elements from certification.
- Glass:Bifacial panel substrates and protective surface treatments. Bifacial cell technology improvements collapse the performance gap between fixed and rotating configurations.
Procurement volume clusters in Aluminum; specification premiums accrue to Stainless Steel.
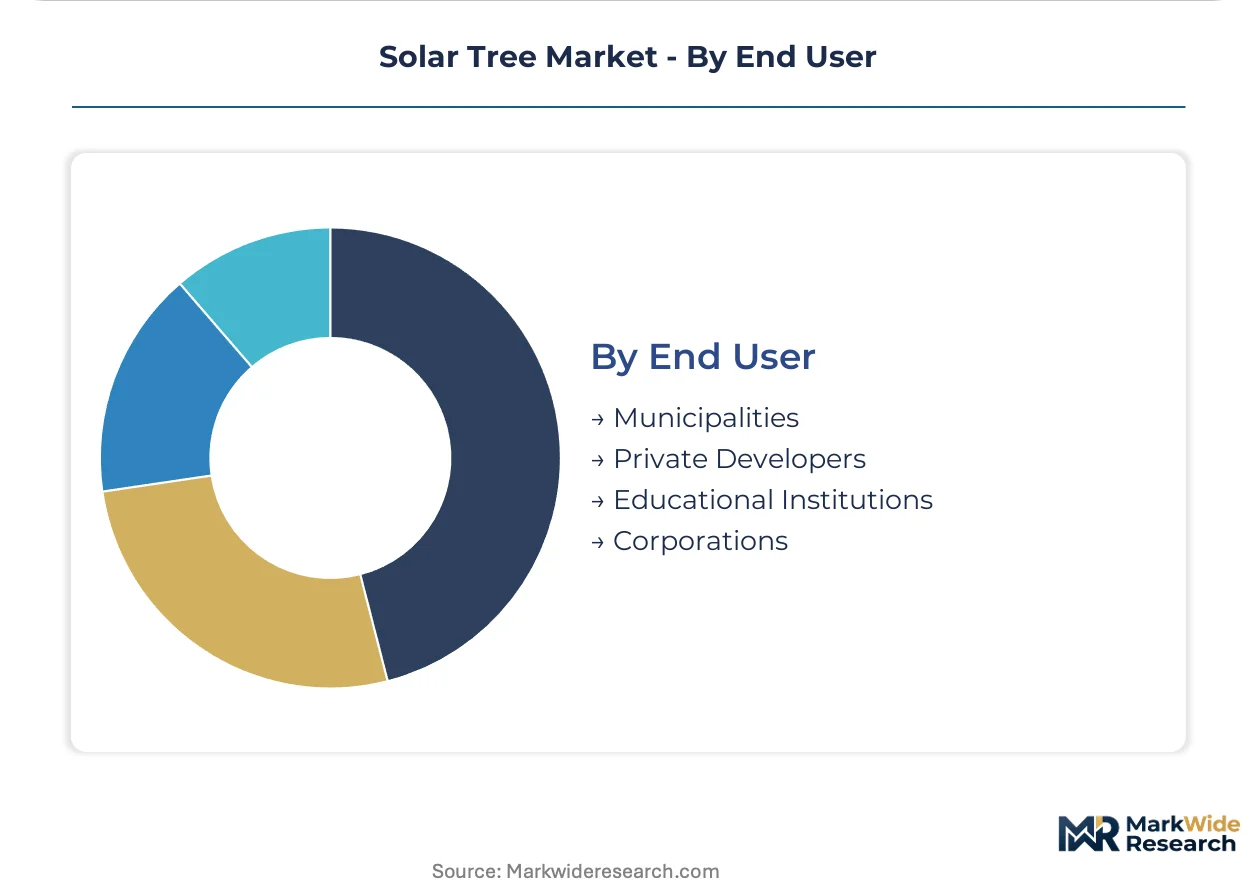
End User:
Customer type determines procurement channel structure and service bundling requirements.
- Municipalities:Direct-to-municipality bidding on smart-city infrastructure packages bypasses traditional EPC contractors. KBA and BIS certification requirements shape technical specifications.
- Corporations:Fleet electrification programs and employee charging amenities drive power-purchase agreement structures. Margin pools concentrate where energy yield guarantees support vehicle throughput commitments.
- Private Developers:Yield-per-square-meter optimization priorities favor rotating configurations despite higher capital outlay. South Korean urban density maximizes returns on tracking investments.
- Educational Institutions:Pilot deployments and sustainability demonstration projects. Off-grid lighting applications unlock deployment flexibility where campus grid access remains unreliable.
Contract value concentrates with Municipalities; growth velocity concentrates with Corporations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German municipalities command 30-40% pricing premiums over Indian procurement due to KBA structural certification requirements and EU Green Deal compliance timelines. Indian PLI scheme subsidies compress domestic manufacturing costs but extend validation cycles. This asymmetry shapes vendor prioritization across deployment clusters.
Germany
KBA roadway-adjacent certification anchors municipal procurement specifications for transit hub installations. The EU F-Gas Regulation accelerates distributed renewable asset timelines favoring fixed-structure solar trees in dense urban corridors. Berlin and Hamburg concentrate deployment in public plaza electrification projects tied to fleet decarbonization mandates.
India
BIS efficiency thresholds under the PLI scheme reshape domestic manufacturing capabilities for bifacial module integration. Municipal corporations in Delhi-NCR and Bengaluru bypass traditional EPC contractors through direct smart-city infrastructure bidding. Maharashtra's urban development authorities pilot hybrid configurations with integrated storage for grid-unreliable zones.
France
ANSM technical safety protocols coordinate with Germany's KBA on hybrid installation standards across the Rhine corridor. Corporations in Île-de-France negotiate power-purchase agreements for employee charging amenities anchored in La Défense and Roissy-Charles de Gaulle clusters. The EU Green Deal binding targets compress procurement decision cycles for urban corridor deployments.
South Korea
Seoul Capital Area density maximizes returns on rotating-tracker investments despite higher capital outlay. MFDS-equivalent technical standards for electrical safety shape product qualification timelines for private developers. Busan-Ulsan industrial zones concentrate corporate fleet electrification programs with throughput-linked energy yield guarantees.
United States
IRA production tax credits indirectly support domestic bifacial module supply chains feeding solar tree assembly. California's SB 100 decarbonization mandates accelerate municipal procurement in Los Angeles and San Diego transit corridors. Pacific Northwest technology campuses pilot off-grid lighting configurations before permanent infrastructure commitments.
Solar Tree Market Competitive Landscape
Rotating-tracker specialists and fixed-structure fabricators split the market along yield-optimization versus capital-efficiency fault lines. The vendor base concentrates around three strategic archetypes: IP-heavy mechanical tracking innovators, integrated storage configurators, and municipal-direct smart-city packagers. Consolidation pressure intensifies as bifacial cell efficiency collapses performance premiums previously commanded by mechanical complexity. Dominant competitive moves include direct-to-municipality channel compression and modular battery-expansion engineering for future-proofed base configurations.
Within the rotating-tracker tier, OmniVolt Solar exemplifies IP-anchored premium positioning through its single-trunk mechanical drive systems. Illumetric occupies the integrated-storage archetype with modular base configurations accommodating future expansion. SmartHelio represents the algorithmic-differentiation vector through AI-driven sun-tracking optimization. These three companies illustrate how competitive positioning shifts from hardware specifications toward software-layer control systems and storage management integration.
| Leading Market Players |
|---|
| Illumetric |
| OmniVolt Solar |
| Solar Tree Company |
| SunTree Innovations |
| Tree Energy Solutions |
| SmartHelio |
| Green Venture Solar |
| Photon Harvest |
| SEED Solar |
| Others |
Value Network & Pricing Analysis
Rhine-Alpine corridor freight rates from Rotterdam to Milan shape landed cost differentials between German fabricators and Asian module suppliers, compressing margin pools for fixed-structure vendors while amplifying price premiums for KBA-certified rotating configurations in municipal procurement.
Pricing Analysis
The customization-premium spread separates configured-to-order hybrid installations with modular battery expansion from standard fixed-structure products. Three-tier pricing structure across premium, standard, and economy levels reflects bifacial cell efficiency grades and KBA structural certification tiers. Cost compression in economy-grade aluminum configurations is intensifying because Indian PLI scheme subsidies expand domestic manufacturing capacity. Municipal buyers in Germany exhibit lowest price sensitivity due to EU Green Deal compliance mandates, while educational institutions piloting portable units face acute budget constraints.
Supply Chain Analysis
Export-control regimes limiting semiconductor-grade polysilicon flows from China reshape raw material access for photovoltaic module assembly. Manufacturing concentrates in China, India, and Germany for structural components, with Vietnam emerging for aluminum extrusion. Polysilicon ingots, tempered glass substrates, and lithium-ion storage cells anchor component dependencies. Single-source vulnerability runs through Chinese metallurgical-grade silicon purification. Distribution runs through direct-to-municipality bidding channels displacing traditional EPC contractor intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solar tree deployment sits in early-cycle expansion as EU member states accelerate distributed renewable asset procurement to meet binding decarbonization timelines, with bifacial cell efficiency improvements collapsing historical performance gaps between fixed and rotating configurations.
For Market Incumbents: Build algorithmic IP moats through AI-driven sun-tracking software layers that command recurring revenue streams. Deepen backward integration into bifacial module supply through captive manufacturing partnerships in India under PLI scheme coverage. Defensive moves must counter conventional rooftop solar substitution threatening budget-constrained municipal segments outside premium public-space applications. For New Entrants and Emerging Players: Maharashtra's grid-unreliable urban corridors present immediate white-space opportunity for hybrid configurations with integrated storage. Portable solar tree pilots at educational institutions offer lowest competitive intensity entry point. Go-to-market positioning should emphasize off-grid lighting flexibility for disaster relief and construction site temporary deployment. For Investors and Strategic Acquirers: Algorithmic-differentiation specialists with proprietary sun-tracking software represent priority acquisition archetypes for platform consolidation plays. Long-term viability hinges on software-layer margin capture displacing hardware commoditization. Watch for bifacial cell efficiency thresholds breaching rotating-tracker yield premiums as inflection signal for fixed-structure market share acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Battery Expansion Engineering | Illumetric-style base configurations accommodate future storage upgrades without KBA recertification delays. |
| Direct-to-Municipality Channel Compression | Bypassing EPC intermediaries captures margin pools in Berlin and Hamburg smart-city infrastructure packages. |
| AI-Driven Sun-Tracking Licensing | SmartHelio-type algorithmic optimization commands recurring revenue from private developers in Seoul Capital Area. |
| Bifacial Module Backward Integration | Captive supply under India's PLI scheme insulates against polysilicon input cost volatility. |
| Hybrid Configuration Certification | ANSM-KBA coordinated safety protocols unlock Rhine corridor transit hub deployments with storage integration. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of municipal procurement databases, EU Green Deal implementation trackers, and photovoltaic module trade flow data. Primary interviews engaged smart-city infrastructure officers at German municipalities, EPC contractors in Indian urban development authorities, and procurement leads at South Korean private developers. Secondary validation drew from KBA certification registries, BIS efficiency testing protocols, and F-Gas Regulation compliance filings. Bottom-up project pipeline aggregation triangulates against top-down renewable asset deployment targets.
Forecast inputs incorporate bifacial cell efficiency trajectories, municipal decarbonization timeline acceleration, and fleet electrification program expansion. Segmentation modeling spans product type, application category, material specification, and end-user archetype across the projection horizon. CAGRs derive from installed base growth rates correlated with charging station corridor development and public plaza electrification commitments. Grid-interconnection standard evolution and storage-integration technical complexity feed sensitivity scenarios.
The forecast holds incumbent behavior within observed patterns; aggressive moves by algorithmic-differentiation specialists or state-backed Chinese module manufacturers would shift outcomes. Material shifts in EU F-Gas Regulation enforcement stringency or Indian PLI scheme subsidy duration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Solar Farm Market
Renewable Energy
Hungary Renewable Energy Market
Renewable Energy
Republic of Ireland Renewable Energy Market
Renewable Energy
Venezuela Renewable Energy Market
Renewable Energy
Renewable Energy Contractor Market
Renewable Energy
Solar PV and Wind Energy Market
Renewable Energy
Solar Drying System Market
Renewable Energy
Renewable Energy Monitoring and Control System Market
Renewable Energy
United Arab Emirates Renewable Energy Market
Renewable Energy
North America Renewable Energy Market
Renewable Energy
Spain Renewable Energy Market
Renewable Energy
Solar District Heating Market
Renewable Energy
Africa Renewable Energy Market
Renewable Energy
India Renewable Energy Market
Renewable Energy
Asia-Pacific Renewable Energy Market
Renewable Energy
Mexico Renewable Energy Market