
 Solar Bicycle Shed Market | 2026-2036
Solar Bicycle Shed Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Bicycle Shed Market Insights
The split between premium integrated-system sheds and commodity standalone units is realigning procurement patterns across European municipal programs. Canadian Solar leverages its module-scale manufacturing to anchor large public-space installations across German cities. Swiftmile competes on charging-integrated designs that dominate transit-hub deployments in Copenhagen and Amsterdam. HBT Energy specializes in polycarbonate-roof structures that occupy the mid-tier institutional segment in Dutch provinces.
A solar bicycle shed combines photovoltaic panel arrays with weather-protected bicycle parking infrastructure, typically incorporating aluminum or steel framing with polycarbonate glazing and DC-to-AC microinverters rated between 300W and 600W per parking bay. The primary commercial purpose is generating on-site renewable electricity while protecting cycles from precipitation and UV degradation. Integrated Systems command the steepest margin pools where solar generation, battery storage, and e-bike charging converge in single-vendor packages. Modular Solutions represent the fastest-expanding category as Dutch and Danish municipalities phase standardized shelter rollouts across dispersed transit nodes. Aluminum-framed installations lead volume in coastal geographies where corrosion resistance extends structural service life.
EU Green Deal building-efficiency standards and the F-Gas Regulation's phase-down of hydrofluorocarbon coolants are reshaping thermal specifications for enclosed shed designs across member states. REACH compliance on photovoltaic component chemistry restricts certain backsheet polymers, compelling material substitutions that alter supplier qualification pathways. Stakeholders must monitor how national cycling-infrastructure subsidy programs in Germany, the Netherlands, and Denmark synchronize with local grid-interconnection rules for distributed solar assets.
Market Dynamics
The EU Green Deal's building-efficiency mandates are compressing procurement timelines for photovoltaic-integrated cycling infrastructure across European municipal transit authorities. This regulatory pressure is forcing a split between premium integrated-system vendors and commodity shelter suppliers, with specification standards tightening faster than supplier qualification pathways can adapt.
Growth Catalysts
- E-bike charging convergence:Municipalities in the Netherlands are mandating solar shelters with integrated DC fast-charging ports at transit nodes. This specification is pulling battery-inverter combinations into standard procurement bundles.
- F-Gas Regulation phase-down:The EU's hydrofluorocarbon coolant restrictions are eliminating conventional HVAC-dependent enclosed shed designs. Polycarbonate-roof passive ventilation systems are capturing displaced demand.
- Copenhagen metropolitan cycle network expansion:The Danish capital's 300-kilometer protected route program is specifying solar shelters at every 500-meter interval. This geographic concentration is anchoring volume commitments for aluminum-framed coastal-grade structures.
Market Restraints
- Aluminum price volatility:Coastal-grade frame extrusions depend on primary aluminum ingot supplies. LME price swings above 15% quarter-to-quarter are compressing fabrication margins for mid-tier Dutch suppliers.
- Microinverter supply concentration:DC-to-AC conversion hardware for 300W-600W bay ratings concentrates among three East Asian component houses. Single-source dependencies are extending lead times for German municipal rollouts.
- REACH polymer restrictions:Backsheet chemistry compliance is disqualifying legacy fluoropolymer suppliers. Material substitution cycles are adding 8-12 weeks to qualification timelines for polycarbonate glazing integrators.
Strategic Opportunities
- Danish provincial transit nodes:Secondary cities outside Copenhagen lack covered cycling infrastructure. Jutland and Funen municipalities are issuing bundled shelter tenders with 50-200 unit minimums.
- Battery-solar convergence:Second-life EV battery repurposing is enabling 10kWh-50kWh storage integration at marginal cost. This technology pairing is opening premium pricing tiers for overnight e-bike charging.
- German cycling infrastructure subsidies:The National Cycling Plan's 2025-2030 funding window is earmarking 12% of federal transport budget for covered parking. Application deadlines are compressing vendor selection cycles.
Industry Challenges
- Photovoltaic electrical certification backlog:Microinverter-grid interconnection testing for distributed solar assets faces 14-18 week queues at German certification bodies. Municipal procurement schedules are misaligned with approval timelines.
- Structural engineering skill scarcity:Combined solar-plus-civil design competency concentrates among specialized consultancies. Dutch provinces report 6-month search cycles for qualified shelter specification reviewers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Bicycle Shed Market |
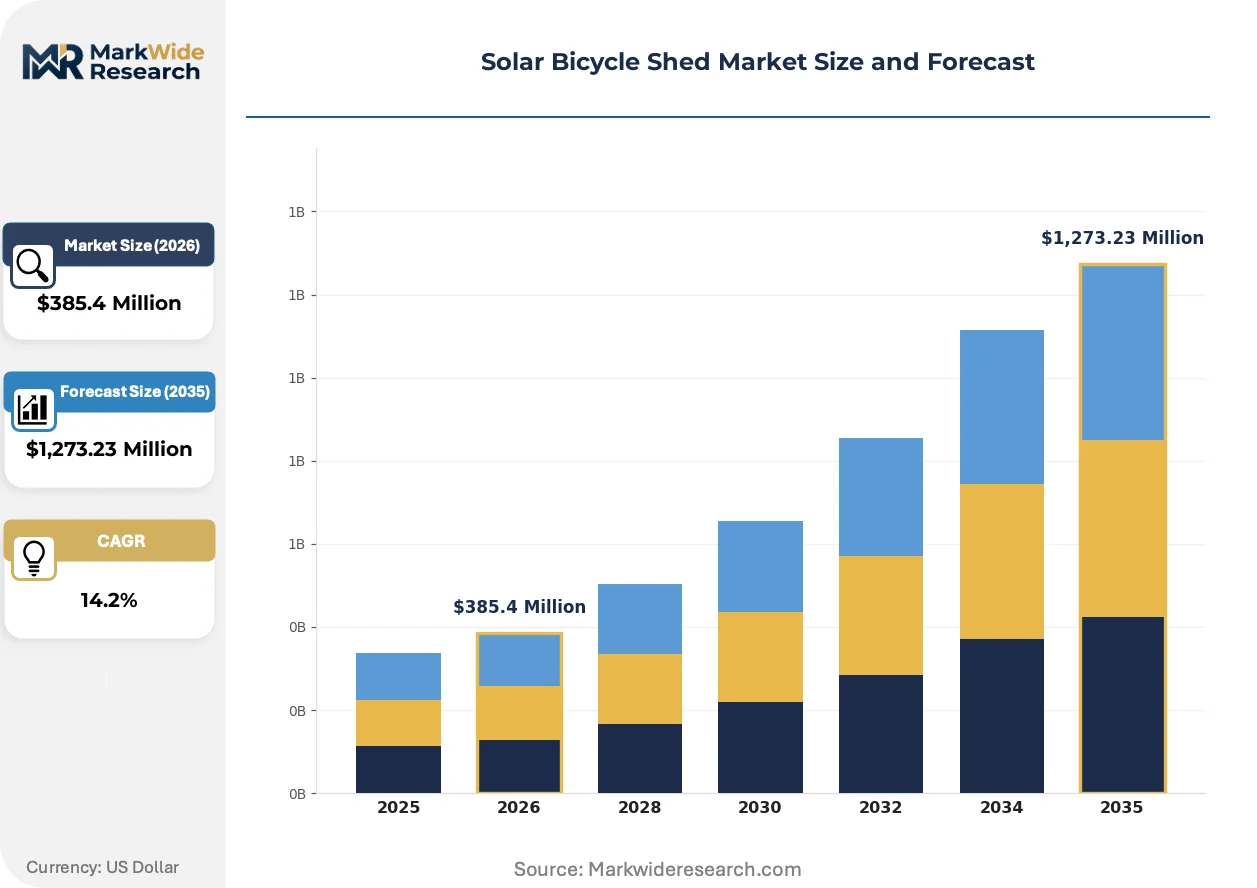
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,273.23 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Shed, Integrated Systems, Modular Solutions, Custom Designs Material: Aluminum, Steel, Polycarbonate, Wood Installation Type: Permanent, Temporary, Portable, Wall-Mounted End User: Residential, Commercial, Institutional, Public Spaces |
| Companies Covered | InfraMarks, Azure Bikes, HBT Energy, Sun-moon Power, Swiftmile, Canadian Solar, SolarEdge Technologies, SMA Solar Technology, LG Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Bicycle Shed Market Trends and Innovations
Power electronics miniaturization and passive thermal engineering are converging to reshape shelter design specifications. Vendors are racing to integrate storage and charging without expanding physical footprints or breaching municipal height restrictions.
Perovskite-silicon tandem photovoltaic modules are decentralizing generation density in constrained roof areas. German transit authorities in Hamburg and Munich are piloting these cells at 22% efficiency ratings versus 18% for conventional silicon. The technology is compressing the physical shelter footprint required per charging port by roughly 15%.
REACH compliance deadlines for fluorinated polymer phase-outs are accelerating material substitution programs across glazing suppliers. ECHA's 2025 restriction timeline is forcing polycarbonate and ETFE membrane qualification cycles. Dutch shelter fabricators are responding with accelerated weathering-test protocols to maintain municipal tender eligibility.
Municipal procurement offices are consolidating vendor relationships around single-source integrated-system contracts. Copenhagen's transit authority recently collapsed separate solar, storage, and charging specifications into unified performance-based tenders. This bundling is displacing standalone shelter suppliers who lack electrical engineering capabilities.
Solar Bicycle Shed Market Segmentation
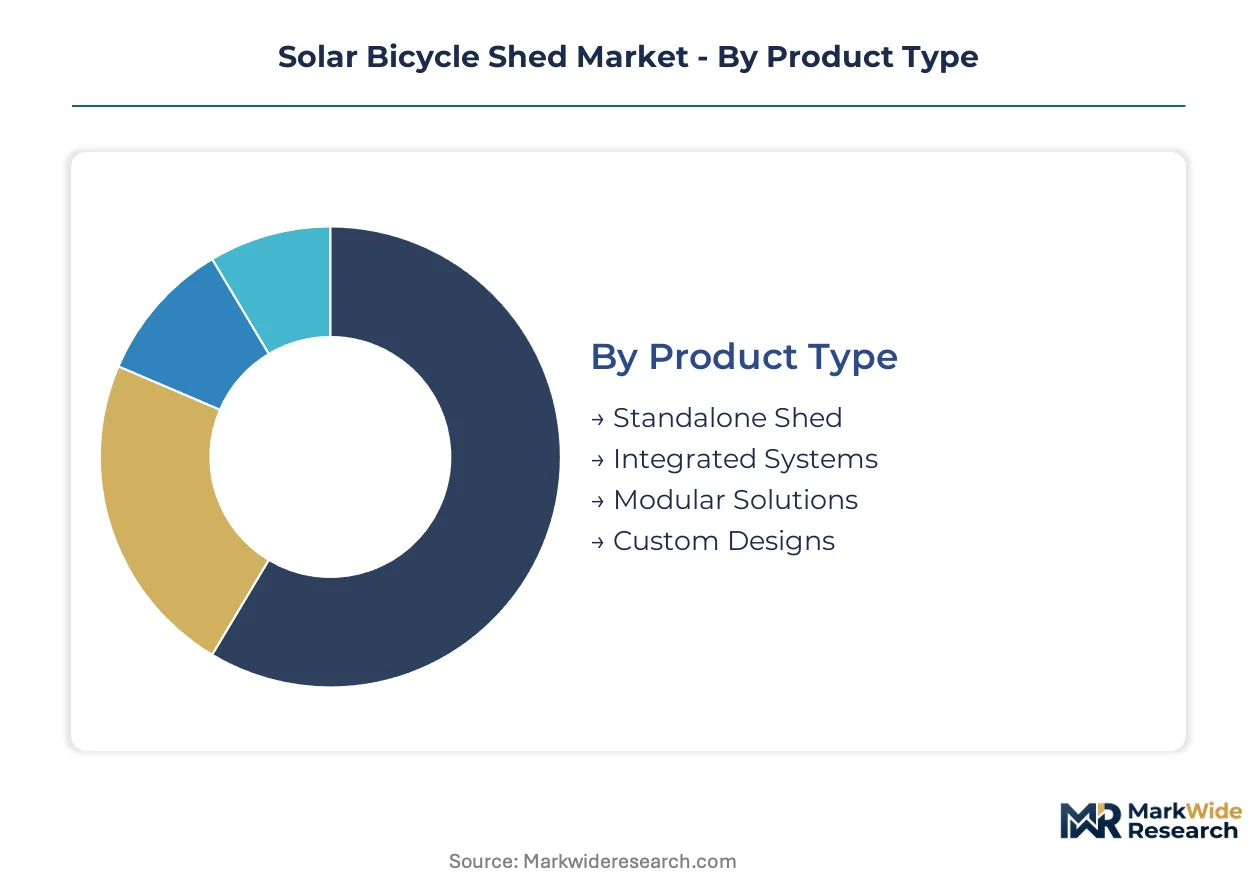
Solar bicycle shed procurement patterns diverge sharply between standardized municipal rollouts and bespoke architectural integrations. Specification complexity scales with end-use sophistication, from basic weather protection to grid-interactive energy assets.
Product Type:
The customization-standardization spectrum spans from off-the-shelf commodity units to engineered multi-function systems where solar generation, storage, and charging converge in single-vendor packages.
- Standalone Shed:Basic weather-protected bicycle parking with bolt-on photovoltaic arrays and minimal electrical integration. Dutch provinces favor these for dispersed rural transit nodes where grid interconnection costs exceed generation value.
- Integrated Systems:Converged packages combining photovoltaic generation, battery storage, and DC fast-charging ports within unified structural frames. Copenhagen's transit authority mandates these at every 500-meter interval across its metropolitan cycle network, compressing vendor qualification to electrical engineering-capable suppliers.
- Modular Solutions:Standardized bay units designed for rapid deployment across multiple sites with consistent specifications. German municipalities under National Cycling Plan timelines prefer these for volume procurement efficiency.
- Custom Designs:Architecturally specified structures integrating with heritage building envelopes or unique urban contexts. Amsterdam's canal-side districts and Hamburg's warehouse districts drive demand for these premium configurations.
Most installed capacity flows through Integrated Systems. Expansion is steepest in Modular Solutions.
Material:
Cost tier stratification separates premium corrosion-resistant alloys from commodity structural grades, with coastal exposure dictating material selection in North Sea and Baltic geographies.
- Aluminum:Coastal-grade extrusions with anodized finishes deliver 25-year service life in salt-air environments. Copenhagen's specifications require these for all harbor-proximate installations.
- Steel:Galvanized structural tubing dominates inland German deployments where corrosion exposure is limited and procurement budgets favor lower unit costs.
- Polycarbonate:UV-stabilized glazing panels provide passive thermal management without F-Gas Regulation-dependent HVAC systems. Dutch fabricators HBT Energy specialize in these mid-tier institutional structures.
- Wood:Laminated timber frames serve heritage-sensitive districts in Danish provincial cities where aesthetic integration outweighs maintenance cost considerations.
Aluminum commands the premium tier by performance specification. Polycarbonate is climbing fastest as passive ventilation designs displace enclosed HVAC-dependent alternatives.
Installation Type:
Application context determines mounting permanence, from anchored civil foundations to redeployable assets serving temporary event infrastructure or construction-phase mobility programs.
- Permanent:Cast-in-place concrete foundations with embedded electrical conduits for grid-interactive systems. German municipal transit authorities require 20-year structural warranties for these installations.
- Temporary:Ballasted or anchored systems without civil excavation, deployable for festival seasons or construction-phase cycling infrastructure. Rotterdam's port expansion zones utilize these during multi-year development cycles.
- Portable:Trailer-mounted or skid-based units redeployable across sites. Danish music festival circuits and seasonal tourist destinations drive this segment's niche demand.
- Wall-Mounted:Cantilevered structures attached to existing building envelopes, minimizing ground footprint in dense urban cores. Amsterdam's narrow canal-side streets favor these space-constrained configurations.
Permanent foundations anchor the majority of installed base. Temporary installations are expanding most quickly as construction-phase cycling mandates proliferate.
End User:
Customer type segmentation tracks procurement sophistication from individual residential decisions to centralized municipal tendering with performance-based specifications.
- Residential:Single-dwelling installations typically serving 2-6 bicycle bays with basic photovoltaic generation and no grid export. German federal tax incentives for residential solar partially offset these units.
- Commercial:Workplace parking serving employee e-bike fleets with integrated charging. Dutch corporate campuses under mobility-as-a-service programs specify these for carbon accounting compliance.
- Institutional:University and hospital campus deployments with 50-200 bay capacities and centralized energy management. Copenhagen's university district anchors volume demand in this tier.
- Public Spaces:Municipal transit nodes, train stations, and civic plazas with highest specification complexity and longest procurement cycles. EU Green Deal building-efficiency mandates concentrate investment in this category.
Public Spaces concentrate the largest project values. Commercial deployments are gaining share fastest as workplace mobility programs expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent clusters in Dutch industrial design hubs and German precision manufacturing regions anchor solar bicycle shed development. Copenhagen's metropolitan planning office employs dedicated cycling infrastructure architects. North Rhine-Westphalia technical universities feed specialized structural-solar engineering programs.
Germany
Municipal transit authorities in Hamburg and Munich are piloting perovskite-silicon tandem photovoltaic modules at transit nodes. The National Cycling Plan's 2025-2030 funding window earmarks federal transport budget for covered parking infrastructure. Berlin-Brandenburg procurement offices are compressing vendor selection cycles to meet application deadlines.
Netherlands
Dutch urban cores concentrate demand for integrated DC fast-charging ports at every transit node. The EU Green Deal's building-efficiency mandates accelerate photovoltaic-integrated shelter specifications nationwide. Eindhoven Region fabricators specialize in polycarbonate-roof passive ventilation systems for mid-tier institutional deployments.
Denmark
Copenhagen's metropolitan cycle network specifies solar shelters at 500-meter intervals across 300 kilometers of protected routes. The Danish capital's transit authority bundles solar, storage, and charging specifications into unified performance-based tenders. Jutland and Funen provincial municipalities are issuing bundled shelter tenders with 50-200 unit minimums.
United Kingdom
Workplace mobility programs in London and Southeast commercial campuses are specifying employee e-bike fleet charging infrastructure. The country's national cycling infrastructure subsidies partially offset residential solar bicycle shed installations. Midlands manufacturing regions supply galvanized structural tubing for inland deployments where corrosion exposure is limited.
Solar Bicycle Shed Market Competitive Landscape
Top-tier vendors anchor integrated-system contracts with electrical engineering capabilities, while commodity shelter suppliers face displacement from unified performance-based tenders. The vendor base stratifies across three tiers: photovoltaic module manufacturers with module-scale manufacturing, charging-integrated design specialists, and polycarbonate-roof structural fabricators. Strategic moves concentrate on backward integration into battery-inverter combinations and geographic expansion into Danish provincial transit nodes.
Within the module-manufacturing tier, Canadian Solar occupies a position exemplifying scale-driven public-space installations. Among charging-integrated specialists, Swiftmile represents the archetype of transit-hub deployment dominance in Copenhagen and Amsterdam. HBT Energy sits within the mid-tier institutional segment, anchoring polycarbonate-roof structure supply for Dutch provincial markets.
| Leading Market Players |
|---|
| InfraMarks |
| Azure Bikes |
| HBT Energy |
| Sun-moon Power |
| Swiftmile |
| Canadian Solar |
| SolarEdge Technologies |
| SMA Solar Technology |
| LG Electronics |
| Others |
Pricing and Supply Chain Analysis
Structural-solar engineering talent clusters in North Rhine-Westphalia technical universities feed specialized design competency into German and Dutch fabrication centers. Labor-cost differentials between these engineering hubs and commodity shelter suppliers in Eastern European manufacturing zones widen pricing-tier spreads across integrated-system and standalone product categories.
Pricing Analysis
The bundled-versus-unbundled service split separates integrated-system vendors commanding premium positioning from commodity standalone suppliers competing on unit economics. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade for EU Green Deal compliance and volume scale of municipal tenders. Cost compression in the mid-tier polycarbonate segment is intensifying because REACH polymer substitution cycles extend qualification timelines. Public-space municipal buyers exhibit highest price sensitivity due to compressed procurement schedules, while institutional campus purchasers prioritize performance specifications over unit cost.
Supply Chain Analysis
Reverse-logistics flows for second-life EV battery repurposing are creating circular supply pathways for storage-integrated shelter configurations. Primary aluminum ingot supplies draw from Norwegian smelters and Canadian hydroelectric production, with microinverter hardware sourcing concentrated among East Asian component houses. Single-source vulnerability in DC-to-AC conversion hardware extends lead times for German municipal rollouts. Distribution runs through specialized civil-solar engineering consultancies that bridge photovoltaic electrical certification with structural fabrication procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where Copenhagen's unified performance-based tendering signals demand-shift toward premium integrated-system specifications over commodity standalone alternatives.
For Market Incumbents: Lock in electrical engineering capabilities through backward integration into battery-inverter combinations before REACH compliance deadlines disqualify legacy suppliers. Secure aluminum extrusion supply agreements with Norwegian primary producers to hedge LME price volatility threatening mid-tier fabrication margins. Consolidate vendor relationships around single-source integrated-system contracts to match Copenhagen's bundled tender specifications. For New Entrants and Emerging Players: Launch via Danish provincial transit node tenders in Jutland and Funen where bundled shelter specifications with 50-200 unit minimums lack incumbent saturation. Target secondary cities outside Copenhagen's metropolitan cycle network where covered cycling infrastructure remains underpenetrated. Pursue polycarbonate-roof passive ventilation specialization to capture demand displaced by F-Gas Regulation phase-downs. For Investors and Strategic Acquirers: Municipal infrastructure funds are the most active acquirer in this space, consolidating fragmented shelter fabricators into platform-scale integrated-system vendors. Five-to-ten year viability hinges on qualification pathway acceleration for photovoltaic-grid interconnection capabilities. Monitor German National Cycling Plan funding window closures as inflection indicator for procurement velocity compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery-Inverter Systems | Captures margin pools from second-life EV battery repurposing for overnight e-bike charging. |
| Polycarbonate Glazing Material Substitution Program | Ensures REACH compliance eligibility for ECHA's fluorinated polymer phase-out timeline. |
| Perovskite-Silicon Tandem Module Pilot Deployment | Hamburg and Munich transit authorities validate 22% efficiency ratings compressing shelter footprints. |
| Danish Provincial Transit Node Geographic Expansion | Jutland and Funen municipalities issue bundled tenders with volume minimums lacking incumbent presence. |
| Unified Performance-Based Tender Capability Buildout | Copenhagen's collapsed solar-storage-charging specifications displace standalone shelter suppliers. |
Research Methodology
Direct dialogue with municipal procurement officers, structural-solar engineering consultants, polycarbonate glazing fabricators, and photovoltaic module manufacturers anchored qualitative grounding. Secondary validation drew from EU Green Deal implementation documents, ECHA REACH restriction timelines, German National Cycling Plan funding disclosures, and Danish municipal tender databases. Bottom-up project pipeline analysis triangulated against top-down regulatory spending commitments.
Bottom-up modeling tracked individual shelter deployments across Copenhagen's 300-kilometer cycle network, German federal transport budget allocations, and Dutch provincial transit node specifications. Segmentation dimensions spanned product type complexity tiers, material corrosion-resistance grades, installation permanence categories, and end-user procurement sophistication levels. CAGRs derived from volume-weighted aggregation of municipality-level rollout schedules across the projection horizon. Industry-specific forecast inputs incorporated perovskite-silicon tandem efficiency trajectories and second-life EV battery cost curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under aluminum price volatility spikes or microinverter supply disruptions. Forecasts reflect documented assumptions on EU Green Deal building-efficiency mandate enforcement timelines and national cycling infrastructure subsidy synchronization. Practitioners should monitor German certification body queue lengths for photovoltaic electrical approval and ECHA polymer restriction enforcement dates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Indonesia Renewable Energy CAPEX Market
Renewable Energy
Venezuela Renewable Energy Market
Renewable Energy
Renewable Naphtha Market
Renewable Energy
Tidal Energy Generation Systems Market
Renewable Energy
Blockchain in Renewable Energy Market
Renewable Energy
Australia Renewable Energy Market
Renewable Energy
Solar Boat Market
Renewable Energy
Italy Renewable Energy Market
Renewable Energy
Wind Turbine Automation Market
Renewable Energy
Global Artificial Photosynthesis Market
Renewable Energy
Kazakhstan Renewable Energy Market
Renewable Energy
Renewable Energy MRO Market
Renewable Energy
Mexico Renewable Energy Market
Renewable Energy
Uzbekistan Renewable Energy Market
Renewable Energy
Solar Tracker Market
Renewable Energy
United States Renewable Energy Market