
 Zigbee System-On-Chip Market | 2026-2036
Zigbee System-On-Chip Market Size, Share, and Industry Trends Forecast 2026-2036
Zigbee System-On-Chip Market Analytics
Multi-source procurement for RF front-end components is hardening as OEMs reduce dependence on single foundry relationships. Texas Instruments leverages its captive 300mm analog fab network to sustain die supply commitments for Zigbee SoC customers. NXP Semiconductors anchors European automotive-qualified Zigbee portfolios with AEC-Q100 process discipline. Silicon Laboratories specializes in sub-GHz coexistence architectures that differentiate its portfolio in congested smart home spectrum environments.
A Zigbee System-On-Chip integrates an IEEE 802.15.4-compliant radio transceiver, ARM Cortex-M class application processor, and embedded flash memory in a single die package, typically operating at 2.4 GHz or sub-GHz bands with receive sensitivities below -100 dBm for reliable mesh networking in building automation and energy management systems. Standard Zigbee variants occupy the mature volume tier in lighting control applications where cost optimization dominates procurement criteria, while Zigbee Green Power segments capture expanding margin pools in battery-less sensor deployments for energy harvesting architectures. Wireless Communication technology leads unit shipments across smart home end users, though Mesh Networking functionality generates premium pricing in industrial automation deployments requiring self-healing topology resilience.
FCC Part 15 rules in the United States govern unlicensed 2.4 GHz emissions and shape transmit power limits that directly constrain SoC amplifier design margins, while CE marking under the EU Radio Equipment Directive mandates harmonized spectrum access protocols for European market entry. China's MIIT issues type approval certificates through its radio transmission equipment certification system, creating a three-regulator compliance burden for vendors pursuing cross-border volume. Stakeholders must monitor evolving cybersecurity labeling requirements from the FCC and EU agencies, as firmware attestation mandates will soon filter procurement specifications and disqualify legacy silicon lacking secure boot capabilities.
Market Dynamics
Smart home device manufacturers are consolidating RF module procurement around single-die Zigbee SoC architectures to reduce bill-of-material complexity and accelerate certification cycles for thermostat and lighting ecosystems.
Growth Catalysts
- EU Cybersecurity Certification:The EU Radio Equipment Directive's emerging firmware attestation mandates are filtering procurement specifications toward secure-boot-capable silicon, disqualifying legacy architectures and creating replacement demand.
- Sub-GHz Spectrum Allocation:China's MIIT spectrum allocations for sub-GHz IoT bands support domestic smart city deployments, concentrating infrastructure procurement around MIIT-certified module suppliers.
- Energy Harvesting Architectures:Zigbee Green Power segments capture expanding margin pools in battery-less sensor deployments for industrial energy management systems requiring ultra-low standby power.
Market Restraints
- Foundry Concentration Risk:Multi-source procurement for RF front-end components remains constrained by limited 300mm analog fab capacity, hardening dependence on captive semiconductor manufacturing networks.
- Amplifier Design Margins:FCC Part 15 transmit power limits constrain SoC power amplifier efficiency, compressing thermal budgets in compact lighting control modules.
- Thread Protocol Substitution:The Thread networking protocol's IP-native architecture threatens Zigbee's position in premium smart home hubs where interoperability with Matter-certified devices dominates specification sheets.
Strategic Opportunities
- AEC-Q100 Automotive Qualification:European automotive-qualified Zigbee portfolios for in-cabin wireless sensor networks remain underpenetrated, with OEMs specifying mesh connectivity for battery management systems.
- CE Marking Harmonization:The EU Radio Equipment Directive's spectrum access protocol harmonization creates regulatory tailwinds for vendors with pre-certified module platforms.
- Sub-GHz Coexistence:Silicon Laboratories' specialized coexistence architectures demonstrate technical differentiation potential in congested 2.4 GHz environments, opening premium positioning in multi-protocol residential gateways.
Industry Challenges
- Secure Boot Integration Complexity:Firmware attestation mandates from FCC and EU agencies require cryptographic hardware blocks that legacy Zigbee silicon lacks, forcing costly die respins for existing product lines.
- Three-Regulator Certification Burden:Cross-border volume requires simultaneous FCC Part 15, EU CE marking, and MIIT type approval, extending time-to-market by 8-14 months for new SoC platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zigbee System-On-Chip Market |
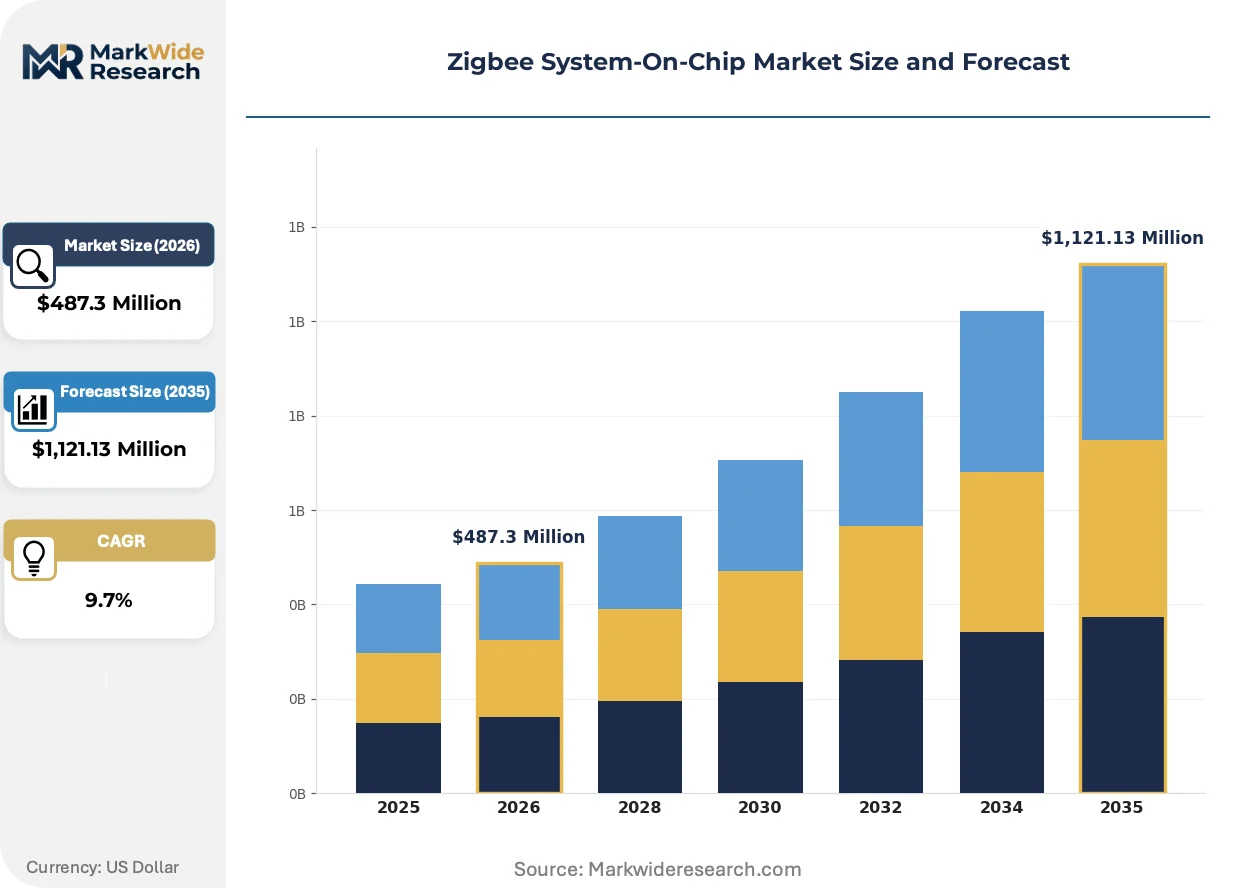
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,121.13 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Zigbee, Enhanced Zigbee, Zigbee PRO, Zigbee Green Power End User: Smart Home, Industrial Automation, Healthcare, Agricultural Monitoring Technology: Wireless Communication, Low-Power RF, Mesh Networking, Device Interoperability Application: Lighting Control, Energy Management, Asset Tracking, Environmental Monitoring |
| Companies Covered | Texas Instruments, NXP Semiconductors, Silicon Laboratories, Microchip Technology, STMicroelectronics, Digi International, Qualcomm, Intel Corporation, Renesas Electronics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zigbee System-On-Chip Market Evolving Landscape
Mesh networking functionality is commanding premium pricing in industrial automation while standard Zigbee variants face commoditization pressure in mature lighting control applications.
Ultra-wideband ranging capability is converging with Zigbee radio cores in single-package solutions. Smart lock manufacturers in North America are adopting these converged architectures for precise indoor positioning. This integration is converging with demand for single-chip solutions that reduce RF subsystem footprint by 40% in compact door hardware.
The EU Radio Equipment Directive's cybersecurity certification framework mandates hardware-backed secure boot for all RF modules entering European markets. Industrial automation OEMs are redesigning sensor nodes to incorporate embedded cryptographic engines. Process control deployments in Germany and France face the steepest compliance timelines, with certification backlogs extending hardware refresh cycles.
Smart home hub procurement now prioritizes multi-protocol silicon supporting concurrent Zigbee, Thread, and Bluetooth Low Energy stacks. Retail channel buyers in the United States are specifying interoperable modules to simplify inventory management. This consolidation is most visible in thermostat and lighting controller categories where single-SKU flexibility reduces distributor carrying costs.
Zigbee System-On-Chip Market Segmentation
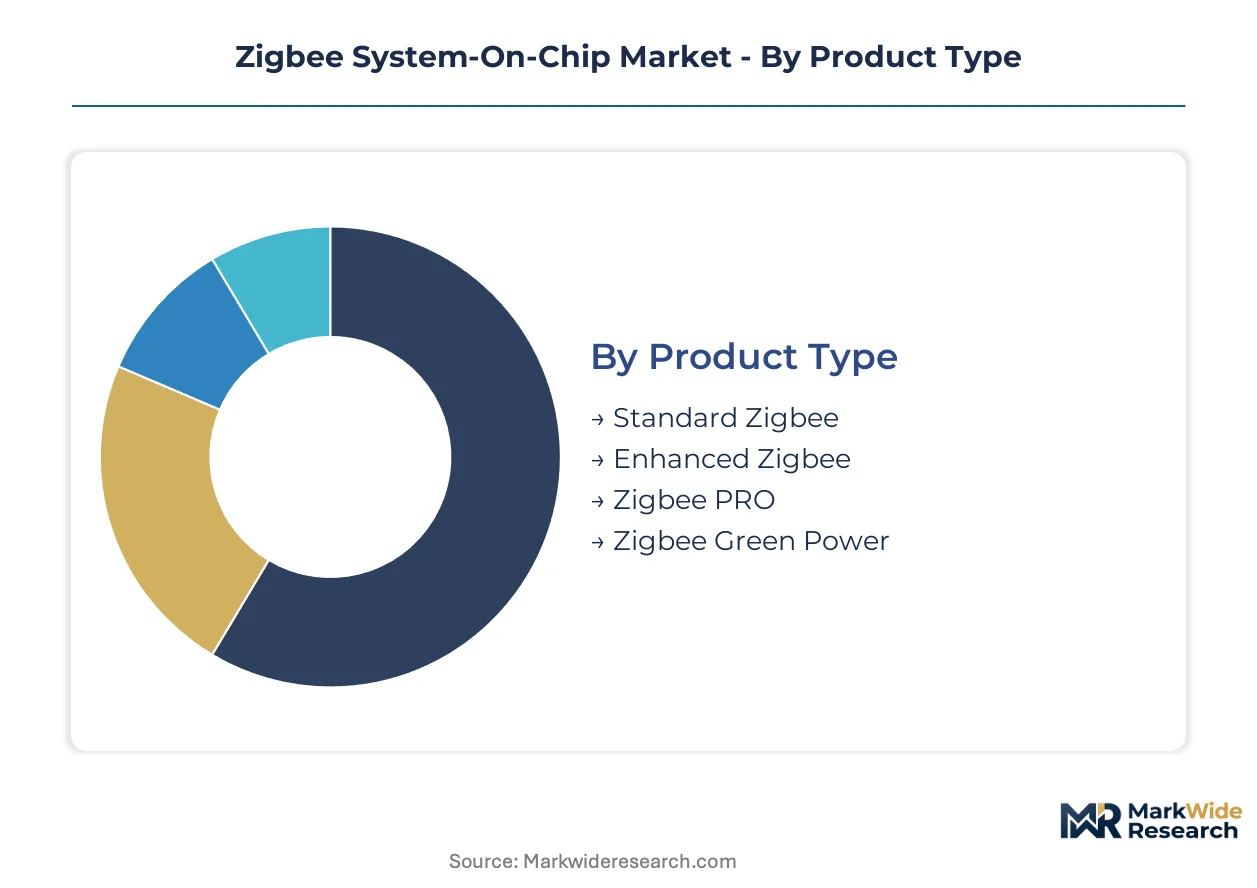
Zigbee SoC procurement patterns diverge sharply across product tiers and end-use applications. Supply chain configuration for each segment dictates foundry allocation, certification burden, and margin structure.
Product Type:
RF front-end component sourcing concentrates differently across Zigbee variants, with captive fab access determining which suppliers capture volume in each tier.
- Standard Zigbee:IEEE 802.15.4-compliant transceiver cores with basic mesh networking stack. Lighting control OEMs in China concentrate procurement here, prioritizing die cost over feature depth for high-volume fixture deployments.
- Enhanced Zigbee:Upgraded protocol stacks with improved security primitives and extended range amplifiers. Smart home hub manufacturers in the United States specify these for thermostat ecosystems requiring reliable wall penetration.
- Zigbee PRO:Full-featured mesh networking with centralized commissioning and advanced routing tables. Industrial automation deployments in Germany leverage PRO-certified modules for factory floor sensor grids.
- Zigbee Green Power:Ultra-low standby current architectures enabling battery-less energy harvesting designs. Sub-GHz variants gain traction in French building automation for maintenance-free environmental sensors.
Standard Zigbee absorbs the bulk of installed capacity; Zigbee Green Power is expanding most quickly.
End User:
Customer procurement specifications create divergent margin pools, with certification requirements and volume scale determining supplier profitability.
- Smart Home:Thermostat, lighting, and security device OEMs dominate unit demand. Retail channel consolidation in the United States pushes suppliers toward multi-protocol silicon supporting concurrent Zigbee and Thread stacks.
- Industrial Automation:Process control and predictive maintenance applications command premium pricing. German automotive suppliers specify AEC-Q100 qualified variants for battery management system connectivity.
- Healthcare:Patient monitoring and medical asset tracking with stringent EMC compliance. FDA device classification requirements extend certification timelines for RF module vendors.
- Agricultural Monitoring:Soil moisture and livestock tracking sensors operating in remote coverage areas. Sub-GHz spectrum allocations from China's MIIT support domestic smart agriculture deployments.
Smart Home generates the highest absolute volume; Industrial Automation captures the steepest expansion trajectory.
Technology:
Technical differentiation in the RF layer determines competitive positioning, with coexistence architecture and power efficiency serving as primary selection criteria.
- Wireless Communication:Core 2.4 GHz and sub-GHz transceiver implementations with O-QPSK modulation. FCC Part 15 transmit power limits constrain amplifier design margins for compact lighting modules.
- Low-Power RF:Sub-milliamp receive modes and aggressive duty cycling for battery-operated endpoints. Energy harvesting sensor vendors prioritize these architectures for maintenance-free deployments.
- Mesh Networking:Self-healing topology protocols with multi-hop routing and network-wide commissioning. Industrial automation OEMs pay premium pricing for resilience in factory environments.
- Device Interoperability:Multi-protocol stacks supporting concurrent Zigbee, Thread, and Bluetooth Low Energy operation. Smart home hub procurement increasingly mandates this flexibility to simplify inventory management.
Wireless Communication commands the largest installed base; Mesh Networking is climbing the fastest.
Application:
End-use functional requirements shape die specification, with thermal constraints and reliability targets varying substantially across deployment contexts.
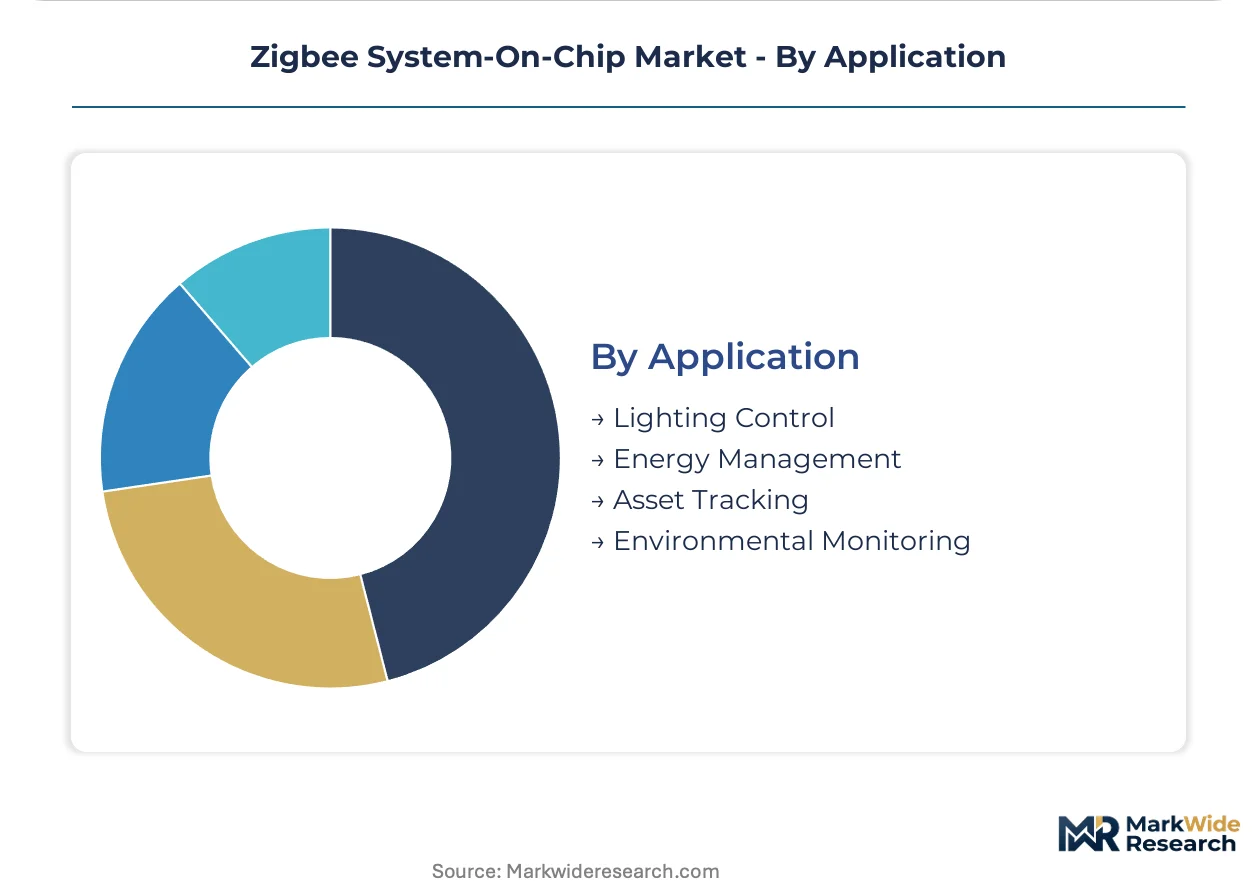
- Lighting Control:Dimmable fixture and smart switch modules with tight cost targets. Chinese fixture manufacturers drive commoditization pressure through consolidated procurement.
- Energy Management:Smart meter and load control applications with utility-grade reliability requirements. European Union cybersecurity certification mandates filter procurement toward secure-boot-capable silicon.
- Asset Tracking:Real-time location systems and inventory management with precise ranging requirements. Converged ultra-wideband plus Zigbee architectures gain adoption in North American smart lock hardware.
- Environmental Monitoring:Temperature, humidity, and air quality sensors with extended battery life. Zigbee Green Power variants capture margin pools in battery-less industrial deployments.
Lighting Control holds the majority of shipped units; Asset Tracking is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon foundry capacity in Taiwan and South Korea anchors the upstream supply base for Zigbee SoC fabrication, while module assembly and certification activities concentrate in China, Germany, and the United States.
China
MIIT spectrum allocations for sub-GHz IoT bands drive smart city infrastructure procurement across Shenzhen and Shanghai industrial clusters. Domestic module vendors secure type approval certificates through China's radio transmission equipment certification system. Yangtze River Delta manufacturing hubs produce certified Zigbee Green Power variants for agricultural monitoring deployments.
United States
FCC Part 15 rules govern unlicensed 2.4 GHz emissions and constrain power amplifier design margins for compact lighting modules. Smart home hub manufacturers in Silicon Valley and Austin specify multi-protocol silicon supporting concurrent Zigbee and Thread stacks. Retail channel consolidation pushes suppliers toward interoperable module platforms.
Germany
EU Radio Equipment Directive cybersecurity certification mandates filter procurement toward secure-boot-capable silicon for industrial automation. Bavarian automotive suppliers specify AEC-Q100 qualified variants for battery management system connectivity. Factory floor sensor grids in Baden-Württemberg leverage Zigbee PRO-certified modules with centralized commissioning.
Japan
METI industrial IoT promotion programs accelerate building automation sensor deployments in Tokyo and Osaka metropolitan areas. Sub-GHz coexistence architectures gain traction for congested spectrum environments. Nagoya-area electronics clusters integrate ultra-wideband ranging with Zigbee radio cores for precise indoor positioning applications.
France
ANSM and CNIL data protection frameworks intersect with RF module cybersecurity requirements for healthcare asset tracking. Building automation OEMs in Île-de-France redesign sensor nodes to incorporate embedded cryptographic engines. Environmental sensor deployments in Auvergne-Rhône-Alpes adopt Zigbee Green Power variants for maintenance-free energy harvesting architectures.
Zigbee System-On-Chip Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors secure captive foundry access and pre-certified module platforms. The vendor base clusters around three tiers: integrated semiconductor conglomerates with captive analog fab networks, fabless RF specialists with sub-GHz coexistence IP, and module integrators with regulatory certification expertise. Competitive positioning hinges on M&A activity for RF front-end IP and geographic expansion through local certification partnerships.
Among US-based semiconductor suppliers, Texas Instruments and Silicon Laboratories exemplify divergent strategic archetypes. Texas Instruments occupies a position anchored by captive 300mm analog fab capacity. Silicon Laboratories represents the fabless specialization model with technical differentiation in congested spectrum coexistence. NXP Semiconductors, headquartered in the Netherlands, anchors European automotive-qualified portfolios with AEC-Q100 process discipline.
| Leading Market Players |
|---|
| Texas Instruments |
| NXP Semiconductors |
| Silicon Laboratories |
| Microchip Technology |
| STMicroelectronics |
| Digi International |
| Qualcomm |
| Intel Corporation |
| Renesas Electronics Corporation |
| Others |
Value Network & Pricing Analysis
300mm analog wafer costs cascade through Zigbee SoC pricing tiers, with captive fab access separating premium AEC-Q100 automotive modules from commoditized lighting control silicon sourced through merchant foundries in Taiwan and South Korea.
Pricing Analysis
Pre-certified module bundles with FCC Part 15 and CE marking documentation command 15-25% premiums over bare-die quotations. Pricing stratifies across secure-boot-enabled automotive tiers, standard industrial grades, and cost-optimized lighting control variants. Cost compression in the standard tier intensifies because Chinese fixture OEMs consolidate procurement volumes. Smart home hub manufacturers exhibit lowest price sensitivity, prioritizing multi-protocol interoperability over per-unit die costs.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale smart home device manufacturer demand, while distribution partners serve mid-tier industrial automation accounts across Germany and France. Foundry capacity concentrates in Taiwan, South Korea, and the United States, with back-end assembly anchored in China's Yangtze River Delta. Silicon wafer, RF front-end IP, and embedded flash memory draw from concentrated upstream suppliers. Single-source vulnerability in 300mm analog fab allocation exposes procurement timelines to capacity constraints. Distribution runs through module integrators with MIIT, FCC, and EU regulatory certification expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Zigbee System-On-Chip market sits in a protocol-transition phase, with Thread and Matter-certified multi-protocol silicon displacing single-stack legacy architectures in premium smart home hub procurement.
For Market Incumbents: To counter Thread protocol substitution in residential gateway sockets, Texas Instruments and NXP Semiconductors should accelerate backward integration into sub-GHz coexistence IP while expanding AEC-Q100-qualified die capacity for automotive battery management system connectivity. Secure boot cryptographic hardware blocks must become standard across all product tiers before EU firmware attestation mandates harden. For New Entrants and Emerging Players: Enter via unpenetrated French and German industrial automation segments where Zigbee PRO-certified modules with centralized commissioning face limited domestic competition. Agricultural monitoring in China's MIIT-allocated sub-GHz spectrum offers the most penetrable geography. License pre-certified module platforms from established regulatory partners to compress 8-14 month certification timelines. For Investors and Strategic Acquirers: MIIT type approval certificate backlogs extending hardware refresh cycles is the leading indicator that certification expertise carries scarcity value in this market. Over the medium-term horizon, acquisition targets should emphasize fabless RF specialists with sub-GHz coexistence architectures and established three-regulator approval track records. Watch for FCC cybersecurity labeling rule finalization as the signal for secure-boot-capable silicon replacement demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Protocol Silicon Integration | Concurrent Zigbee, Thread, and Bluetooth Low Energy stacks satisfy Matter-certified smart home hub procurement mandates from US retail channel buyers. |
| Secure Boot Hardware Block Deployment | Embedded cryptographic engines enable EU Radio Equipment Directive firmware attestation compliance for industrial automation sensor nodes in Germany. |
| Sub-GHz Coexistence Architecture Development | Specialized RF layer IP differentiates offerings in congested spectrum environments for Japanese building automation deployments. |
| AEC-Q100 Automotive Qualification | Process discipline certification opens Bavarian battery management system connectivity specifications from European OEMs. |
| Three-Regulator Certification Platform | Simultaneous FCC Part 15, CE marking, and MIIT approval capability accelerates time-to-market for cross-border volume customers. |
Research Methodology
Multi-period observation of MIIT type approval certificate issuance volumes, FCC equipment authorization filings, and EU notified body certification timelines anchored the trend analysis, supplemented by interviews with smart home device procurement directors, industrial automation platform engineers, RF module regulatory affairs managers, and semiconductor foundry planning officers. Secondary validation drew from SEC 10-K semiconductor segment disclosures, MIIT radio transmission equipment certification system records, and EU Radio Equipment Directive implementation guidance documents. Bottom-up die shipment aggregation and top-down OEM procurement spend estimates were triangulated to cross-check volume and value outputs.
Input-output matrices mapped Zigbee SoC unit demand across product type, end user, technology, and application dimensions over the projection horizon. CAGRs were derived from segment-level growth rate convergence analysis. Forecast inputs included foundry capacity allocation announcements, regulatory mandate implementation schedules, and OEM platform standardization roadmaps for mesh networking protocol selection.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden Thread protocol acceleration or MIIT spectrum reallocation scenarios. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Chips & Hardware
Wi-Fi Adapter Card Market
Communication Chips & Hardware
Jobsite Radios Market
Communication Chips & Hardware
Bluetooth Low Energy (BLE) Module Market
Communication Chips & Hardware
Nano GPS Chip Market
Communication Chips & Hardware
Bluetooth Audio Soc Chips Market
Communication Chips & Hardware
Ethernet PHY Chip Market
Communication Chips & Hardware
Global PCI Express Serial Communication Card Market
Communication Chips & Hardware
Power Line Communication System-On-Chip Market
Communication Chips & Hardware
Optical Communications Market
Communication Chips & Hardware
Zigbee Market
Communication Chips & Hardware
GNSS Chip Market
Communication Chips & Hardware
Global Hybrid Fiber Coaxial Market
Communication Chips & Hardware
VR Device Chips Market
Communication Chips & Hardware
Global Narrowband IoT (NB IoT) Chipset Market
Communication Chips & Hardware
Global Wireless Gigabit Market
Communication Chips & Hardware
Global Network Processing Unit (NPU) Market