
 Jobsite Radios Market | 2026-2036
Jobsite Radios Market Size, Share, and Industry Trends Forecast 2026-2036
Jobsite Radios Market Insights
Market Context
The gap between premium professional-grade jobsite radios and commodity consumer alternatives is consolidating around battery ecosystem lock-in and MIL-STD-810G durability ratings. DeWalt leverages its 20V Max battery platform to anchor replacement demand among existing tool owners. Milwaukee Tool sustains premium positioning through M18 Fuel compatibility and Bluetooth app integration. Makita competes across voltage platforms while extending XGT branding into audio accessories.
Technical Definition and Segment Structure
Jobsite radios are ruggedized audio playback devices engineered to withstand dust ingress, water exposure, and impact shocks while delivering decibel output sufficient for noisy construction environments, typically incorporating sealed enclosures, rubberized bumpers, and compatibility with proprietary cordless battery systems. Bluetooth-enabled units command margin pools as contractors prioritize wireless streaming and hands-free calling, while battery-operated power sources dominate volume due to cord-free mobility on unfinished sites. Stationary AC-powered variants occupy a shrinking niche in permanent workshop installations.
Regulatory Environment and Outlook
OSHA noise exposure limits shape maximum volume engineering decisions, while FCC Part 15 governs Bluetooth and radio transmission compliance for all units sold in the United States. IP code certification requirements from IEC standards increasingly filter market access as European and Australian procurement specifications harden. Stakeholders must weigh ecosystem exclusivity against cross-platform charging standards as the decisive competitive variable.
Market Dynamics
Battery ecosystem lock-in is consolidating competitive positioning around proprietary cordless platforms, with construction contractors prioritizing cross-compatibility over standalone audio performance. This structural force compresses pricing power for unaffiliated manufacturers while amplifying replacement demand among existing tool owners.
Growth Catalysts
- OSHA workplace noise guidelines:Contractors in the United States face stricter enforcement of permissible exposure limits, accelerating replacement of non-compliant units with volume-capped, certified alternatives.
- Bluetooth streaming adoption:Wireless audio connectivity eliminates cord hazards on active construction sites while enabling hands-free calling integration.
- German trades union procurement standards:IG Metall-affiliated contractors mandate IP65 durability ratings, filtering out uncertified competitors from commercial bidding pools.
Market Restraints
- Lithium-ion cell cost volatility:Battery pack input costs fluctuate with cobalt and nickel spot markets, squeezing margins on cordless units.
- Single-source semiconductor dependency:Bluetooth module fabrication concentrates in Taiwan, exposing supply continuity to geopolitical friction.
- AC-powered workshop niche erosion:Stationary corded units face substitution from portable battery alternatives, shrinking addressable volume in permanent installations.
Strategic Opportunities
- Japan's aging construction workforce:Voice-activated controls and simplified interfaces address ergonomic needs among trades workers over 55.
- Australia's infrastructure stimulus:Federal procurement mandates under the National Construction Code favor certified jobsite equipment for public projects.
- 5G-enabled fleet management:Converged connectivity allows contractors to track, configure, and diagnose radio networks remotely across dispersed sites.
Industry Challenges
- IEC IP code certification timelines:Third-party testing for dust and water ingress ratings extends product launch cycles by four to six months.
- Legacy analog radio tuner integration:Maintaining AM/FM reception alongside digital streaming requires dual RF engineering expertise scarce among audio specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Jobsite Radios Market |
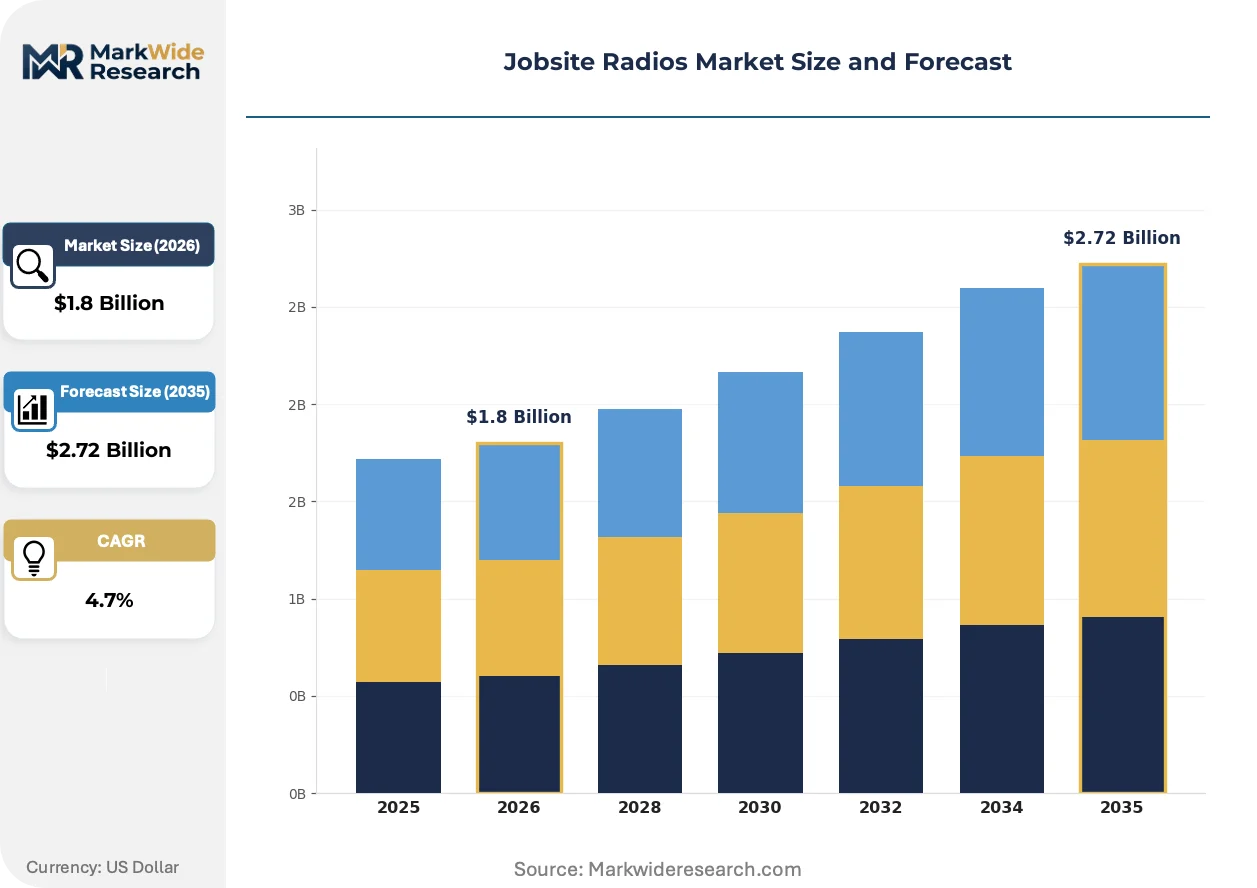
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Stationary, Bluetooth-enabled, Weather-resistant End User: Construction Workers, Electricians, Plumbers, Contractors Power Source: Battery-operated, AC-powered, Solar-powered, Hybrid Features: Durability, Waterproofing, USB Charging, Auxiliary Input |
| Companies Covered | DeWalt, Milwaukee Tool, Makita, Bosch, Ryobi, Ridgid, Sangean, Flex, Hilti, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Jobsite Radios Market Trends and Innovations
Digital connectivity standards and durability certification requirements are compressing product development cycles while elevating minimum viable specifications for market entry. Manufacturers must now engineer for simultaneous compliance across multiple regulatory jurisdictions.
Mesh networking technology is integrating distributed audio synchronization across large construction sites. General contractors managing multi-acre developments adopt these systems to eliminate dead zones without range-extending hardware. This capability is integrating formerly separate intercom and entertainment functions into unified jobsite communication platforms.
REACH substance restrictions in the European Union are phasing out specific flame retardants and plasticizers common in rubberized housing compounds. Manufacturers reformulate enclosure materials to maintain impact resistance while complying with chemical authorization lists. German industrial distributors now require full material disclosure documentation before listing new products.
Certification-driven purchasing is displacing price-first evaluation among professional trades. Contractors in the United States prioritize FCC Part 15 compliance documentation and OSHA noise exposure verification over unit cost comparisons. This behavioral shift concentrates procurement authority with safety officers rather than traditional purchasing departments.
Jobsite Radios Market Segmentation
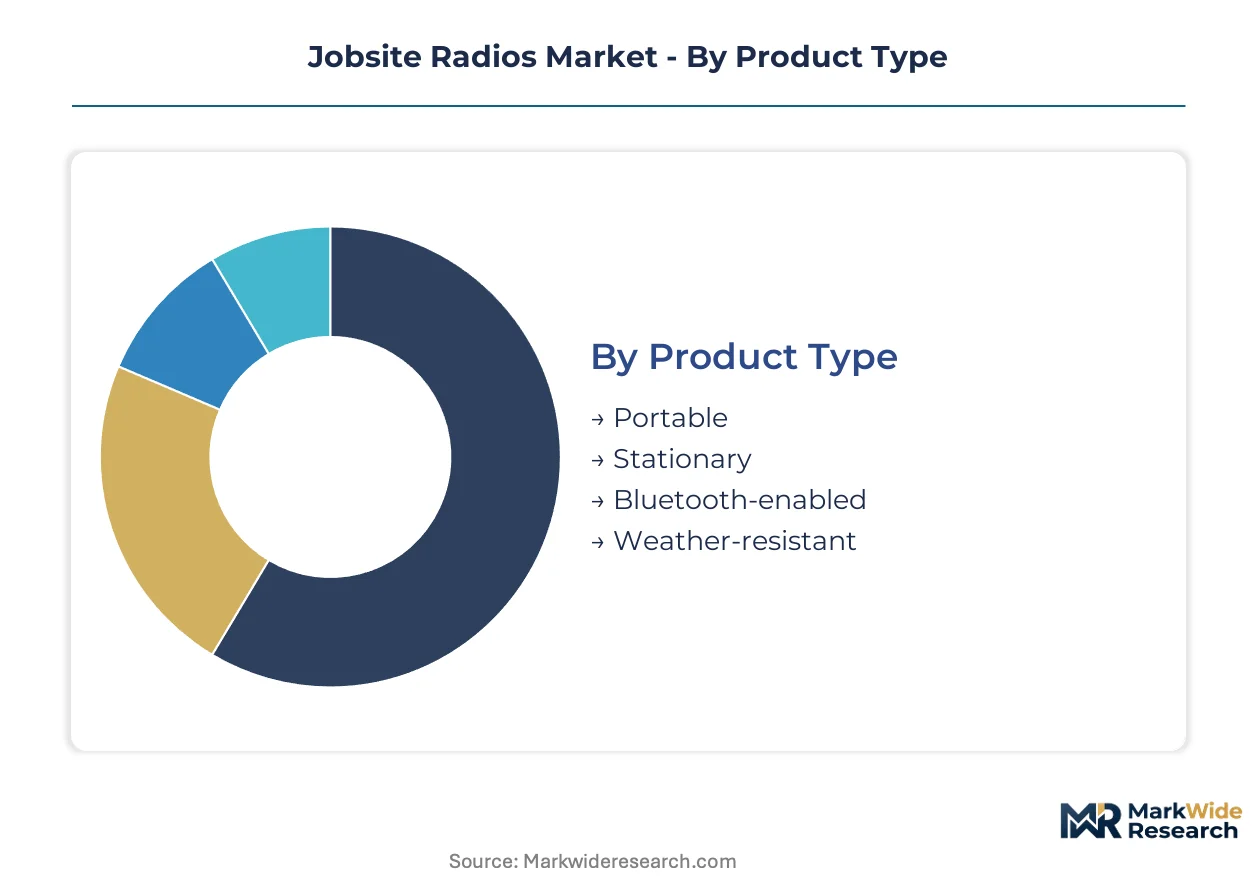
Jobsite radios serve heterogeneous work environments where power availability, mobility requirements, and trade-specific durability demands fragment purchasing decisions. Segmentation reveals how battery ecosystem compatibility and OSHA compliance certifications partition contractor procurement patterns across product configurations.
Product Type:
Contractors prioritize portability against mounting points and weather exposure when selecting form factors for active construction zones.
- Portable:Cordless units with sealed enclosures and rubberized bumpers dominate volume as electricians and plumbers move between unfinished spaces without power access. Demand concentrates in the United States where OSHA noise enforcement drives replacement of non-compliant legacy units with volume-capped certified alternatives.
- Bluetooth-enabled:Wireless streaming modules eliminate cord trip hazards while enabling hands-free calling integration for general contractors managing dispersed crews. German trades union procurement standards mandate IP65 durability ratings, filtering uncertified competitors from commercial bidding pools.
- Stationary:AC-powered workshop installations occupy shrinking niche as battery alternatives substitute permanent corded setups.
- Weather-resistant:Enhanced sealing maintains audio output in rain-exposed exterior applications.
Portable units lead on scale; Bluetooth-enabled configurations lead on momentum.
End User:
Trade-specific tool ownership patterns determine battery platform compatibility and replacement cycle timing.
- Contractors:General contractors managing multi-acre developments adopt mesh networking systems for distributed audio synchronization without range-extending hardware.
- Construction Workers:Framing and concrete crews prioritize decibel output sufficient for noisy environments with impact-resistant housing.
- Electricians:Existing 20V Max and M18 battery platform ownership drives cross-compatible radio procurement to minimize charger redundancy.
- Plumbers:Crawl space and basement work demands compact form factors with extended battery runtime.
Contractors concentrate procurement authority; electricians drive replacement frequency.
Power Source:
Site electrification status and mobility requirements segment power architecture preferences across construction phases.
- Battery-operated:Proprietary cordless platforms anchor replacement demand among existing tool owners. Lithium-ion cell cost volatility squeezes margins as cobalt and nickel spot markets fluctuate.
- Hybrid:Dual AC/battery flexibility serves workshop-to-site transitions for independent tradespeople.
- AC-powered:Stationary workshop installations face substitution from portable alternatives.
- Solar-powered:Off-grid remote site applications remain marginal due to panel durability concerns.
Battery-operated systems capture volume leadership; hybrid configurations expand most quickly.
Features:
Certification documentation and connectivity specifications displace price-first evaluation among professional procurement.
- Durability:MIL-STD-810G ratings and IP code certifications compress product development cycles by four to six months for third-party testing.
- Waterproofing:IEC IP65 ratings filter market access as European and Australian procurement specifications harden.
- USB Charging:Device power outlets extend jobsite utility beyond audio playback.
- Auxiliary Input:Legacy wired connectivity persists for contractors with non-Bluetooth audio sources.
Durability certification leads on scale; waterproofing specifications lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled trades workers in the United States, Germany, and Japan concentrate replacement demand as battery platform ownership and union procurement standards reshape purchasing authority across developed construction markets.
United States
OSHA noise exposure enforcement drives replacement of non-compliant legacy radios with volume-capped certified units. FCC Part 15 governs Bluetooth transmission compliance for all units sold nationally. Texas and Florida construction corridors anchor procurement volume as residential and infrastructure spending accelerates equipment turnover.
Germany
IG Metall-affiliated contractors mandate IP65 durability ratings that filter uncertified competitors from commercial bidding pools. REACH substance restrictions phase out specific flame retardants in rubberized housing compounds. Industrial distributors in North Rhine-Westphalia now require full material disclosure documentation before listing new products.
Japan
An aging construction workforce over 55 prioritizes voice-activated controls and simplified interfaces for ergonomic accessibility. METI industrial standards shape durability certification requirements for professional-grade equipment. Osaka-based contractors drive replacement frequency through existing XGT and 18V battery platform ownership.
Australia
Federal procurement mandates under the National Construction Code favor certified jobsite equipment for public infrastructure projects. IEC IP code certification requirements harden market access specifications. Queensland and New South Wales infrastructure stimulus programs concentrate demand for weather-resistant portable units.
United Kingdom
Construction safety officers displace traditional purchasing departments in procurement authority for certified equipment. CE marking and UKCA post-Brexit compliance documentation filter market entry for imported units. London and Southeast England commercial development clusters prioritize Bluetooth-enabled configurations for multi-site crew coordination.
Jobsite Radios Market Competitive Landscape
Top-tier vendors anchor the premium professional-grade segment, while mid-tier specialists and unaffiliated audio manufacturers compete on price without battery ecosystem integration. The vendor base stratifies around proprietary cordless platform compatibility, with consolidated positioning among construction tool manufacturers and fragmented alternatives from consumer electronics entrants. Two strategic archetypes dominate: ecosystem-locked power tool brands and cross-platform durability specialists. Competitive moves concentrate on M&A for battery technology access and portfolio diversification into converged jobsite communication platforms.
Among power tool manufacturers with integrated audio divisions, DeWalt, Milwaukee Tool, and Makita exemplify the ecosystem-locked archetype. DeWalt leverages its 20V Max battery platform to anchor replacement demand among existing tool owners. Milwaukee Tool occupies a premium positioning through M18 Fuel compatibility and connected tool app integration. Makita competes across multiple voltage platforms while extending XGT branding into audio accessories. These three represent the decisive competitive dynamic where cross-compatibility trumps standalone audio performance in contractor purchasing decisions.
| Leading Market Players |
|---|
| DeWalt |
| Milwaukee Tool |
| Makita |
| Bosch |
| Ryobi |
| Ridgid |
| Sangean |
| Flex |
| Hilti |
| Others |
Pricing and Supply Chain Analysis
Cobalt and nickel spot market volatility cascades through lithium-ion battery pack costs into three distinct pricing tiers for jobsite radios, compressing margins on cordless units while amplifying premium capture for ecosystem-locked manufacturers with captive cell supply.
Pricing Analysis
Battery ecosystem bundling versus standalone unbundled sales splits the market into divergent pricing models. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and battery platform exclusivity as primary differentiation drivers. Cost compression in economy tiers is intensifying because unaffiliated manufacturers lack volume scale to absorb cell price swings. Independent tradespeople exhibit highest price sensitivity, while general contractors managing fleet procurement prioritize cross-compatibility over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan for Bluetooth module fabrication, exposing continuity to geopolitical friction. Manufacturing concentrates in China, South Korea, and Japan for lithium-ion cells, speaker drivers, and RF components. The supply chain draws from cobalt mines in the Democratic Republic of Congo, nickel processing in Indonesia, and rare earth magnet production in China. Tariff exposure on Chinese electronics imports threatens margin stability. Distribution runs through industrial distributors, big-box retailers, and direct-to-contractor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The jobsite radios market represents a late-cycle quality story where certification-driven purchasing displaces price-first evaluation, with contractors prioritizing OSHA compliance documentation and IP65 ratings over cost comparisons.
For Market Incumbents: Acquire battery cell manufacturing capacity or secure long-term offtake agreements to hedge cobalt and nickel price exposure. Deepen backward integration into semiconductor sourcing to reduce Taiwan dependency. Fortify certification investment pipelines to compress IEC testing timelines by two months. Channel control through exclusive distributor relationships defends against unaffiliated audio entrants. For New Entrants and Emerging Players: The mid-tier price gap between DeWalt-Milwaukee premium positioning and commodity alternatives offers white-space opportunity. Target hybrid power source configurations for independent tradespeople transitioning between workshop and site work. Pursue cross-platform battery adapter development to bypass ecosystem lock-in. Go-to-market leverage through specialty electrical distributors bypasses big-box saturation. For Investors and Strategic Acquirers: Asymmetric upside sits with cross-platform durability specialists holding MIL-STD-810G certification capabilities without proprietary battery baggage. Five-to-ten year viability hinges on convergence into integrated jobsite communication platforms beyond standalone audio. Monitor mesh networking patent filings as inflection indicator for platform consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Platform Integration | Locks replacement demand among existing cordless tool owners through charger compatibility. |
| IP65 Certification Investment | Filters uncertified competitors from German IG Metall and Australian NCC procurement pools. |
| Mesh Networking Development | Converges audio and intercom functions for multi-acre construction site coordination. |
| REACH-Compliant Material Reformulation | Maintains German distributor access as flame retardant restrictions phase in. |
| Voice-Activated Interface Design | Captures Japan's aging workforce ergonomic requirements for simplified controls. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with procurement managers at general contracting firms, safety officers at unionized construction companies, product managers at power tool manufacturers, and category buyers at industrial distributors with secondary validation against OSHA enforcement databases, FCC Part 15 filings, IEC certification registries, and customs import records. Bottom-up unit shipment estimates triangulated against top-down construction spending correlations.
Comparable-period anchoring linked projection models to historical replacement cycle patterns across cordless tool platform adoptions. Segmentation dimensions spanned power source architecture, durability certification tier, Bluetooth connectivity integration, and regional regulatory cluster. CAGRs derived from logistic diffusion curves fitted to battery platform penetration rates and OSHA compliance enforcement intensity. Industry-specific inputs included lithium-ion cell cost indices and construction employment demographics.
Caveats apply where cobalt and nickel spot market dislocations, Taiwan semiconductor supply interruptions, or accelerated OSHA noise rulemaking could materially shift the outlook. Forecasts embed assumptions regarding battery platform loyalty persistence and certification standard harmonization timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Chips & Hardware
System Basis Chip Market
Communication Chips & Hardware
Data Transmission Module Market
Communication Chips & Hardware
Wifi Chip Market
Communication Chips & Hardware
Nano GPS Chip Market
Communication Chips & Hardware
Communication Standard Logic IC Market
Communication Chips & Hardware
Ethernet PHY Chip Market
Communication Chips & Hardware
Global Application Specific Communications Analog IC Market
Communication Chips & Hardware
Middle East and Africa Marine Communication Systems Market
Communication Chips & Hardware
Industrial Internet Chip Market
Communication Chips & Hardware
5G PCB Market
Communication Chips & Hardware
Zigbee Enabled Devices Market
Communication Chips & Hardware
Global Narrowband IoT (NB IoT) Chipset Market
Communication Chips & Hardware
IPC Soc Chip Market
Communication Chips & Hardware
Optical Communications Market
Communication Chips & Hardware
IoT Chip Market
Communication Chips & Hardware
Zigbee Market