
 Global PCI Express Serial Communication Card Market | 2026-2036
Global PCI Express Serial Communication Card Market Size, Share, and Industry Trends Forecast 2026-2036
Global PCI Express Serial Communication Card Market Outlook
PCI-SIG compliance certification is unwinding the competitive landscape for serial communication cards, forcing smaller vendors to absorb rising validation costs. Advantech Co., Ltd. leverages its embedded computing ecosystem to bundle PCIe serial cards with industrial motherboards. Moxa Inc. anchors its position through hardened designs for rail and factory environments. Digi International Inc. competes by extending its IoT connectivity portfolio into high-reliability serial interfaces.
A PCI Express serial communication card translates PCIe bus signals into RS-232, RS-422, RS-485, or TTL-level serial protocols, typically supporting baud rates from 300 bps to 921.6 kbps across DB9 or terminal-block connectors. These cards enable legacy industrial equipment, medical devices, and telecom gear to interface with modern computing platforms without protocol translation overhead. Multi-port cards command attention in data center and telecommunications deployments where server density drives demand for consolidated serial management. Low-profile configurations are gaining ground in space-constrained embedded and rack-mounted installations. Standard cards remain the volume base across manufacturing floor applications where full-height slots predominate.
FCC emissions rules in the United States, CE marking requirements under EU directives, and China's GB/T standards for information technology equipment collectively shape electromagnetic compatibility obligations and market access conditions. PCIe interface specifications from PCI-SIG further constrain electrical and mechanical design choices across all jurisdictions. Stakeholders must track interface generation transitions and regional certification timelines to align inventory and development cycles with buyer procurement windows.
Market Dynamics
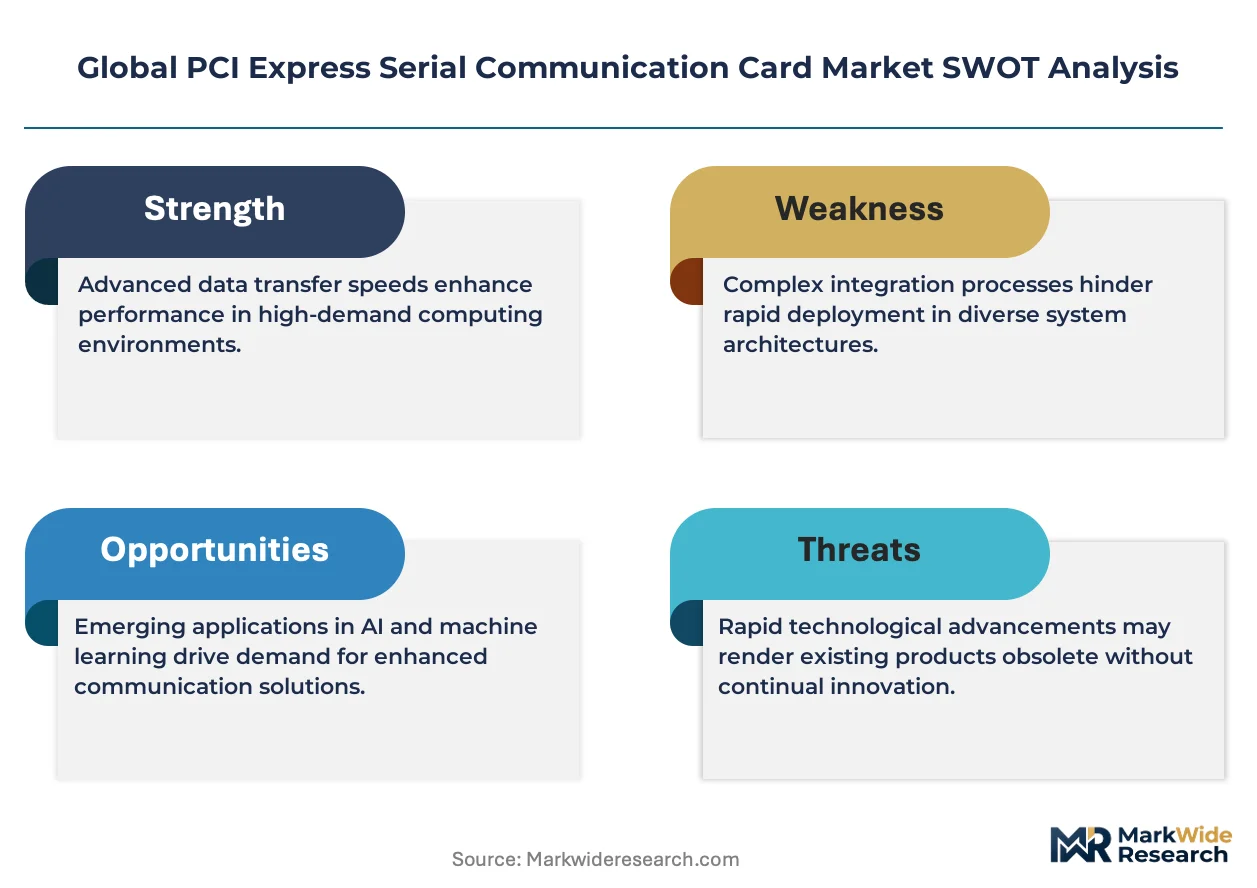
PCI-SIG certification timelines are compressing product development cycles while PCIe 5.0 interface migration forces simultaneous hardware redesigns across industrial computing vendors.
Growth Catalysts
- Smart factory buildouts in Germany:Automotive OEMs are deploying multi-port serial cards for consolidated equipment monitoring on production lines.
- China's GB/T electromagnetic compatibility standards:Domestic certification acceleration is unlocking procurement windows for local industrial automation integrators.
- PCIe 4.0 interface transition:Backward-compatible card designs are capturing upgrade cycles in data center server refreshes.
Market Restraints
- PCI-SIG validation cost inflation:Compliance testing fees for new interface generations are absorbing 15-20% of R&D budgets for smaller card vendors.
- Silicon supply concentration in Taiwan:PCIe bridge chip fabrication bottlenecks are extending lead times for serial controller ASICs.
- USB-C industrial substitution:Native USB serial adapters are displacing low-density PCIe cards in cost-sensitive embedded applications.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Contract manufacturers are qualifying local serial card suppliers for import substitution mandates.
- Rail signaling modernization:Hardened wide-temperature cards are penetrating European and Asian rail infrastructure upgrade programs.
- Medical device connectivity convergence:Isolated RS-422 interfaces on PCIe cards are integrating with patient monitoring system architectures.
Industry Challenges
- FCC Part 15 emissions pre-certification:Electromagnetic testing backlogs are delaying US market entry timelines by 8-12 weeks.
- Legacy BIOS compatibility maintenance:UEFI-only server platforms are forcing dual-firmware development for industrial customer retention.
- Field-programmable gate array skill scarcity:PCIe SerDes implementation expertise is concentrating among senior hardware engineers in semiconductor hubs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global PCI Express Serial Communication Card Market |
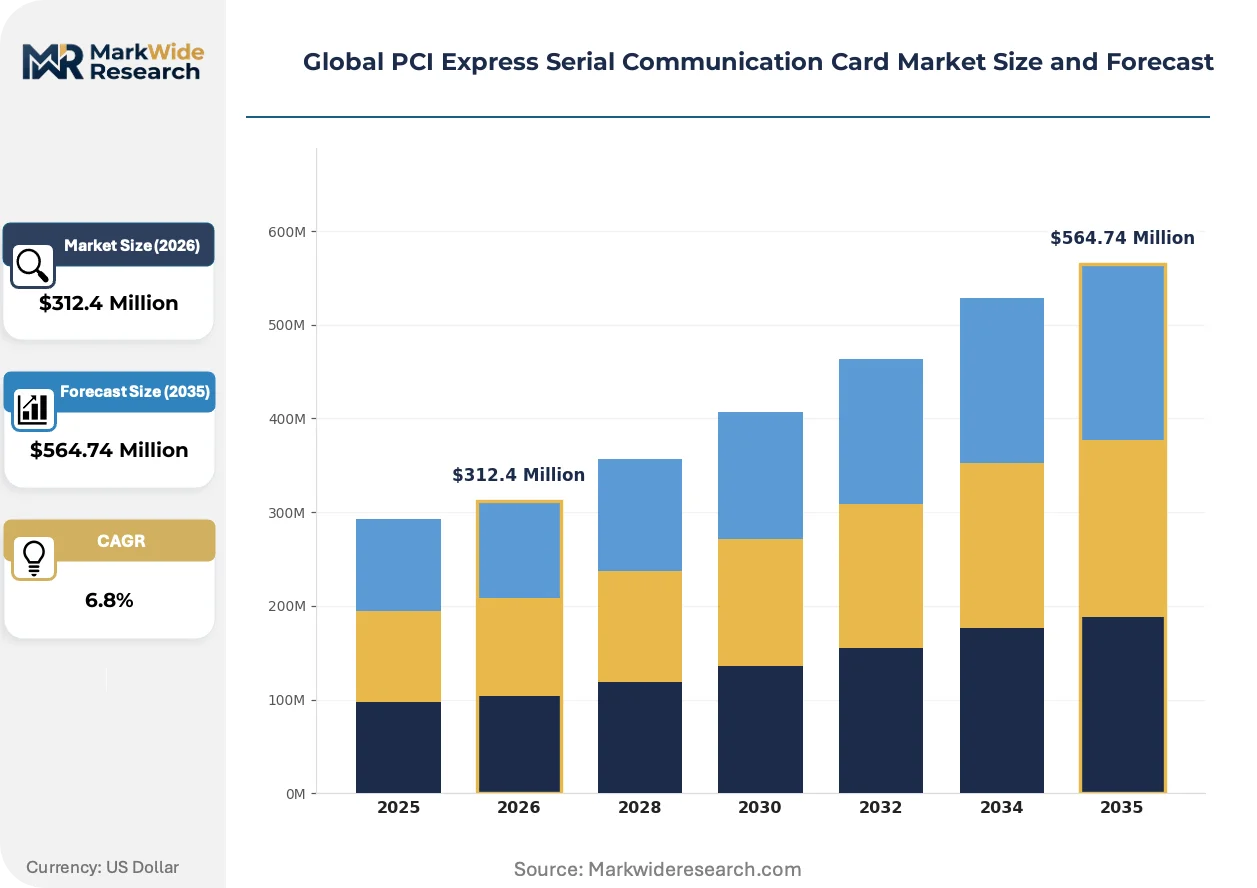
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Cards, Low-Profile Cards, Multi-Port Cards, High-Speed Cards End User: Data Centers, Telecommunications, Manufacturing, Healthcare Installation: Internal, External, Embedded, Rack-Mounted Technology: Serial Communication, Parallel Communication, Hybrid Systems, Wireless Connectivity |
| Companies Covered | Advantech Co., Ltd., ICP DAS Co., Ltd., Brainboxes Limited, Perle Systems, Axiomtek Co., Ltd., Moxa Inc., Sealevel Systems, Inc., Comtrol, Digi International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global PCI Express Serial Communication Card Market Strategic Shifts
Interface generation transitions and hardened design requirements are bifurcating product development roadmaps between data center density optimization and industrial reliability engineering.
PCIe 5.0 signal integrity architectures are fragmenting serial card controller designs into specialized lanes for high-speed data paths. Data center operators are adopting these cards for consolidated out-of-band server management at 32 GT/s transfer rates. The technology is fragmenting vendor R&D allocation between bleeding-edge interface support and legacy PCIe 3.0 maintenance commitments.
EU F-Gas Regulation phase-down schedules are pressuring industrial enclosure thermal management designs. Serial card vendors are eliminating forced-air cooling dependencies in favor of extended-temperature passive heat sinks. Rail and outdoor telecom applications in Germany, France, and the Netherlands are driving hardened -40°C to +85°C operating range certifications.
Consolidated procurement through industrial distributor networks is compressing direct OEM relationships for mid-volume buyers. Automation system integrators in the United States and China are shifting toward single-source vendor agreements covering motherboards, serial cards, and embedded software stacks. Medical device manufacturers represent the vertical where bundled solution purchasing is most advanced.
Global PCI Express Serial Communication Card Market Segmentation
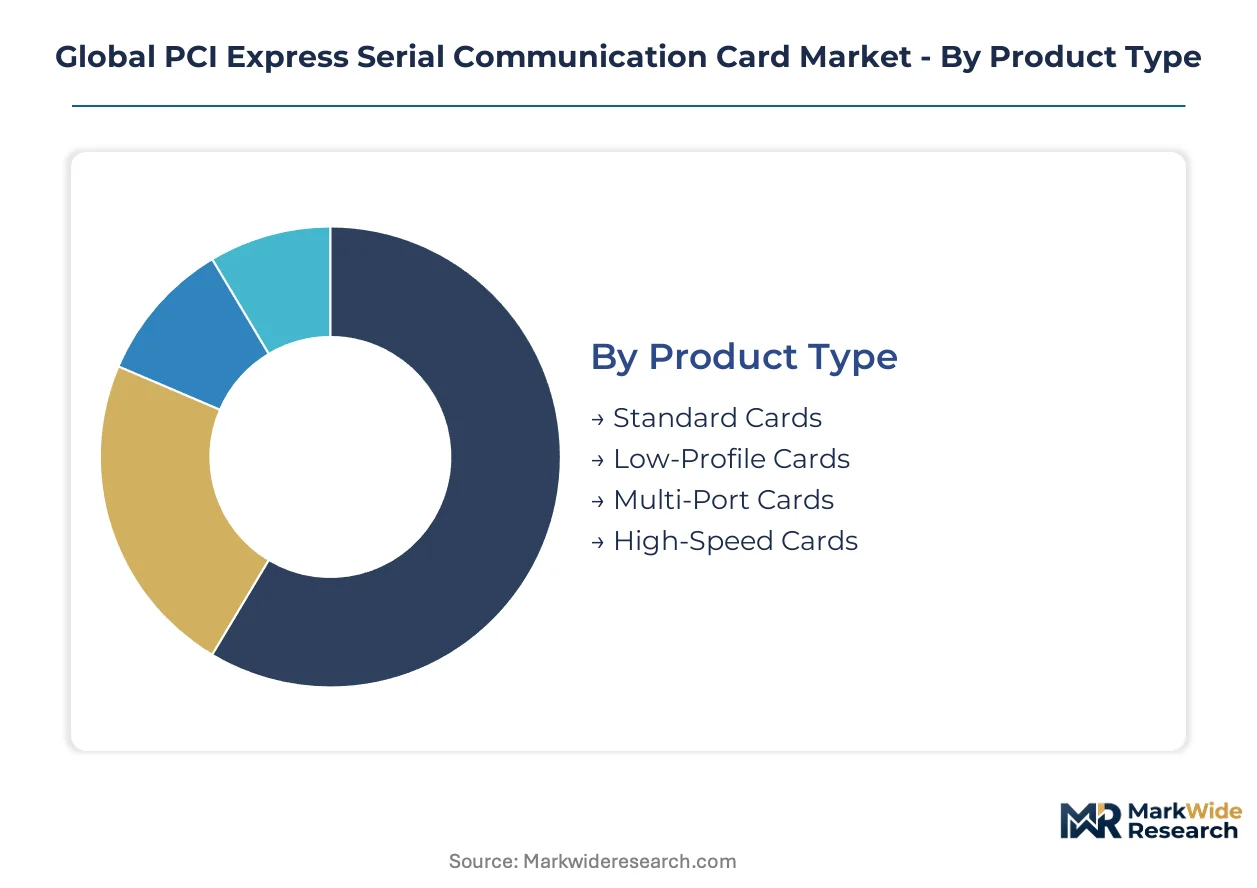
PCIe serial communication cards fragment across four distinct dimensions that govern procurement channels and margin structures. Product type determines whether cards flow through industrial distributors or direct OEM negotiations, while end-user concentration shapes certification requirements and support service bundling.
Product Type:
Channel mix varies sharply by form factor, with multi-port cards commanding direct enterprise sales while low-profile variants dominate embedded computing distributor networks.
- Standard Cards:Full-height PCIe form factors with DB9 connectors supporting RS-232/422/485 protocols at baud rates up to 921.6 kbps. Manufacturing floors in Germany and the United States absorb the majority of volume, driven by legacy equipment retrofit cycles and PCI-SIG compliance mandates for industrial motherboards.
- Multi-Port Cards:Consolidated 4-port to 16-port configurations enabling dense serial management from single PCIe slots. Data center operators in China and the United States deploy these for out-of-band server management, with demand accelerating alongside hyperscale facility buildouts requiring reduced cabling complexity.
- Low-Profile Cards:Half-height designs for space-constrained 1U and 2U rack installations. Embedded system integrators favor these for telecom edge compute nodes.
- High-Speed Cards:PCIe 4.0 and 5.0 implementations supporting 16 GT/s and 32 GT/s transfer rates. Advanced signal integrity requirements limit supplier base to vendors with SerDes implementation expertise.
Standard cards dominate installed base across factory automation. Multi-port configurations are where expansion concentrates for data center density optimization.
End User:
Cost tier stratification separates premium isolated-interface cards for medical applications from economy-grade options for manufacturing floor retrofits.
- Data Centers:Hyperscale and colocation facilities requiring consolidated serial management for thousands of servers. Procurement runs through direct vendor relationships with Advantech and Moxa, bundled with out-of-band management software stacks.
- Telecommunications:Central office and edge infrastructure demanding hardened -40°C to +85°C operating ranges. European rail and Asian telecom operators drive specifications for passive cooling and wide-temperature certification.
- Manufacturing:Automotive OEMs and electronics contract manufacturers deploying cards for PLC communication and CNC machine interfaces. Volume procurement concentrates through industrial distributors like Digi-Key and Mouser.
- Healthcare:Patient monitoring systems and diagnostic equipment requiring isolated RS-422 interfaces for electromagnetic immunity. FDA 510(k) clearance pathways and IEC 60601-1 compliance extend sales cycles but protect margin structures.
Manufacturing absorbs the highest unit volumes. Healthcare represents the steepest expansion trajectory for isolated-interface premium configurations.
Installation:
Volume concentration clusters in rack-mounted deployments for data centers, while embedded installations fragment across diverse industrial form factors.
- Internal:Standard PCIe slot installations within industrial PCs and servers. Dominates manufacturing and data center applications where chassis expansion slots remain available.
- Rack-Mounted:External serial concentrators connecting via PCIe expansion cables. Telecommunications and data center operators favor these for centralized management of distributed equipment.
- Embedded:Direct integration onto single-board computers and COM Express modules. Space constraints favor low-profile and chip-down implementations without standard card edge connectors.
- External:Thunderbolt and USB-C tethered enclosures extending PCIe serial connectivity to laptops and mobile workstations. Field service applications in utilities and transportation drive niche demand.
Internal installations retain the largest installed base. Rack-mounted configurations are climbing the fastest for consolidated infrastructure management.
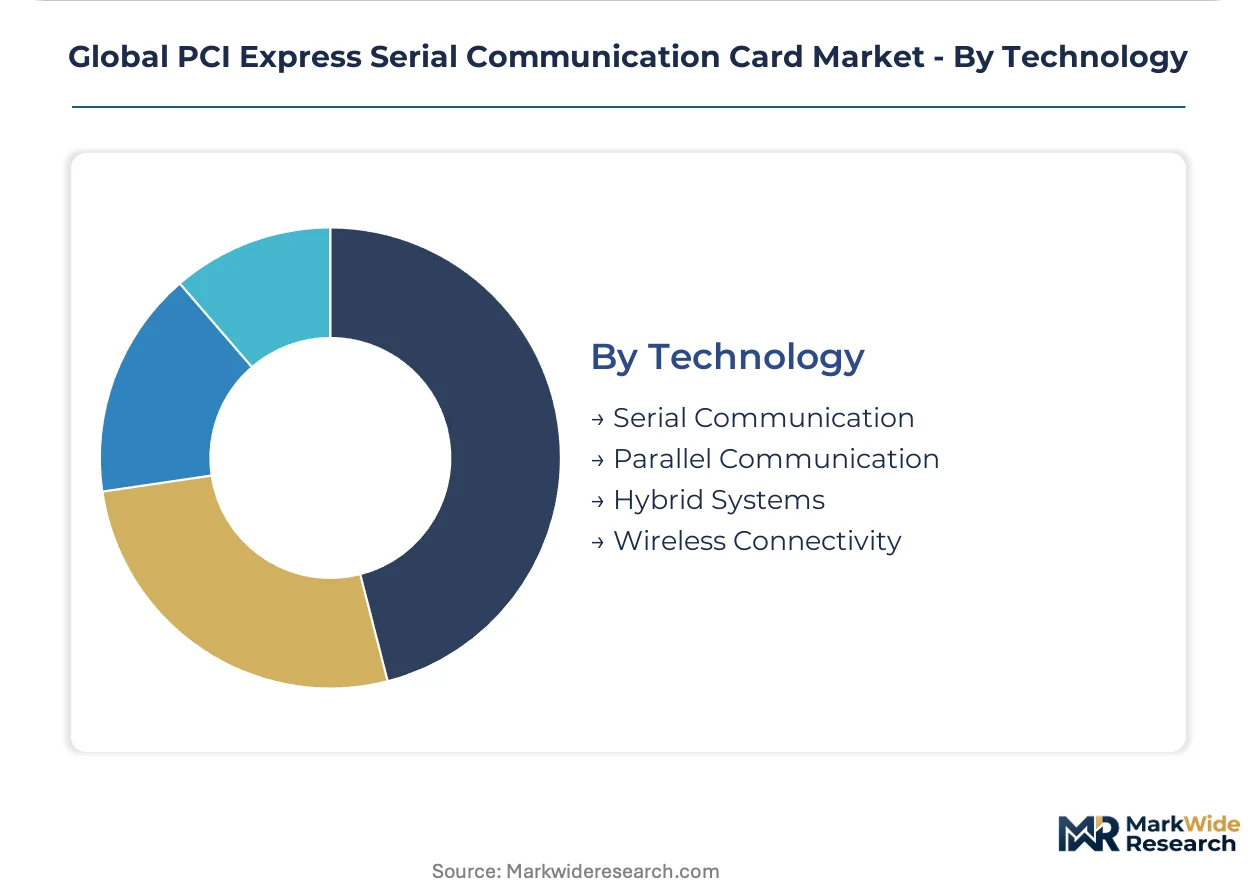
Technology:
Supply concentration for PCIe bridge silicon in Taiwan shapes which technology categories vendors can support profitably.
- Serial Communication:Dominant RS-232, RS-422, and RS-485 protocol translation from PCIe bus signals. Mature controller ASICs from Taiwanese fabs support cost-optimized designs for high-volume manufacturing applications.
- Hybrid Systems:Combined serial and GPIO or CAN bus interfaces on unified PCIe cards. Automotive test equipment and industrial automation integrators in Germany specify these for consolidated I/O reduction.
- Parallel Communication:Legacy IEEE 1284 and GPIO implementations for specialized industrial printers and legacy test equipment. Declining volume concentrates in maintenance-driven replacement cycles.
- Wireless Connectivity:Cellular and Wi-Fi modules integrated with serial protocol translation for IoT gateway applications. Digi International and Sierra Wireless compete in this convergence zone between traditional serial cards and wireless edge devices.
Serial communication dominates installed base across industrial automation. Hybrid systems are gaining share fastest for consolidated I/O architectures in automotive test cells.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government-backed industrial digitization programs across major manufacturing economies are accelerating PCIe serial card deployment timelines. National certification regimes in the United States, China, and Germany are compressing procurement windows for compliant suppliers. Smart factory investments and data center buildouts in these markets concentrate demand for multi-port and hardened configurations.
United States
Hyperscale data center operators in Virginia and Texas are consolidating out-of-band server management through multi-port PCIe serial installations. FCC Part 15 emissions pre-certification backlogs are delaying market entry for non-compliant vendors by 8-12 weeks. The Dallas-Fort Worth metroplex hosts expanding industrial automation integrators qualifying cards for automotive manufacturing retrofits.
China
Domestic electronics contract manufacturers under the PLI scheme are qualifying local serial card suppliers for import substitution mandates. GB/T electromagnetic compatibility standards acceleration is unlocking procurement windows for industrial automation integrators in Shenzhen and Dongguan. The Yangtze River Delta cluster concentrates PCB fabrication and PCIe bridge chip packaging operations.
Germany
Automotive OEMs in Stuttgart and Munich are deploying multi-port serial cards for consolidated equipment monitoring on production lines. EU F-Gas Regulation phase-down schedules are pressuring thermal management designs toward passive cooling architectures. The Bavarian industrial corridor drives hardened -40°C to +85°C operating range certifications for rail signaling modernization.
Japan
Precision manufacturing equipment builders in Nagoya and Osaka are specifying isolated RS-422 interfaces for electromagnetic immunity in medical device integration. METI industrial IoT promotion programs are subsidizing legacy equipment connectivity upgrades. The Chubu region hosts concentrated demand for low-profile configurations in space-constrained machine tool controllers.
India
Electronics manufacturing services firms in Karnataka and Tamil Nadu are establishing local serial card supply chains under PLI scheme incentives. BIS certification requirements for information technology equipment are structuring procurement qualification timelines. The Bengaluru-Tumkur electronics cluster is emerging as a qualification hub for export-oriented industrial computing vendors.
Global PCI Express Serial Communication Card Market Competitive Environment
Listed leaders compete with private specialists across certification bandwidth and vertical application depth. The vendor base stratifies between scale-driven platform vendors, hardened-environment specialists, and regional contract manufacturers. Three archetypes dominate: embedded computing ecosystem bundlers, rail and telecom hardened-design experts, and IoT connectivity portfolio extenders. Competitive moves concentrate on PCI-SIG compliance certification acceleration and industrial distributor network consolidation.
Within the embedded computing ecosystem tier, Advantech Co., Ltd. and Axiomtek Co., Ltd. exemplify platform bundling strategies that integrate serial cards with motherboard and software stack offerings. Moxa Inc. occupies a position as the hardened-environment archetype, representing designs engineered for extreme temperature and vibration tolerance in rail and factory deployments. Digi International Inc. anchors the IoT convergence zone, extending connectivity portfolios into high-reliability serial interfaces for gateway applications.
| Leading Market Players |
|---|
| Advantech Co., Ltd. |
| ICP DAS Co., Ltd. |
| Brainboxes Limited |
| Perle Systems |
| Axiomtek Co., Ltd. |
| Moxa Inc. |
| Sealevel Systems, Inc. |
| Comtrol |
| Digi International Inc. |
| Others |
Value Chain & Pricing Dynamics
Eighteen-to-twenty-four week lead times for PCIe bridge silicon concentrate pricing power with Taiwanese foundry partners, compressing margins for card vendors unable to secure allocation priority. This inventory constraint cascades through certification timelines, forcing buyers into premium prepayment terms for PCI-SIG validated designs.
Pricing Analysis
Certification level (PCI-SIG/FCC/CE-grade) creates the primary spread between economy and premium tiers. Three-tier pricing structure across isolated-interface, standard-industrial, and basic-commercial levels dominates transactional procurement. Cost compression in economy-tier RS-232 cards intensifies because USB-C substitution erodes volume scale. Manufacturing floor retrofit buyers exhibit highest price sensitivity, while medical device OEMs accept premium positioning for IEC 60601-1 compliance.
Supply Chain Analysis
Strategic stockpiling of PCIe controller ASICs supersedes just-in-time preferences as allocation uncertainty persists. Taiwan, South Korea, and China anchor wafer fabrication and PCB assembly operations. Controller silicon, passive components, and connector hardware constitute critical input dependencies. Single-source vulnerability around 16nm and 7nm PCIe bridge production concentrates risk. Distribution runs through industrial electronics distributors like Digi-Key and Mouser for mid-volume manufacturing accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PCIe SerDes implementation expertise concentrates among senior hardware engineers in semiconductor hubs, constraining vendor expansion velocity. This capability bottleneck favors incumbents with captive engineering depth while elevating acquisition premiums for specialized design teams.
For Market Incumbents: Compound defensive positioning through backward integration into PCIe bridge chip supply agreements with Taiwanese foundries. Accelerate PCI-SIG 5.0 certification pipelines to capture data center refresh cycles before USB-C management interfaces gain traction in server architectures. Channel control through exclusive industrial distributor relationships protects margin structures against emerging contract manufacturers. For New Entrants and Emerging Players: Differentiate on rail and medical verticals requiring -40°C to +85°C hardened designs where certification barriers deter commodity competition. India's PLI scheme electronics manufacturing corridor offers the most penetrable geography for import substitution qualification. Pursue single-source vendor agreements with automation system integrators seeking bundled motherboard and serial card procurement. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial computing parents where serial card divisions lack strategic focus but retain PCI-SIG compliance assets. Long-term viability hinges on interface generation transition execution rather than legacy PCIe 3.0 maintenance revenue. Monitor hyperscale data center capex trajectories as the inflection signal for multi-port card demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| PCI-SIG 5.0 Certification Acceleration | Early compliance captures 32 GT/s data center server management refresh cycles. |
| Backward Integration into Bridge Silicon | Captive supply agreements with TSMC or GlobalFoundries secure allocation priority. |
| Rail Infrastructure Partnership | EU F-Gas Regulation compliance positions vendors for hardened -40°C certification mandates. |
| Medical Device Vertical Penetration | IEC 60601-1 isolated interfaces protect margin structures against USB-C displacement. |
| India PLI Scheme Localization | BIS certification and local assembly qualify vendors for electronics manufacturing import substitution. |
Study Parameters
A standing panel of industrial automation procurement managers, embedded system design engineers, PCI-SIG compliance officers, and data center infrastructure architects provided ongoing calibration against secondary validation. Primary fieldwork combined structured interviews with OEM qualification teams and channel partner distribution heads. Secondary sources encompassed PCI-SIG specification releases, FCC equipment authorization databases, EU CE marking directories, and industrial electronics customs trade records. Bottom-up unit shipment estimates triangulated against top-down semiconductor foundry wafer allocation disclosures.
Consistency checks validated volume and value outputs against hyperscale data center capex disclosures and industrial automation capital expenditure surveys across the projection horizon. Segmentation modeling incorporated product type, end-user vertical, installation configuration, and interface generation transition timing. CAGRs derived from logistic diffusion curves fitted to PCIe standard adoption histories. Forecast inputs included foundry capacity expansion announcements and national industrial digitization program budget allocations.
The analysis sits within stated boundaries; outcomes outside sustained hyperscale facility buildouts or accelerated PCIe 5.0 motherboard penetration would require recalibration. Forecasts reflect assumptions regarding Taiwan semiconductor supply continuity and PCI-SIG certification timeline stability. Revision becomes warranted when USB-C industrial substitution rates or rail infrastructure investment commitments cross threshold inflections.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Chips & Hardware
5G CPE Chip Market
Communication Chips & Hardware
Global Application Specific Communications Analog IC Market
Communication Chips & Hardware
Global Narrowband IoT (NB IoT) Chipset Market
Communication Chips & Hardware
Wi-Fi Adapter Card Market
Communication Chips & Hardware
Satellite Communication Components Market
Communication Chips & Hardware
Wireless Transmitter Chip Market
Communication Chips & Hardware
Asia-Pacific Embedded Antenna Systems Market
Communication Chips & Hardware
Optical Communications Market
Communication Chips & Hardware
4D Radar Chip Market
Communication Chips & Hardware
Global Hybrid Fiber Coaxial Market
Communication Chips & Hardware
ESP32 Module Market
Communication Chips & Hardware
4G Smart Device Chip Market
Communication Chips & Hardware
Jobsite Radios Market
Communication Chips & Hardware
Time-Of-Flight Chip Market
Communication Chips & Hardware
Semiconductor Device in Communication Industry Market
Communication Chips & Hardware
Middle East and Africa Marine Communication Systems Market