
 Global Network Processing Unit (NPU) Market | 2026-2036
Global Network Processing Unit (NPU) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Network Processing Unit (NPU) Market Outlook
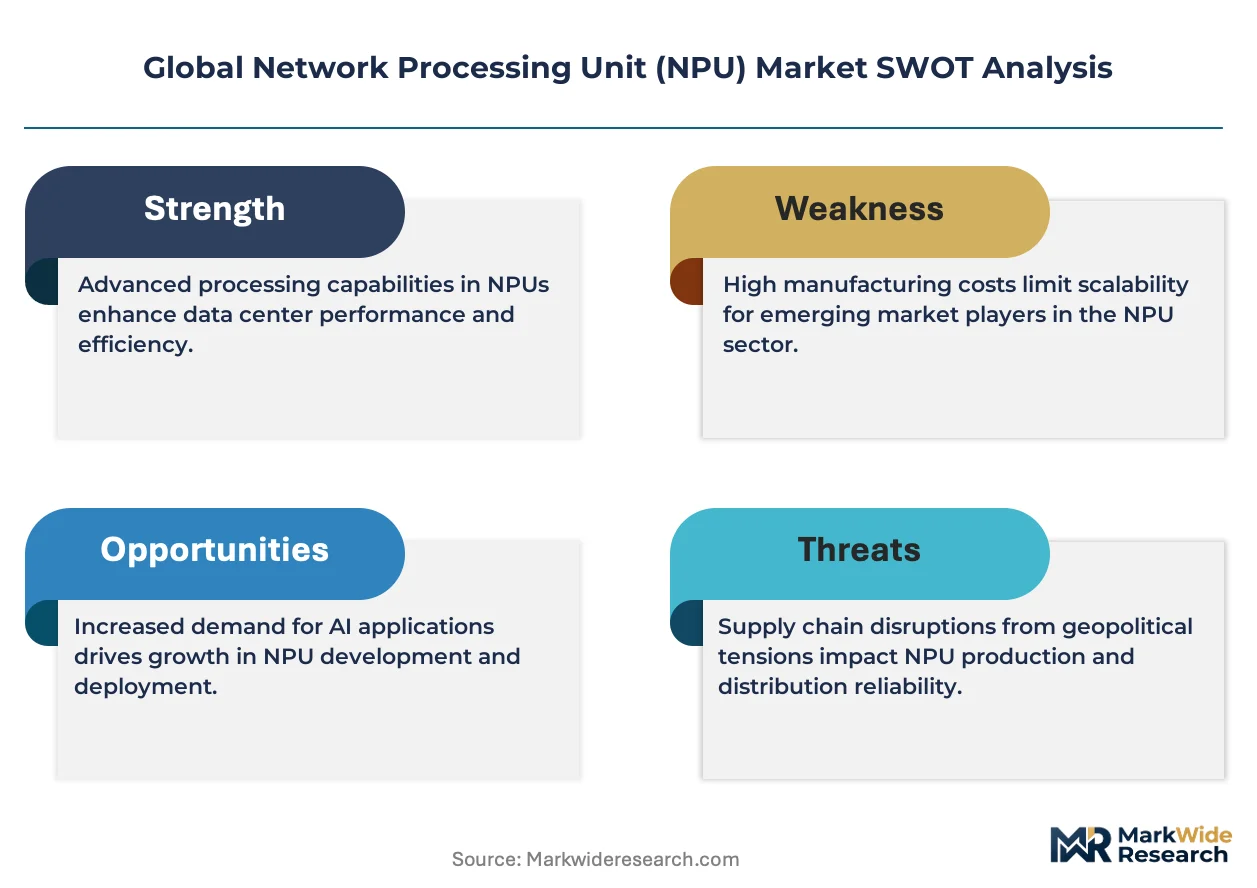
The split between premium multilayer NPUs and commodity Layer 2 silicon is shifting procurement patterns across the networking stack. Broadcom Inc. leverages its merchant silicon scale to dominate high-volume data center sockets. Marvell Technology, Inc. anchors its position in carrier-grade infrastructure through custom ASIC programs. Qualcomm competes at the edge computing frontier with integrated connectivity-NPU combinations for distributed deployments.
A Network Processing Unit is a dedicated semiconductor device architected to execute packet forwarding, traffic classification, and protocol processing at line rates exceeding 400 Gbps, typically fabricated on advanced CMOS nodes with on-chip memory hierarchies optimized for deterministic latency. Its commercial purpose centers on offloading network workloads from general-purpose CPUs in routers, switches, and security appliances. Multilayer NPUs capture the deepest margin pools where carriers consolidate routing, switching, and deep packet inspection into single-chip designs. ASIC-based technology leads in unit economics for hyperscale buyers, while FPGA flexibility sustains premium pricing in prototype and low-volume security applications. Edge computing represents the fastest-growing application vector as latency requirements push intelligence toward radio access networks.
FCC spectrum policy and NIST cybersecurity frameworks in the United States, combined with China's MIIT equipment certification mandates and the EU's Cybersecurity Act through ENISA, collectively tighten compliance thresholds for NPU-enabled infrastructure. REACH substance restrictions and evolving RoHS thresholds in Europe further constrain packaging and foundry choices for vendors serving multiple geographies. Buyers must weigh sovereign certification timelines against performance roadmaps when qualifying suppliers for multi-country deployments.
Market Dynamics
The 5G standalone core rollout is compressing NPU qualification cycles as carriers consolidate routing, switching, and security functions onto single-chip architectures. This convergence is forcing silicon vendors to recalibrate roadmaps around deterministic latency specifications rather than raw throughput benchmarks.
Growth Catalysts
- 5G Core Infrastructure:Telecom operators in Germany, China, and the United States are deploying NPUs at network aggregation points to handle user plane function offloading. Carrier procurement cycles now prioritize line-rate processing above 400 Gbps.
- EU Cybersecurity Act:ENISA certification mandates for critical network infrastructure are accelerating replacement of legacy forwarding silicon with tamper-resistant NPU designs. Hardware security module integration has become a non-negotiable specification.
- Edge Computing Latency Requirements:Radio access network intelligence is migrating toward distributed cell sites. NPUs with integrated AI accelerators are capturing socket opportunities previously served by discrete GPU-CPU combinations.
Market Restraints
- Advanced Node Concentration:Fabrication of sub-7nm NPU designs depends on a concentrated foundry base in Taiwan and South Korea. Geopolitical friction around semiconductor equipment export controls threatens supply continuity for merchant silicon vendors.
- Power Density Constraints:800 Gbps-class NPUs exceed 350W thermal envelopes, complicating chassis design for legacy router platforms. Cooling infrastructure retrofits add substantial capex burden to carrier upgrade decisions.
- FPGA Substitution in Low Volume:Security appliance manufacturers below ten thousand unit annual volumes favor field-programmable gate arrays for protocol flexibility. This price-performance crossover siphons revenue from programmable NPU product lines.
Strategic Opportunities
- India 5G Spectrum Deployment:TRAI auction allocations and BSNL network modernization are creating fresh demand for cost-optimized NPUs. Domestic equipment certification timelines favor vendors with local integration partnerships.
- Converged AI-Networking Silicon:Neural processing and packet forwarding are merging onto unified die architectures. Vendors controlling both vector math units and programmable pipeline engines can capture premium socket positions.
- US CHIPS Act Incentives:Department of Commerce funding for domestic semiconductor fabrication is lowering barrier costs for NPU design houses seeking captive foundry capacity. Arizona and Texas greenfield sites are qualifying advanced packaging for network silicon.
Industry Challenges
- Verification Engineer Scarcity:Formal methods expertise for 400 Gbps+ protocol compliance testing commands compensation premiums exceeding thirty percent above analog design roles. Hiring pipelines from university verification labs remain insufficient.
- Multi-Country Certification Overlap:Simultaneous FCC, MIIT, and BIS equipment approvals require divergent electromagnetic compatibility test suites. Qualification timeline stacking extends product launch windows by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Network Processing Unit (NPU) Market |
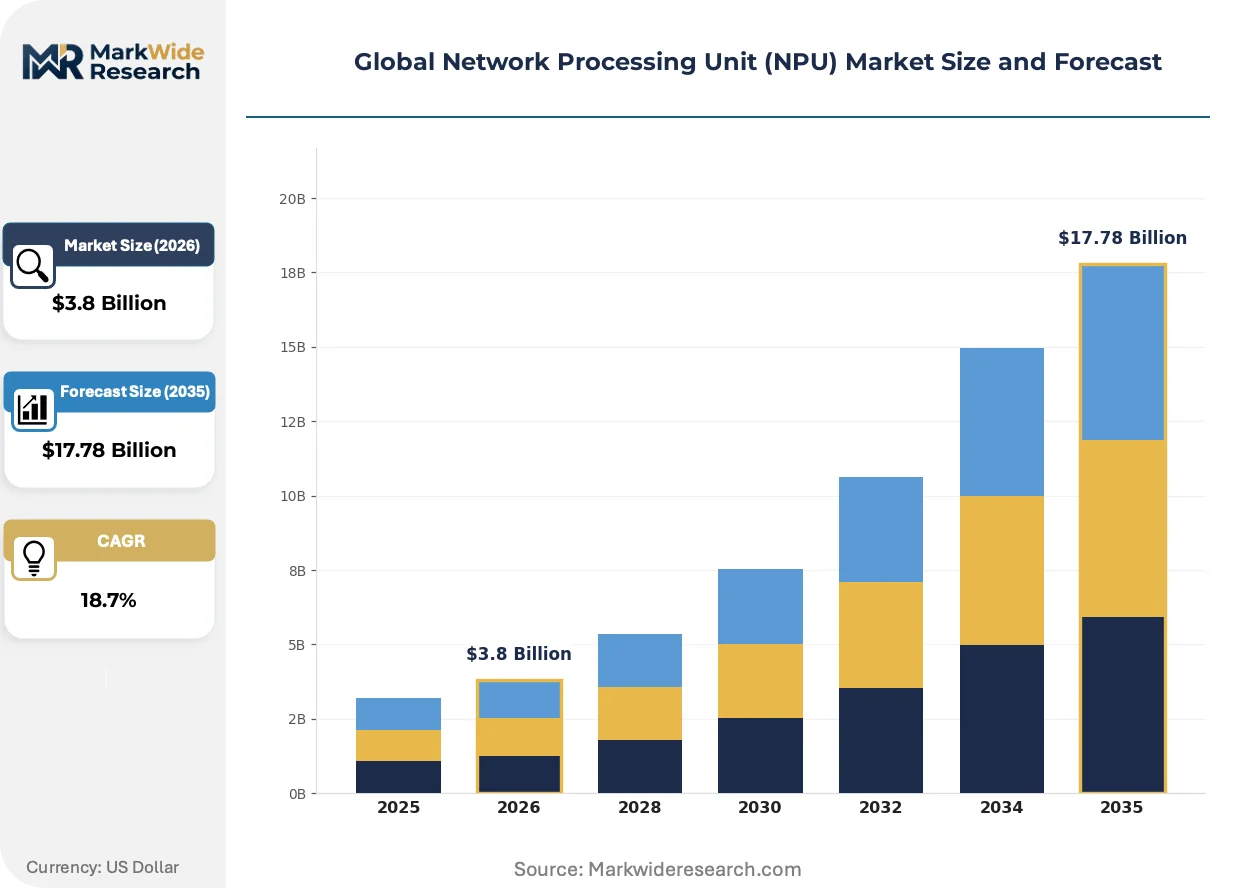
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.78 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Layer 2 NPU, Layer 3 NPU, Multilayer NPU, Hybrid NPU Technology: FPGA, ASIC, RISC, DSP End User: Telecom Providers, Cloud Service Providers, Enterprises, Data Centers Application: Network Management, Traffic Processing, Security Services, Edge Computing |
| Companies Covered | Qualcomm, Intel, Broadcom Inc., Fortinet, Inc., AMD, Cisco Systems, Inc., Marvell Technology, Inc., Sandvine, NVIDIA Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Network Processing Unit (NPU) Market Strategic Shifts
Silicon architectures are fragmenting between merchant scale and custom ASIC programs as hyperscale buyers internalize NPU design. This bifurcation is compressing margins for mid-tier programmable solutions while deepening moats around vertically integrated supply chains.
Chiplet-based NPU designs are expanding into carrier-grade routing platforms. Disaggregated die architectures allow mixing of logic tiles from different process nodes on a single substrate. Juniper and Nokia supply chain teams are qualifying 2.5D interposer assemblies for core network deployment, reducing time-to-market for new protocol support by decoupling I/O die from compute tile refreshes.
China's MIIT equipment certification mandates are tightening electromagnetic compatibility thresholds for network infrastructure silicon. Domestic vendors must now submit to extended thermal cycling tests before receiving network access licenses. Foreign NPU suppliers are responding by pre-qualifying reference designs at MIIT-accredited labs in Shenzhen, front-loading compliance costs to avoid deployment delays.
Hyperscale cloud operators are consolidating silicon procurement around vertically integrated supply chains. Amazon Web Services and Microsoft Azure have established dedicated NPU design teams, displacing merchant silicon at the top of their switching hierarchies. This concentration is most visible in the United States, where top-three cloud providers now account for the majority of 800 Gbps port shipments.
Global Network Processing Unit (NPU) Market Segmentation
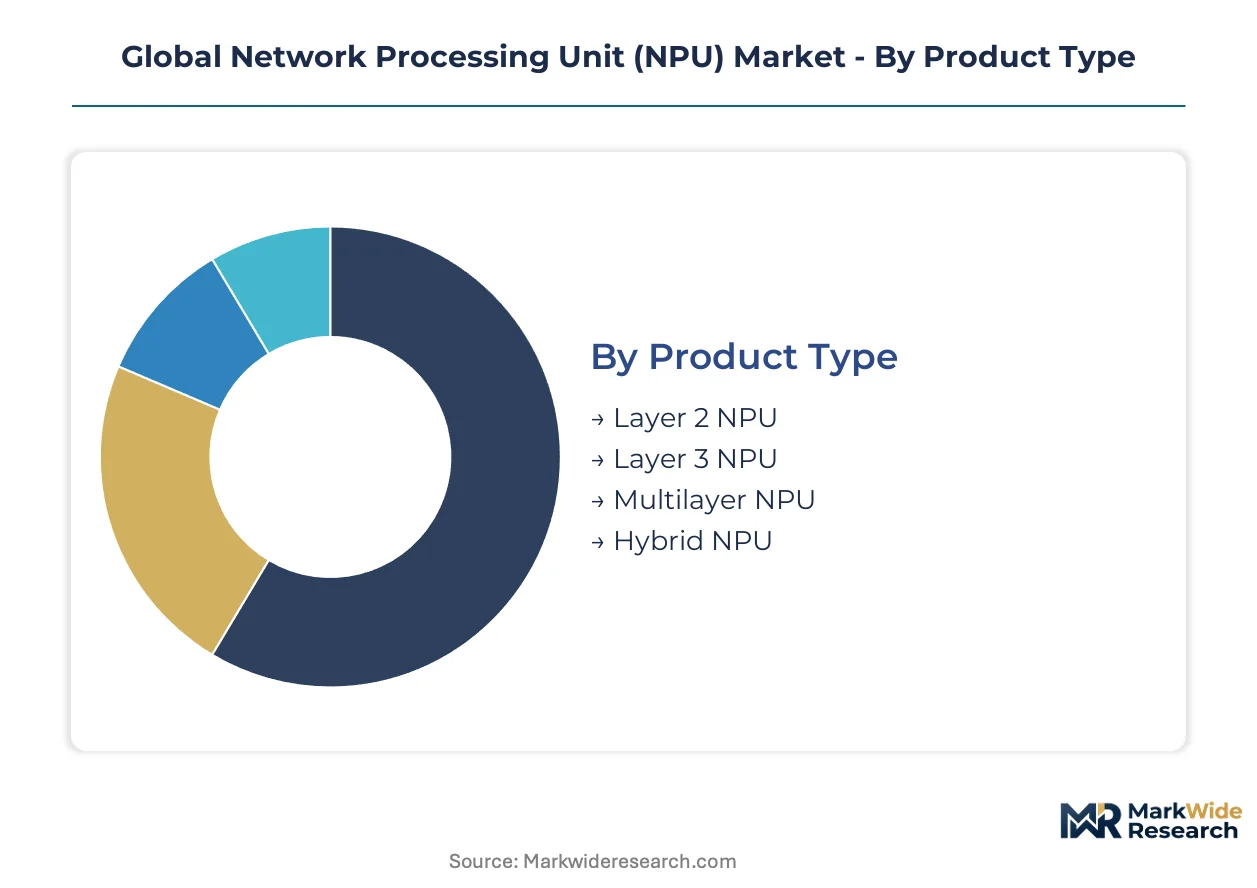
NPU architectures fragment across protocol layers and silicon implementations, with procurement criteria diverging sharply between carrier-grade determinism and hyperscale cost optimization. Understanding these splits reveals where margin pools concentrate and which technology bets carry the highest commercial stakes.
Product Type:
Layer sophistication defines the pricing architecture, with deeper protocol integration commanding premium socket positions in carrier infrastructure.
- Layer 2 NPU:These devices execute Ethernet switching, VLAN tagging, and MAC address learning at line rates up to 800 Gbps with minimal buffering. Demand concentrates in hyperscale data centers across the United States and China where cost-per-port metrics dominate procurement, constrained by merchant silicon commoditization pressures.
- Layer 3 NPU:Architected for IP routing, longest-prefix matching, and MPLS label operations with integrated TCAM blocks for forwarding table scalability. German and Japanese carriers specify these for aggregation routers, driven by deterministic latency requirements in 5G transport networks.
- Multilayer NPU:Consolidates switching, routing, and deep packet inspection onto unified die architectures with hierarchical memory subsystems.
- Hybrid NPU:Combines programmable pipeline stages with fixed-function accelerators for cryptographic and timestamping operations.
Multilayer NPUs lead on scale; Hybrid NPUs lead on momentum.
Technology:
Implementation methodology trades off unit economics against flexibility, with volume thresholds determining the optimal silicon choice for each deployment context.
- ASIC:Full-custom designs deliver optimal power-performance-area metrics at production volumes exceeding one million units annually. Hyperscale cloud operators in the United States and China have driven massive ASIC adoption for top-of-rack switches, constrained by foundry capacity allocation and mask set costs.
- FPGA:Field-programmable gate arrays enable protocol reconfiguration without silicon respins, sustaining premium pricing in security appliances and prototype validation. European defense and financial network operators specify these for post-quantum cryptography migration paths.
- RISC:Reduced instruction set architectures with network-optimized instruction extensions provide programmable forwarding with lower NRE than full custom designs.
- DSP:Digital signal processors target physical layer functions including forward error correction and modulation in coherent optical transceivers.
ASIC technology leads on scale; FPGA technology leads on momentum.
End User:
Customer type dictates performance specifications, with carrier networks prioritizing reliability metrics against cloud operator throughput optimization.
- Telecom Providers:These operators specify carrier-grade NPUs with five-nines availability, redundant power domains, and extended temperature ranges. Deployment concentrates in Germany, China, and India where 5G standalone core buildouts require deterministic latency for network slicing implementations.
- Cloud Service Providers:Hyperscale buyers internalize NPU design teams and displace merchant silicon through custom ASIC programs. United States-based operators dominate 800 Gbps port shipments, constrained by power density limitations in legacy facilities.
- Enterprises:Mid-market buyers prioritize integrated security functions and simplified management interfaces over raw throughput specifications.
- Data Centers:Colocation and wholesale facilities balance capital efficiency against multi-tenant isolation requirements in their silicon selections.
Telecom Providers lead on scale; Cloud Service Providers lead on momentum.
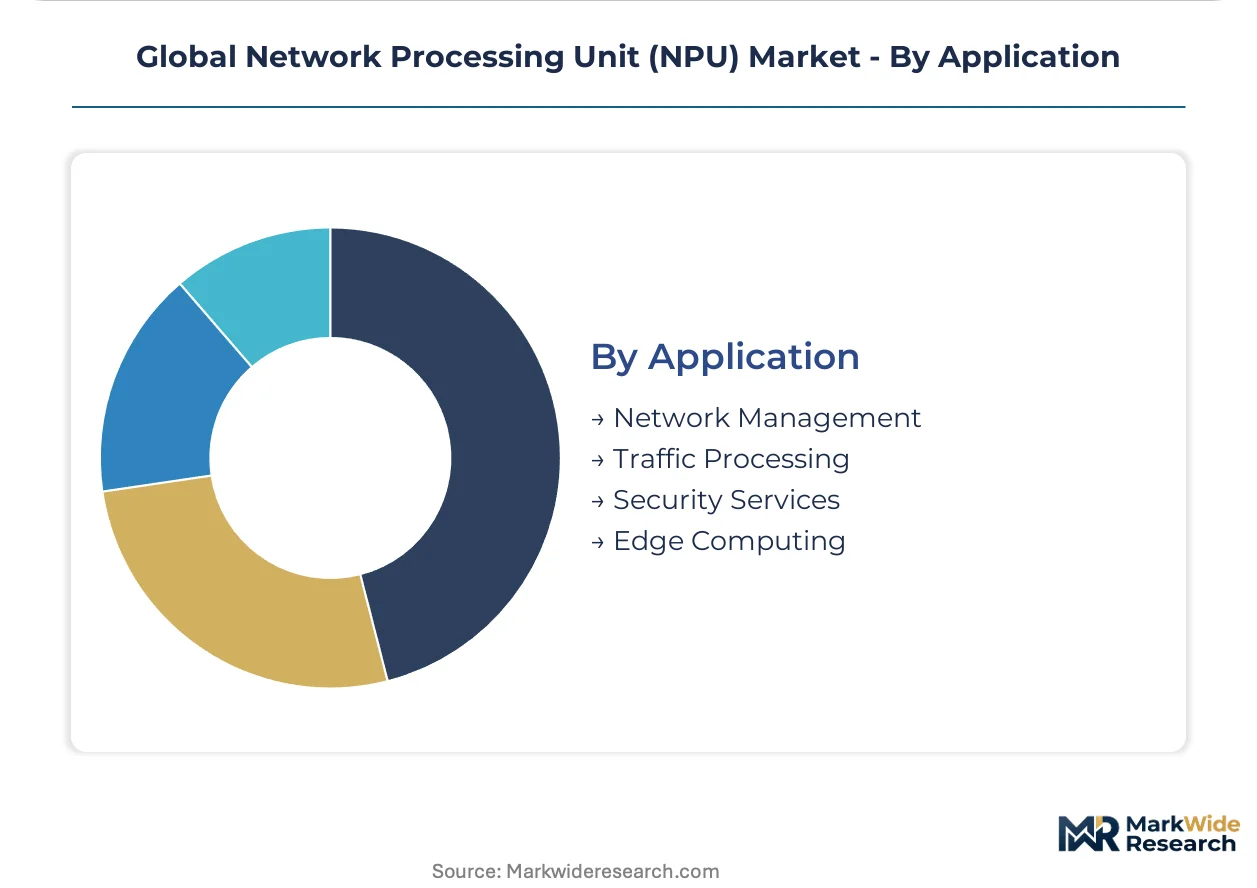
Application:
Workload characteristics determine the optimal balance between programmable flexibility and fixed-function acceleration in NPU selection.
- Edge Computing:Distributed intelligence at radio access networks and industrial sites demands NPUs with integrated AI accelerators and sub-10W thermal envelopes. United States and Chinese deployments are expanding most quickly as latency requirements push computation toward cell sites and factory floors.
- Security Services:Deep packet inspection, intrusion detection, and encrypted traffic analysis require programmable content inspection engines with high-throughput pattern matching. European Union ENISA certification mandates are accelerating hardware security module integration in these applications.
- Network Management:Control plane offloading and telemetry aggregation functions prioritize deterministic response times over peak throughput.
- Traffic Processing:Core forwarding and quality-of-service enforcement represent the baseline NPU function with mature merchant silicon supply.
Traffic Processing leads on scale; Edge Computing leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Verification engineers with formal methods expertise concentrate in Bangalore, Shenzhen, and Austin, anchoring NPU design capabilities across three continents. These talent clusters support the 400 Gbps+ protocol compliance testing required for carrier-grade silicon qualification.
United States
FCC spectrum policy and NIST cybersecurity frameworks tighten compliance thresholds for NPU-enabled infrastructure. The Department of Commerce CHIPS Act funding lowers barrier costs for design houses seeking captive foundry capacity in Arizona and Texas. Hyperscale cloud operators in the Pacific Northwest and Northern Virginia dominate 800 Gbps port shipments through custom ASIC programs.
China
MIIT equipment certification mandates require extended thermal cycling tests before network access licenses are granted. Domestic vendors submit to stricter electromagnetic compatibility thresholds for infrastructure silicon. The Yangtze River Delta and Pearl River Delta clusters host pre-qualification labs in Shenzhen where foreign suppliers front-load compliance costs.
Germany
Telecom operators specify carrier-grade NPUs with five-nines availability for 5G standalone core buildouts. EU Cybersecurity Act mandates through ENISA accelerate replacement of legacy forwarding silicon with tamper-resistant designs. Bavaria and North Rhine-Westphalia anchor aggregation router deployment driven by deterministic latency requirements in transport networks.
India
TRAI auction allocations and BSNL network modernization create fresh demand for cost-optimized NPUs. Domestic equipment certification timelines favor vendors with local integration partnerships. Bangalore and Hyderabad verification labs supply formal methods expertise for protocol compliance testing, though hiring pipelines remain insufficient.
South Korea
Advanced node fabrication concentrates in foundry bases supplying sub-7nm NPU designs for merchant silicon vendors. Geopolitical friction around semiconductor equipment export controls threatens supply continuity. Seoul Capital Area and Busan-Ulsan clusters host packaging facilities qualifying 2.5D interposer assemblies for core network deployment.
Global Network Processing Unit (NPU) Market Competitive Environment
Capital-heavy producers compete with asset-light designers across divergent business models in the NPU market. The vendor base splits between merchant silicon scale players and custom ASIC program specialists serving hyperscale internalization trends. Three archetypes dominate: vertically integrated cloud operators with captive design teams, fabless semiconductor houses leveraging foundry partnerships, and programmable silicon vendors serving security appliance niches. Competitive moves center on strategic partnerships for chiplets integration and geographic expansion into India 5G deployment corridors.
Within the merchant silicon tier, Broadcom Inc. and Marvell Technology, Inc. anchor distinct positioning vectors. Broadcom exemplifies high-volume data center socket dominance through scale economics. Marvell occupies a position in carrier-grade infrastructure through custom program relationships. Qualcomm sits within the edge computing frontier archetype, representing integrated connectivity-NPU combinations for distributed deployments. These three entities collectively illustrate the bifurcation between commodity Layer 2 silicon and premium multilayer architectures reshaping procurement patterns.
| Leading Market Players |
|---|
| Qualcomm |
| Intel |
| Broadcom Inc. |
| Fortinet, Inc. |
| AMD |
| Cisco Systems, Inc. |
| Marvell Technology, Inc. |
| Sandvine |
| NVIDIA Corporation |
| Others |
Value Chain & Pricing Dynamics
Carrier procurement consolidation around 400 Gbps line-rate specifications is compressing supplier margins and forcing foundry capacity commitments before volume materializes. This demand-side pressure elevates pricing power for Taiwan and South Korea fabrication facilities while squeezing mid-tier programmable NPU vendors caught between ASIC scale economies and FPGA flexibility premiums.
Pricing Analysis
Bundled hardware-software service contracts dominate carrier-grade deployments, separating multilayer NPU premiums from commodity Layer 2 silicon spot purchases. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with ENISA-compliant tamper-resistant designs commanding substantial premiums over baseline forwarding silicon. Pricing pressure stems from hyperscale internalization of NPU design teams displacing merchant silicon at top-tier cloud operators. Cloud service providers exhibit lowest price sensitivity due to captive ASIC programs, while security appliance manufacturers below ten thousand unit volumes face acute cost compression from FPGA substitution.
Supply Chain Analysis
Reverse-logistics flows for carrier-grade NPU refurbishment center on extended thermal cycling recovery programs mandated by China's MIIT certification regime. Fabrication concentrates in Taiwan and South Korea for sub-7nm advanced nodes, with Arizona and Texas greenfield sites qualifying under CHIPS Act incentives. Raw material dependencies include silicon wafers, advanced packaging substrates, and EUV photoresist chemistries. Single-source vulnerability around Taiwan Strait geopolitical friction threatens supply continuity for merchant silicon vendors. Distribution runs through direct foundry relationships for hyperscale buyers and authorized distributors for mid-market security appliance manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Network Processing Unit Market operates as a stable compounder anchored by telecom infrastructure refresh cycles that demand deterministic latency specifications regardless of macroeconomic conditions.
For Market Incumbents: To counter hyperscale cloud operator internalization of NPU design teams, Broadcom and Marvell must deepen captive foundry partnerships in Arizona and Texas while accelerating chiplet-based architectures that reduce time-to-market for protocol refreshes. Certification investment in MIIT-accredited Shenzhen labs front-loads compliance costs and defends socket positions against emerging domestic Chinese vendors. For New Entrants and Emerging Players: The EU Cybersecurity Act through ENISA opens a window for tamper-resistant NPU specialists to capture replacement demand from legacy forwarding silicon in German and French carrier networks. India's BSNL modernization and TRAI spectrum allocations present the most penetrable geography for cost-optimized Layer 3 designs. Go-to-market should emphasize local integration partnerships that compress domestic equipment certification timelines. For Investors and Strategic Acquirers: Asymmetric upside sits with verification engineering specialists possessing formal methods expertise for 400 Gbps+ protocol compliance, as hiring pipelines from university labs remain insufficient and compensation premiums exceed thirty percent above analog design roles. Long-term viability favors acquisition targets with established MIIT pre-qualification capabilities and 2.5D interposer assembly partnerships. Monitor CHIPS Act funding disbursement velocity as an inflection indicator for domestic fabrication capacity expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Custom ASIC Program Expansion | Hyperscale cloud operators displace merchant silicon through captive design teams in Pacific Northwest and Northern Virginia. |
| Chiplet Architecture Adoption | Juniper and Nokia supply chains qualify 2.5D interposer assemblies to decouple I/O die from compute tile refreshes. |
| MIIT Pre-Qualification Investment | Foreign suppliers front-load compliance costs at Shenzhen labs to avoid China network access license delays. |
| Edge AI-NPU Integration | Qualcomm captures distributed cell site sockets previously served by discrete GPU-CPU combinations. |
| Domestic Foundry Partnership | Design houses leverage Arizona and Texas CHIPS Act sites to reduce Taiwan Strait concentration risk. |
Study Parameters
Coverage spans the United States, China, Germany, India, and South Korea, with primary inputs from each market cluster combining interviews with silicon design executives, carrier procurement directors, foundry operations managers, and verification engineering leads with secondary validation. Primary fieldwork draws from FCC equipment authorization databases, MIIT network access license filings, ENISA certification registries, and hyperscaler capex disclosures. Secondary sources include SEC 10-K filings, foundry capacity allocation reports, and telecom operator RFP documentation. Bottom-up unit shipment modeling triangulates against top-down semiconductor revenue aggregation.
Granularity-level modeling disaggregates volume and value outputs across product type, technology implementation, end user archetype, and application workload, with additional dimensioning by regional regulatory cluster and foundry process node. CAGRs derive from logistic adoption curve fitting for 5G standalone core deployment phases and edge computing latency requirement trajectories. Industry-specific forecast inputs include TRAI spectrum auction schedules, BSNL modernization timelines, and CHIPS Act funding disbursement trajectories.
Revisions become necessary when semiconductor equipment export control restrictions tighten, foundry capacity allocation shifts displace network silicon, or carrier procurement cycles extend beyond modeled qualification windows. Practitioners should monitor MIIT electromagnetic compatibility threshold adjustments, ENISA hardware security module mandate enforcement, and hyperscale internalization announcement velocity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Chips & Hardware
Wireless Transmitter Chip Market
Communication Chips & Hardware
Bluetooth Low Energy (BLE) Module Market
Communication Chips & Hardware
Nano GPS Chipset Market
Communication Chips & Hardware
GNSS Chip Market
Communication Chips & Hardware
VR Device Chips Market
Communication Chips & Hardware
APAC Semiconductor Device in Communication Industry Market
Communication Chips & Hardware
Smart TV Chip Market
Communication Chips & Hardware
5G PCB Market
Communication Chips & Hardware
Interface Transceiver Market
Communication Chips & Hardware
Jobsite Radios Market
Communication Chips & Hardware
Global Hybrid Fiber Coaxial Market
Communication Chips & Hardware
Gigabit Passive Optical Network (GPON) Chipset Market
Communication Chips & Hardware
Semiconductor Device in Communication Industry Market
Communication Chips & Hardware
4D Radar Chip Market
Communication Chips & Hardware
Mixed Signal System-On-Chip (Mxsoc) Market
Communication Chips & Hardware
Wi-Fi Adapter Card Market