
 Javelle Water Market | 2026-2036
Javelle Water Market Size, Share, and Industry Trends Forecast 2026-2036
Javelle Water Market Insights
REACH compliance is realigning the cost-of-entry calculus for European suppliers, forcing reformulation investments that favor established chlor-alkali producers. Solvay Chem leverages its integrated sodium hypochlorite supply chain to sustain margin advantages across industrial-grade segments. Olin Chlor Alkali anchors North American capacity through membrane-cell manufacturing scale, while Akzo Nobel competes on specialty bleach derivatives for healthcare applications.
Javelle water is an aqueous sodium hypochlorite solution typically containing 2.5–5% available chlorine, produced through chlorine gas absorption in chilled caustic soda and stabilized with sodium hydroxide to prevent decomposition. The formulation serves as a broad-spectrum oxidizing disinfectant across municipal water treatment, food sanitation, and surface decontamination protocols. Liquid Javelle Water dominates volume throughput due to established dosing infrastructure in municipal systems, while Powder Javelle Water captures growth in remote deployment scenarios where transport economics favor solid concentrates. Among end users, Hospitals and Food Processing represent the most defensible margin pools, driven by validated sterilization protocols and audit-intensive compliance requirements that resist commodity substitution.
EPA registration requirements govern disinfectant efficacy claims in the United States, while ECHA oversees substance evaluation and authorization under REACH in Europe, and India's BIS mandates packaging integrity standards for chlorine-based household products. These frameworks elevate testing burdens for new entrants while cementing incumbent positions through established dossier portfolios. Stakeholders must track evolving perchlorate limits and green chemistry procurement mandates, as these thresholds will determine which product grades retain commercial viability across regulated end-use channels.
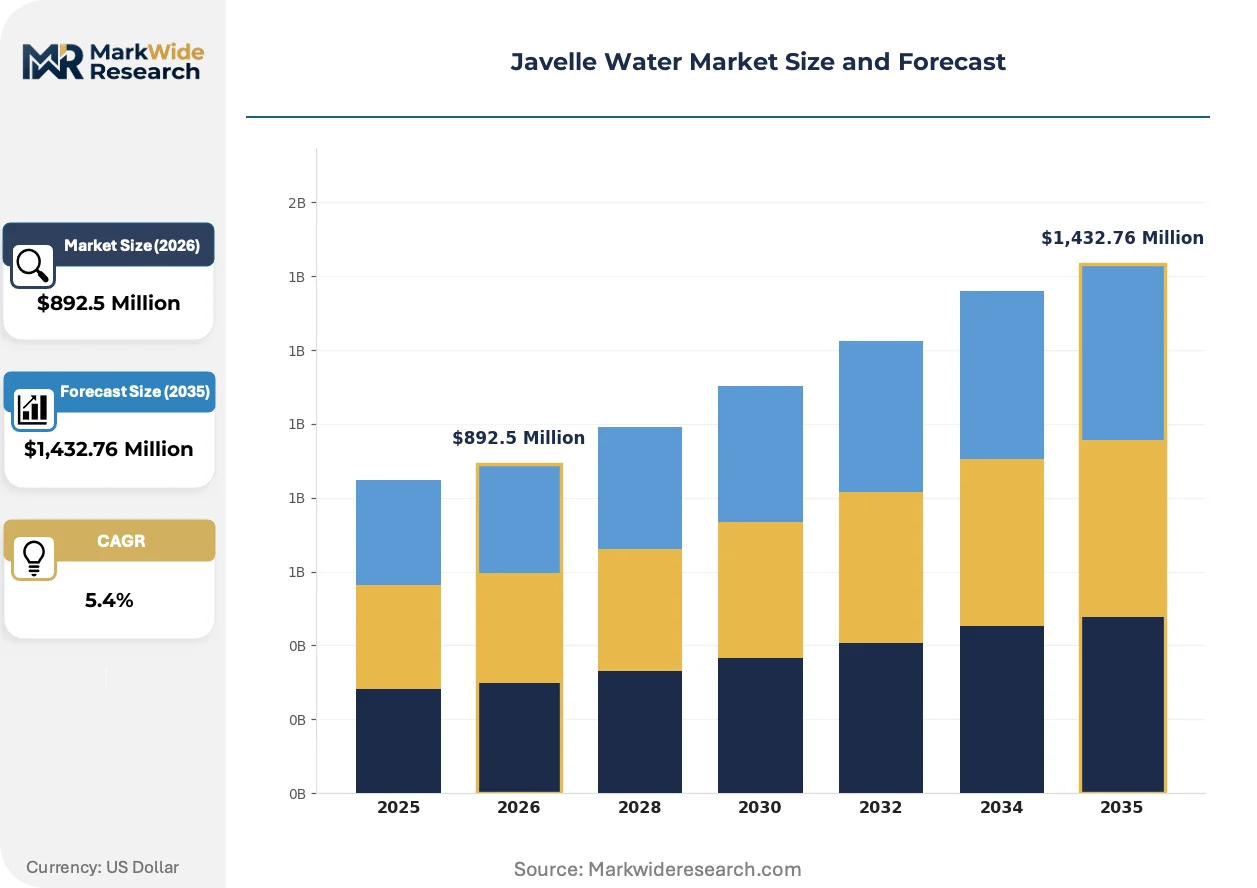
Market Dynamics
REACH compliance in Europe is tightening purity thresholds for chlorine-based disinfectants, forcing reformulation investments that favor established chlor-alkali producers with integrated sodium hypochlorite supply chains.
Growth Catalysts
- Food Processing Sterilization Protocols:Industrial-grade formulations are expanding procurement from equipment sterilization buyers seeking validated decontamination methods that resist commodity substitution.
- Germany's Chemical Corridor Concentration:Specialty bleach manufacturing clusters in Germany serve Central European industrial buyers with captive sodium hypochlorite capacity.
- REACH Purity Threshold Alignment:European suppliers achieving ECHA compliance dossiers cement incumbent positions through established authorization portfolios that elevate testing burdens for new entrants.
Market Restraints
- Caustic Soda Input Volatility:Sodium hydroxide stabilization requirements expose producers to chlor-alkali feedstock cost swings that compress formulation margins.
- Perchlorate Limit Tightening:Evolving EPA thresholds on chlorine byproducts threaten commercial viability of legacy product grades across regulated end-use channels.
- On-Site Electrolysis Substitution:Capital-rich municipal water systems are installing in-house hypochlorite generators that bypass packaged Javelle water procurement entirely.
Strategic Opportunities
- Remote Deployment Solid Concentrates:Powder Javelle Water captures growth scenarios where transport economics favor solid formulations over liquid bulk.
- India BIS Packaging Mandate Alignment:Chlorine-based household product integrity standards create compliant market entry for exporters meeting DGFT labeling requirements.
- Green Chemistry Procurement Mandates:EU Green Deal sustainable chemistry incentives favor low-carbon-footprint hypochlorite production methods in public tender specifications.
Industry Challenges
- Membrane-Cell Technical Certification:Validated sterilization protocols in healthcare applications require extensive dossier documentation that extends product launch timelines.
- Legacy Dosing Infrastructure Integration:Municipal water systems with established liquid dosing equipment resist retrofit costs for alternative disinfectant delivery mechanisms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Javelle Water Market |
| Market Size in 2026 | $892.5 Million |
| Market Size in 2035 | $1,432.76 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Javelle Water, Powder Javelle Water, Industrial Grade, Household Grade Application: Disinfection, Cleanliness, Sanitization, Waste Treatment End User: Households, Hospitals, Laboratories, Food Processing Packaging Type: Plastic Bottles, Bulk Drums, Sachets, Tetra Packs |
| Companies Covered | Solvay Chem, Akzo Nobel, Olin Chlor Alkali, Basf, Ineos, Arkema, Dow Chemical, Occidental Chemical, Salt Works, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Javelle Water Market Trends and Innovations
Stabilization chemistry and delivery-format innovation are reshaping competitive positioning across industrial and institutional disinfectant channels. Formulation advances and regulatory alignment now determine which product grades retain commercial access.
Electrolytic on-site generation technology is expanding into municipal water treatment facilities seeking to eliminate transport and storage liabilities associated with bulk hypochlorite delivery. Mid-sized utilities in the United States are piloting skid-mounted systems that produce sodium hypochlorite from salt and electricity at the point of use. This distributed production model is compressing demand for packaged industrial-grade Javelle water in metropolitan treatment plants while creating aftermarket service revenue streams for equipment suppliers.
REACH authorization requirements are forcing substance evaluation updates for chlorine-based disinfectants across European industrial supply chains. ECHA's tightening purity specifications demand enhanced analytical testing and documentation burdens that favor large chlor-alkali producers with dedicated regulatory affairs capacity. Specialty bleach derivatives for healthcare applications face the steepest compliance escalations as MDR overlaps with chemical substance frameworks.
Food processing audit intensity is compressing supplier qualification cycles and consolidating procurement toward validated sterilization protocol providers. Third-party certification requirements from SQF and BRCGS standards now mandate documented hypochlorite efficacy testing that smaller regional blenders cannot sustain. This credential-driven consolidation is most visible in Germany's meat and dairy processing corridors, where facility audits occur quarterly and non-compliant chemical inputs trigger immediate supply suspension.
Javelle Water Market Segmentation
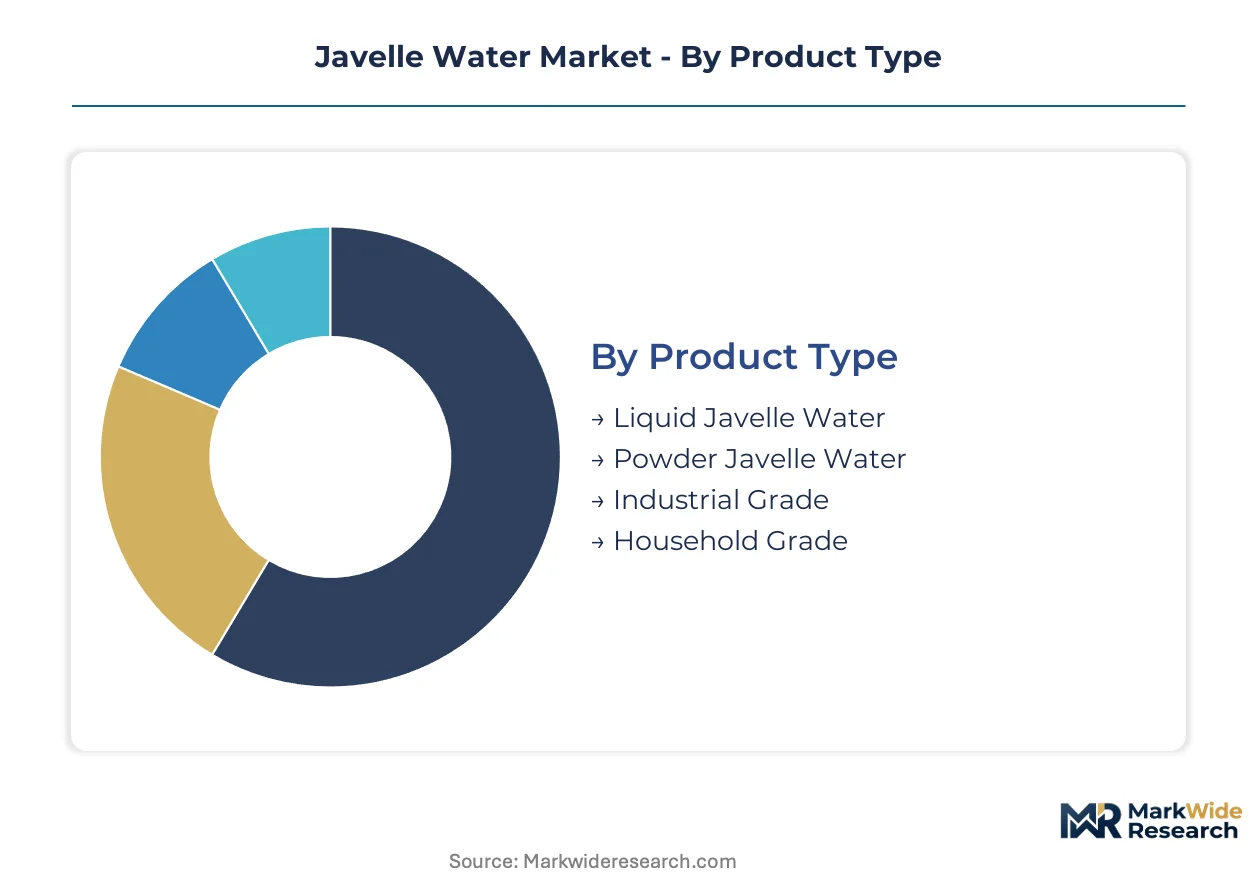
Segmentation in the Javelle water market determines which product grades access regulated end-use channels. EPA registration, REACH authorization, and BIS packaging mandates create tiered entry barriers that reshape competitive positioning across formulations and delivery formats.
Product Type:
Liquid Javelle Water carries EPA and ECHA registration burdens for disinfectant efficacy claims, while Powder Javelle Water faces additional stability testing requirements under transport classification rules. Industrial Grade formulations require OSHA process safety documentation for bulk handling protocols.
- Liquid Javelle Water:Aqueous sodium hypochlorite solution containing 2.5–5% available chlorine, stabilized with sodium hydroxide to prevent decomposition. Municipal water treatment systems in Germany's chemical corridor anchor procurement volume, though on-site electrolysis substitution threatens packaged demand in capital-rich utilities.
- Powder Javelle Water:Solid concentrate formulation enabling transport economics favoring remote deployment scenarios. India's BIS packaging integrity standards and DGFT labeling requirements create compliant export pathways for concentrated solid grades serving institutional buyers.
- Industrial Grade:Higher-concentration formulations for equipment sterilization protocols in food processing facilities. REACH purity thresholds and ECHA dossier requirements favor established chlor-alkali producers with integrated regulatory affairs capacity.
- Household Grade:Diluted consumer formulations for surface decontamination. India's BIS mandates govern chlorine-based product packaging integrity, while EPA registration governs efficacy claims in United States retail channels.
Leading the category by volume: Liquid Javelle Water. Expanding most quickly: Powder Javelle Water.
Application:
Application segmentation tracks where validated sterilization protocols resist commodity substitution versus where cost pressures dominate procurement decisions.
- Disinfection:Broad-spectrum oxidizing protocols across municipal water treatment and surface decontamination. EPA registration requirements in the United States and REACH authorization in Europe elevate testing burdens that cement incumbent positions through established dossier portfolios.
- Sanitization:Food processing audit-intensive applications requiring SQF and BRCGS third-party certification. Germany's meat and dairy processing corridors demand quarterly facility audits with immediate supply suspension for non-compliant chemical inputs.
- Cleanliness:General surface maintenance in institutional and commercial settings. Lower regulatory threshold permits regional blender participation, though green chemistry procurement mandates in EU public tenders favor low-carbon-footprint production methods.
- Waste Treatment:Industrial effluent and medical waste oxidation protocols. Evolving EPA perchlorate limits on chlorine byproducts threaten commercial viability of legacy product grades across regulated end-use channels.
Dominating procurement volume: Disinfection. Facing steepest compliance escalations: Sanitization.
End User:
End user segmentation separates audit-intensive institutional buyers from price-sensitive consumer markets, with margin concentration in validated protocol environments.
- Hospitals:Healthcare sterilization protocols overlapping MDR with chemical substance frameworks under REACH. Extensive dossier documentation requirements extend product launch timelines for membrane-cell technical certification.
- Food Processing:Equipment sterilization buyers seeking validated decontamination methods. Germany's specialty bleach manufacturing clusters serve Central European industrial buyers with captive sodium hypochlorite capacity.
- Laboratories:Research and diagnostic facility decontamination protocols. Moderate volume, high specification requirements favor specialty bleach derivatives from established chlor-alkali producers.
- Households:Consumer surface cleaning applications. India's BIS packaging mandates and United States EPA registration create dual-jurisdiction compliance burdens for multinational suppliers.
Capturing the most defensible margin pools: Hospitals and Food Processing. Most exposed to commodity substitution pressure: Households.
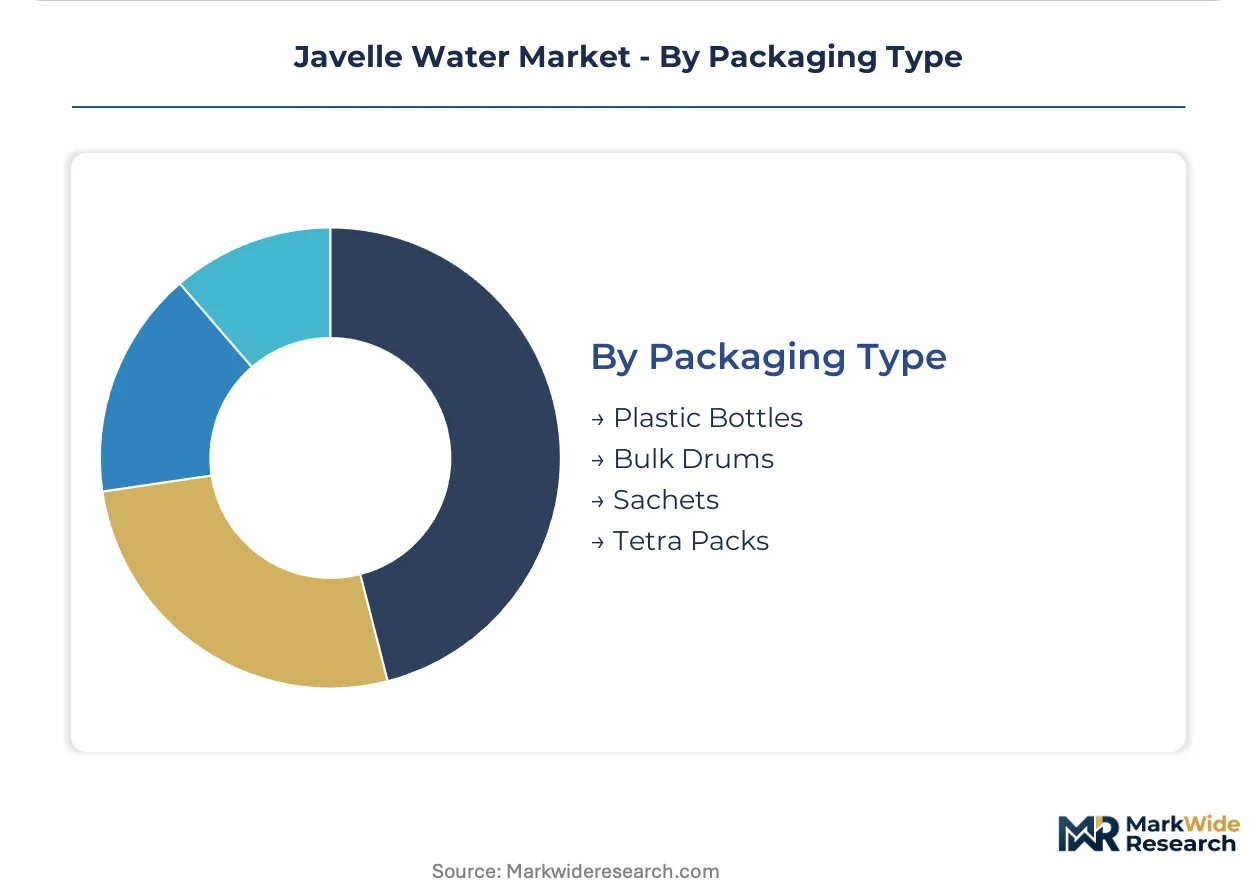
Packaging Type:
Packaging segmentation reflects transport economics, dosing infrastructure compatibility, and regulatory labeling mandates across distribution channels.
- Bulk Drums:Industrial-scale liquid delivery to municipal water treatment facilities with established dosing infrastructure. Legacy equipment integration resists retrofit costs for alternative disinfectant delivery mechanisms.
- Plastic Bottles:Standard retail and institutional packaging format. India's BIS mandates packaging integrity standards for chlorine-based household products, while REACH governs European industrial labeling.
- Sachets:Single-use solid concentrate packaging for remote deployment and emerging market distribution. DGFT labeling requirements in India create compliant market entry for exporters meeting BIS specifications.
- Tetra Packs:Alternative liquid containment with extended shelf stability claims. Limited penetration due to established infrastructure preference for conventional plastic bottle and drum formats.
Commanding institutional procurement: Bulk Drums. Gaining share in remote deployment: Sachets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for Javelle water concentrates in Germany's chemical corridor, where specialty bleach manufacturing clusters serve Central European industrial buyers with captive sodium hypochlorite capacity.
Germany
Food processing facilities in Bavaria and North Rhine-Westphalia drive procurement of industrial-grade formulations for equipment sterilization. REACH compliance through ECHA tightens purity thresholds for chlorine-based disinfectants. The Leverkusen-Dormagen chemical corridor anchors specialty bleach production serving meat and dairy processors across Central Europe.
United States
Municipal water treatment systems in Texas and California sustain bulk liquid procurement volumes. EPA registration requirements govern disinfectant efficacy claims for sodium hypochlorite solutions. The Gulf Coast chlor-alkali belt around Houston supplies membrane-cell sodium hypochlorite feedstock to municipal utilities nationwide.
India
Household-grade formulations expand distribution through sachet packaging for emerging market consumers. BIS mandates packaging integrity standards for chlorine-based products under DGFT labeling requirements. Maharashtra's chemical manufacturing zones around Mumbai produce concentrated solid grades for institutional export markets.
France
Healthcare sterilization protocols in Paris and Lyon medical centers sustain demand for validated hypochlorite derivatives. ANSM oversight overlaps with REACH substance evaluation for hospital-grade disinfectants. The Lyon chemical basin hosts specialty bleach production serving French and Swiss healthcare procurement networks.
China
Industrial effluent treatment facilities in the Yangtze River Delta deploy sodium hypochlorite oxidation protocols. MEE standards govern chlorine byproduct limits in wastewater discharge applications. Shanghai's chemical industrial parks supply concentrated formulations to municipal treatment plants across the eastern seaboard.
Javelle Water Market Competitive Landscape
European producers anchor one tier through integrated chlor-alkali operations; North American specialists hold capacity advantages through membrane-cell manufacturing scale. The market structures around three archetypes: integrated chemical majors with captive sodium hypochlorite supply chains, regional blenders serving institutional dosing infrastructure, and electrolytic equipment suppliers displacing packaged demand. Dominant competitive moves include backward integration into caustic soda feedstock and geographic expansion through REACH-compliant dossier portfolios.
Within the integrated chemical major tier, Solvay Chem and Akzo Nobel occupy positions sustained by regulatory affairs capacity. Olin Chlor Alkali exemplifies the North American scale-driven archetype. These three entities represent the competitive core around which regional blenders and equipment suppliers position for residual market access.
| Leading Market Players |
|---|
| Solvay Chem |
| Akzo Nobel |
| Olin Chlor Alkali |
| Basf |
| Ineos |
| Arkema |
| Dow Chemical |
| Occidental Chemical |
| Salt Works |
| Others |
Pricing and Supply Chain Analysis
On-site electrolysis technology is displacing packaged procurement in capital-rich municipal utilities, simultaneously compressing spot-market pricing power for liquid bulk suppliers while concentrating residual demand among audit-intensive institutional buyers willing to pay certification premiums. This production-method transition rewards backward-integrated chlor-alkali majors with captive sodium hypochlorite feedstock, while regional blenders face margin erosion from transport-cost disadvantages and dosing-infrastructure lock-in.
Pricing Analysis
Volume throughput concentrates in commodity-grade liquid bulk sold under long-term offtake contracts to municipal water systems, while margin pools accrue to specialty-grade formulations for healthcare and food processing applications bearing REACH dossier costs and third-party certification premiums. Price differentiation hinges on ECHA authorization status and SQF/BRCGS compliance documentation, with industrial-grade bleach derivatives commanding substantial premia over household formulations. Pricing pressure stems from on-site electrolysis substitution in metropolitan treatment plants, eroding spot-market liquidity for packaged bulk. Household-grade consumer segments exhibit highest price sensitivity, whereas hospital sterilization protocols resist substitution due to MDR-validated technical dossier requirements.
Supply Chain Analysis
Regional distribution centers in Germany's chemical corridor and the US Gulf Coast chlor-alkali belt anchor hub-and-spoke patterns serving Central European industrial buyers and North American municipal utilities respectively. Manufacturing concentrates in Germany, the United States, and India, with captive sodium hypochlorite capacity tethered to membrane-cell chlor-alkali operations. Raw material dependencies center on chlorine gas, caustic soda, and stabilized packaging substrates. Distribution runs through bulk drum logistics for institutional buyers and sachet-format retail channels for emerging-market households. Single-source vulnerability risks concentrate in caustic soda feedstock supply, with European producers exposed to energy-cost volatility in electrolysis operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around REACH-compliant dossier portfolios, with ECHA purity threshold tightening and food-processing audit intensity forcing sub-scale regional blenders toward exit or acquisition.
For Market Incumbents: Hedge against on-site electrolysis displacement by deepening captive sodium hypochlorite integration and securing long-term offtake agreements with audit-intensive food processing clusters in Germany's meat and dairy corridors. Prioritize ECHA authorization maintenance and MDR technical dossier updates for healthcare-grade derivatives to sustain margin premiums against commodity substitution pressure from capital-rich municipal utilities installing in-house generation capacity. For New Entrants and Emerging Players: Begin with powder concentrate export opportunities into India's institutional markets, where BIS packaging mandates and DGFT labeling requirements create compliant entry pathways for solid-formulation specialists lacking liquid dosing infrastructure relationships. Target remote deployment scenarios in emerging economies where transport economics favor concentrated solid grades over bulk liquid, leveraging sachet-format distribution partnerships with local chemical traders. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition of regional blenders possessing established SQF/BRCGS certifications but lacking capital for REACH dossier updates, with long-term viability hinging on backward integration into chlor-alkali feedstock or specialization in electrolytic equipment servicing. The signal to watch is EPA perchlorate limit tightening, which threatens commercial viability of legacy product grades and accelerates consolidation toward integrated producers with reformulation R&D capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Caustic Soda | Captive sodium hydroxide supply stabilizes formulation margins against chlor-alkali feedstock volatility. |
| REACH Dossier Portfolio Expansion | ECHA authorization maintenance cements incumbent positions in European industrial-grade segments. |
| On-Site Electrolysis Equipment Servicing | Aftermarket revenue streams capture value from municipal utilities bypassing packaged procurement. |
| Solid Concentrate Export Capacity | BIS-compliant sachet production enables compliant market entry into India's institutional channels. |
| Third-Party Certification Investment | SQF and BRCGS documentation sustains supplier qualification in Germany's audit-intensive food processing corridors. |
Research Methodology
Multi-period observation of EPA registration filings, ECHA authorization timelines, and municipal procurement contract awards anchored the trend analysis, supplemented by interviews with chlor-alkali plant managers, food processing procurement leads, hospital sterilization officers, and specialty bleach distribution channel partners. Secondary validation drew from customs trade data, SEC 10-K disclosures of listed chemical producers, Cefic sector reports, and BIS regulatory notifications. Bottom-up volume estimates triangulated against top-down chlor-alkali capacity utilization assessments across the analysis window.
Input-output matrices modeled demand drivers across product type, application protocol, end-user audit intensity, and regional regulatory cluster dimensions. CAGRs were derived from segmented growth rate differentials applied to base-period volume estimates, with cross-segment elasticity adjustments for on-site electrolysis substitution effects. Industry-specific forecast inputs incorporated REACH substance evaluation timelines and perchlorate limit evolution scenarios.
Underlying measurement precision varies by segment; hospital and food processing end-use channels carry tighter precision than household consumer markets due to documented procurement contract visibility. Forecasts reflect assumptions regarding regulatory timeline adherence and electrolysis technology adoption rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water and Wastewater Treatment
US Wastewater Secondary Treatment Equipment Market
Water and Wastewater Treatment
Global Wastewater Treatment Services Market
Water and Wastewater Treatment
Packaged Wastewater Treatment Market
Water and Wastewater Treatment
Zero Liquid Discharge (ZLD) Systems Market
Water and Wastewater Treatment
Global Vertical Sewage Pumps Market
Water and Wastewater Treatment
Global Smart Leak Detection Solutions for Water and Wastewater Industries Market
Water and Wastewater Treatment
Borehole Yield Testing Market
Water and Wastewater Treatment
Global Water Recycle and Reuse Market
Water and Wastewater Treatment
Global SCADA in Water and Wastewater Management Market
Water and Wastewater Treatment
United States Membrane Bioreactor (MBR) Market
Water and Wastewater Treatment
Global Biological Wastewater Treatment Market
Water and Wastewater Treatment
Global Enhanced Water Market
Water and Wastewater Treatment
Wastewater Screening Equipment Market
Water and Wastewater Treatment
Backwash Pre-Filters Market
Water and Wastewater Treatment
Global Water and Wastewater Treatment Equipment Market
Water and Wastewater Treatment
China Water and Wastewater Treatment (WWT) Technology Market