
 Global Liquid Filtration Market | 2026-2036
Global Liquid Filtration Market Size, Share, and Industry Trends Forecast 2026-2036
Global Liquid Filtration Market Intelligence
The rise of filtration-as-a-service models is fragmenting the competitive landscape, allowing smaller specialists to compete without large capital outlays for equipment. Pall Corporation leverages its extensive intellectual property in membrane science to dominate the biopharmaceutical segment. Pentair sustains a strong position through its broad portfolio targeting residential and commercial water purification applications. Entegris specializes in high-purity filtration solutions tailored for the demanding semiconductor industry.
Liquid filtration involves the physical or mechanical separation of suspended solids, contaminants, or particles from a fluid stream. This process utilizes porous media, such as membrane filters with precisely controlled pore sizes often measured in microns, to achieve desired purity levels. Membrane filters and reverse osmosis technology command significant value, particularly in high-stakes applications like pharmaceutical manufacturing. Cartridge filters see high-volume use in mature segments like municipal water purification and general chemical processing.
Regulatory frameworks from the US Food and Drug Administration (FDA) and the European Union's REACH directive dictate material safety and performance standards for filter media. In parallel, China's national GB standards for drinking water quality and industrial discharge are driving investment in advanced filtration systems. Future competitive advantage will depend on developing filtration media that meets tightening environmental mandates while simultaneously reducing operational energy consumption.
Market Dynamics
The liquid filtration market is defined by a structural tension between the demand for ultra-high purity in advanced industries and the need for cost-effective, high-volume solutions in mature sectors. This divergence compels suppliers to maintain distinct technology roadmaps and supply chains for segments like biopharmaceuticals versus municipal water treatment.
Growth Catalysts
- Stringent Regulations:China's national GB standards for drinking water quality and industrial wastewater discharge are mandating widespread upgrades to filtration infrastructure, benefiting membrane and cartridge filter suppliers.
- Pharmaceutical Expansion:Growth in global biopharmaceutical manufacturing requires advanced filtration for critical steps like sterile processing and Active Pharmaceutical Ingredient (API) purification, driving demand for validated, high-performance filters.
- Semiconductor Manufacturing:The production of advanced semiconductors necessitates ultrapure water, a requirement that is concentrating demand for reverse osmosis and ultrafiltration systems in electronics manufacturing hubs across Asia.
Market Restraints
- High Capital Costs:The construction of facilities for producing advanced membrane technologies, such as those used in reverse osmosis, requires significant capital investment, creating a high barrier to entry for new competitors.
- Membrane Fouling:The persistent issue of membrane fouling and biofouling reduces filtration efficiency, shortens media lifespan, and increases operational costs due to required cleaning cycles and premature replacement.
- Energy Consumption:Pressure-driven filtration processes, particularly reverse osmosis, are energy-intensive, posing a significant operational cost burden for end-users, especially in regions with high electricity prices.
Strategic Opportunities
- Filtration-as-a-Service (FaaS):The emergence of FaaS models, where customers pay for performance or volume rather than owning equipment, creates new revenue streams and lowers the adoption barrier for smaller industrial clients.
- Battery Material Production:The rapid expansion of electric vehicle battery manufacturing presents a new, large-scale application for specialized filtration to purify slurries and recover valuable materials during production.
- Material Science Innovation:Developing filter media with enhanced chemical resistance and lower energy requirements to meet tightening environmental mandates like the EU's REACH directive offers a path to competitive differentiation.
Industry Challenges
- Compliance and Certification:Navigating the complex and lengthy validation processes required by bodies like the US Food and Drug Administration (FDA) for filters used in pharmaceutical applications delays product launches and increases development costs.
- Energy Footprint Reduction:A primary operational challenge is reducing the significant energy consumption of high-pressure filtration systems without compromising purification performance, a key focus of R&D efforts.
- Lack of Pore Size Standardization:Inconsistent definitions and testing methodologies for nominal versus absolute pore size ratings across different manufacturers can lead to performance mismatches and procurement complexity for end-users.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Liquid Filtration Market |
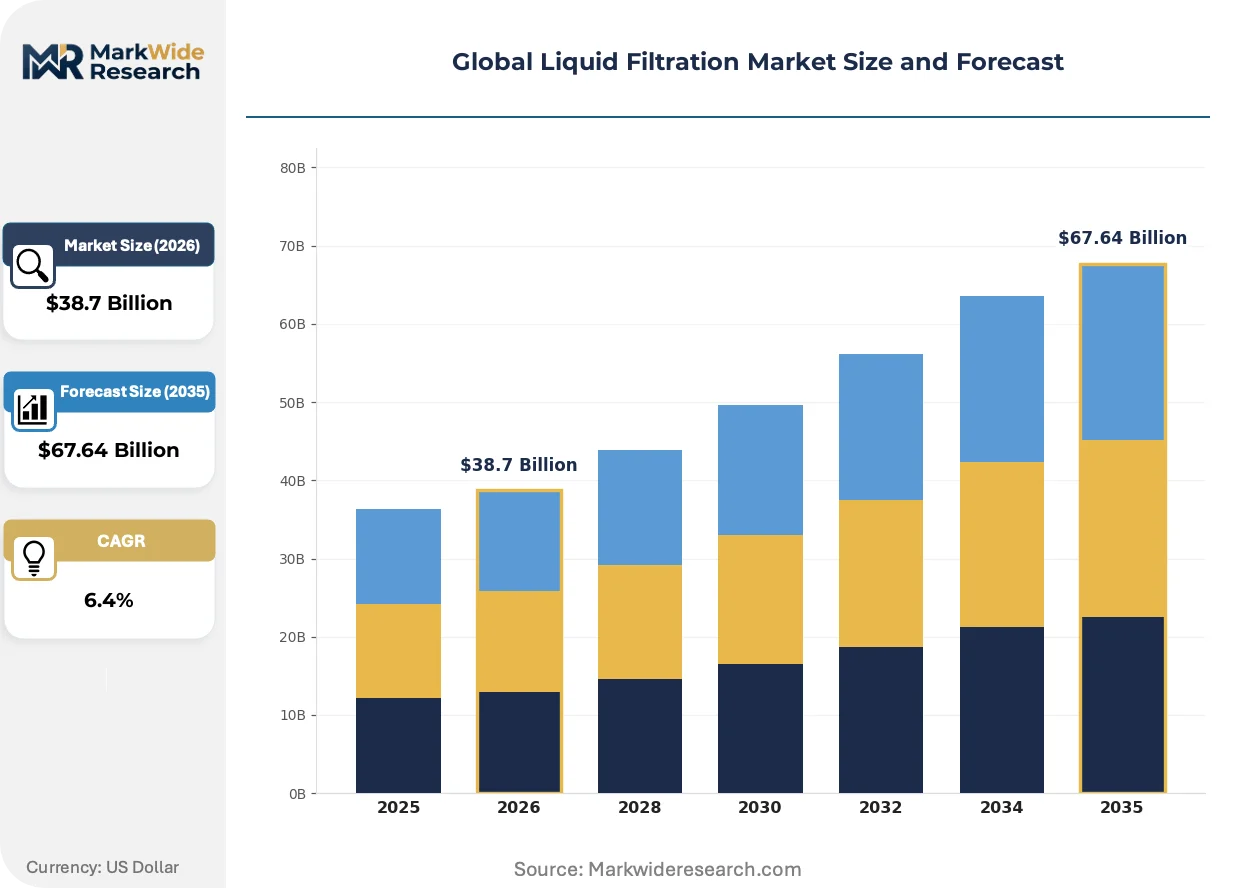
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $67.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Membrane Filters, Depth Filters, Screen Filters, Magnetic Filters, Cartridge Filters Technology: Microfiltration, Ultrafiltration, Nanofiltration, Reverse Osmosis, Adsorption Application: Food & Beverage, Pharmaceutical Manufacturing, Chemical Processing, Water Purification, Petrochemical Treatment End User: Consumer Goods Manufacturers, Municipal Water Plants, Oil & Gas E&P Operators, Power Generation Facilities, Metal Fabrication Plants |
| Companies Covered | Pentair, Toray Industries, Pall Corporation, Xylem, Evoqua Water Technologies, Entegris, 3M, Mann+Hummel, SUEZ, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Liquid Filtration Market Strategic Shifts & Innovations
The evolution of liquid filtration is centered on integrating digital intelligence with physical media to create systems that self-monitor and optimize performance. This shift transforms filtration components from passive consumables into active assets within a connected industrial ecosystem, enhancing reliability and reducing total cost of ownership.
Smart sensors embedded within filter systems provide real-time data on differential pressure, flow rates, and turbidity. Industrial operators in food and beverage and chemical processing are adopting this technology to enable predictive maintenance, moving away from fixed replacement schedules. This integration of IoT technology and data analytics is digitizing the historically mechanical process of filtration, turning components into intelligent network nodes that predict failure and optimize lifespan.
Regulatory actions from the US Environmental Protection Agency (EPA) concerning PFAS compounds in drinking water are creating new market imperatives. The establishment of enforceable Maximum Contaminant Levels compels municipal water authorities to invest in advanced treatment technologies. As a result, demand for specific media like granular activated carbon and high-rejection reverse osmosis membranes designed for PFAS removal is accelerating, especially in North America.
A transition from capital expenditure-heavy equipment sales to service-oriented contracts is altering commercial relationships. This model replaces large upfront purchases with ongoing operational agreements covering media supply, system maintenance, and performance guarantees, aligning supplier incentives with customer outcomes. This trend is most prominent within industrial water treatment and bioprocessing, where process uptime and consistent water quality are paramount business objectives.
Global Liquid Filtration Market Segmentation
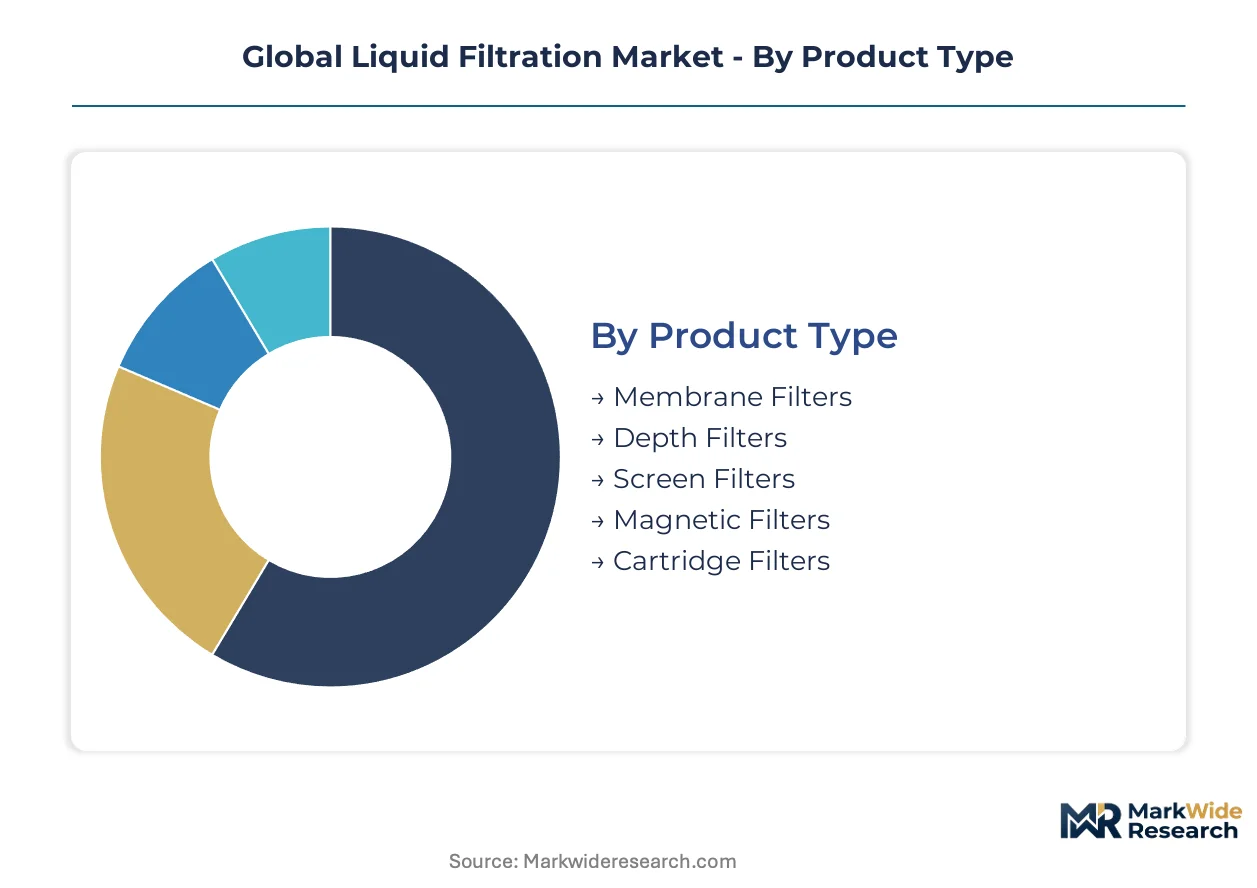
The liquid filtration market serves a broad spectrum of industrial and commercial requirements, from ultra-pure applications to high-volume contaminant removal. Effective segmentation clarifies the distinct technological demands and operational priorities across these varied end-use environments. This analysis delineates the market by product type, underlying technology, specific application, and primary end-user categories.
Product Type:
The product type segment showcases a mix of mature, high-volume consumables and advanced, specialized filtration media.
- Membrane Filters:Utilize thin, porous layers with precisely controlled pore sizes, often in the nanometer range, to achieve high-purity separations. Demand is concentrating in biopharmaceutical manufacturing for sterile processing and API purification, driven by stringent FDA guidelines.
- Cartridge Filters:Consist of disposable or cleanable media encased in a housing, offering versatile filtration across various micron ratings. Municipal water purification systems and general chemical processing facilities drive high-volume demand due to their cost-effectiveness and ease of replacement.
- Depth Filters:Employ a thick matrix of fibrous material to capture particles throughout the filter's depth, commonly used in pre-filtration stages.
- Screen Filters:Feature a single layer of woven or perforated material, primarily for removing larger suspended solids in irrigation and industrial water intake.
- Magnetic Filters:Remove ferrous particles from fluid streams using strong magnetic fields, finding use in cooling lubricants and hydraulic systems.
Cartridge Filters retain volume leadership; Membrane Filters hold the steepest expansion curve.
Technology:
The technologies employed in liquid filtration span a wide range of operational costs and purification capabilities, from basic separation to ultra-fine particle removal.
- Reverse Osmosis:Utilizes a semi-permeable membrane and high pressure to separate dissolved solids and ions from water, producing ultrapure water. Demand is concentrated in semiconductor manufacturing in Asia and desalination plants, driven by the critical need for high-purity water.
- Ultrafiltration:Employs membranes with pore sizes typically between 0.01 and 0.1 microns to remove suspended solids, bacteria, and viruses. Water purification and wastewater treatment facilities use ultrafiltration extensively, especially for pretreatment to reverse osmosis systems.
- Microfiltration:Separates particles and microorganisms larger than 0.1 microns from liquids, commonly used for clarifying beverages and sterilizing pharmaceutical ingredients.
- Nanofiltration:Operates between ultrafiltration and reverse osmosis, removing multivalent ions and larger organic molecules, applied in water softening and color removal.
- Adsorption:Relies on porous materials like activated carbon to attract and retain contaminants on their surface, crucial for taste, odor, and PFAS removal in drinking water.
Ultrapure water requirements drive the core demand for Reverse Osmosis, while Adsorption technologies are seeing renewed investment due to emerging contaminant regulations.
Application:
Liquid filtration applications range from essential public health services to highly specialized industrial processes, each demanding specific purity levels.
- Water Purification:Encompasses municipal drinking water treatment, industrial process water, and wastewater management, addressing diverse contaminant profiles. Stricter US EPA regulations on PFAS compounds are compelling significant investment in advanced water purification technologies.
- Pharmaceutical Manufacturing:Requires sterile and particle-free liquids for API production, sterile processing, and final product formulation, adhering to rigorous FDA standards. The expansion of global biopharmaceutical manufacturing directly fuels demand for validated, high-performance filters in this segment.
- Food & Beverage:Focuses on clarification, sterilization, and particle removal to ensure product quality and safety for beverages, dairy, and processed foods.
- Chemical Processing:Involves separating solids from liquids in chemical synthesis, product purification, and effluent treatment, often requiring chemically resistant filter media.
- Petrochemical Treatment:Addresses the filtration of crude oil, refined products, and process water in refineries and chemical plants, managing challenging operating conditions.
Public health mandates and biopharmaceutical innovation are the primary demand shapers in this segment, while industrial efficiency drives adoption in chemical and petrochemical sectors.
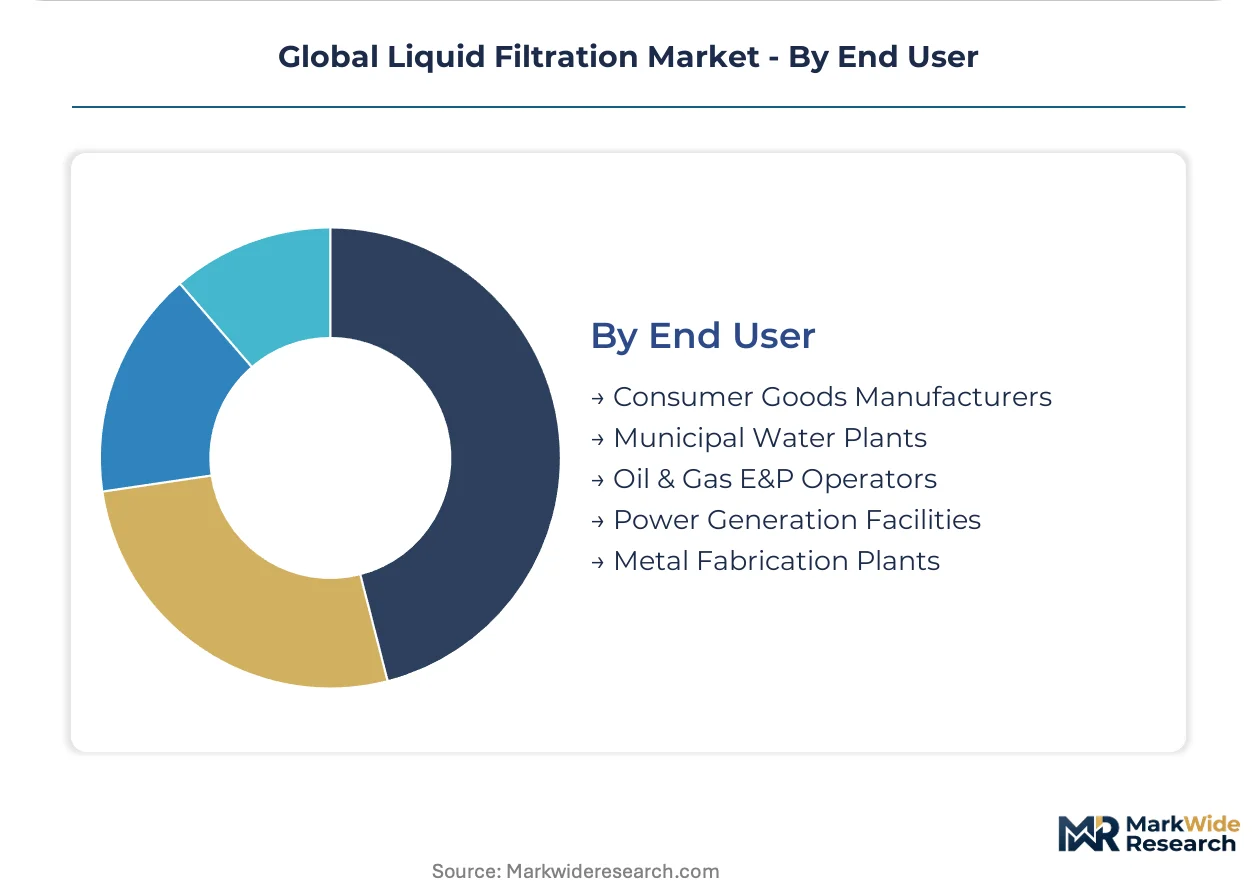
End User:
The end-user segment reveals distinct procurement patterns and operational scales, influencing supplier strategies and technology deployment.
- Municipal Water Plants:Responsible for treating public drinking water and wastewater, these facilities prioritize cost-effectiveness, reliability, and compliance with national standards. China's national GB standards for drinking water quality are mandating widespread upgrades to filtration infrastructure in this sector.
- Consumer Goods Manufacturers:Require filtration for product quality, ingredient purity, and wastewater discharge across diverse products from beverages to personal care items. Brand reputation and compliance with local environmental regulations are critical drivers for filtration investments in this end-user group.
- Oil & Gas E&P Operators:Utilize liquid filtration for produced water treatment, injection water quality, and fuel purification in exploration and production activities.
- Power Generation Facilities:Employ filtration for boiler feedwater, cooling tower makeup water, and wastewater discharge to maintain equipment efficiency and environmental compliance.
- Metal Fabrication Plants:Implement filtration for cutting fluids, wash water, and wastewater to improve process efficiency, extend fluid lifespan, and meet discharge limits.
Large-scale infrastructure projects define demand from Municipal Water Plants, whereas product quality and brand integrity drive filtration choices for Consumer Goods Manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global liquid filtration market exhibits a complex export-import balance, with certain nations driving technological innovation while others represent significant end-use consumption hubs. This dynamic shapes regional investment and regulatory priorities for advanced filtration systems. Specific countries lead in either manufacturing capacity or demand for purified liquids.
China
Demand for ultrapure water in China's semiconductor sector is substantial. China's national GB standards for drinking water and industrial discharge are compelling widespread infrastructure upgrades. Manufacturing hubs like the Yangtze River Delta are seeing concentrated investment in advanced filtration.
United States
Stricter environmental regulations drive significant investment in water treatment technologies across the United States. The US EPA's focus on PFAS compounds mandates advanced removal solutions for municipal water authorities. Major industrial clusters in Texas and California are upgrading systems for compliance.
Germany
Pharmaceutical manufacturing and high-tech industrial processes require advanced filtration in Germany. The EU's REACH directive influences material safety and performance standards for filter media. Production facilities in Bavaria and North Rhine-Westphalia integrate specialized filtration for biopharmaceutical and chemical applications.
Japan
Demand for high-purity water is critical for Japan's electronics and precision manufacturing industries. Japan's national water quality standards ensure consistent investment in filtration infrastructure. Industrial zones around Tokyo and Osaka are key centers for advanced membrane technology deployment.
India
India's expanding pharmaceutical sector requires advanced filtration for sterile processing and Active Pharmaceutical Ingredient (API) purification. The country's national drug regulatory body mandates high standards for manufacturing processes. Industrial clusters in Maharashtra and Gujarat are seeing increased demand for validated filtration solutions.
Global Liquid Filtration Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in the liquid filtration market. The competitive landscape is tiered, with larger entities offering comprehensive solutions and niche players focusing on specific media or applications. Strategic partnerships and targeted acquisitions are common competitive moves observed among market participants. Companies often expand portfolios to cover broader end-user requirements.
Specialists in high-performance filtration, such as Pall Corporation, exemplify market leadership in the biopharmaceutical segment through extensive intellectual property. Pentair occupies a strong position in residential and commercial water purification applications with its broad portfolio. Entegris, Inc., represents a key player specializing in high-purity filtration solutions for the demanding semiconductor industry. These companies anchor distinct segments of the global market.
| Leading Market Players |
|---|
| Pentair |
| Toray Industries |
| Pall Corporation |
| Xylem |
| Evoqua Water Technologies |
| Entegris |
| 3M |
| Mann+Hummel |
| SUEZ |
| Others |
Cost & Logistics Intelligence
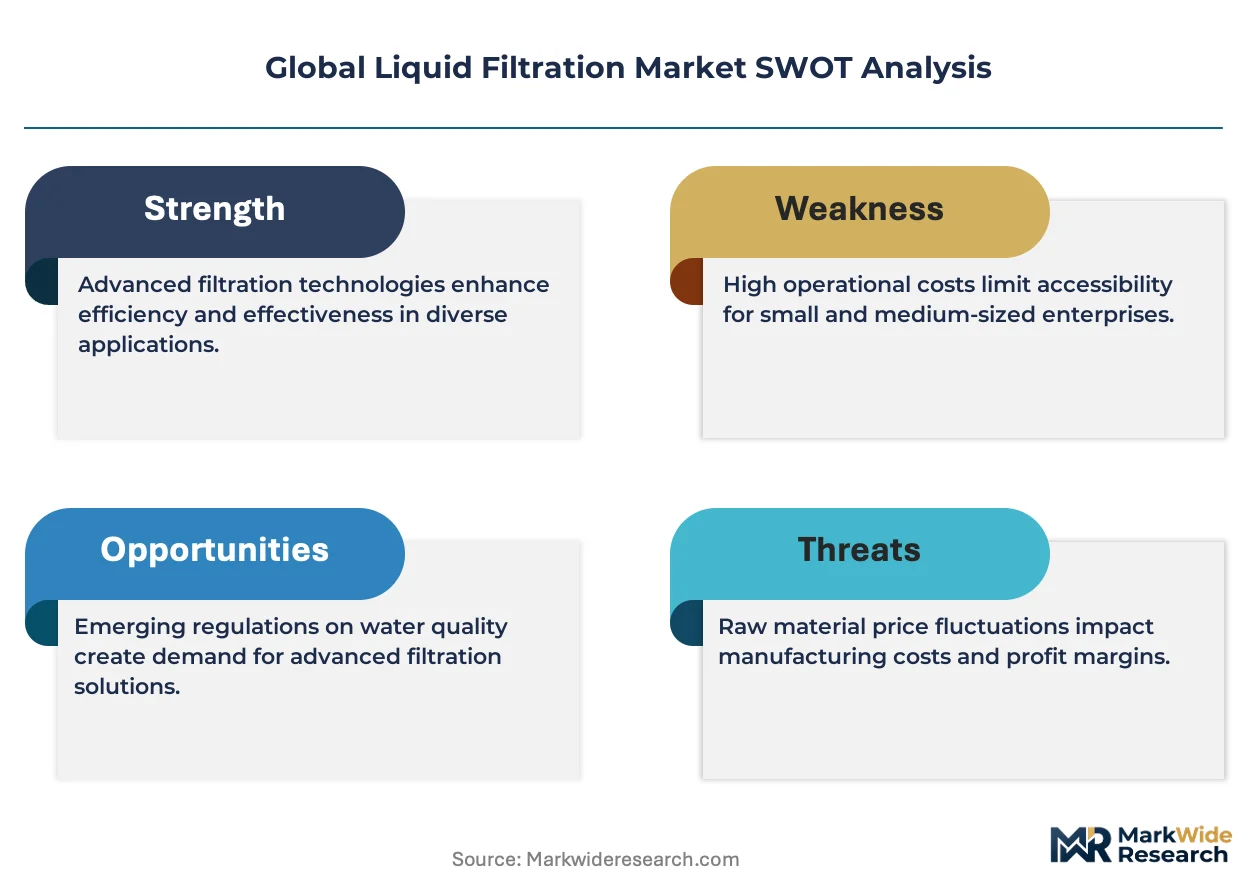
Raw material volatility for specialized polymers and membrane precursors determines both pricing tier spreads and supply chain shape for liquid filtration products. This volatility creates pressure points across the manufacturing process, influencing where production capacity is strategically located.
Pricing Analysis
Biopharmaceutical manufacturers anchor value-based pricing for high-performance liquid filtration systems. This model reflects the critical nature of sterile processing and API purification, where FDA certification level and customization level are primary differentiation drivers. Pricing softness runs through mature segments like municipal water purification due to commoditization of standard cartridge filters. Municipal water plants remain the most price-sensitive buyers, contrasting with the lower sensitivity of biopharmaceutical and semiconductor end-users.
Supply Chain Analysis
Export-control regimes on advanced manufacturing technologies limit the free flow of critical components, affecting supply chain resilience. Geographic supply concentrates in China for basic filter media and in Germany for advanced membrane technologies. The industry draws from specialized polymers and activated carbon as key raw material dependencies. Single-source vulnerability for specific high-purity membrane components presents a structural supply chain risk. Distribution runs through specialized distributors for advanced filtration solutions and broad industrial channels for commodity products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global liquid filtration market demands a substitution defense, as incumbents must navigate the threat of decentralized point-of-use purification systems. These systems offer alternatives to large-scale, centralized filtration infrastructure, potentially altering demand patterns.
For Market Incumbents: Build intellectual property moats through continuous investment in material science innovation for novel filter media. This strategy counters the persistent challenge of membrane fouling and extends product lifespan. Strategic acquisitions of niche technology providers with expertise in advanced separation techniques or digital integration capabilities can further solidify market position. Investing in R&D for advanced materials offers a critical lever against emerging contaminant challenges.
For New Entrants and Emerging Players: Pursue underserved market segments by offering flexible Filtration-as-a-Service (FaaS) models, particularly for smaller industrial clients. Focus on specialized applications like battery material production filtration, which requires unique purification solutions. A go-to-market angle emphasizing performance-based contracts and guaranteed operational uptime can differentiate offerings in competitive environments.
For Investors and Strategic Acquirers: The market sits at an early growth phase that favors specialized technology developers with proven intellectual property. Long-term viability remains strong, driven by tightening environmental regulations and the increasing demand for ultra-high purity in advanced industries. Target mid-cap specialists excelling in membrane science or advanced adsorption technologies. Regulatory updates on emerging contaminants, such as PFAS, serve as a key signal to watch for market inflection points.
| Strategic Initiative | Industry Significance |
|---|---|
| Material Science Innovation | Develops next-generation filter media with enhanced performance and longevity for industrial applications. |
| Digital Integration (IoT) | Enables real-time monitoring and predictive maintenance, optimizing system efficiency for end-users. |
| Regulatory Certification Investment | Ensures compliance with stringent standards like FDA and REACH, opening access to high-value segments. |
| Filtration-as-a-Service Expansion | Lowers capital expenditure barriers for customers, creating recurring revenue streams for providers. |
| Strategic Niche Acquisition | Expands technology portfolios and market reach into high-growth, specialized filtration applications. |
Research Approach
Cross-validation between primary interviews with industry stakeholders and extensive secondary validation anchors the qualitative findings of this study. The analysis involved conversations with R&D directors, plant engineers, procurement managers, and regulatory affairs specialists across the value chain. Secondary data sources included EPA reports, FDA guidelines, China's GB standards, and various industry association publications. Both bottom-up and top-down triangulation methods were employed to ensure data accuracy.
The analytical framework calibrated historical market data with current market dynamics across the analysis window. Segmentation dimensions modeled included product type, technology, application, end-user, and regional regulatory stringency. Compound annual growth rates were derived from historical growth patterns and projected future demand. Infrastructure investment cycles and technological advancements in material science served as key forecast inputs over the projection horizon.
Sensitivities concentrate around geopolitical events, rapid shifts in environmental policy, and unforeseen technological breakthroughs. Forecasts reflect assumptions regarding economic stability and regulatory enforcement. Material shifts in global trade agreements or public health crises would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Filters
Global Lamella Clarifier Market
Filters
Filters and Particle Monitoring Market
Filters
Global Gas Filtration Media Market
Filters
Filter Media Market
Filters
Aerospace Filter Market
Filters
Canada Filtration and Separation Market
Filters
Industrial Filter Paper Market
Filters
Fiberglass Filters Market
Filters
Adsorbent Market
Filters
Filter Bag Market
Filters
Global Cartridge Filters Market
Filters
Filter Paper Market
Filters
Furnace Filters Market
Filters
GCC Industrial Air Filtration Market
Filters
Europe Industrial Air Filtration Market
Filters
Filtering Centrifuges Market