
 Processed Eucheuma Seaweed Market | 2026-2036
Processed Eucheuma Seaweed Market Size, Share, and Industry Trends Forecast 2026-2036
Processed Eucheuma Seaweed Market Analytics
Plant-based food manufacturers are rotating toward marine-derived hydrocolloids as gelatin alternatives gain shelf space. CP Kelco leverages its Philippines supply base to secure consistent Kappaphycus alvarezii feedstock. Gelymar SA specializes in high-gel-strength carrageenan grades for dairy applications. Cargill Incorporated extends its hydrocolloid portfolio through integrated extraction capabilities in Southeast Asia.
Processed Eucheuma seaweed comprises dried, milled, or extracted biomass of Kappaphycus and Eucheuma species, yielding carrageenan fractions with gel strengths ranging from 500 to 2,000 g/cm² depending on sulfate content and cation type. The material functions primarily as a thermoreversible gelling agent, stabilizer, and thickener across formulated food systems. Extract-grade product commands the deepest margin pool due to downstream pharmaceutical and precision food applications, while whole seaweed remains the volume anchor for direct consumption and agricultural biostimulant markets. Powder formats are gaining fastest in cosmetic formulations where solubility and dispersibility determine formulation compatibility.
Indonesia's national standards body (BSN) enforces moisture and heavy-metal thresholds for exported seaweed, while the EU's REACH and F-Gas Regulation frameworks govern chemical processing aids used in European extraction facilities. The FDA's GRAS notification pathway shapes carrageenan acceptance in U.S. infant formula and nutritional beverages. Stakeholders must monitor evolving maximum residue limits for arsenic species in Codex Alimentarius deliberations, as these will determine which farming regions retain market access.
Market Dynamics
EU Green Deal sustainable sourcing mandates are restructuring import certification requirements for carrageenan hydrocolloids, forcing processors to revalidate supply chains against tightened heavy-metal and traceability standards.
Growth Catalysts
- Clean-label stabilizer demand:Food manufacturers are substituting synthetic hydrocolloids with Eucheuma-derived carrageenan in dairy and plant-based formulations. The FDA's GRAS notification pathway for infant formula applications accelerates this transition.
- EU F-Gas Regulation:Restrictions on synthetic refrigerants and processing aids in European extraction facilities favor seaweed-derived alternatives with lower chemical processing intensity.
- Indonesian farming cooperatives:Smallholder Kappaphycus alvarezii production in Sulawesi and Bali provides scalable biomass volumes with expanding organic certification coverage.
Market Restraints
- Arsenic species variability:Inorganic arsenic levels in Eucheuma cottonii from specific Philippine coastal zones trigger automatic EU border rejections under evolving Codex Alimentarius maximum residue limits.
- Input cost volatility:Diesel prices for inter-island biomass transport in Indonesia fluctuate with global crude benchmarks, compressing farmgate margins during price spikes.
- Substitution threat:Locust bean gum and tara gum from South American seed sources compete in low-gel-strength dairy applications where cost sensitivity dominates formulation decisions.
Strategic Opportunities
- Pharmaceutical-grade extraction:USP-grade carrageenan for vaccine adjuvant and cell-culture media applications commands 3-4x food-grade pricing with limited qualified suppliers.
- Cosmetic solubility formats:Cold-water dispersible seaweed powders for Korean and Japanese skincare formulations bypass traditional heat-hydration barriers in sheet-mask and serum production.
- EU CSRD alignment:Corporate sustainability reporting mandates create premium pricing tiers for traceable, cooperatively sourced biomass with documented carbon footprint data.
Industry Challenges
- Extraction chemist scarcity:Specialized knowledge of potassium hydroxide refinement and gel-strength optimization concentrates among aging technicians in Philippine processing facilities.
- Organic certification timelines:Three-year conversion periods for conventional seaweed farms in Indonesia delay access to premium EU and North American organic food channels.
- Legacy equipment retrofit costs:Batch extraction vessels in older Southeast Asian plants require stainless steel upgrades to meet pharmaceutical-grade material contact standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Processed Eucheuma Seaweed Market |
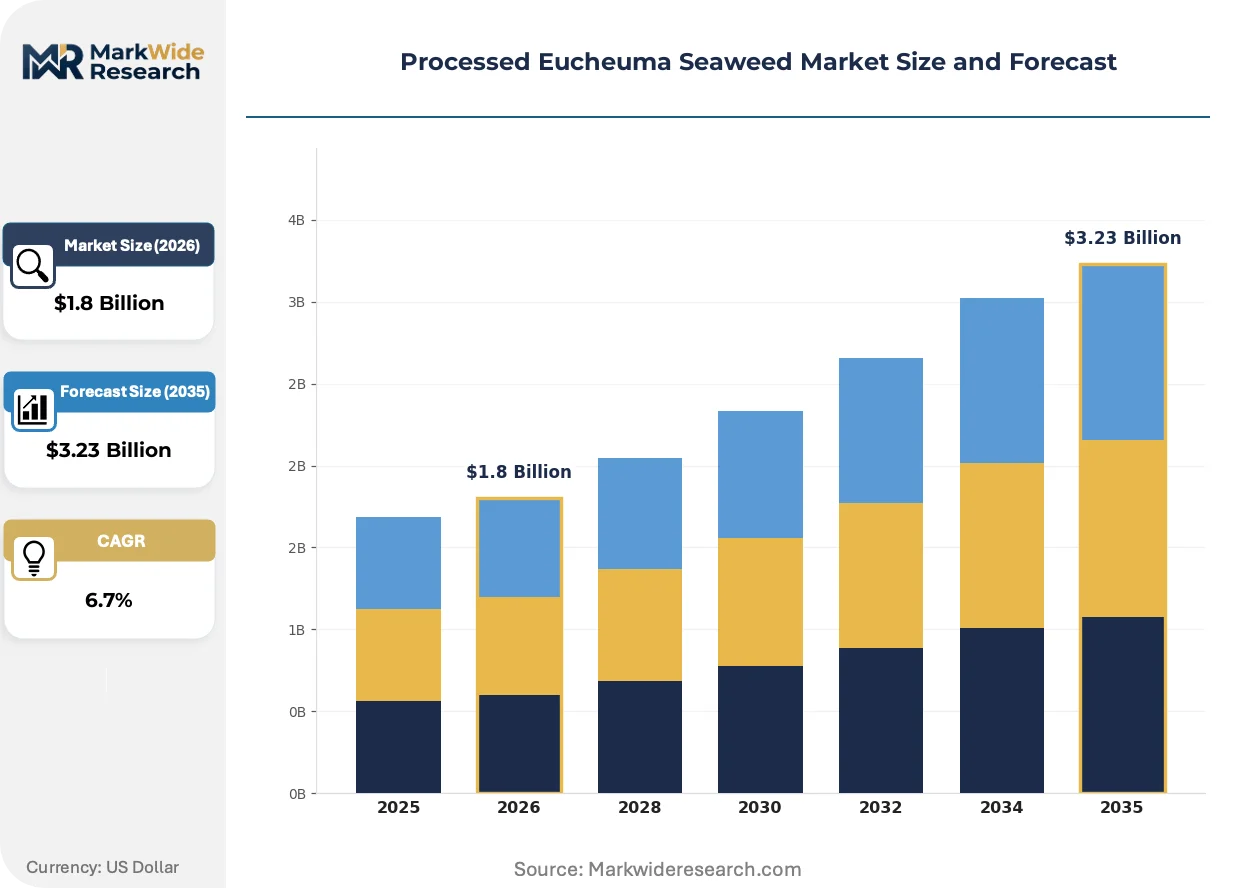
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Seaweed, Powder, Flakes, Extract Application: Food, Cosmetics, Pharmaceuticals, Agricultural Processing Method: Drying, Freeze-Drying, Extraction, Grading End User: Food Manufacturers, Cosmetic Companies, Pharmaceutical Firms, Research Institutions |
| Companies Covered | Gelymar SA, Algaia SA, CP Kelco, Seawin Biotech Group Co., Ltd., Ceamsa, Cargill Incorporated, KIMICA Corporation, Qingdao Gather Great Ocean Algae Industry Group Co., Ltd., DuPont de Nemours, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Processed Eucheuma Seaweed Market Evolving Landscape
Enzymatic extraction protocols and precision fermentation of seaweed polysaccharides are fragmenting traditional carrageenan production economics. These technologies promise cleaner label claims while threatening incumbent solvent-based processors.
Membrane filtration concentration systems are displacing conventional alcohol precipitation in premium carrageenan extraction. European dairy ingredient buyers are adopting these grades for organic yogurt stabilizers at 15-20% volume premiums. The shift is compressing margins for solvent-dependent processors unable to fund filtration capex.
REACH authorization requirements for chemical processing aids now cover potassium hydroxide and isopropanol used in European carrageenan facilities. German and Dutch extraction plants face reformulation costs or supply chain relocation to Southeast Asia. Pharmaceutical-grade producers are accelerating in-house solvent recovery investments to maintain EU market access.
Direct contracting between Indonesian farming cooperatives and end-use food manufacturers is shortening traditional trader-mediated supply chains. Large dairy processors in Germany and France now source traceable Kappaphycus biomass through cooperative partnerships rather than commodity brokers. This disintermediation is most advanced in organic-certified channels where provenance documentation commands price premiums.
Processed Eucheuma Seaweed Market Segmentation
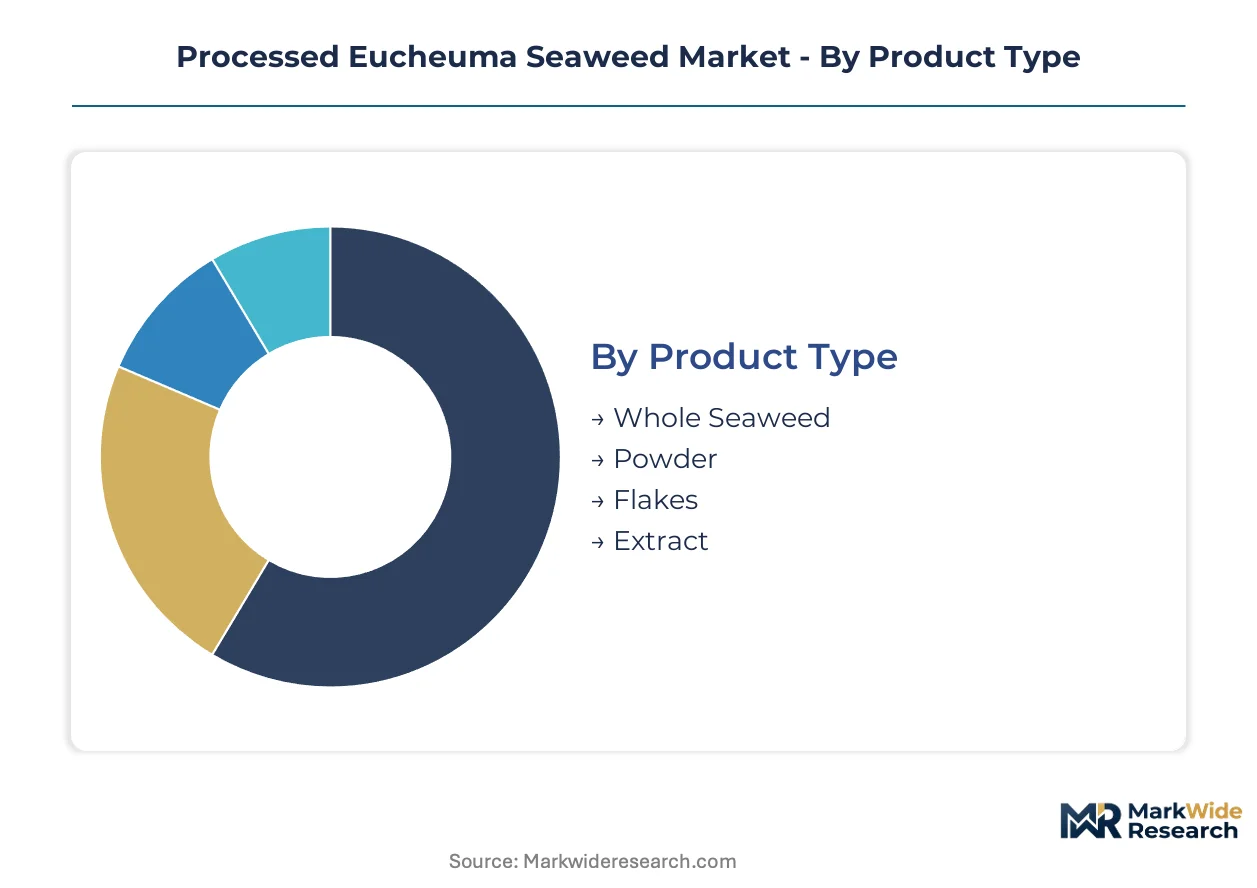
Processed Eucheuma seaweed markets fragment across extraction depth and formulation requirements. Carrageenan functionality varies sharply by product format, while regulatory thresholds for heavy metals and arsenic species reshape viable supply routes by end-use application.
Product Type:
Margin pools concentrate in refined extract grades where pharmaceutical and precision food applications command substantial premiums over commodity whole seaweed.
- Whole Seaweed:Sun-dried Kappaphycus alvarezii and Eucheuma cottonii biomass retains native polysaccharide structure for direct consumption and agricultural biostimulant markets. Indonesian farming cooperatives in Sulawesi supply the bulk of this volume anchor, though farmgate margins compress during diesel price spikes for inter-island transport.
- Extract:Refined carrageenan fractions with gel strengths from 500 to 2,000 g/cm² yield the deepest margin pool through downstream pharmaceutical and precision food applications. USP-grade material for vaccine adjuvants commands three to four times food-grade pricing with limited qualified suppliers.
- Powder:Cold-water dispersible formats are expanding most quickly in cosmetic formulations where solubility determines sheet-mask and serum compatibility.
- Flakes:Intermediate processing grade serves regional food manufacturers seeking visual seaweed identity in finished products.
The dominant share belongs to Whole Seaweed, while Extract is closing the gap fastest through pharmaceutical-grade qualification.
Application:
Cost tier stratification separates commodity food stabilizers from pharmaceutical-grade extract where qualification timelines protect incumbent margins.
- Food:Dairy and plant-based manufacturers substitute Eucheuma-derived carrageenan for synthetic hydrocolloids as clean-label stabilizers. The FDA's GRAS notification pathway for infant formula accelerates this transition.
- Pharmaceuticals:Vaccine adjuvant and cell-culture media applications require USP-grade material with documented heavy-metal and arsenic species compliance. Limited extraction chemist capacity in Philippine facilities constrains supply expansion.
- Cosmetics:Korean and Japanese skincare formulators drive demand for cold-water dispersible powders that bypass traditional heat-hydration barriers.
- Agricultural:Biostimulant applications utilize whole seaweed and lower-grade extracts where organic certification coverage from Indonesian cooperatives commands premium positioning.
Food retains the volume base, though Pharmaceuticals demonstrates the steepest expansion trajectory through adjuvant qualification.
Processing Method:
Supply concentration in Southeast Asian extraction facilities shapes method viability, with European REACH authorization costs favoring membrane filtration over solvent-dependent routes.
- Extraction:Potassium hydroxide refinement and alcohol precipitation yield food-grade and pharmaceutical-grade carrageenan fractions. German and Dutch plants face reformulation costs or relocation to Indonesia as REACH covers processing aids.
- Drying:Sun-drying dominates Indonesian smallholder operations, providing scalable biomass volumes with expanding organic certification coverage.
- Freeze-Drying:Premium cosmetic and pharmaceutical applications preserve native polysaccharide structure for maximum bioactivity retention.
- Grading:Gel-strength sorting separates commodity from specialty tiers, with high-gel-strength grades commanding dairy stabilizer premiums.
Extraction holds the value concentration, while Freeze-Drying is gaining share fastest in cosmetic-grade channels.
End User:
Customer type determines procurement structure, with direct cooperative contracting displacing trader mediation in organic-certified channels.
- Food Manufacturers:Large dairy processors in Germany and France now source traceable Kappaphycus biomass through Indonesian cooperative partnerships rather than commodity brokers.
- Pharmaceutical Firms:Vaccine producers require USP-grade carrageenan with batch-documented arsenic species compliance, creating qualification barriers for new suppliers.
- Cosmetic Companies:Korean and Japanese formulators prioritize cold-water dispersibility and solubility metrics over gel strength.
- Research Institutions:Cell-culture media developers source small-lot pharmaceutical-grade material for protocol validation.
Food Manufacturers anchor procurement volumes, while Pharmaceutical Firms are expanding fastest through adjuvant application qualification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesian farming cooperatives in Sulawesi and Bali ship dried Kappaphycus biomass to European dairy processors and Southeast Asian extraction facilities, forming the dominant trade-flow corridor in processed Eucheuma seaweed commerce.
Indonesia
Smallholder cooperatives in Sulawesi and Bali supply scalable Kappaphycus alvarezii volumes with expanding organic certification coverage. The national standards body enforces moisture and heavy-metal thresholds for exported seaweed. Extraction plants in Makassar process raw biomass into refined carrageenan fractions for pharmaceutical and food-grade channels.
Philippines
Eucheuma cottonii farming concentrates in coastal zones supplying both domestic processors and export markets. Inorganic arsenic variability in specific regions triggers automatic EU border rejections under evolving Codex Alimentarius maximum residue limits. Cebu-based extraction facilities specialize in high-gel-strength carrageenan grades for dairy stabilizer applications.
Germany
Large dairy processors in Bavaria and North Rhine-Westphalia source traceable Kappaphycus biomass through direct cooperative partnerships rather than commodity brokers. REACH authorization requirements for potassium hydroxide and isopropanol processing aids force reformulation costs or supply chain relocation. Membrane filtration concentration systems in Hamburg plants displace conventional alcohol precipitation for organic yogurt stabilizers.
France
Dairy ingredient buyers in the Île-de-France and Auvergne-Rhône-Alpes regions adopt membrane-filtered carrageenan grades at volume premiums for organic product lines. The EU Green Deal's sustainable sourcing mandates restructure import certification requirements for hydrocolloid procurement. Paris-based food manufacturers accelerate clean-label stabilizer substitution in plant-based formulations.
United States
Infant formula and nutritional beverage manufacturers drive FDA GRAS notification pathway utilization for carrageenan acceptance. Cosmetic formulators in New Jersey and California prioritize cold-water dispersible seaweed powders for skincare applications. Pharmaceutical firms source USP-grade material for vaccine adjuvant applications with limited qualified suppliers.
Processed Eucheuma Seaweed Market Competitive Landscape
Listed leaders compete with private specialists across extraction depth and certification tiers, creating a bifurcated structure where scale-driven processors vie with boutique qualification holders. The market fragments between solvent-dependent legacy operators and membrane filtration adopters. Three archetypes dominate: integrated agribusiness conglomerates with captive Southeast Asian supply bases, specialized carrageenan extractors with pharmaceutical-grade capabilities, and regional seaweed processors serving commodity food channels. Dominant competitive moves include backward integration into Indonesian farming cooperatives and in-house solvent recovery investments to maintain EU market access.
Within the integrated agribusiness tier, Cargill Incorporated and CP Kelco occupy positions anchored by Southeast Asian extraction capabilities and cooperative supply partnerships. Among specialized extractors, Gelymar SA exemplifies the high-gel-strength dairy application focus, while KIMICA Corporation represents Japanese pharmaceutical-grade qualification standards. These three entities collectively illustrate the competitive tension between scale-driven supply security and premium-tier certification depth.
| Leading Market Players |
|---|
| Gelymar SA |
| Algaia SA |
| CP Kelco |
| Seawin Biotech Group Co., Ltd. |
| Ceamsa |
| Cargill Incorporated |
| KIMICA Corporation |
| Qingdao Gather Great Ocean Algae Industry Group Co., Ltd. |
| DuPont de Nemours, Inc. |
| Others |
Value Network & Pricing Analysis
Capacity utilization at Indonesian extraction plants in Makassar and Cebu shapes both supply concentration and price floors for carrageenan hydrocolloids. Scale economies in membrane filtration systems create tiered entry barriers that compress margins for solvent-dependent processors while rewarding capital-intensive operators with durable pricing power.
Pricing Analysis
Membrane filtration generation equipment commands 15-20% volume premiums over solvent-based extraction grades in European organic dairy channels. Three-tier pricing structure across pharmaceutical-grade, food-grade, and agricultural-grade levels tracks certification depth and arsenic species compliance thresholds. Pricing pressure stems from locust bean gum substitution in low-gel-strength dairy applications where cost sensitivity dominates formulation decisions. Agricultural biostimulant buyers exhibit highest price sensitivity, while vaccine adjuvant procurement shows lowest elasticity due to USP-grade qualification barriers.
Supply Chain Analysis
Inter-island diesel transport between Sulawesi farming clusters and Makassar processing facilities creates a chokepoint that amplifies cost volatility during crude price spikes. Supply draws from Indonesia, the Philippines, and Vietnam, with raw Kappaphycus biomass resting on seaweed seedstock, potassium hydroxide reagents, and stainless steel equipment inputs. Single-source vulnerability concentrates in aging Philippine extraction chemist capacity. Distribution runs through direct cooperative contracting to German and French dairy processors, displacing traditional trader mediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward large dairy processors in Germany and France as direct cooperative contracting consolidates procurement leverage against fragmented trader networks.
For Market Incumbents: Shield pharmaceutical-grade margin pools through in-house solvent recovery investments that preserve EU REACH compliance without supply chain relocation. Accelerate backward integration into Indonesian organic-certified farming cooperatives to secure traceable biomass against Codex Alimentarius arsenic threshold tightening. Membrane filtration capex represents the critical defensive lever against solvent-dependent cost compression. For New Entrants and Emerging Players: Organic certification fast-track programs in Sulawesi and Bali cooperatives offer the most penetrable white-space entry point for premium EU and North American food channels. Target cold-water dispersible cosmetic powder formats for Korean and Japanese skincare formulators where solubility specifications bypass incumbent gel-strength optimization. Lead with enzymatic extraction protocols as a clean-label differentiation angle against legacy solvent processors. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among pharmaceutical-grade extraction specialists with USP qualification and documented heavy-metal compliance batch records. Long-term viability across the analysis window favors acquisition targets with captive Indonesian supply bases and membrane filtration capabilities. Watch for Codex Alimentarius maximum residue limit finalization as the inflection signal that determines which farming regions retain market access.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Farming Cooperatives | Direct Kappaphycus sourcing from Sulawesi cooperatives secures traceable biomass for EU CSRD alignment. |
| Membrane Filtration Capacity Expansion | Alcohol precipitation displacement captures organic yogurt stabilizer premiums in German dairy channels. |
| Pharmaceutical-Grade Qualification Investment | USP-grade carrageenan for vaccine adjuvants commands durable pricing multiples with limited supplier competition. |
| In-House Solvent Recovery Systems | Potassium hydroxide and isopropanol recovery preserves EU REACH market access against authorization costs. |
| Cosmetic Solubility Format Development | Cold-water dispersible powders bypass heat-hydration barriers in Korean sheet-mask production lines. |
Research Methodology
Desk research of customs trade databases, BSN export standards documentation, and REACH authorization filings preceded structured interviews with extraction plant managers, dairy procurement leads, Indonesian cooperative coordinators, and pharmaceutical quality assurance directors. Primary fieldwork across Sulawesi farming clusters and Cebu processing facilities combined with secondary validation from Codex Alimentarius deliberation records. Bottom-up biomass volume estimates and top-down hydrocolloid demand projections were triangulated to constrain forecast variance.
Variance decomposition across product type, application, processing method, and end user dimensions informed the analytical framework throughout the projection horizon. CAGRs were derived from segmented growth rate reconciliation against aggregate market expansion constraints. Key inputs included diesel price elasticity for inter-island transport, organic certification conversion timelines, and pharmaceutical-grade qualification success rates.
Decision-makers should treat outputs as directional under assumptions of stable Codex Alimentarius deliberation timelines and continued EU Green Deal implementation; material deviation in arsenic species thresholds or REACH authorization scope would warrant model refresh. Revision becomes warranted when inorganic arsenic limit proposals cross implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Africa Soup Market
Processed Foods
Pea Processed Ingredients Market
Processed Foods
Fat Free Soup Market
Processed Foods
Porridge Market
Processed Foods
Fat Free Food Market
Processed Foods
Sugar-Free Ice Cream Market
Processed Foods
Fruit Processing Market
Processed Foods
Instant Cooking Food Market
Processed Foods
US Processed Pumpkin Market
Processed Foods
Ready to Serve Prefabricated Dishes Market
Processed Foods
Europe Soup Market
Processed Foods
Coffee Creamer Market
Processed Foods
Global Take Out Fried Chicken Market
Processed Foods
Processed Fruit Bases Market
Processed Foods
Processed Vegetable Market
Processed Foods
Ready to Cook Market