
 Imitation Whipped Cream Market | 2026-2036
Imitation Whipped Cream Market Size, Share, and Industry Trends Forecast 2026-2036
Imitation Whipped Cream Market Analysis
ISO 22000 certification is rotating toward a baseline gating requirement for imitation whipped cream suppliers seeking entry into European and North American retail channels. Rich Products Corporation leverages its frozen dessert infrastructure to sustain broad foodservice coverage across multiple continents. Nestlé S.A. anchors its position through deep R&D investment in emulsion stability and fat-replacement chemistry. Arla Foods competes by extending its dairy expertise into hybrid formulations that blend vegetable fats with functional milk proteins.
Imitation whipped cream is a stabilized oil-in-water emulsion containing vegetable fats, sweeteners, emulsifiers, and hydrocolloids, typically whipped to overrun levels of 200-300% to replicate the texture of dairy whipped cream for dessert and beverage applications. The aerosol segment dominates retail convenience channels but faces margin compression from propellant cost volatility, while powder formats are gaining traction in emerging markets where cold-chain reliability remains limited. The foodservice distribution channel captures the largest value pool, as bakeries and cafes prioritize portion-controlled liquid and tub formats that reduce waste and labor time during peak service hours.
The FDA enforces identity standards of labeling for products marketed as cream substitutes, while the EMA and EFSA jointly influence emulsifier and additive approvals across European markets, directly constraining formulation choices for exporters. In Japan, METI-administered food sanitation laws govern vegetable fat content thresholds and labeling protocols for imitation dairy products. Stakeholders must monitor evolving trans-fat restrictions and clean-label emulsifier approvals, as regulatory divergence between major markets threatens to fragment formulation strategies and complicate cross-border manufacturing footprints.
Market Dynamics
Plant-based emulsion chemistry and trans-fat regulatory pressure are compressing formulation cycles while cold-chain reliability gaps in emerging markets force format diversification beyond aerosol cans.
Growth Catalysts
- ISO 22000 Certification Mandates:European and North American retail channels now gate entry on food safety management systems, pushing suppliers toward standardized hazard controls.
- Foodservice Channel Expansion:Bakery chains and quick-service restaurants in the United States, Germany, and Japan are scaling portion-controlled liquid formats to reduce labor time during peak hours.
- Clean-Label Emulsifier Approvals:EFSA's evolving stance on additive safety is opening formulation pathways previously blocked by methylcellulose and polysorbate restrictions.
Market Restraints
- Propellant Cost Volatility:Aerosol formats face margin compression from hydrocarbon propellant price swings tied to petrochemical feedstock markets.
- Trans-Fat Threshold Divergence:FDA labeling requirements clash with Japan METI-administered fat content rules, fragmenting cross-border manufacturing footprints.
- Cold-Chain Infrastructure Gaps:Emerging markets lack reliable refrigerated distribution, limiting liquid and tub format penetration outside urban clusters.
Strategic Opportunities
- Powder Format Penetration:Ambient-stable dry mixes address cold-chain gaps in Southeast Asian and Latin American foodservice channels.
- Hybrid Formulation Development:Blending vegetable fats with functional milk proteins captures consumers seeking dairy-adjacent taste without full dairy cost exposure.
- EU Green Deal Alignment:Sustainability-linked procurement criteria favor suppliers with verified carbon footprint reductions in emulsion processing.
Industry Challenges
- Emulsion Stability Expertise Scarcity:Fat-replacement chemistry and hydrocolloid optimization require specialized food science talent concentrated in Western Europe and Japan.
- Multi-Jurisdiction Labeling Compliance:Simultaneous adherence to FDA identity standards, EFSA additive approvals, and METI sanitation protocols extends product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Imitation Whipped Cream Market |
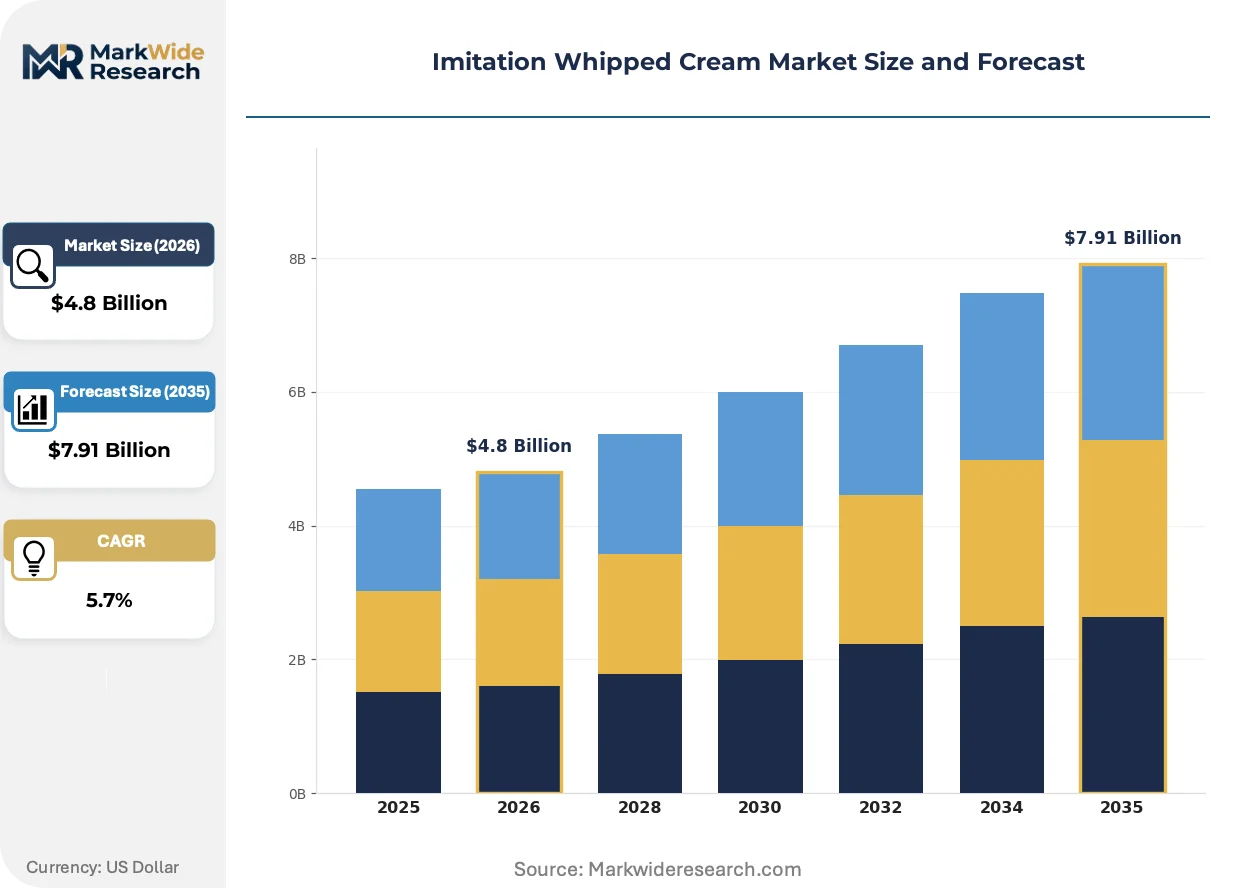
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aerosol, Liquid, Powder, Tub Application: Baking, Toppings, Desserts, Beverages Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Foodservice End User: Households, Restaurants, Cafes, Bakeries |
| Companies Covered | The Kraft Heinz Company, Rich Products Corporation, Nestlé S.A, Arla Foods, PURATOS, Hydrosol GmbH & Co. KG, Danone S.A., Eurocas Group of Companies, DuPont de Nemours, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Imitation Whipped Cream Market Emerging Trajectories
Clean-label hydrocolloid systems and propellant-free dispensing technologies are redrawing competitive boundaries while regulatory divergence between major markets forces parallel formulation tracks.
Advanced hydrocolloid stabilization systems using modified starch and plant-derived gums are fragmenting the traditional emulsifier landscape. Food manufacturers in Germany and Japan are adopting these systems at accelerated rates to preempt trans-fat restrictions. The shift is fragmenting supplier tiers as specialty ingredient houses capture share from commodity chemical distributors.
REACH-compliant emulsifier reauthorization timelines are compressing formulation windows across European manufacturing. ECHA's evolving hazard classifications for polysorbates and sorbitan esters are forcing R&D redirection toward bio-based alternatives. Powder format producers serving Eastern European markets face the steepest compliance cost escalations.
Direct-store-delivery models for foodservice liquid formats are displacing traditional broadline distributor relationships in urban United States markets. Bakery chains in California and Texas are consolidating supplier relationships to capture volume rebates and technical service bundling. The consolidation is most visible in metropolitan clusters where real estate costs favor just-in-time inventory systems over warehouse stocking.
Imitation Whipped Cream Market Segmentation
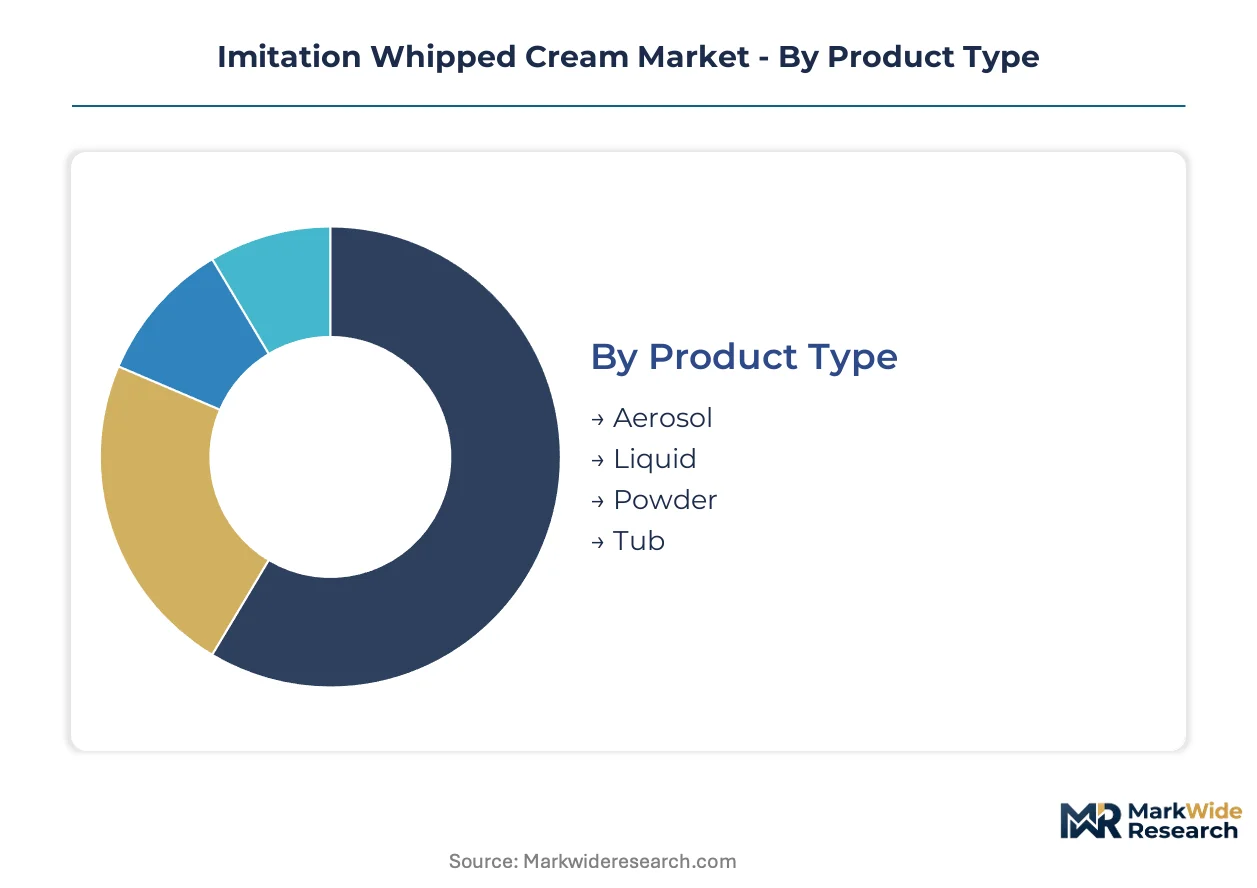
Format selection in imitation whipped cream determines cold-chain requirements, shelf stability, and channel economics. Product viscosity and overrun specifications vary sharply across retail convenience versus foodservice bulk applications.
Product Type:
Channel-mix dynamics favor aerosol and tub formats in retail, while liquid concentrates in foodservice procurement.
- Aerosol:Nitrous oxide or hydrocarbon-propelled cans deliver 250-300% overrun through pressurized dispensing. Demand clusters in United States and German supermarket channels where grab-and-go dessert preparation drives impulse purchases, though propellant cost volatility compresses margins.
- Liquid:Pourable emulsions in bag-in-box or bulk tote formats allow precise portion control for high-volume operators. United States bakery chains and Japanese cafe networks are consolidating procurement around refrigerated liquid to reduce labor time during peak service windows.
- Powder:Dehydrated mixes reconstitute with water or milk for ambient distribution. Southeast Asian and Latin American foodservice channels adopt powder where refrigerated infrastructure remains unreliable.
- Tub:Pre-whipped, frozen, or refrigerated bulk containers target institutional kitchens with consistent throughput needs. European retail discounters favor tub formats for private-label dessert topping lines.
Aerosol dominates installed base. Powder is where expansion concentrates.
Application:
End-use specifications drive fat-content thresholds and stability requirements across formulation tiers.
- Baking:Heat-stable emulsions with modified starch withstand oven temperatures without weeping or oil separation. German industrial bakeries specify these formulations for cream-filled pastries and layered cakes.
- Toppings:High-overrun, spoonable textures for pie and sundae applications. United States quick-service restaurants prioritize topping stability through freeze-thaw cycles.
- Desserts:Premium mouthfeel formulations with vegetable fat blends mimicking dairy cream richness. Japanese convenience stores stock dessert-format tubs for parfait and mousse applications.
- Beverages:Lower-viscosity emulsions that integrate into hot and cold drinks without feathering. Coffee shop chains in Germany and the United States are expanding beverage-format liquid procurement.
Baking commands volume share. Beverages is climbing the fastest.
Distribution Channel:
Margin structures and service requirements fragment supplier relationships across channel types.
- Supermarkets:Multi-SKU shelf sets with aerosol and tub formats dominate. United States and German retail buyers negotiate annual volume rebates with technical service bundling.
- Online Retail:Direct-to-consumer powder and shelf-stable liquid formats bypass cold-chain constraints. Urban Japanese households drive subscription replenishment models.
- Convenience Stores:Single-serve aerosol cans and small-format tubs for immediate consumption. United States petroleum retail chains stock seasonal dessert toppings.
- Foodservice:Broadline and direct-store-delivery models for liquid and bulk tub formats. Bakery chains in California and Texas consolidate supplier relationships to capture just-in-time inventory efficiencies.
Foodservice captures value concentration. Online retail is gaining share fastest.
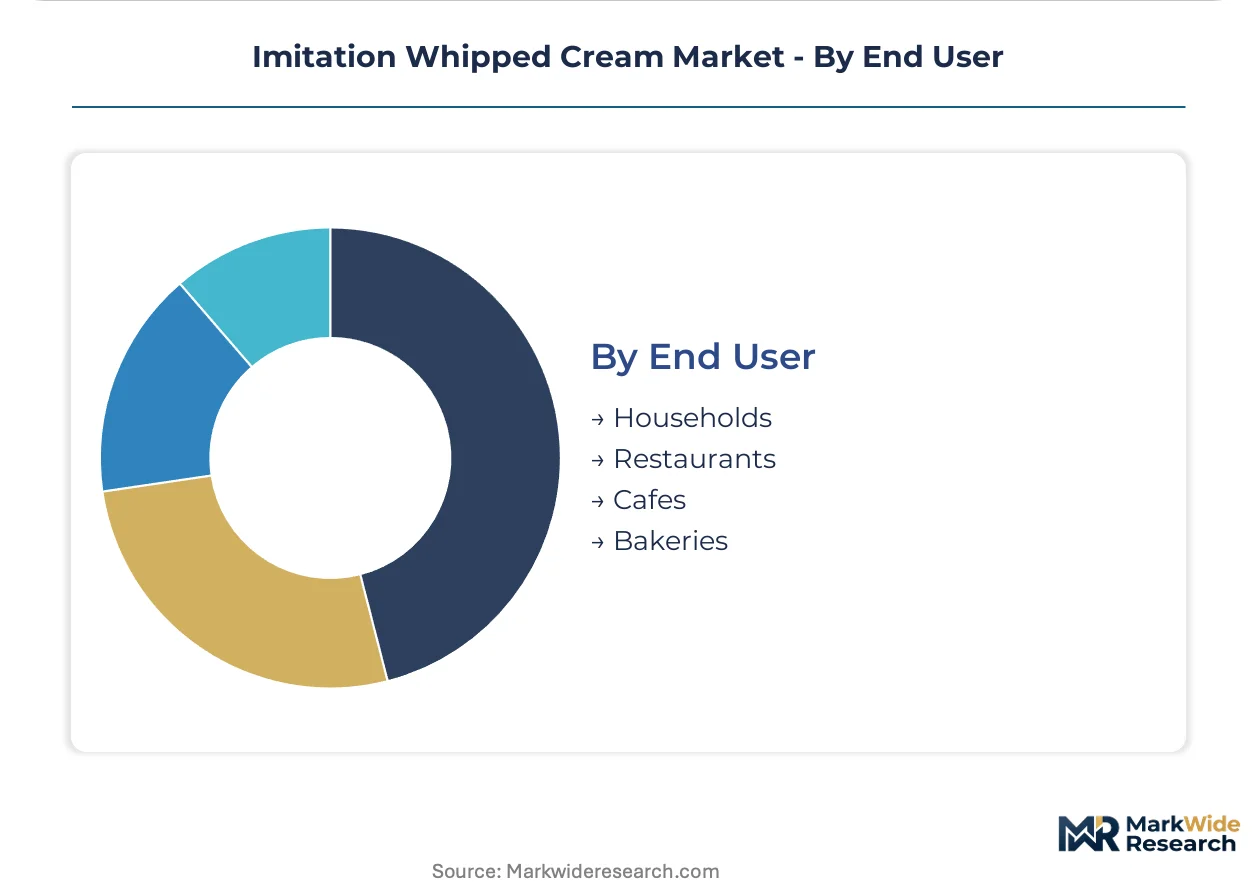
End User:
Volume scale and specification precision separate household from commercial procurement patterns.
- Households:Retail-format aerosol and small tub purchases for occasional dessert preparation. German and United States consumers show price sensitivity toward private-label alternatives.
- Restaurants:Portion-controlled liquid and reconstituted powder for plate finishing. Full-service operators in Japan specify METI-compliant labeling for menu transparency.
- Cafes:Beverage-integrated liquid formats with consistent foam stability. Specialty coffee chains in the United States test plant-based whipped alternatives for latte art applications.
- Bakeries:Bulk liquid and frozen tub formats with customized overrun specifications. Industrial bakeries in Germany demand ISO 22000 certification as a baseline gating requirement.
Bakeries anchor commercial demand. Cafes is where formulation innovation concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foodservice procurement managers in the United States, Germany, and Japan drive cross-regional demand for portion-controlled liquid formats and cost-stable dairy alternatives. Bakery chains and quick-service operators in these markets prioritize ISO 22000-certified suppliers to reduce supplier audit burdens.
United States
Bakery chains in California and Texas consolidate procurement around refrigerated liquid formats to capture just-in-time inventory efficiencies. FDA identity standards for cream substitutes constrain labeling claims and formulation choices for domestic manufacturers. Chicago and New York metropolitan clusters anchor foodservice distribution networks for aerosol and tub formats.
Germany
Industrial bakeries specify heat-stable emulsions with modified starch for cream-filled pastries and layered cakes. EFSA additive approvals and ECHA REACH compliance timelines compress formulation windows for exporters. Bavaria and North Rhine-Westphalia concentrate manufacturing capacity for private-label dessert topping lines.
Japan
Convenience stores stock dessert-format tubs for parfait and mousse applications in Kanto and Kansai regions. METI-administered food sanitation laws govern vegetable fat content thresholds and labeling protocols for imitation dairy products. Tokyo and Osaka metropolitan areas drive subscription replenishment models for direct-to-consumer powder formats.
United Kingdom
Retail discounters favor tub formats for private-label lines as consumers show price sensitivity toward dairy alternatives. EU Green Deal sustainability criteria influence procurement decisions for emulsion processing suppliers. Greater London and Midlands industrial bakeries demand ISO 22000 certification as baseline entry requirements.
Canada
Petroleum retail chains in Ontario and Quebec stock seasonal aerosol dessert toppings for immediate consumption. Health Canada labeling requirements align with FDA standards while maintaining distinct bilingual packaging mandates. Toronto and Vancouver urban clusters test plant-based whipped alternatives for specialty coffee applications.
Imitation Whipped Cream Market Vendor Landscape
Player mix skews toward diversified food conglomerates with frozen dessert infrastructure and specialized emulsion ingredient suppliers. Tier-one positions concentrate among North American and European firms with integrated R&D capabilities in fat-replacement chemistry. Three archetypes dominate: frozen dessert specialists leveraging cold-chain networks, dairy processors extending into hybrid formulations, and ingredient technology providers supplying hydrocolloid stabilization systems. Competitive moves center on direct-store-delivery model expansion and clean-label emulsifier portfolio diversification.
Within the diversified food conglomerate tier, Rich Products Corporation and Nestlé S.A. exemplify scale-driven positions anchored through frozen dessert infrastructure and emulsion stability expertise respectively. Arla Foods occupies a hybrid-formulation position blending dairy processing heritage with vegetable fat integration. Among specialized ingredient suppliers, Hydrosol GmbH & Co. KG represents the emulsion technology archetype focused on hydrocolloid and stabilizer systems. PURATOS and Eurocas Group of Companies sit within the European-centered supplier tier serving industrial bakery channels with customized overrun specifications.
| Leading Market Players |
|---|
| The Kraft Heinz Company |
| Rich Products Corporation |
| Nestlé S.A |
| Arla Foods |
| PURATOS |
| Hydrosol GmbH & Co. KG |
| Danone S.A. |
| Eurocas Group of Companies |
| DuPont de Nemours, Inc. |
| Others |
Supply Flow & Price Mechanics
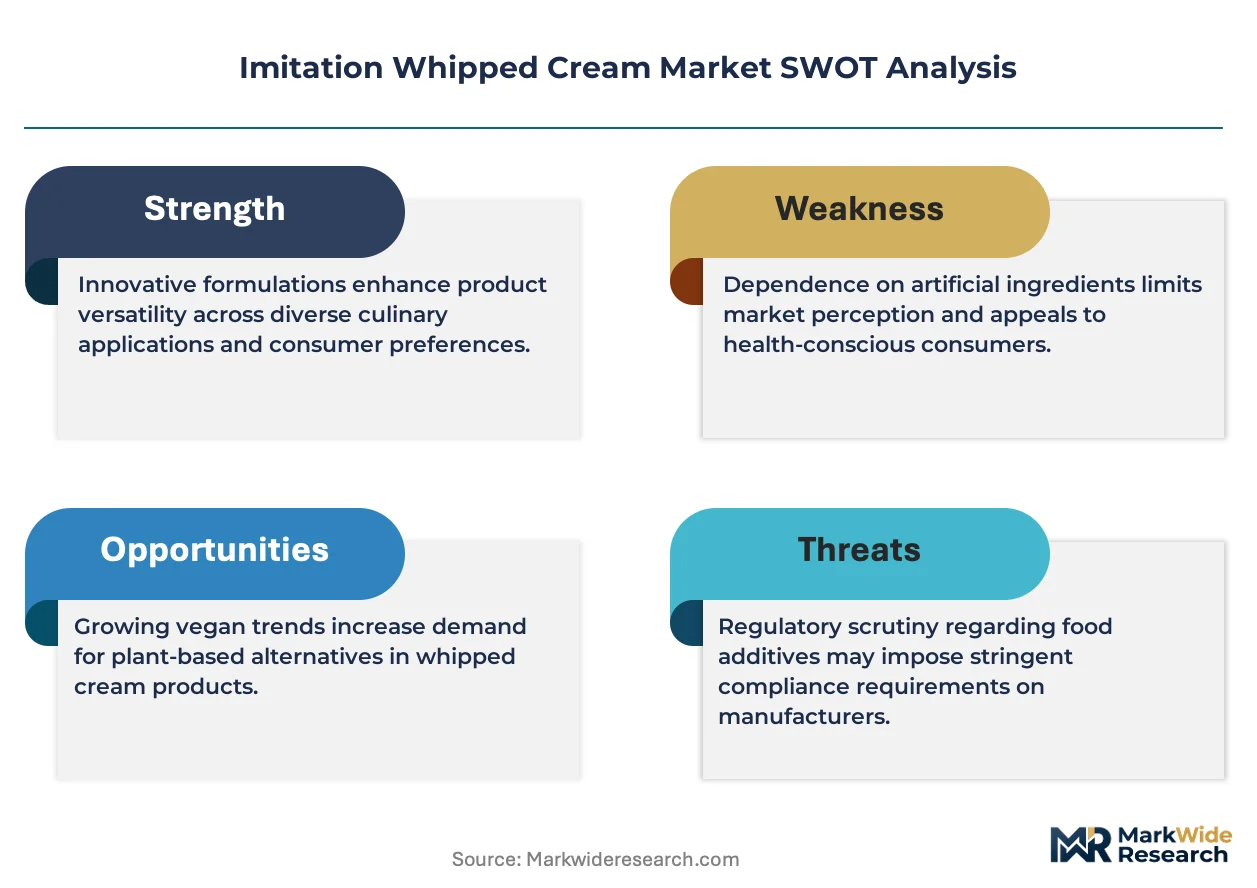
Vegetable fat substitution for dairy cream simultaneously redraws supply geography toward Southeast Asian palm oil processing hubs and compresses pricing power among aerosol format producers exposed to hydrocarbon propellant indexation. This dual restructuring forces buyers to arbitrage between cold-chain-dependent liquid premiums and ambient-stable powder discounts.
Pricing Analysis
Cost-plus contracts with palm kernel oil indexation dominate procurement agreements between United States bakery chains and emulsion suppliers. Three-tier pricing structure across ISO 22000-certified premium, standard foodservice, and private-label economy levels reflects certification investment and volume scale. Pricing pressure stems from propellant cost volatility in aerosol formats. Quick-service restaurants show highest price sensitivity, while Japanese convenience store operators absorb premiums for METI-compliant labeling.
Supply Chain Analysis
Just-in-time inventory strategies prevail among California and Texas bakery chains consolidating direct-store-delivery relationships, while Southeast Asian foodservice channels stockpile powder formats to bridge cold-chain gaps. Manufacturing concentrates in Germany, the United States, and Japan. Formulation draws from palm kernel oil, modified starch hydrocolloids, and nitrous oxide propellants. Single-source vulnerability sits with Malaysian and Indonesian palm oil supply. Distribution runs through broadline foodservice distributors and direct-store-delivery models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated United States bakery chains and quick-service restaurant procurement consortia, fragmenting supplier pricing leverage across format tiers.
For Market Incumbents: Consolidate direct-store-delivery coverage in metropolitan Texas and California clusters to defend against broadline distributor disintermediation. Deepen backward integration into palm oil fractionation to offset feedstock volatility. Lock in ISO 22000 certification moats before European retail channel mandates harden. For New Entrants and Emerging Players: Differentiate on clean-label hydrocolloid systems to bypass EFSA methylcellulose restrictions blocking incumbent reformulation. Target Southeast Asian powder format penetration where cold-chain gaps exclude refrigerated liquid competition. Pursue co-manufacturing partnerships with established emulsion houses to bypass capital-intensive aerosol canning infrastructure. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed frozen dessert specialists holding underoptimized emulsion R&D capabilities. Five-to-ten-year viability hinges on hybrid formulation patents bridging dairy and vegetable fat domains. Watch ECHA REACH reauthorization timelines for polysorbate restrictions as inflection signals for bio-based emulsifier acquisition targets.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Emulsifier Portfolio Diversification | EFSA additive approvals for plant-derived gums preempt regulatory blockage in German retail channels. |
| Direct-Store-Delivery Model Expansion | Just-in-time liquid distribution captures California bakery chain volume rebates from broadline distributors. |
| Powder Format Manufacturing Scale-Up | Ambient-stable production addresses cold-chain gaps in Southeast Asian foodservice procurement. |
| Hybrid Formulation R&D Investment | Functional milk protein integration captures consumers seeking dairy-adjacent taste at reduced cost exposure. |
| ISO 22000 Certification Acceleration | Food safety management systems gate European retail entry ahead of competitor compliance. |
Methodological Framework
A spread of perspectives from foodservice procurement managers, industrial bakery R&D directors, emulsion technology specialists, and retail category buyers converged on the working assumptions underlying volume and value estimates. Primary fieldwork combined structured interviews with ingredient supplier technical sales teams and food manufacturer formulation scientists. Secondary validation drew from FDA labeling guidance documents, EFSA additive safety opinions, METI food sanitation circulars, and customs trade data on vegetable fat imports. Bottom-up SKU-level modeling triangulated against top-down channel value assessments.
Segmentation dimensions modeled include product format, application stability requirements, distribution channel service intensity, and end-user procurement scale across the projection horizon. CAGRs derived from curve-fitting historical volume trajectories against regulatory milestone impacts and channel shift elasticities. Forecast inputs incorporated ECHA REACH reauthorization timelines and cold-chain infrastructure investment pipelines in emerging markets.
The analysis sits within stated boundaries; outcomes outside sustained palm oil price stability and EFSA clean-label additive approvals would require recalibration. Forecasts reflect documented assumptions on trans-fat threshold convergence and propellant cost normalization. Revision becomes warranted when regulatory divergence between FDA identity standards and METI fat content rules crosses fragmentation thresholds forcing parallel formulation tracks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Asia-Pacific Food Spread Market
Processed Foods
Pea Processed Ingredients Market
Processed Foods
Noodles Market
Processed Foods
Fat Free Soup Market
Processed Foods
Global Malted Milk Market
Processed Foods
Ready-To-Whip Toppings Market
Processed Foods
Artisanal Ice Cream Market
Processed Foods
United States Fresh Noodles Market
Processed Foods
Low Fat Chicken Soup Market
Processed Foods
Processed Potatoes Market
Processed Foods
Low Moisture Food Market
Processed Foods
United States Processed Meat Market
Processed Foods
Soup & Broth Market
Processed Foods
Low Calorie Rice Pudding Market
Processed Foods
Processed Vegetable Market
Processed Foods
Mashed Potatoes Market