
 Mashed Potatoes Market | 2026-2036
Mashed Potatoes Market Size, Share, and Industry Trends Forecast 2026-2036
Mashed Potatoes Market Outlook
Foodservice distribution is fragmenting as quick-service chains and institutional buyers split volume between national suppliers and regional co-packers. Idahoan Foods leverages its dehydrated potato expertise to dominate the instant-mix aisle across North American grocery channels. McCain Foods anchors its position through frozen-format scale and backward integration into potato sourcing. Unilever competes through brand equity in the premium chilled segment across European supermarkets.
Mashed potatoes consist of cooked, crushed, or whipped potato tubers blended with milk, butter, or emulsifiers to achieve a smooth, pumpable, or scoopable texture; industrial production employs steam-peeling, ricing, and vacuum-cooling to preserve starch integrity and extend shelf life. The product serves as a convenience side dish, an ingredient in prepared meals, and a base for reconstituted foodservice portions. Instant Mix leads volume in the Product Type category due to pantry-stockpiling behavior and minimal preparation requirements, though Organic commands the widest margin pool as retailers allocate premium shelf space. Frozen formats sustain growth in the End User segment among Restaurants and Food Chains seeking batch consistency and labor reduction, while Pouches outperform Bulk in Packaging Type for single-serve and on-the-go consumption occasions.
The FDA governs labeling and sodium content in the United States, while the EU Green Deal and Farm-to-Fork strategy push toward sustainable sourcing and reduced pesticide residues in European potato supply chains. EFSA nutritional claims regulation shapes how manufacturers communicate health benefits on front-of-pack labels. Stakeholders must monitor reformulation costs against clean-label premiums and decide whether to invest in regional processing assets or rely on centralized production with cold-chain extension.
Market Dynamics
Clean-label mandates across Germany, the United Kingdom, and the United States are forcing simultaneous sodium reduction and additive removal while manufacturers preserve texture and shelf stability in prepared potato formats.
Growth Catalysts
- EU Farm-to-Fork Strategy:The European Commission's pesticide reduction targets are accelerating investment in integrated pest management across potato sourcing regions, creating certified supply pools for clean-label product lines.
- Steam-peeling technology:Industrial steam-peeling systems reduce water consumption and preserve starch integrity better than abrasion methods, enabling longer shelf life without chemical preservatives.
- Foodservice labor compression:Quick-service chains in the United States are standardizing on frozen mashed potato formats to eliminate on-site preparation steps and reduce training overhead.
Market Restraints
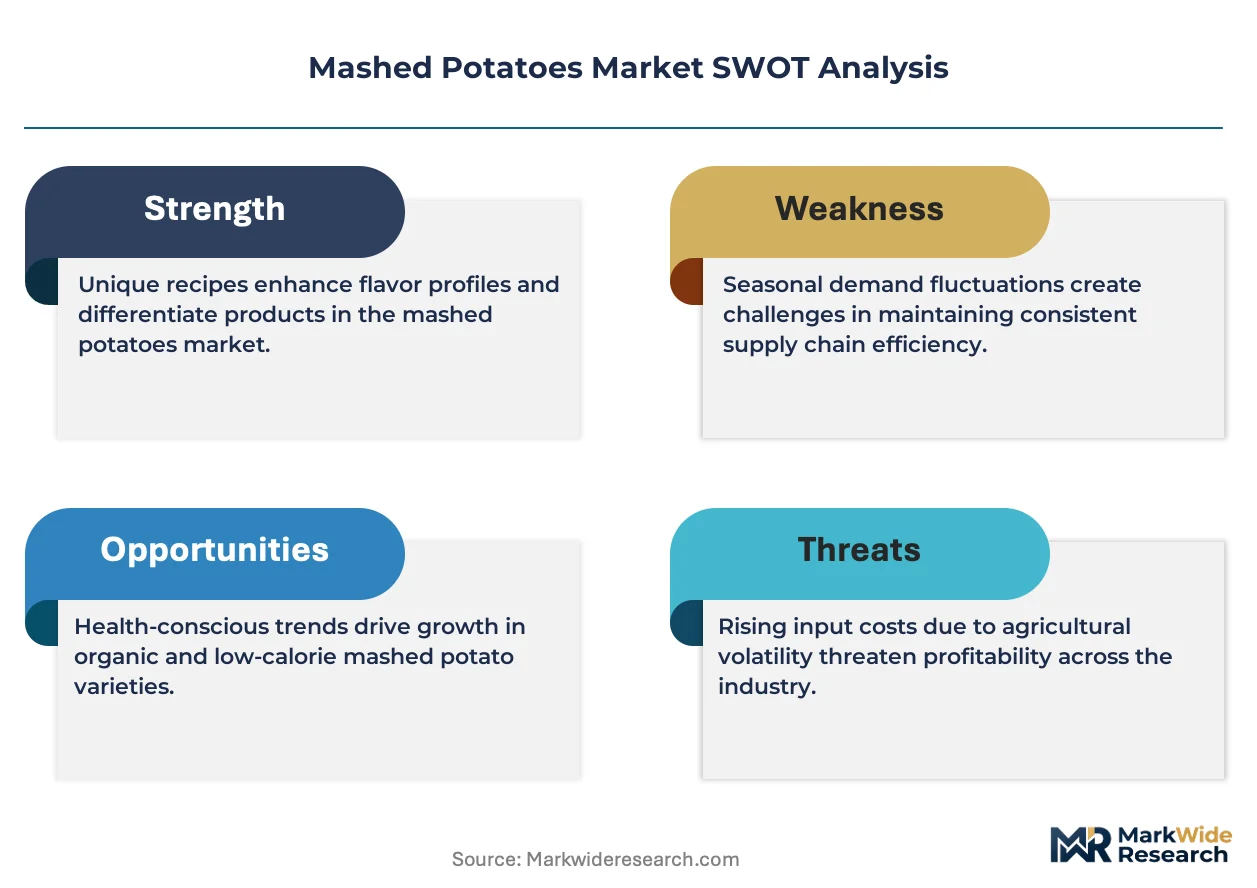
- Fresh potato price volatility:Weather-driven yield fluctuations in Idaho and the Pacific Northwest create input cost instability that squeezes margin pools in private-label contracts.
- Single-source dehydration capacity:North American instant-mix production concentrates among a handful of specialized processors, creating supply vulnerability during peak demand windows.
- Clean-label reformulation costs:EFSA nutritional claims regulation requires expensive sensory testing and label validation for reduced-sodium variants, raising barriers for mid-tier manufacturers.
Strategic Opportunities
- Pouch packaging expansion:Single-serve flexible pouches are capturing on-the-go consumption occasions in German commuter rail and UK meal-prep channels, displacing rigid trays.
- Organic certification premiums:USDA Organic and EU Organic labels command dedicated shelf space in premium retail tiers, with retailers absorbing higher procurement costs for differentiation.
- Chilled segment penetration:Refrigerated mashed potato formats remain underdeveloped in US grocery compared to frozen, creating white space for fresh-focused retailers.
Industry Challenges
- Starch retrogradation control:Maintaining smooth texture through freeze-thaw cycles without modified starches requires specialized process engineering that exceeds capabilities at smaller co-packing facilities.
- Dual certification timelines:Simultaneous USDA Organic and EU Organic approvals demand parallel documentation systems that extend product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mashed Potatoes Market |
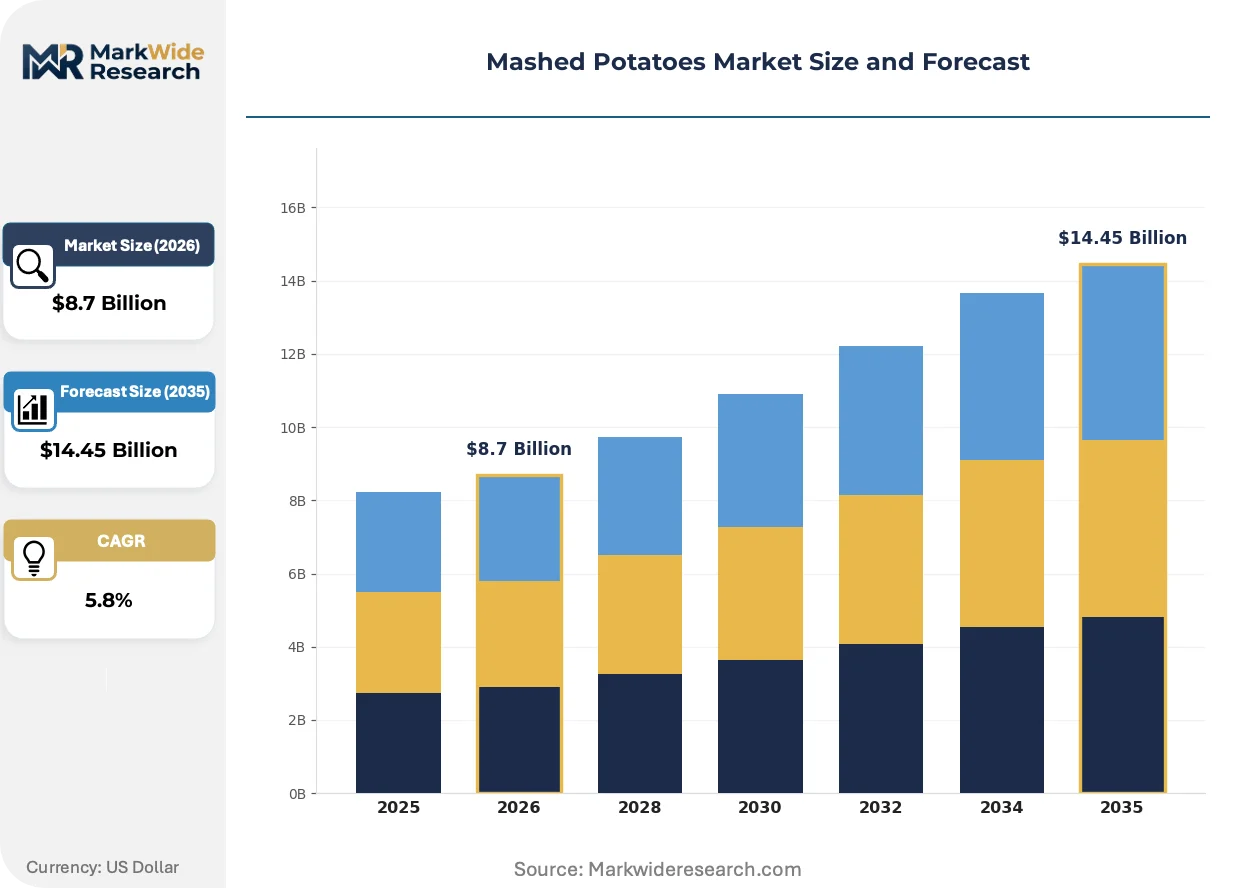
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instant Mix, Fresh, Frozen, Organic End User: Households, Restaurants, Catering Services, Food Chains Packaging Type: Bulk, Pouches, Cups, Sachets Distribution Channel: Supermarkets, Online Retailers, Convenience Stores, Specialty Stores |
| Companies Covered | Unilever, Agristo, Idahoan Foods, Hormel Foods, Post Holdings, McCain Foods, Pomuni, Branston, General Mills, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mashed Potatoes Market Strategic Shifts
Digital quality control systems and sustainable packaging formats are converging with reformulation science to redefine competitive advantage in prepared potato manufacturing.
Hyperspectral imaging systems for defect detection and starch quality assessment are virtualizing traditional manual inspection lines, enabling real-time sorting decisions without human intervention. Large-scale dehydration facilities in Idaho and the Pacific Northwest are adopting these systems fastest, compressing quality variability and reducing waste rates that previously required buffer inventory.
REACH restrictions on certain food-contact substances are compelling European manufacturers to validate alternative emulsifiers and packaging films, with ECHA substance evaluation driving substitution timelines. Frozen format producers serving EU foodservice channels face the steepest compliance curves, reformulating around phosphate-free texture modifiers ahead of 2027 evaluation deadlines.
Direct-to-operator procurement platforms are fragmenting traditional broadline distributor relationships, with institutional buyers in US healthcare and education sectors negotiating volume contracts through specialized foodservice technology vendors. This channel compression is most visible in the Midwest and Southeast, where regional hospital systems consolidate purchasing through group purchasing organizations that bypass legacy distribution tiers.
Mashed Potatoes Market Segmentation
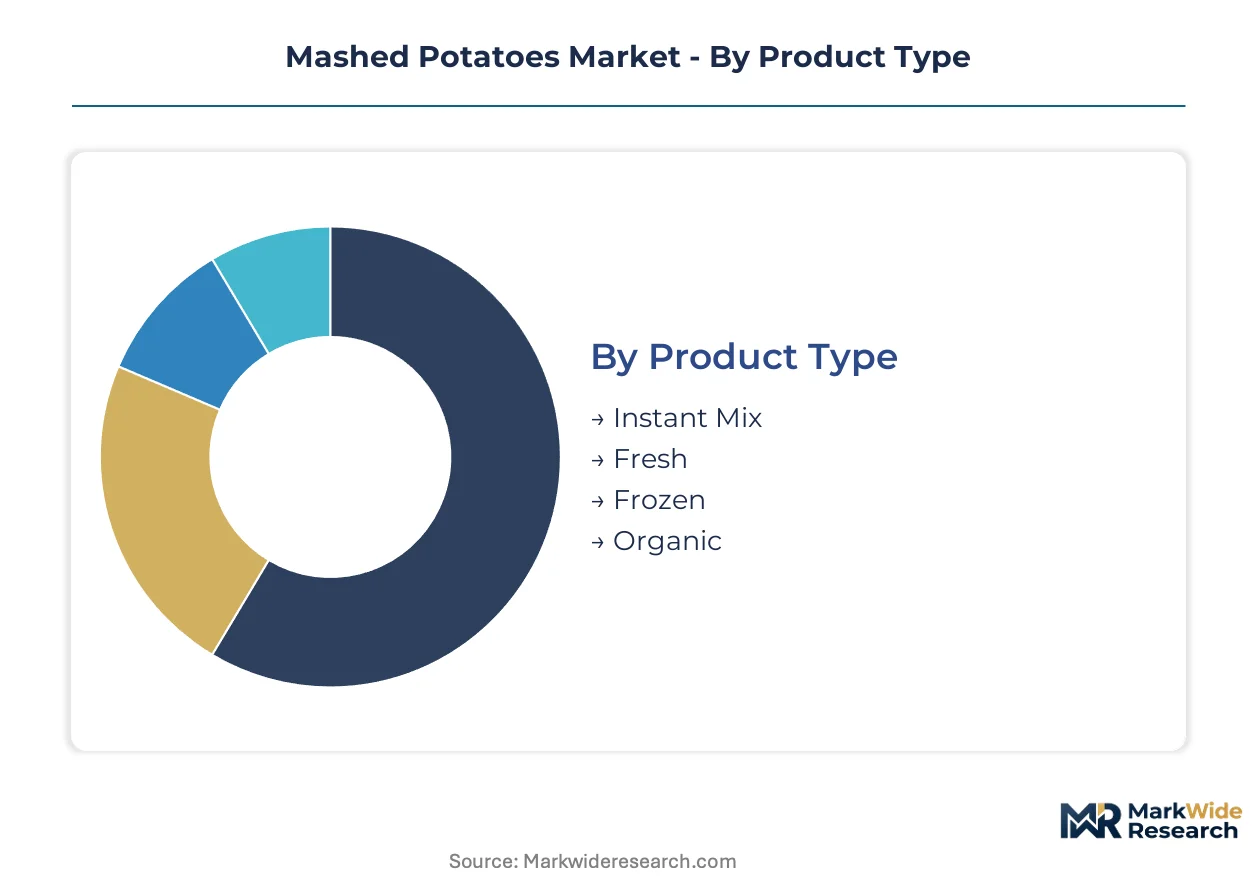
Segmentation in prepared potato products reveals divergent margin structures and inventory velocity patterns. Manufacturers must align production cycles with channel-specific turnover rates while managing formulation complexity across format tiers.
Product Type:
Inventory velocity varies dramatically across formats, with dehydrated products turning weekly in pantry channels while chilled organic lines move monthly through premium retail.
- Instant Mix:Dehydrated potato flakes and granules reconstitute with hot water or milk to deliver shelf-stable convenience. Pantry-stockpiling behavior in US and German households drives volume concentration, though sodium-reduction mandates are forcing reformulation investments that compress margins on standard variants.
- Frozen:Steam-peeled, riced, and rapid-chilled potato preparations maintain texture through freeze-thaw cycles. US quick-service chains and UK foodservice distributors absorb the bulk of frozen volume as labor compression eliminates on-site mashing operations.
- Fresh:Refrigerated mashed potatoes with minimal processing and shorter shelf life. Chilled distribution networks in France and Benelux support regional penetration.
- Organic:Certified potato sourcing with restricted pesticide inputs and additive-free recipes. EU Green Deal compliance costs and dual-certification timelines limit supplier pools.
Instant Mix anchors the volume base while Organic gains share at the steepest rate.
End User:
Cost-to-serve economics separate high-volume institutional contracts from fragmented household purchasing.
- Food Chains:Standardized frozen and instant formats procured through national distribution agreements. US and German quick-service operators specify batch-consistent texture modifiers to eliminate preparation variability across locations.
- Households:Retail-packaged instant mixes and fresh formats for home preparation. UK and US grocery channels show pouch preference for single-serve convenience.
- Restaurants:Independent operators balancing labor savings against premium positioning. Frozen bulk formats dominate mid-tier establishments.
- Catering Services:Event and institutional foodservice requiring scalable portion control. Pouch and cup formats reduce waste in mobile service environments.
Food Chains command procurement scale while Catering Services expand most quickly through contract consolidation.
Packaging Type:
Format selection directly links to consumption occasion and channel economics.
- Pouches:Flexible single-serve and multi-serve bags for retail and foodservice. German commuter rail meal programs and UK meal-prep subscription channels are displacing rigid trays with lightweight alternatives that reduce shipping cube.
- Bulk:Large-format bags and tubs for institutional kitchens and manufacturing inputs. US healthcare and education sector group purchasing organizations negotiate annual volume contracts.
- Cups:Individual portion cups for grab-and-go retail. Convenience store penetration in Japan and South Korea supports regional demand.
- Sachets:Small powder packets for instant reconstitution. Travel and outdoor recreation channels in Nordic countries absorb specialty variants.
Bulk formats dominate tonnage shipments while Pouches climb the fastest through on-the-go channel expansion.
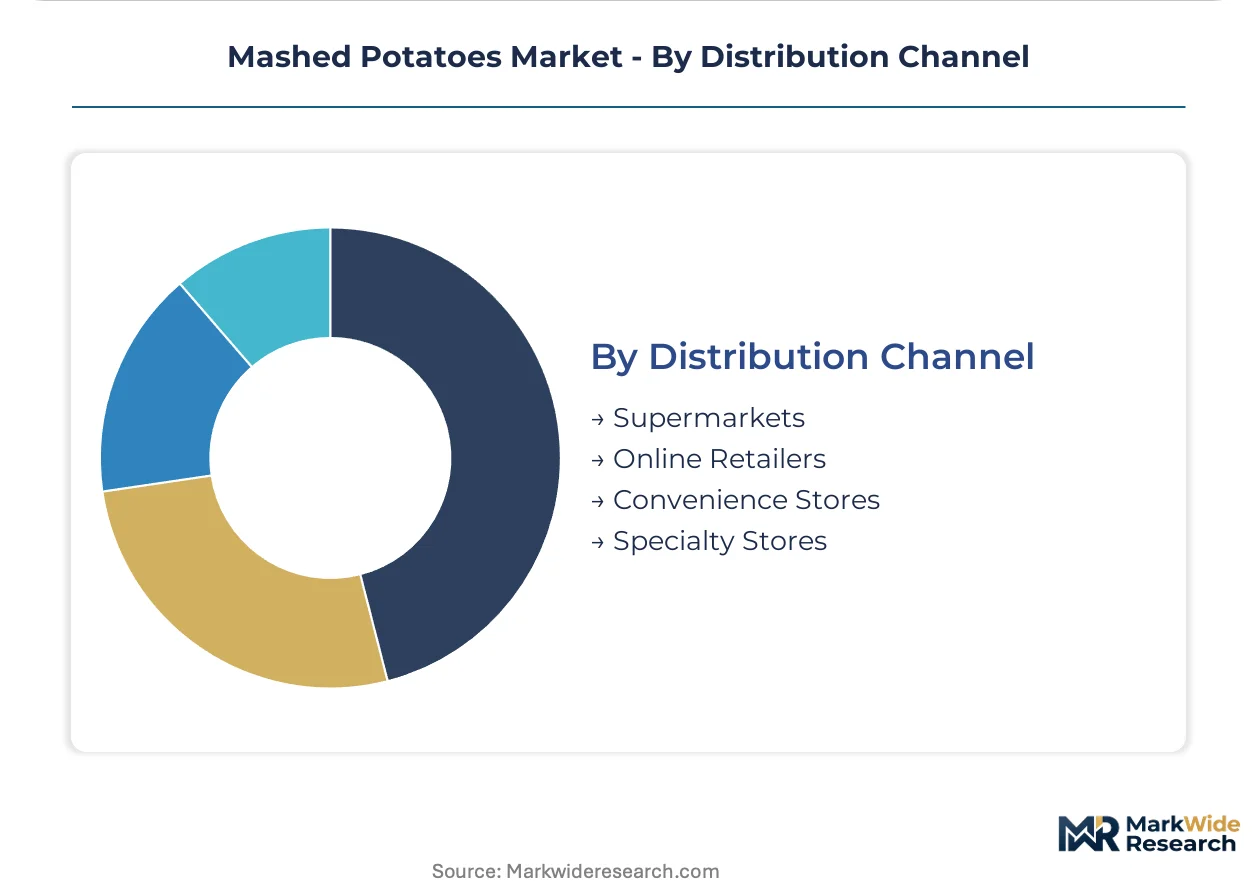
Distribution Channel:
Channel fragmentation is compressing traditional distributor relationships.
- Supermarkets:Multi-format shelf placement spanning economy instant mixes through premium organic chilled lines. UK and German retailers allocate dedicated facing for clean-label variants.
- Online Retailers:Direct-to-consumer and subscription models enabling pantry replenishment. US meal-kit platforms bundle mashed potato components with protein pairings.
- Convenience Stores:Single-serve cups and sachets for immediate consumption. Urban density in Tokyo and Seoul supports format development.
- Specialty Stores:Organic and gourmet positioning through curated assortments. Paris and Milan premium food halls source small-batch regional producers.
Supermarkets maintain the broadest SKU coverage while Online Retailers capture the steepest expansion trajectory through subscription lock-in.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA sodium-reduction guidelines and EU Green Deal sourcing mandates are reshaping where manufacturers locate processing assets and which supply chains qualify for clean-label product lines.
United States
Quick-service chains in the Midwest and Southeast are consolidating frozen-format procurement through group purchasing organizations that bypass traditional broadline distributors. FDA labeling requirements for reduced-sodium claims force reformulation investments that favor processors with captive R&D facilities. Idaho and the Pacific Northwest host dehydration capacity that supplies instant-mix volume to national grocery channels.
Germany
Commuter rail meal programs and meal-prep subscription channels are displacing rigid trays with flexible pouch formats across urban corridors. EU Farm-to-Fork pesticide reduction targets accelerate integrated pest management investment in potato sourcing regions. Bavaria and North Rhine-Westphalia anchor chilled-format production for premium retail tiers seeking clean-label positioning.
United Kingdom
Foodservice distributors absorb bulk frozen volume as labor compression eliminates on-site mashing in mid-tier restaurant chains. EFSA nutritional claims regulation shapes front-of-pack communication for reduced-sodium variants. The Midlands concentration of co-packing facilities handles reformulation runs for private-label contracts.
France
Chilled distribution networks in Paris and Lyon support regional penetration of fresh-format mashed potatoes with shorter shelf life. REACH restrictions on food-contact substances compel validation of alternative emulsifiers ahead of ECHA evaluation deadlines. Benelux-border processing clusters manage cross-border supply for EU organic certification lines.
Canada
Healthcare and education sector procurement through provincial purchasing authorities mirrors US group purchasing organization consolidation patterns. Health Canada regulations align with FDA sodium thresholds for cross-border product standardization. Prairie potato-growing regions supply raw material to frozen-format processors serving North American foodservice accounts.
Mashed Potatoes Market Competitive Environment
Dehydration specialists and frozen-format scale producers split the market between pantry-stockpiling convenience and foodservice labor reduction. The structure concentrates volume among processors with backward integration into potato sourcing and captive dehydration capacity. Three archetypes dominate: heritage dehydrated-pottery specialists, frozen-format multinationals with agricultural supply control, and chilled-segment brand equity holders. Competitive moves center on pouch packaging line expansion and dual organic certification timelines.
Within the heritage specialist tier, Idahoan Foods exemplifies dehydration-focused market presence, while McCain Foods occupies a position as a frozen-format multinational with agricultural integration. Unilever sits within the brand-equity tier leveraging chilled-segment recognition. These three anchors represent distinct strategic postures without implying specific tactical moves or financial performance.
| Leading Market Players |
|---|
| Unilever |
| Agristo |
| Idahoan Foods |
| Hormel Foods |
| Post Holdings |
| McCain Foods |
| Pomuni |
| Branston |
| General Mills |
| Others |
Value Chain & Pricing Dynamics
Idaho and the Pacific Northwest dehydration clusters concentrate instant-mix capacity, granting processors leverage over private-label contract negotiations while fresh potato price volatility in these regions compresses margin pools for standardized formulations.
Pricing Analysis
Geographic price spreads between German commuter rail channels and US institutional bulk contracts reflect divergent cost-to-serve economics. Three-tier pricing structure across organic, clean-label, and conventional levels separates certified supply pools from additive-permitted alternatives. Cost compression in conventional instant-mix tiers is intensifying because sodium-reduction reformulation demands R&D investment without corresponding price recovery. Foodservice distributors show least price sensitivity due to labor-savings calculus, while household retail segments absorb pouch premiums for convenience positioning.
Supply Chain Analysis
Fresh potato sourcing draws from Idaho, the Pacific Northwest, and Prairie provinces in Canada, with starch integrity preserved through steam-peeling investments. Dehydrated flake production rests on specialized ricing and vacuum-cooling equipment, while frozen-format lines require rapid-chilling infrastructure. Single-source dehydration capacity in North America creates supply vulnerability during peak demand windows. Distribution runs through broadline foodservice distributors consolidating volume with group purchasing organizations in US healthcare and education sectors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Prepared potato formats sit at early-cycle expansion as clean-label mandates accelerate reformulation investment and pouch packaging captures on-the-go consumption occasions previously served by rigid alternatives.
For Market Incumbents: Insulate margin pools by securing captive dehydration capacity in Idaho and Pacific Northwest clusters against fresh potato price volatility. Prioritize dual USDA Organic and EU Organic certification timelines to lock premium shelf space before mid-tier competitors complete parallel documentation systems. Channel control through direct-to-operator procurement platforms defends against distributor disintermediation in US institutional sectors.
For New Entrants and Emerging Players: US chilled-format retail remains underpenetrated relative to frozen, offering white-space entry through fresh-focused retailers seeking differentiation. German commuter rail and UK meal-prep subscription channels absorb pouch volume fastest, displacing rigid trays with lightweight alternatives. Go-to-market positioning should emphasize single-serve convenience and clean-label credentials to bypass incumbent scale advantages in bulk formats.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors processors with backward integration into potato sourcing and captive steam-peeling infrastructure. Long-term viability hinges on controlling starch retrogradation through specialized process engineering that exceeds co-packing facility capabilities. Watch hyperspectral imaging adoption rates as inflection indicator for quality-control automation and waste reduction at scale.
| Strategic Initiative | Industry Significance |
|---|---|
| Pouch Packaging Line Expansion | German commuter rail and UK meal-prep channels displace rigid trays with lightweight flexible alternatives. |
| Dual Organic Certification Investment | Parallel USDA Organic and EU Organic documentation extends product launch cycles but secures premium retail placement. |
| Steam-Peeling Technology Upgrade | Industrial systems reduce water consumption and preserve starch integrity without chemical preservatives. |
| Direct-to-Operator Platform Development | US healthcare and education group purchasing organizations consolidate procurement through specialized foodservice technology vendors. |
| Hyperspectral Imaging Integration | Real-time defect detection and starch quality assessment virtualizes manual inspection lines at Idaho dehydration facilities. |
Study Parameters
Cross-validation between primary interviews with foodservice procurement directors, retail category buyers, dehydration plant managers, and regulatory affairs specialists anchors the qualitative findings against secondary validation from FDA labeling guidelines, EU Farm-to-Fork strategy documents, EFSA nutritional claims regulation, and customs trade data on potato product flows. Bottom-up segment sizing triangulates with top-down market consolidation assessments.
Calibration against historical volume trajectories and documented capacity expansions at major dehydration clusters informs the analytical framework across the projection horizon. Segmentation dimensions span product type, end user, packaging format, and distribution channel with regional regulatory cluster overlay. CAGR derivation incorporates input cost elasticity, clean-label premium capture rates, and channel shift velocity. Industry-specific forecast inputs include fresh potato yield volatility patterns and steam-peeling technology adoption curves.
Practitioners should monitor ECHA substance evaluation timelines and REACH restriction implementation for early signals of emulsifier reformulation costs. Forecasts reflect assumptions about labor compression persistence in foodservice and clean-label mandate enforcement intensity. Cross-checking against USDA and EU organic certification approval backlogs is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
United States Egg Powder Market
Processed Foods
United States Ice Cream Market
Processed Foods
Dairy Desserts Market
Processed Foods
Margarine Market
Processed Foods
Accompanying Marinated Product Market
Processed Foods
Asia-Pacific Food Spread Market
Processed Foods
Artisanal Ice Cream Market
Processed Foods
Porridge Market
Processed Foods
Fat Free Food Market
Processed Foods
Processed Fruit Bases Market
Processed Foods
Shelf-Stable Soup Market
Processed Foods
Butter Crisco Market
Processed Foods
United States Fresh Noodles Market
Processed Foods
Pea Processed Ingredients Market
Processed Foods
United States Processed Meat Market
Processed Foods
Processed Vegetable Market