
 United States Ice Cream Market | 2026-2036
United States Ice Cream Market Size, Share, and Industry Trends Forecast 2026-2036
United States Ice Cream Market Outlook
Single-serve and mini-portion bundling is broadening impulse purchase occasions across convenience and foodservice channels. Unilever PLC leverages its freezer-door presence in mass retail to sustain year-round brand visibility. Blue Bell Creameries anchors regional loyalty through dense distribution in the South Central states. Tillamook County Creamery Association differentiates via premium positioning tied to cooperative dairy sourcing.
Ice cream is a frozen dairy dessert typically containing milk fat, sweeteners, and stabilizers, churned and frozen to incorporate air and achieve a semi-solid texture; overrun levels and fat content determine product classification under FDA standards. Its primary commercial purpose is to serve as a refreshment and indulgence product across retail and foodservice environments. Premium ice cream commands the deepest margin pools due to ingredient cost pass-through and brand equity, while non-dairy formulations represent the fastest-growing product type as oat and coconut bases displace traditional dairy in allergen-sensitive households. Distribution through food services and online retail channels is expanding fastest, though supermarkets still occupy the largest volume share.
The FDA governs standard of identity and labeling requirements for frozen desserts, while the USDA oversees Grade A dairy inputs through its Agricultural Marketing Service, and state-level departments of agriculture enforce interstate milk shipment compliance. These frameworks elevate formulation costs for clean-label and reduced-sugar variants, filtering smaller producers from mainstream retail placement. Stakeholders must monitor plant-based labeling disputes and evolving state dairy-defamation statutes that could reshape non-dairy competitive access.
Market Dynamics
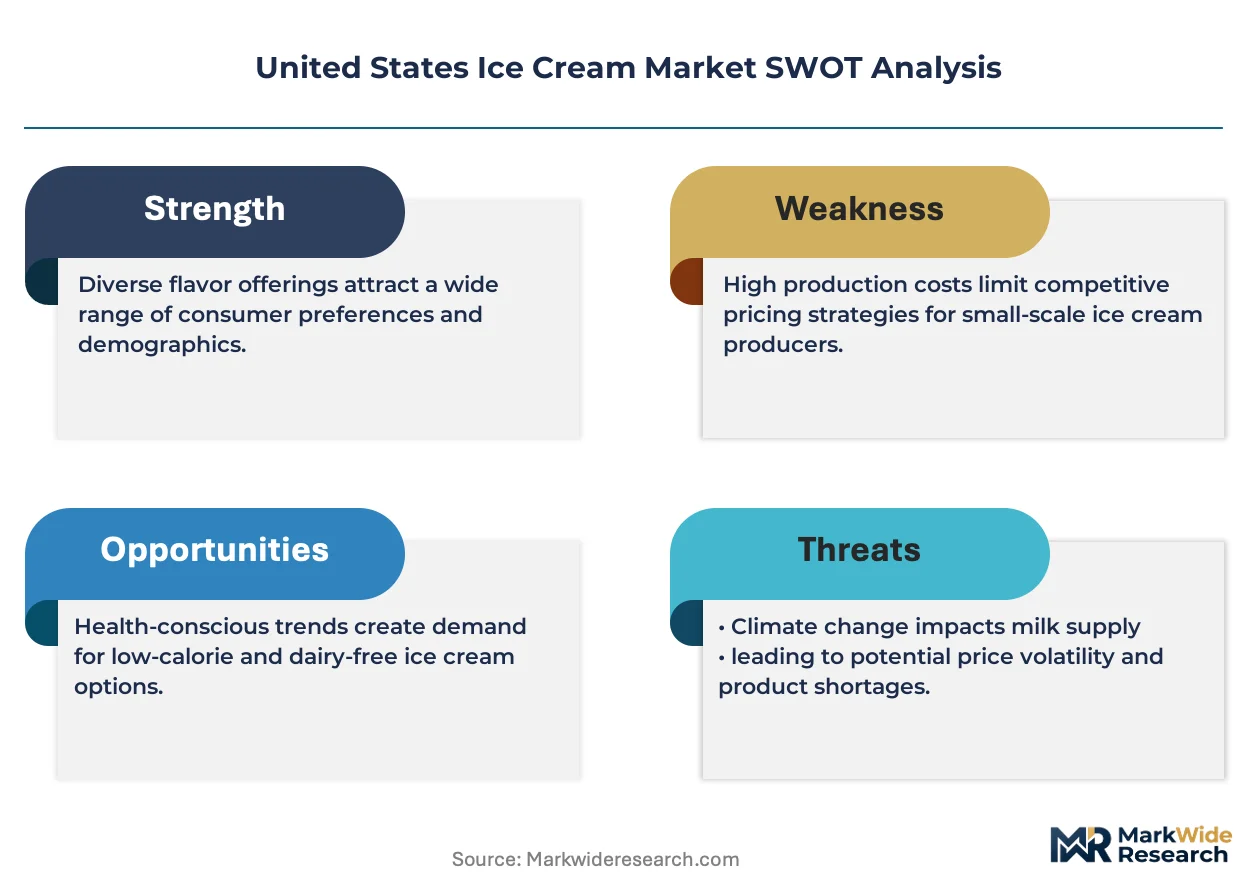
The FDA's updated Nutrition Facts labeling mandates for added sugars are forcing rapid reformulation across the United States Ice Cream Market, compressing legacy recipes and elevating clean-label development costs for mid-tier producers.
Growth Catalysts
- Sun Belt Consumption Concentration:Year-round warm temperatures in Texas and neighboring states sustain elevated per-capita consumption rates, anchoring regional demand density for manufacturers.
- Convenience Channel Freezer Expansion:C-stores and quick-service restaurants are dedicating incremental freezer space to single-serve impulse formats, capturing unplanned purchase occasions.
- Reduced-Sugar Formulation Pressure:The FDA's added-sugar disclosure requirements are accelerating adoption of alternative sweeteners and reformulated recipes that align with evolving consumer expectations.
Market Restraints
- Dairy Input Cost Volatility:Grade A milk price fluctuations governed by USDA Agricultural Marketing Service pricing mechanisms compress margin predictability for traditional dairy-based production.
- Clean-Label Compliance Burden:State-level departments of agriculture enforce interstate milk shipment standards that elevate formulation and documentation costs, filtering smaller producers from mainstream retail placement.
- Plant-Based Substitution Threat:Oat and coconut base alternatives are capturing allergen-sensitive and flexitarian households, eroding addressable market for conventional dairy formulations.
Strategic Opportunities
- Foodservice Distribution White Space:Online retail and direct-to-foodservice channels are expanding faster than legacy supermarket routes, offering margin capture outside traditional retail gatekeepers.
- Premium Positioning Vacancy:Cooperative-sourced dairy and heritage branding commands pricing power in underpenetrated Northeast and Pacific Coast metropolitan markets.
- Non-Dairy Regulatory Tailwind:Evolving state dairy-defamation statutes create competitive access uncertainty that favors established plant-based formulators with legal resources to navigate labeling disputes.
Industry Challenges
- Reformulation Talent Scarcity:Clean-label and reduced-sugar recipe development requires specialized food science capabilities that concentrate at larger manufacturers with dedicated R&D infrastructure.
- Legacy Equipment Retrofit Costs:Transitioning production lines between dairy and plant-based formulations demands capital-intensive cleaning protocols and segregated processing assets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Ice Cream Market |
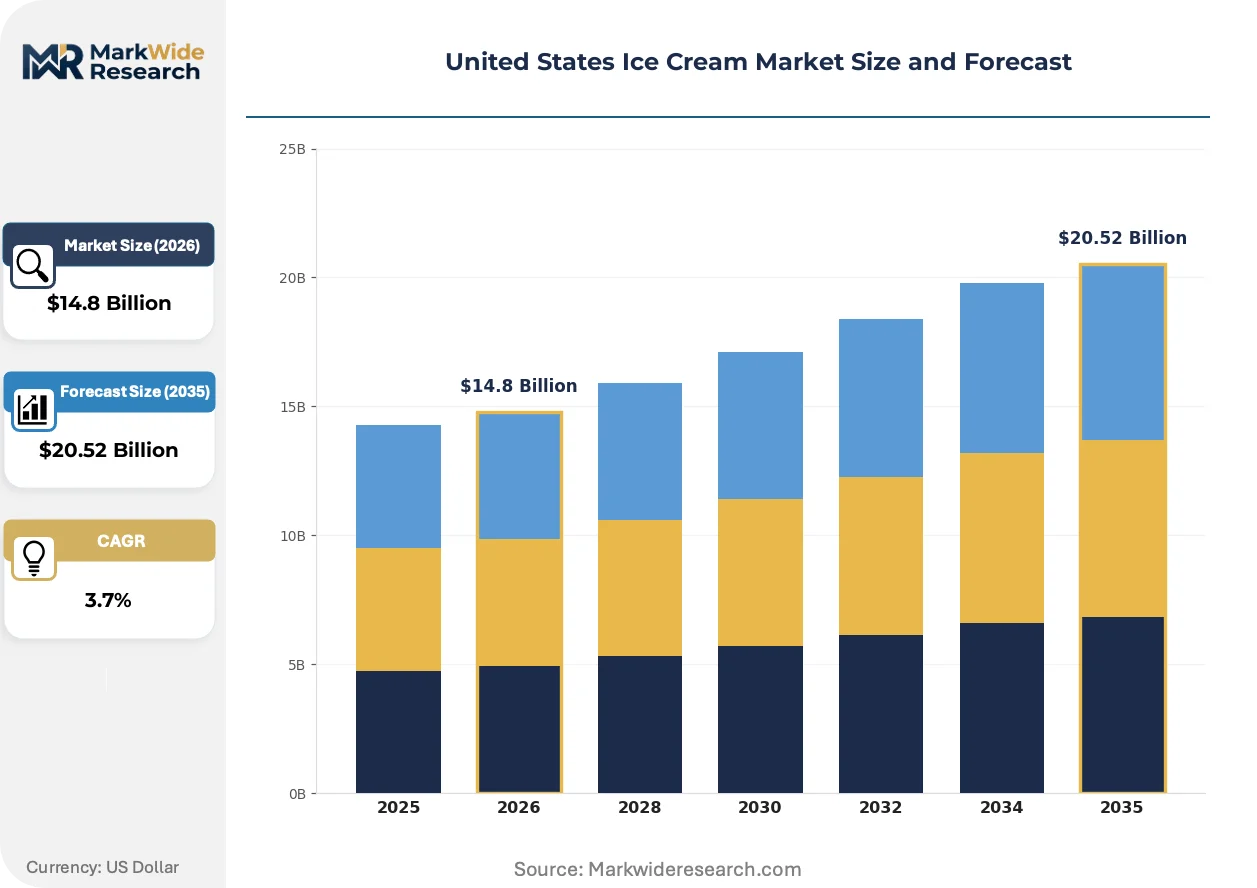
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $20.52 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regular, Premium, Low-Fat, Non-Dairy Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Food Services Flavor: Vanilla, Chocolate, Strawberry, Mint Chocolate Chip Packaging Type: Cups, Cones, Pints, Quart |
| Companies Covered | Wells Enterprises, Tillamook County Creamery Association, Unilever PLC, Mars, Turkey Hill Dairy, Nestlé SA, Blue Bell Creameries, General Mills, Froneri U.S., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Ice Cream Market Strategic Shifts
Reformulation technologies and distribution channel experimentation are compressing traditional product lifecycles while fragmenting consumer touchpoints across physical and digital environments.
Precision fermentation-derived dairy proteins are overtaking conventional extraction methods for flavor and texture replication in premium non-dairy segments. Specialty manufacturers in California and New York are integrating these inputs at pilot scale. The technology is overtaking enzyme-modified starch systems that previously dominated mouthfeel simulation, enabling cleaner ingredient declarations that satisfy both FDA disclosure requirements and retailer clean-label mandates.
The FDA's enforcement discretion timeline for plant-based dairy terminology is tightening labeling compliance windows for non-dairy marketers. Manufacturers must reconcile state-level dairy-defamation statutes with federal preemption arguments in pending litigation. Plant-based entrants in Texas and Florida face the highest regulatory friction as agricultural interest groups press for restrictive labeling laws in state legislatures.
Single-serve mini-portion bundling is fragmenting traditional family-size purchase patterns across convenience and quick-service channels. Younger demographics in urban Sun Belt markets are substituting impulse single-serve for planned grocery-aisle stock-up. This rotation is most visible in Houston, Phoenix, and Atlanta metropolitan statistical areas where c-store density and year-round frozen consumption overlap.
United States Ice Cream Market Segmentation
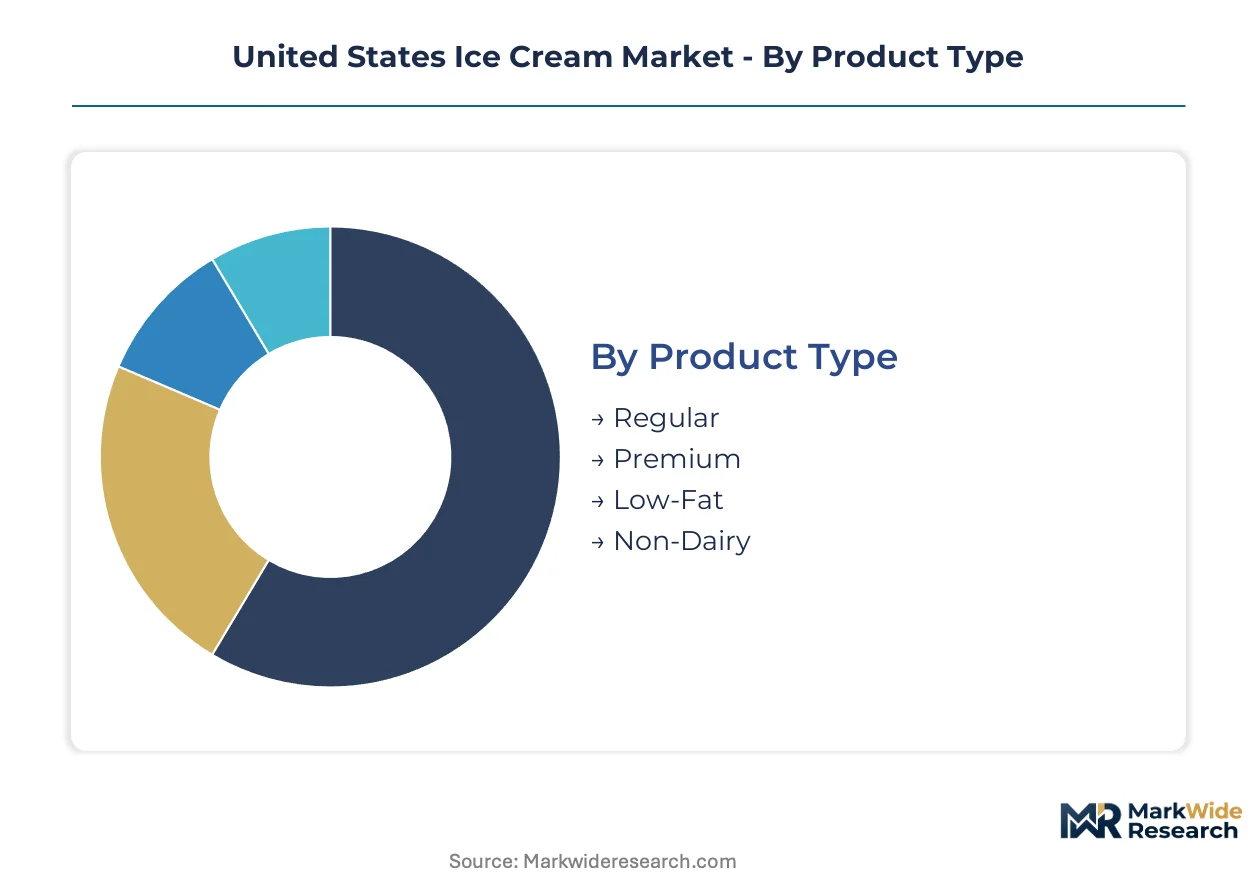
Segmentation in the United States Ice Cream Market reveals divergent margin structures and channel strategies. Manufacturers must align formulation investments with freezer placement economics and regional consumption patterns.
Product Type:
Price sensitivity and ingredient cost pass-through separate buyers across quality tiers.
- Premium:Higher butterfat content and lower overrun levels define FDA-standard premium classification. Texas and Sun Belt metropolitan areas sustain year-round demand density for super-premium positioning.
- Non-Dairy:Oat and coconut base formulations displace conventional dairy in allergen-sensitive households. FDA labeling discretion timelines compress compliance windows for plant-based marketers in Texas and Florida.
- Regular:Standard butterfat formulations dominate volume production at legacy manufacturers.
- Low-Fat:Reduced-fat recipes face reformulation pressure under FDA added-sugar disclosure mandates.
Premium leads volumes today; Non-Dairy is climbing the fastest.
Distribution Channel:
Freezer asset ownership and impulse purchase capture separate channel economics.
- Convenience Stores:Dedicated freezer expansion for single-serve formats captures unplanned purchase occasions. Houston, Phoenix, and Atlanta c-store density overlaps with year-round warm-weather consumption patterns.
- Food Services:Direct-to-operator routes bypass traditional retail gatekeepers. Online retail and foodservice channels are expanding faster than legacy supermarket distribution.
- Supermarkets:Mass retail freezer-door placement sustains year-round brand visibility for national manufacturers.
- Online Retail:Cold-chain fulfillment investments concentrate at established dairy processors with dedicated logistics infrastructure.
Supermarkets anchor volume share; Food Services is expanding most quickly.
Flavor:
Menu versatility and mix-in compatibility drive formulation R&D allocation.
- Vanilla:Base flavor for premium positioning and cooperative-sourced dairy branding. Clean-label vanilla extraction commands ingredient cost premiums in Northeast metropolitan markets.
- Chocolate:Cocoa butter and liquor sourcing differentiates tier positioning. Mint Chocolate Chip and specialty flavors concentrate innovation investment at California and New York pilot-scale manufacturers.
- Strawberry:Fruit inclusion stability challenges clean-label formulation without artificial stabilizers.
- Mint Chocolate Chip:Mix-in texture retention requires specialized freezing protocols for chip integrity.
Vanilla dominates base volume; Mint Chocolate Chip shows the steepest premium trajectory.
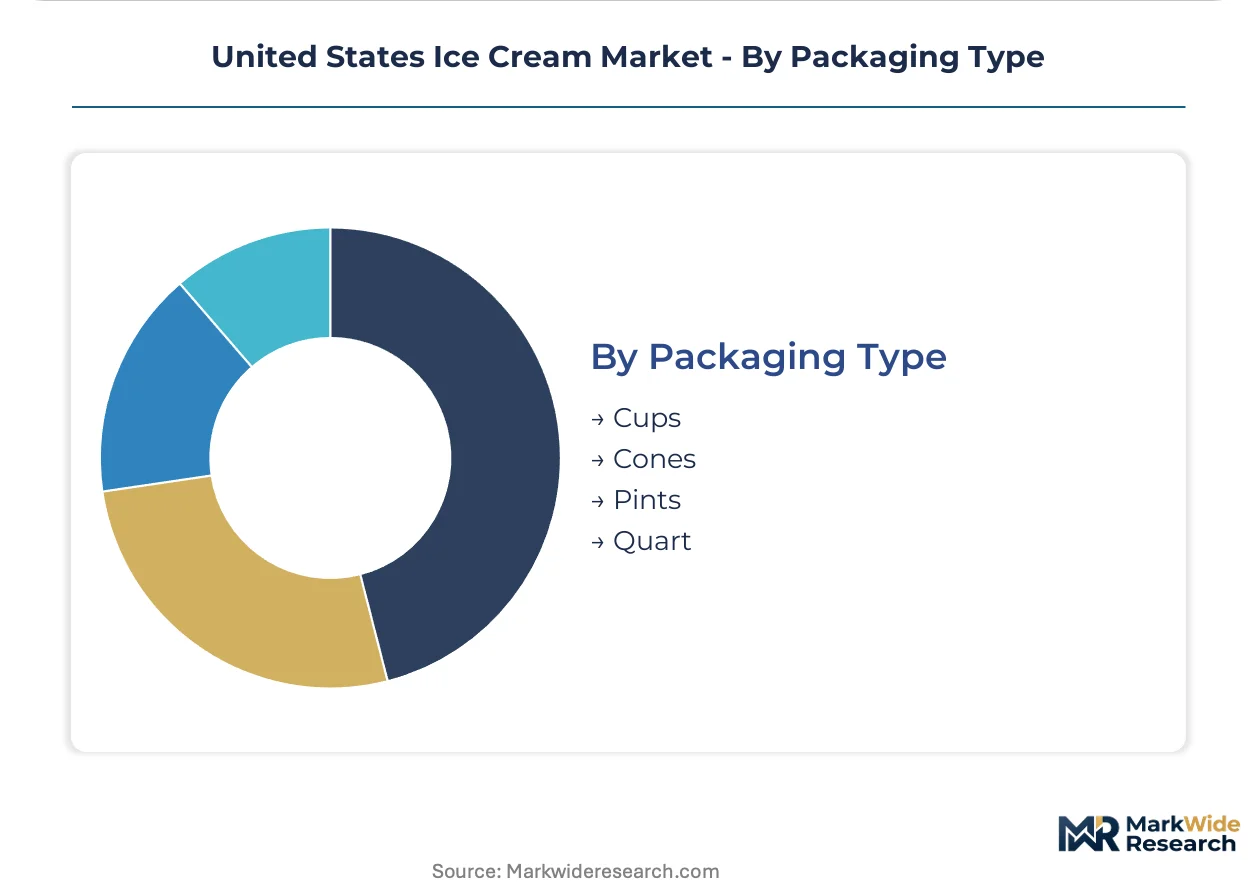
Packaging Type:
Consumption occasion and household size determine format preference.
- Single-Serve Cups:Mini-portion bundling fragments traditional family-size purchase patterns. Younger demographics in urban Sun Belt markets substitute impulse single-serve for planned stock-up.
- Pints:Premium positioning standard for cooperative-sourced and heritage branding. Pint formats command deepest margin pools through ingredient cost pass-through.
- Cones:Pre-filled novelty formats concentrate at quick-service restaurant freezer placements.
- Quart:Family-size formats face share erosion from single-serve fragmentation in convenience channels.
Pints lead premium revenue; Single-Serve Cups are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States ice cream industry traces its commercial roots to 19th-century urban dairies in Philadelphia and New York, where mechanical refrigeration first enabled mass production. Regional consumption patterns now concentrate in Sun Belt states where warm climates sustain year-round demand density.
Texas
Houston and Dallas-Fort Worth metropolitan areas anchor the nation's highest per-capita consumption rates. The Texas Department of Agriculture enforces interstate milk shipment standards that elevate compliance costs for out-of-state suppliers. Blue Bell Creameries maintains dense distribution networks across South Central Texas, leveraging regional loyalty to defend freezer-door placement.
California
Los Angeles and San Francisco Bay Area markets drive premium and non-dairy innovation adoption. The California Department of Food and Agriculture oversees Grade A dairy standards that exceed federal minimums, filtering smaller producers from mainstream retail. Specialty manufacturers in Oakland and Los Angeles pilot precision fermentation-derived proteins for cleaner-label formulations.
Florida
Miami and Tampa metropolitan statistical areas sustain elevated consumption through year-round warm temperatures. The Florida Department of Agriculture and Consumer Services enforces labeling statutes that create friction for plant-based entrants. Quick-service restaurant freezer expansion concentrates along I-4 corridor corridors between Orlando and Tampa.
New York
New York City and Hudson Valley markets command ingredient cost premiums for cooperative-sourced dairy branding. The New York State Department of Agriculture and Markets regulates fluid milk pricing through federal order participation. Brooklyn and Queens specialty manufacturers integrate precision fermentation inputs at pilot scale for premium non-dairy segments.
Georgia
Atlanta metropolitan area c-store density overlaps with impulse single-serve fragmentation trends. The Georgia Department of Agriculture enforces interstate milk shipment compliance that elevates documentation burdens for regional entrants. Convenience channel freezer expansion captures unplanned purchase occasions across Sun Belt suburban corridors.
United States Ice Cream Market Competitive Environment
Premium-margin players sit above commodity-margin players across formulation tier and distribution access. The United States Ice Cream Market structures around three concentration nodes: multinational conglomerates with mass retail freezer dominance, regional dairies with cooperative heritage positioning, and specialty formulators with clean-label or non-dairy specialization. Strategic moves concentrate on portfolio diversification into plant-based lines and vertical control over cold-chain distribution assets.
Within the multinational conglomerate tier, Unilever PLC and Nestlé SA occupy positions defined by year-round freezer-door visibility and cross-category scale. Tillamook County Creamery Association and Blue Bell Creameries exemplify regional cooperative heritage, anchoring loyalty through dense distribution in their respective strongholds. These four represent the dominant archetypes: global scale, regional heritage, and the emerging specialist formulator segment.
| Leading Market Players |
|---|
| Wells Enterprises |
| Tillamook County Creamery Association |
| Unilever PLC |
| Mars |
| Turkey Hill Dairy |
| Nestlé SA |
| Blue Bell Creameries |
| General Mills |
| Froneri U.S. |
| Others |
Value Chain & Pricing Dynamics
Grade A milk price fluctuations governed by USDA Agricultural Marketing Service pricing mechanisms cascade through formulation tiers into premium-standard-economy price stratification across retail and foodservice channels.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels anchors the United States Ice Cream Market, with butterfat content and overrun levels serving as the primary grade differentiators under FDA standards. Price differentiation stems from cooperative-sourced dairy certification and clean-label ingredient declarations. Cost compression in mid-tier formulations is intensifying because FDA added-sugar disclosure mandates force rapid recipe redevelopment. Economy buyers at mass retail show highest price sensitivity; premium purchasers at specialty grocers exhibit lowest elasticity.
Supply Chain Analysis
Reverse-logistics flows for temperature-compromised product returns concentrate cost burdens on distributors lacking dedicated cold-chain infrastructure. Grade A dairy sourcing draws from Wisconsin, California, and New York production clusters. Coconut and oat base inputs for non-dairy formulations rest on Southeast Asian and North American agricultural supply. Single-source vulnerability in precision fermentation-derived protein supply threatens premium non-dairy segment scaling. Distribution runs through direct-to-foodservice routes and mass retail freezer-door placement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States Ice Cream Market functions as a stable compounder, with Sun Belt consumption concentration providing steady demand density regardless of macroeconomic cycling.
For Market Incumbents: Hedge against plant-based substitution by securing captive supply of precision fermentation-derived dairy proteins before specialty manufacturers lock pilot-scale capacity. Dedicate R&D infrastructure to clean-label stabilizer systems that satisfy FDA disclosure requirements without artificial ingredient declarations. Channel control through convenience store freezer expansion captures impulse occasions eroding family-size format share. For New Entrants and Emerging Players: Precision fermentation technology offers entry wedge into premium non-dairy segments where established players lack specialized formulation capabilities. Target foodservice distribution white space in Northeast metropolitan markets where cooperative-sourced dairy branding commands pricing premiums. Direct-to-operator routes bypass supermarket gatekeeper consolidation. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier regional dairies possessing dense distribution in Sun Belt states and underutilized plant capacity suitable for non-dairy line retrofit. Long-term viability hinges on regulatory navigation capabilities as state dairy-defamation statutes evolve. Monitor FDA enforcement discretion timelines for plant-based terminology as inflection indicator for competitive access shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation | Alternative sweetener adoption aligns product portfolios with FDA added-sugar disclosure mandates. |
| Foodservice Channel Expansion | Direct-to-operator routes capture margin outside supermarket retail gatekeeper consolidation. |
| Precision Fermentation Integration | Pilot-scale protein sourcing enables premium non-dairy texture replication without enzyme-modified starch. |
| Sun Belt Distribution Density | Houston and Dallas-Fort Worth freezer placement anchors year-round consumption against seasonal volatility. |
| Cooperative Heritage Branding | Premium positioning through dairy sourcing transparency commands pricing power in underpenetrated coastal metros. |
Study Parameters
Direct dialogue with brand managers, category buyers at convenience and mass retail chains, supply planners at dairy processors, and channel sales heads grounded qualitative findings in operational reality. Secondary validation drew from FDA labeling guidance documents, USDA Agricultural Marketing Service dairy pricing reports, Nielsen retail audit data, and state department of agriculture enforcement records. Bottom-up volume modeling triangulated against top-down value projections.
Segmented outputs across product type, distribution channel, and regional consumption cluster calibrated growth trajectories over the projection horizon. CAGRs emerged from historical consumption elasticity analysis against temperature and income variables. Modeling incorporated FDA regulatory timeline uncertainty, plant-based substitution rates, and cold-chain logistics cost inflation as scenario inputs.
The model holds under stable dairy input pricing and gradual regulatory implementation; deviation in abrupt FDA enforcement shifts or Grade A milk price spikes would shift volume and value trajectories. Practitioners should monitor state legislative activity on dairy-defamation statutes and precision fermentation capacity announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Global Take Out Fried Chicken Market
Processed Foods
Middle East and Africa Processed Meat Market
Processed Foods
High Pressure Processing (HPP) for Rice and Grain Market
Processed Foods
Potato Soup Market
Processed Foods
Asia-Pacific Soup Market
Processed Foods
Low Calorie Rice Pudding Market
Processed Foods
Egg Powder Market
Processed Foods
Low Fat Pasta Market
Processed Foods
Casual Marinated Products Market
Processed Foods
Ready-To-Whip Toppings Market
Processed Foods
High-Pressure Processing (HPP) Foods Market
Processed Foods
Fresh Pasta Market
Processed Foods
India Ready to Mix Food Market
Processed Foods
Global Pasta Market
Processed Foods
Ice Cream Parlor Market
Processed Foods
Low Fat Soups Market