
 Tomato Puree Market | 2026-2036
Tomato Puree Market Size, Share, and Industry Trends Forecast 2026-2036
Tomato Puree Market Analysis
Food service operators is reorganizing procurement priorities toward concentrated and value-added puree formats as restaurant chains and ready-meal manufacturers seek cost-efficient, flavor-dense inputs. Del Monte Foods Inc leverages its integrated California processing network to sustain year-round supply continuity. Dohler GmbH differentiates through beverage and sauce application expertise, anchoring European industrial demand. Tiger Brands Limited dominates sub-Saharan African distribution channels, controlling shelf placement in formal retail.
Tomato puree is a processed tomato product manufactured by cooking and straining tomatoes to remove seeds and skins, typically achieving 8-24% soluble solids content depending on concentration grade, and serving as a foundational ingredient in sauces, soups, beverages, and prepared meals. Canned puree retains the largest volume share due to established industrial purchasing patterns and extended ambient shelf stability, though organic puree commands premium positioning in European and North American retail channels where EFSA-monitored pesticide residue thresholds shape certification requirements. Pouch packaging is gaining traction in household and food service segments as flexible formats reduce logistics cube and improve dispensing efficiency compared to traditional glass jar and tin can alternatives.
FDA standards for acidified foods and thermal processing parameters govern US market entry, while EU REACH and F-Gas Regulation constrain refrigerant choices in cold-chain logistics for temperature-sensitive tomato concentrates. BIS certification requirements in India and CDSCO-aligned food safety protocols affect import eligibility for international suppliers targeting institutional buyers. Stakeholders must monitor evolving extended producer responsibility mandates for single-use packaging across multiple jurisdictions, as these frameworks will determine which material formats retain channel access and which incur compliance-driven cost escalation.
Market Dynamics
Food service operators are reorganizing procurement priorities toward concentrated and value-added puree formats as restaurant chains and ready-meal manufacturers seek cost-efficient, flavor-dense inputs. EU F-Gas Regulation and REACH compliance are simultaneously reshaping cold-chain logistics and packaging specifications for temperature-sensitive tomato concentrates.
Growth Catalysts
- EU F-Gas Regulation phase-down:Cold-chain operators are retrofitting processing facilities with lower-GWP refrigerants, expanding demand for ambient-stable concentrated puree that reduces refrigerated transport intensity.
- Food service consolidation:Multi-unit restaurant chains are standardizing on 28-30% Brix concentrate to reduce water weight in inbound logistics and extend kitchen yield per case.
- Pouch packaging adoption:Flexible aseptic pouches are displacing tin cans in institutional channels, cutting cube-out costs and enabling portion-controlled dispensing systems.
Market Restraints
- Processing tomato supply concentration:California drought cycles and Italian heat stress are tightening origination from the three dominant cultivation clusters, amplifying price volatility for paste-grade tomatoes.
- REACH chemical compliance costs:ECHA registration requirements for coating resins and adhesives used in aseptic packaging are elevating qualification timelines and supplier switching costs for European processors.
- Glass jar substitution pressure:Retail channels in premium segments face consumer preference migration toward shelf-stable cartons and pouches, eroding demand for traditional jarred formats.
Strategic Opportunities
- Sub-Saharan African retail formalization:Supermarket expansion in Nigeria and Kenya is creating first-mover shelf space for long-life carton puree targeting emerging middle-class households.
- Beverage application convergence:Cold-pressed tomato juice and smoothie bases are opening incremental demand from health-positioned beverage manufacturers seeking clean-label vegetable inputs.
- Extended Producer Responsibility tailwinds:EU packaging waste directives are accelerating flexible format adoption, rewarding processors with in-house pouch converting capabilities.
Industry Challenges
- Thermal processing engineering scarcity:Specialized knowledge of high-temperature short-time sterilization parameters for concentrate is concentrating among aging technician cohorts in Italian and Californian processing hubs.
- Aseptic line capex intensity:Commercial-scale Tetra Pak and Scholle-compatible filling systems require eight-figure capital commitments, constraining mid-processor expansion into value-added formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tomato Puree Market |
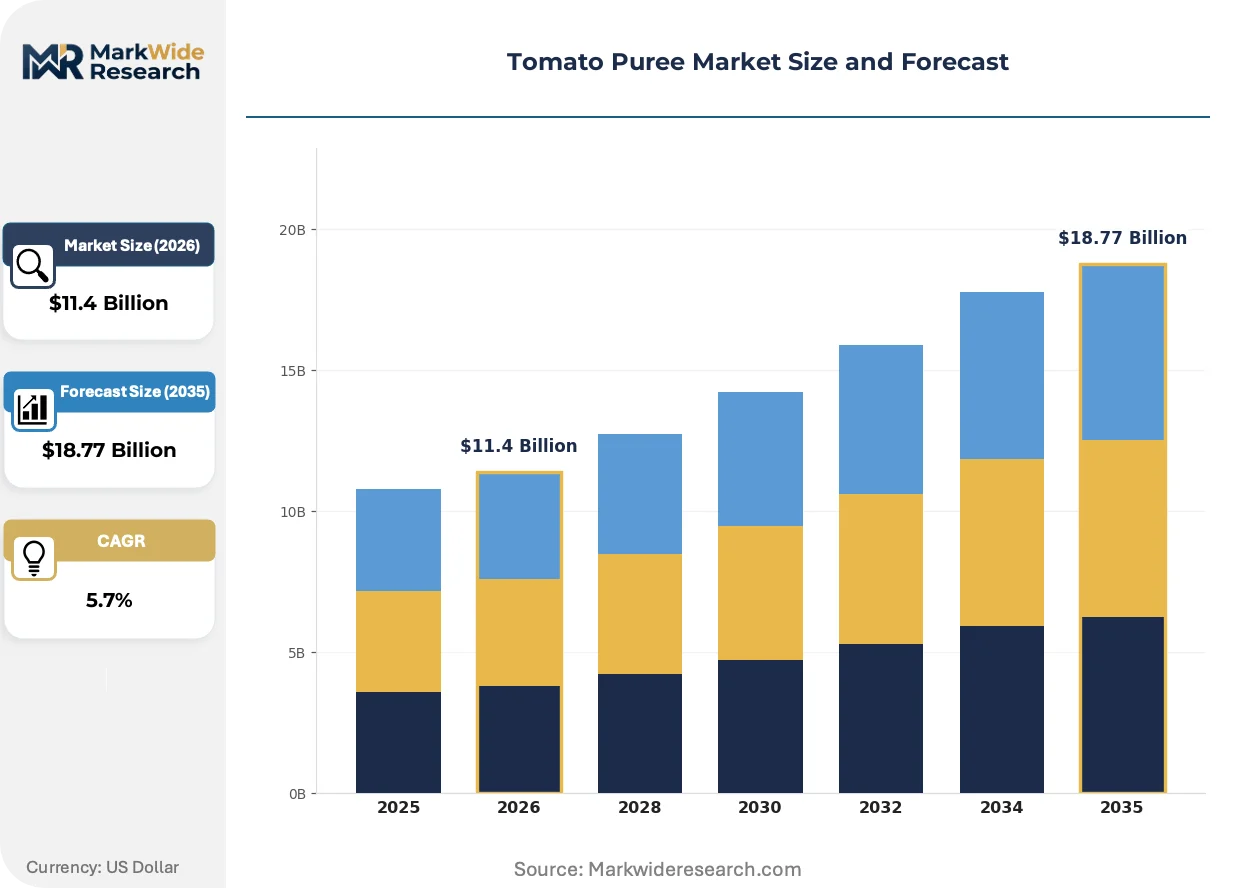
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $18.77 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrated Puree, Canned Puree, Organic Puree, Value-Added Puree End User: Food Service, Retail, Industrial, Household Packaging Type: Glass Jar, Pouch, Tin Can, Plastic Container Distribution Channel: Online Retail, Grocery Stores, Wholesale, Specialty Stores |
| Companies Covered | Riviana Foods Pty Ltd, Del Monte Foods Inc, Symrise AG, Ariza B.V., H. J. Heinz Company, Dohler GmbH, Tiger Brands Limited, Dabur India Ltd., Kiril Mischeff, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tomato Puree Market Emerging Trajectories
Processing technology, regulatory chemistry constraints, and procurement model evolution are converging to reshape competitive positioning across concentrate grades and packaging formats. Three developments are commanding strategic attention from operators and investors.
High-pressure processing (HPP) is fragmenting the thermal pasteurization paradigm for premium puree segments. Cold-pressed juice manufacturers and organic label holders are adopting HPP to retain volatile aromatic compounds and vitamin C stability. This technology is fragmenting quality-tier segmentation, creating a distinct super-premium shelf-stable category between raw refrigerated and traditional canned formats.
REACH Annex XVII restrictions on bisphenol-A (BPA) in food contact materials are accelerating coating chemistry transitions across European canning lines. Epoxy-phenolic internal coatings face substitution by polyester and vinyl-organosol alternatives with shorter validated shelf-life histories. Italian and Spanish processors are most affected, conducting accelerated stability trials to maintain export eligibility under EFSA-monitored migration limits.
Direct contracting between food service operators and processing cooperatives is compressing traditional distributor layers. Large quick-service chains are negotiating multi-year offtake agreements with Californian and Andalusian tomato grower associations, securing volume commitments in exchange for price transparency. This pattern is most visible in North American and Western European institutional channels where procurement teams have invested in agricultural commodity analytics capabilities.
Tomato Puree Market Segmentation
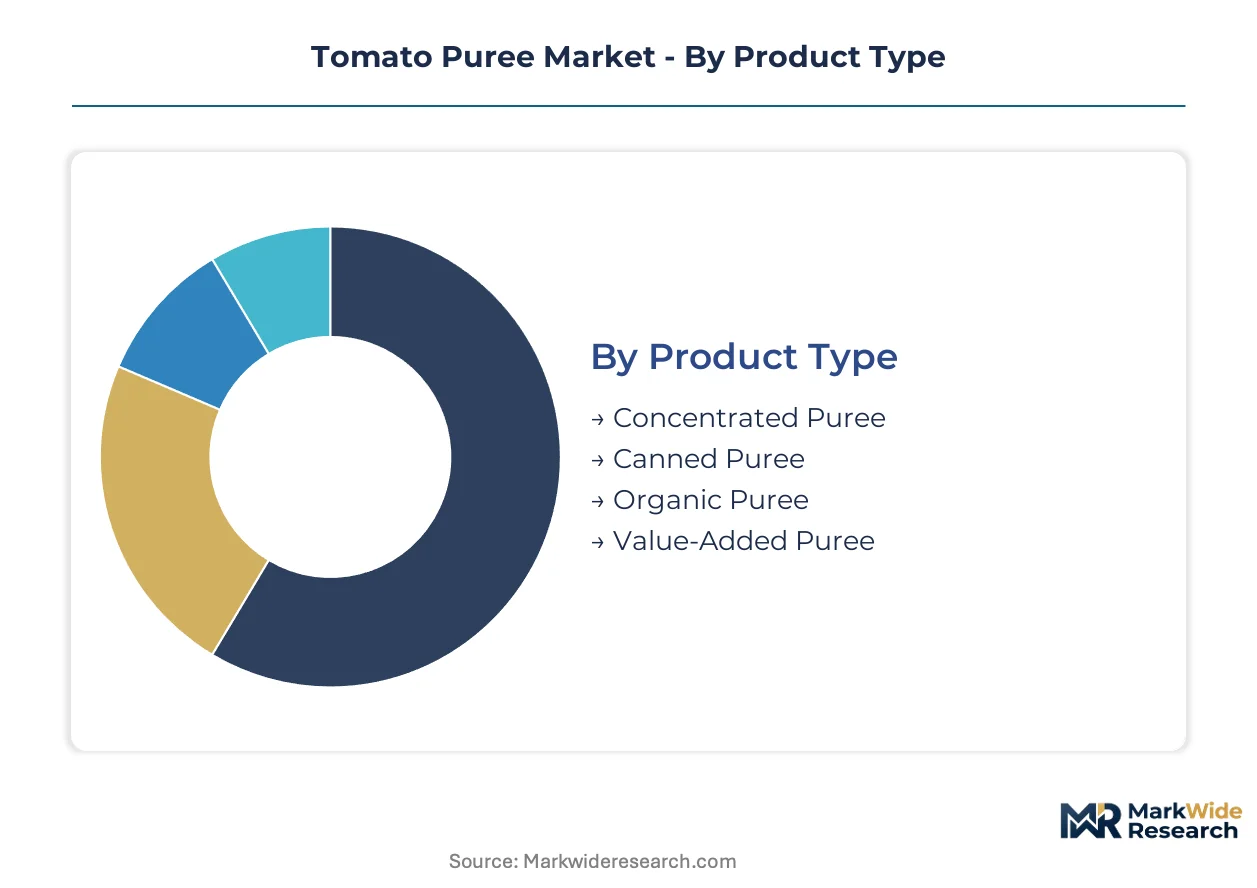
Tomato puree demand fragments across four distinct segmentation dimensions, each governed by divergent cost structures and regulatory exposure. Understanding substitution pressures within product formats and packaging types enables processors to prioritize capital allocation across margin tiers.
Product Type:
Concentrated puree faces the most acute substitution threat from ambient-stable paste alternatives, while value-added formats defend position through formulation complexity barriers.
- Concentrated Puree:Achieves 28-30% Brix soluble solids through evaporative reduction, enabling food service operators to cut inbound logistics costs by reducing water weight. Multi-unit restaurant chains in Italy and California are standardizing procurement on this grade to extend kitchen yield per case.
- Canned Puree:Retains ambient shelf stability through thermal sterilization in tin-plated containers, dominating industrial purchasing patterns established over decades. Established supply contracts with institutional buyers in Spain create switching friction against flexible format alternatives.
- Organic Puree:Cultivated under EFSA-monitored pesticide residue thresholds with premium positioning in European and North American retail channels.
- Value-Added Puree:Incorporates seasoning blends or functional ingredients for ready-meal manufacturers seeking formulation shortcuts.
Canned puree retains volume leadership; value-added puree holds the steepest expansion curve.
End User:
Cost tier stratification separates commodity-scale industrial buyers from premium-positioned retail channels with divergent specification tolerance.
- Food Service:Chains and contract caterers drive demand for 28-30% concentrate in aseptic bag-in-box formats, prioritizing portion control and waste reduction over brand recognition.
- Retail:Supermarket and hypermarket channels command organic certification and clean-label positioning, with EFSA residue compliance serving as table stakes for shelf placement in France and Germany.
- Industrial:Sauce manufacturers and soup processors purchase paste-grade material in bulk tanker quantities, with specifications tightening around color index and viscosity consistency.
- Household:Smaller-format pouch and carton purchases concentrate in urban markets of Nigeria and Kenya as supermarket formalization expands.
Industrial buyers dominate tonnage throughput; food service channels are climbing the fastest on value-added format adoption.
Packaging Type:
Supply concentration among aseptic filling equipment vendors is forcing mid-tier processors toward material formats with lower capital intensity barriers.
- Pouch:Flexible aseptic formats reduce logistics cube by 40% versus rigid alternatives and enable portion-controlled dispensing systems for institutional kitchens. REACH Annex XVII constraints on coating chemistry are accelerating European adoption.
- Glass Jar:Premium retail positioning in Italian and Spanish markets persists despite extended producer responsibility mandates elevating end-of-life costs.
- Tin Can:Established industrial infrastructure and established recycling streams defend share in mature markets with conservative buyer preferences.
- Plastic Container:Polypropylene formats serve fresh-chilled distribution channels with shorter shelf-life requirements.
Glass jar formats retain premium channel access; pouches are gaining share fastest on logistics efficiency gains.
Distribution Channel:
Customer type stratification determines whether procurement flows through consolidated wholesale layers or direct-to-operator contracting models.
- Wholesale:Food service distributors in California and Andalusia maintain inventory positions for restaurant chains with limited cold-storage capacity, though direct cooperative contracting is compressing margins.
- Grocery Stores:European supermarket consolidation is standardizing private-label specifications around organic certification tiers.
- Online Retail:Direct-to-consumer pouch formats are penetrating urban Indian households with convenience-positioned subscription models.
- Specialty Stores:Italian delicatessen channels command heritage-protected origin labeling for premium positioning.
Wholesale channels retain volume concentration; online retail is expanding most quickly on urban convenience positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian processors export concentrated puree to German industrial buyers through established Alpine logistics corridors. California's Central Valley ships aseptic bag-in-box formats to quick-service chains across the United States and Canada. Spanish cooperatives supply paste-grade material to French sauce manufacturers under seasonal contracting arrangements.
Italy
Emilia-Romagna processing cooperatives supply 28-30% Brix concentrate to German and Austrian ready-meal manufacturers. EFSA-monitored pesticide residue thresholds shape organic certification requirements for exports to France and Benelux markets. Parma-based facilities face REACH Annex XVII coating chemistry transitions as BPA restrictions accelerate can lining substitutions.
United States
California's Central Valley dominates paste-grade tomato origination for North American food service chains. FDA acidified food standards govern thermal processing parameters for interstate commerce. Fresno County processing clusters are retrofitting cold-chain facilities to comply with EPA refrigerant phase-down mandates under AIM Act regulations.
Spain
Andalusian grower associations negotiate direct offtake agreements with British retail consolidators. EU F-Gas Regulation constrains refrigerated transport choices for temperature-sensitive concentrate exports to Northern Europe. Murcia-based processors are expanding aseptic pouch capacity to serve Scandinavian institutional buyers seeking reduced logistics cube.
India
Maharashtra and Karnataka cultivation belts supply paste-grade tomatoes to domestic sauce manufacturers and Middle Eastern export markets. BIS certification requirements and FSSAI food safety protocols govern import eligibility for international suppliers targeting institutional buyers. Nashik processing hubs are adopting flexible carton formats for urban retail formalization in Mumbai and Bangalore.
South Africa
Tiger Brands controls shelf placement in formal retail channels across Nigeria and Kenya through sub-Saharan distribution networks. Regional cold-chain limitations favor ambient-stable concentrated formats over refrigerated alternatives. Gauteng-based logistics operators are expanding warehouse capacity to serve supermarket consolidation in Lagos and Nairobi.
Tomato Puree Market Vendor Landscape
Player mix skews toward integrated agro-industrial conglomerates with captive tomato origination and specialized ingredient houses with beverage application expertise. Structure concentrates around three strategic archetypes: California-based vertically integrated processors, European flavor-system specialists, and sub-Saharan distribution-dominant conglomerates. Dominant competitive moves include direct cooperative contracting that compresses distributor layers and in-house pouch converting capabilities that capture extended producer responsibility tailwinds.
Among integrated North American processors, Del Monte Foods Inc exemplifies the captive supply archetype through its California processing network. Dohler GmbH represents European beverage and sauce application specialists anchoring industrial demand. Tiger Brands Limited occupies the distribution-control position in sub-Saharan African formal retail channels.
| Leading Market Players |
|---|
| Riviana Foods Pty Ltd |
| Del Monte Foods Inc |
| Symrise AG |
| Ariza B.V. |
| H. J. Heinz Company |
| Dohler GmbH |
| Tiger Brands Limited |
| Dabur India Ltd. |
| Kiril Mischeff |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at Italian and Californian processing clusters determines price floors across concentrate grades, with evaporative reduction economics creating steep scale barriers that protect incumbent margins while squeezing mid-tier competitors. Food service procurement consolidation amplifies volume-discount leverage, compressing realized prices for standard-grade puree even as organic certification premiums widen in European retail channels.
Pricing Analysis
Thermal-processing generation gaps separate HPP-equipped super-premium facilities from legacy retort operators and emerging aseptic pouch converters. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and concentration intensity, with organic EFSA-compliant puree commanding substantial premiums over conventional paste-grade material. Cost compression in standard-grade concentrate is intensifying because California drought cycles are tightening processing tomato origination. Industrial buyers in sauce manufacturing exhibit highest price sensitivity, while heritage-protected Italian delicatessen channels show lowest elasticity.
Supply Chain Analysis
Strategic stockpile preferences dominate food service procurement, with multi-unit chains negotiating multi-year offtake agreements to secure volume commitments against harvest volatility. Supply concentrates in Italy, California, and Spain, with Emilia-Romagna cooperatives, Fresno County processors, and Andalusian grower associations anchoring global origination. Processing tomato cultivation draws from irrigation-dependent acreage, steel-plated can substrates, and aseptic packaging films. Single-source vulnerability runs through concentrated cultivation clusters exposed to climate stress. Distribution runs through wholesale food service layers in California and Andalusia, though direct cooperative contracting is compressing intermediary margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tomato puree sits in early-cycle expansion as pouch packaging adoption penetrates institutional channels and sub-Saharan retail formalization accelerates ambient-stable format demand.
For Market Incumbents: Secure captive tomato origination through backward integration into Californian and Andalusian grower associations, insulating against climate-driven supply volatility. Deepen aseptic pouch converting capabilities to capture extended producer responsibility tailwinds in EU markets. Regulatory chemistry transitions under REACH Annex XVII threaten canning line compliance costs for Italian processors lacking in-house coating validation. For New Entrants and Emerging Players: Anchor in Nigerian and Kenyan supermarket expansion corridors where formal retail shelf space remains contested and long-life carton formats address cold-chain limitations. Target beverage application convergence for cold-pressed tomato juice bases, where health-positioned manufacturers seek clean-label vegetable inputs. Partner with regional logistics operators in Gauteng to bypass Tiger Brands' distribution control. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors processors with HPP capabilities and in-house flexible packaging conversion, as these assets capture premium-tier segmentation and regulatory-driven format shifts. Long-term viability hinges on agricultural commodity analytics capabilities that enable direct contracting models. Watch California groundwater adjudication proceedings as inflection indicator for processing tomato acreage stability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Grower Associations | Captive supply from Californian and Andalusian cooperatives insulates against drought-driven price volatility. |
| Aseptic Pouch Capacity Expansion | Murcia-based lines serving Scandinavian buyers cut logistics cube by 40% versus tin can alternatives. |
| HPP Technology Deployment | Cold-pressed retention of aromatic compounds creates super-premium tier between raw and canned formats. |
| Direct Cooperative Contracting | Quick-service chains negotiating with Fresno County growers compress traditional distributor margins. |
| REACH-Compliant Coating Transition | Parma facilities substituting epoxy-phenolic linings maintain EFSA-monitored export eligibility to France. |
Methodological Framework
Initial hypotheses were tested against primary input from processing plant managers, food service procurement directors, retail category buyers, and agricultural cooperative representatives and refined through secondary validation. Primary fieldwork drew from tomato processor technical directors, cold-chain logistics operators, and packaging equipment vendors. Secondary sources included FDA acidified food filings, EU F-Gas Regulation implementation reports, EFSA pesticide residue monitoring data, and trade customs records for concentrate shipments. Bottom-up volume modeling triangulated against top-down demand aggregation across end-use segments.
Variance decomposition separated volume drivers from price realization factors across the projection horizon. Segmentation dimensions modeled include concentration grade, packaging format, end-user channel, and geographic regulatory cluster. CAGRs were derived from trend extrapolation adjusted for structural shift assumptions. Forecast inputs incorporated California irrigation water allocation forecasts and EU packaging waste directive implementation timelines.
Underlying assumptions cover stable climate patterns in Mediterranean and Central Valley cultivation belts, with deviation risk concentrated in groundwater adjudication outcomes and F-Gas Regulation refrigerant retrofit schedules. Revision becomes warranted when California processing tomato acreage contracts exceed historical volatility bands or when REACH coating chemistry transitions accelerate beyond validated shelf-life histories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Processed Eucheuma Seaweed Market
Processed Foods
Artisanal Ice Cream Market
Processed Foods
Ice Cream Parlor Market
Processed Foods
Block Margarine Market
Processed Foods
Yogurt Dip Market
Processed Foods
Ready-To-Whip Toppings Market
Processed Foods
Processed Fruit Bases Market
Processed Foods
High Pressure Processing (HPP) for Rice and Grain Market
Processed Foods
Global Malted Milk Market
Processed Foods
Fat Free Soup Market
Processed Foods
United States Egg Powder Market
Processed Foods
Asia-Pacific Food Spread Market
Processed Foods
Low-Fat Desserts to Buy Market
Processed Foods
Processed Meat Market
Processed Foods
Low Calorie Rice Pudding Market
Processed Foods
United States Food Spread Market