
 Low Moisture Food Market | 2026-2036
Low Moisture Food Market Size, Share, and Industry Trends Forecast 2026-2036
Low Moisture Food Market Analytics
The gap between premium artisanal offerings and mass-market commodity products is rebalancing as ingredient provenance and clean-label credentials split pricing power across tiers. Mondelez International leverages its global sourcing infrastructure to secure consistent nut and dried fruit supplies across multiple continents. Nestlé S.A. differentiates through specialized dehydration technologies that preserve micronutrient density in shelf-stable formats. General Mills anchors its position in retail channels with extended distribution reach into convenience stores and club formats.
Low moisture food encompasses products with water activity below 0.6, achieved through thermal dehydration, freeze-drying, or osmotic processing to inhibit microbial proliferation and extend shelf stability without refrigeration. These products serve commercial food manufacturing, institutional catering, and consumer pantry stocking where cold chain reliability remains constrained. Dehydrated fruits and nuts command the largest revenue pools due to their integration into both snacking and ingredient applications across multiple downstream sectors. Shelf-stable meals represent the fastest-expanding category as camping, military, and disaster preparedness buyers escalate procurement volumes. Snack bars occupy a mature growth trajectory with established brand loyalty but face margin compression from private-label alternatives.
The FDA enforces preventive controls under FSMA that mandate hazard analysis and risk-based preventive controls for low moisture food facilities, elevating compliance costs for smaller processors. USDA grading standards for dried fruits and nuts create quality benchmarks that shape procurement contracts between ingredient suppliers and finished goods manufacturers. ISO 22000 certification increasingly functions as a market access threshold for export-oriented producers supplying European and North American buyers. Stakeholders must monitor evolving mycotoxin testing protocols and packaging sustainability mandates as dual pressures that will reshape capital allocation toward detection technologies and recyclable barrier materials.
Market Dynamics
The FDA's FSMA preventive controls mandate hazard analysis and risk-based preventive controls across low moisture food facilities, forcing capital reallocation toward detection infrastructure and elevating compliance thresholds for smaller processors.
Growth Catalysts
- California's Central Valley processing cluster:Concentrated dehydration infrastructure and nut-drying capacity creates supply-side efficiency that attracts downstream ingredient buyers.
- Military and emergency preparedness procurement:Federal shelf-stable meal contracts are accelerating demand for retort-pouch and freeze-dried formats with 5-year stability windows.
- Clean-label credentialing:Consumer packaged goods manufacturers are sourcing dried fruits and nuts with verified origin documentation to support front-of-pack claims.
Market Restraints
- Almond and pistachio input cost volatility:California drought cycles and water allocation disputes create price instability for core ingredients.
- Single-region supply concentration:Over 80% of global almond supply originates in California's Central Valley, creating geographic risk exposure.
- Mycotoxin testing protocol fragmentation:Divergent aflatoxin limits between the FDA, EFSA, and Codex Alimentarius complicate export certification.
Strategic Opportunities
- Southeast Asia retail penetration:Indonesia and Vietnam present underdeveloped shelf-stable snack distribution with expanding convenience store networks.
- EU Green Deal packaging mandates:Recyclable barrier material requirements are creating first-mover advantage for processors investing in mono-material films.
- Camping and outdoor recreation channel expansion:Specialty retailers and direct-to-consumer subscription models are bypassing traditional grocery slotting fees.
Industry Challenges
- Food safety auditor certification backlog:FSMA-qualified individual training programs face capacity constraints, delaying facility commissioning timelines.
- Legacy drying equipment retrofit complexity:Converting thermal dehydration lines to hybrid solar-thermal configurations requires extended downtime and specialized engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Moisture Food Market |
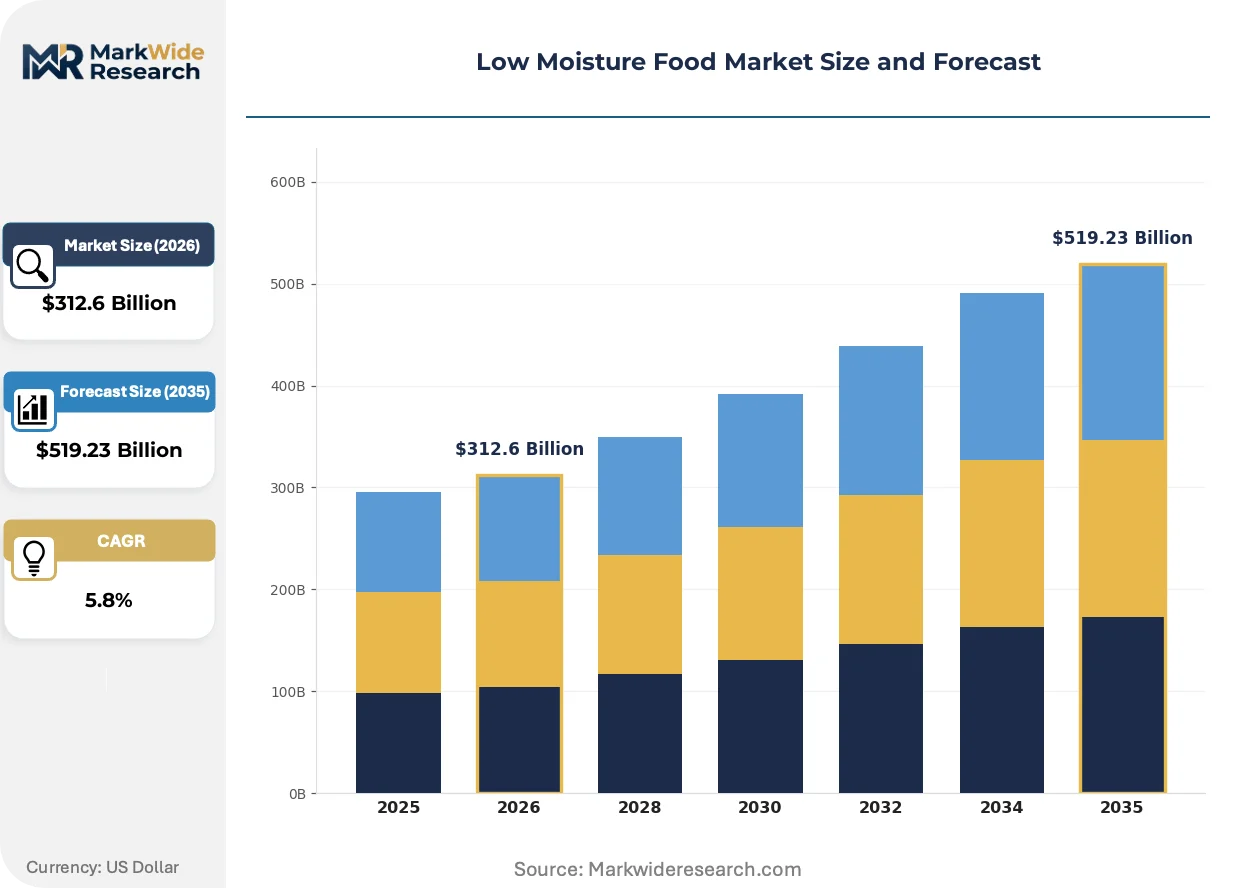
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $519.23 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dehydrated Fruits, Nuts, Shelf-Stable Meals, Snack Bars Application: Catering, Retail, Food Service, Direct Consumption End User: Households, Restaurants, Food Manufacturers, Catering Services Distribution Channel: Supermarkets, Online Retailers, Specialty Stores, Wholesale |
| Companies Covered | Mondelez International, PepsiCo, Cargill, ConAgra Foods, General Mills, Kraft Heinz, Leprino Foods, Nestlé S.A., Unilever PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Moisture Food Market Evolving Landscape
Dehydration technology, packaging material science, and procurement transparency standards are converging to redefine shelf-stable food production economics and competitive positioning.
Pulse electric field pretreatment is rewriting moisture removal kinetics in fruit and vegetable processing. Commercial adopters in California's Central Valley report 15-20% energy reduction versus conventional blanching-drying sequences. This thermal efficiency gain is compressing unit economics for mid-scale processors competing against integrated multinationals.
The EU Green Deal's packaging sustainability mandates are forcing migration from multi-layer metallized films to recyclable mono-material barriers. EFSA is accelerating novel food contact material approvals for bio-based coatings. European retail private-label buyers are now specifying recyclable packaging as a procurement gate, shifting supplier qualification criteria.
Direct-to-consumer subscription models for camping and emergency preparedness kits are displacing traditional wholesale-distributor relationships. Specialty outdoor retailers are building captive dried meal brands using co-manufacturing partnerships. This channel evolution is most visible in the United States, where REI and direct brands like Peak Refuel are capturing margin previously allocated to supermarket slotting.
Low Moisture Food Market Segmentation
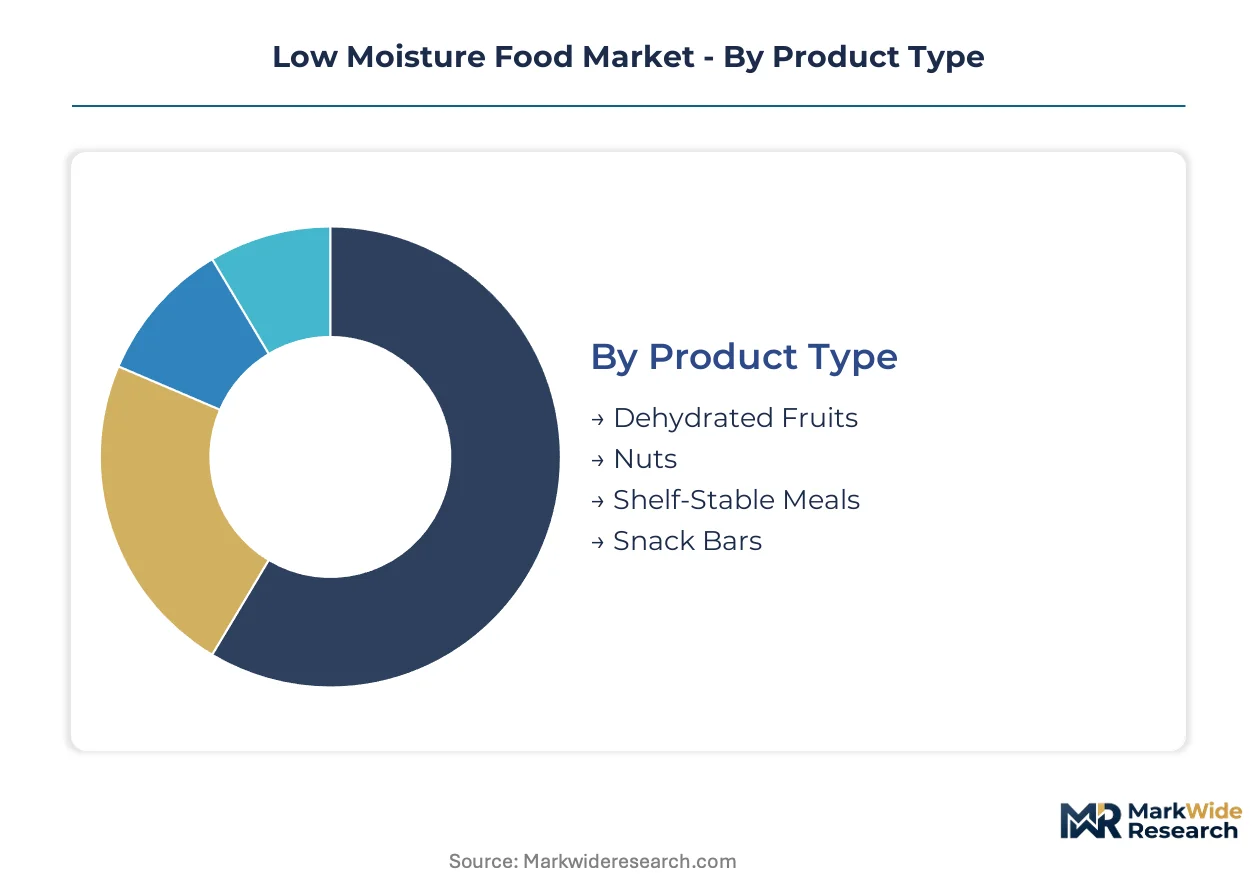
Low moisture food segmentation reflects divergent shelf-life requirements and procurement scale across institutional buyers and consumer channels. Product moisture specifications, packaging formats, and distribution logistics vary sharply between military contracts and retail snacking applications.
Product Type:
Standardization dominates commodity nuts and dehydrated fruits, while shelf-stable meals demand customized formulation for specific end-use stability windows.
- Dehydrated Fruits:Water activity below 0.6 preserves texture and flavor through thermal or osmotic processing. California's Central Valley processors supply bulk ingredients to General Mills and Mondelez for inclusion in cereal and snack applications, with procurement contracts tied to USDA grading standards.
- Shelf-Stable Meals:Retort-pouch and freeze-dried formats engineered for 5-year stability windows without refrigeration. Military and emergency preparedness buyers in the United States drive volume concentration through federal procurement contracts, with Nestlé leveraging specialized dehydration technologies to preserve micronutrient density.
- Nuts:Almond and pistachio supplies concentrate in California's Central Valley, where drought cycles create input cost volatility for processors.
- Snack Bars:Mature category with established brand loyalty facing margin compression from private-label alternatives in retail channels.
Leading the category by volume: Dehydrated Fruits. Expanding most quickly: Shelf-Stable Meals.
Application:
Cost tier separation shapes this category, with institutional catering prioritizing unit economics and retail commanding premium positioning.
- Retail:Packaged consumer goods sold through supermarkets, convenience stores, and club formats. Clean-label credentialing and verified origin documentation support front-of-pack claims, with Mondelez leveraging global sourcing infrastructure to secure consistent nut and dried fruit supplies.
- Catering:Bulk procurement for institutional meal programs requiring consistent portion control and extended shelf stability. Military and federal emergency preparedness contracts in the United States specify retort-pouch formats with defined stability windows, creating dedicated supply relationships with freeze-dried meal specialists.
- Food Service:Ingredient inputs for commercial kitchen preparation, where rehydration speed and yield consistency determine procurement decisions.
- Direct Consumption:Camping, outdoor recreation, and disaster preparedness buyers purchasing through specialty retailers and subscription models, with REI and direct brands like Peak Refuel capturing margin previously allocated to supermarket slotting.
Driving the most revenue: Retail. Steepest expansion trajectory: Direct Consumption.
End User:
Volume concentration clusters with food manufacturers, while customer type differentiation separates procurement specification rigor.
- Food Manufacturers:Industrial-scale buyers integrating dehydrated fruits and nuts into finished consumer goods. California's Central Valley processing cluster attracts downstream ingredient buyers through concentrated dehydration infrastructure and nut-drying capacity.
- Households:Consumer pantry stocking for snacking and home meal preparation, with demand shifting toward clean-label products with verified origin documentation.
- Restaurants:Commercial kitchen operators requiring consistent rehydration performance and predictable yield for menu applications.
- Catering Services:Institutional meal providers serving military bases, schools, and emergency shelters with shelf-stable procurement specifications.
Highest procurement volume: Food Manufacturers. Gaining share fastest: Households through direct-to-consumer channels.
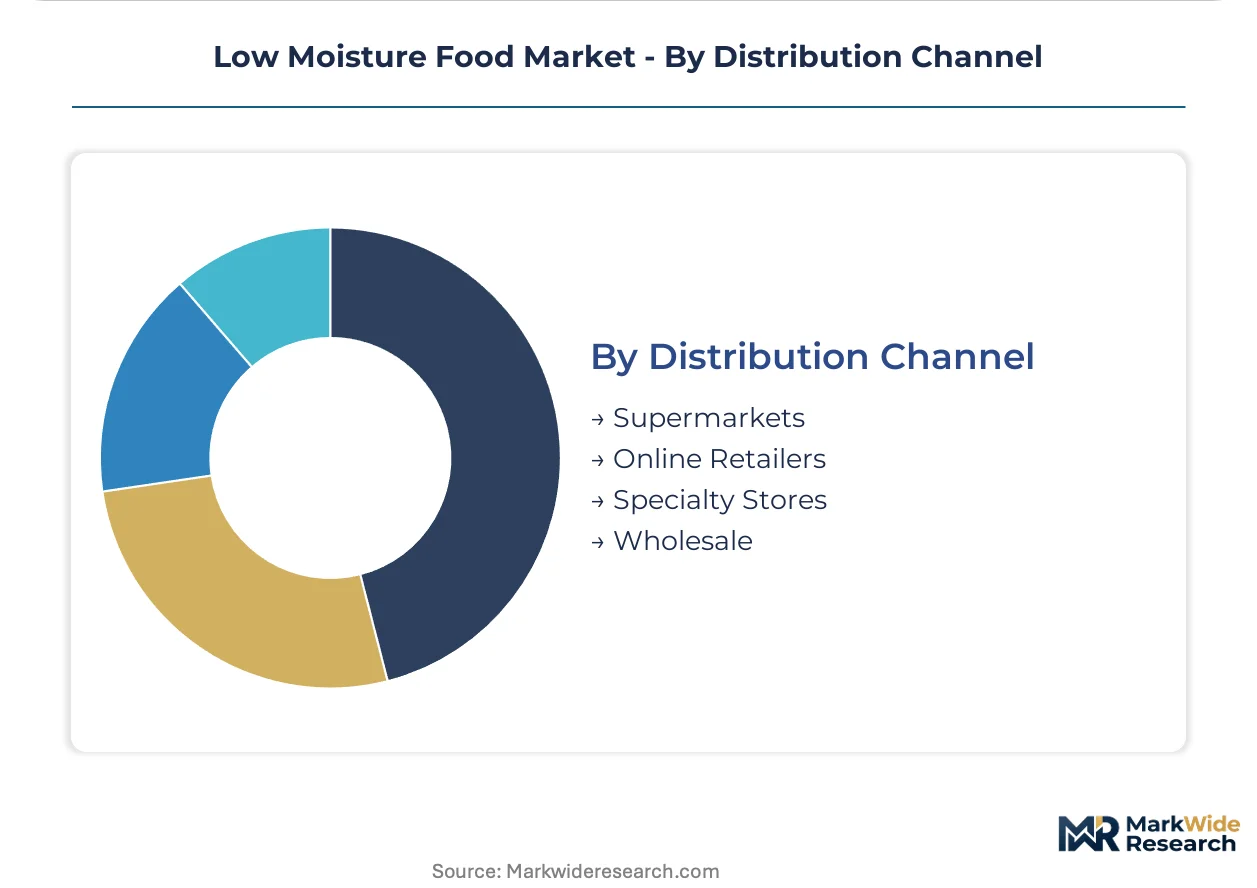
Distribution Channel:
Geographic reach and margin structure separate channel economics, with online retail compressing traditional wholesale-distributor relationships.
- Supermarkets:Dominant retail channel for branded snack bars and packaged nuts, where slotting fees and promotional spending determine shelf placement. General Mills anchors position through extended distribution reach into convenience stores and club formats.
- Online Retailers:Direct-to-consumer subscription models for camping and emergency preparedness kits displacing traditional wholesale relationships. Specialty outdoor retailers build captive dried meal brands using co-manufacturing partnerships, most visible in the United States.
- Specialty Stores:Outdoor recreation and health food retailers curating premium artisanal offerings with ingredient provenance credentials.
- Wholesale:Bulk distribution to food service and institutional buyers, where FSMA preventive controls and ISO 22000 certification function as market access thresholds.
Capturing the most volume: Supermarkets. Climbing the fastest: Online Retailers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Central Valley processing cluster anchors global dehydration infrastructure, concentrating over 80 percent of almond supply and attracting downstream ingredient buyers through integrated nut-drying capacity and established cold storage networks.
United States
Military and federal emergency preparedness procurement accelerates demand for retort-pouch and freeze-dried formats with five-year stability windows. FDA preventive controls under FSMA mandate hazard analysis across low moisture food facilities, elevating compliance costs for smaller processors. California's Central Valley dominates dehydration infrastructure, with Modesto and Fresno processing hubs supplying bulk dried fruits and nuts to national CPG manufacturers.
Germany
EU Green Deal packaging sustainability mandates force migration from multi-layer metallized films to recyclable mono-material barriers, reshaping supplier qualification criteria. EFSA accelerates novel food contact material approvals for bio-based coatings. Baden-Württemberg's industrial corridor hosts specialized drying equipment manufacturers serving Central European processors.
China
Domestic camping and outdoor recreation sectors escalate procurement of shelf-stable meals through e-commerce subscription models. SAMR enforces stricter mycotoxin testing protocols for dried fruit exports, aligning with Codex Alimentarius standards. Shandong Province's processing belt concentrates thermal dehydration capacity for regional ingredient supply.
Australia
Direct-to-consumer subscription channels for emergency preparedness kits displace traditional wholesale-distributor relationships among urban households. FSANZ maintains aflatoxin limits for nut imports that diverge from FDA thresholds, complicating cross-border certification. Victoria's Goulburn Valley hosts fruit-drying operations serving Asia-Pacific ingredient buyers.
Netherlands
Rotterdam's port logistics hub facilitates re-export of dehydrated ingredients to European food manufacturers seeking consolidated procurement. REACH compliance for packaging additives extends lead times for novel barrier material approvals. Noord-Brabant's food technology cluster develops hybrid solar-thermal drying configurations for mid-scale processors.
Low Moisture Food Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the low moisture food landscape, creating a tiered structure where integrated multinationals control upstream ingredient flows while specialty brands capture premium positioning through direct channels. The vendor base separates into three strategic archetypes: global CPG conglomerates with captive sourcing infrastructure, regional dehydration specialists serving institutional contracts, and direct-to-consumer brands leveraging co-manufacturing partnerships. Dominant competitive moves include backward integration into nut orchards and drying facilities, plus geographic expansion into Southeast Asian retail networks.
Within the multinational tier, Mondelez International and Nestlé S.A. exemplify divergent sourcing strategies—Mondelez leveraging global infrastructure to secure consistent nut and dried fruit supplies across multiple continents, while Nestlé occupies a position anchored in specialized dehydration technologies. General Mills represents the retail-channel anchor, extending distribution reach into convenience stores and club formats. These three entities illustrate how scale, technology, and channel control separate competitive positioning across premium and mass-market tiers.
| Leading Market Players |
|---|
| Mondelez International |
| PepsiCo |
| Cargill |
| ConAgra Foods |
| General Mills |
| Kraft Heinz |
| Leprino Foods |
| Nestlé S.A. |
| Unilever PLC |
| Others |
Value Network & Pricing Analysis
Federal shelf-stable meal procurement programs anchor pricing power in the United States, with military and emergency preparedness buyers negotiating multi-year contracts that compress margins for mid-scale processors competing against integrated multinationals.
Pricing Analysis
Yield-based pricing anchors procurement contracts for dehydrated fruits and nuts, with USDA grading standards creating discrete quality tiers that command 15-40% spreads between Grade A and Grade B lots. Certification tier—specifically FSMA preventive controls compliance and ISO 22000 accreditation—functions as a secondary price discriminator, with audit-ready facilities capturing premium positioning. Cost compression in commodity nuts is intensifying due to California drought cycles and water allocation disputes, while private-label snack bar alternatives are driving price erosion in retail channels. Institutional catering buyers exhibit highest price sensitivity, whereas direct-to-consumer outdoor recreation segments accept premium positioning for provenance-verified ingredients.
Supply Chain Analysis
FSMA preventive controls and ISO 22000 certification function as market access gates, filtering supplier qualification and elevating compliance costs that disadvantage smaller processors. Geographic concentration centers on the United States, Vietnam, and Turkey for dried fruit processing, with California's Central Valley hosting over 80% of global almond supply. Raw material dependencies rest on pistachio orchards, thermal energy inputs, and specialized barrier packaging films. Single-region supply concentration creates geographic risk exposure, particularly for California-sourced nuts vulnerable to drought-induced crop failures. Distribution runs through integrated CPG conglomerates with captive sourcing infrastructure, regional dehydration specialists serving institutional contracts, and direct-to-consumer brands leveraging co-manufacturing partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pulse electric field pretreatment is displacing conventional blanching-drying sequences, rewriting moisture removal kinetics and compressing unit economics for processors that fail to retrofit legacy thermal dehydration lines.
For Market Incumbents: Anticipate margin compression from private-label alternatives and energy-efficient processing technologies by securing backward integration into California nut orchards and investing in hybrid solar-thermal drying configurations that reduce thermal energy dependencies. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription models targeting camping and outdoor recreation channels in Indonesia and Vietnam, where underdeveloped shelf-stable snack distribution and expanding convenience store networks create white-space penetration opportunities without traditional grocery slotting fee barriers. For Investors and Strategic Acquirers: The window for entry favors regional dehydration specialists with FSMA-compliant facilities and established military procurement relationships, with long-term viability hinging on packaging sustainability transitions; monitor EU Green Deal packaging mandate implementation timelines as the inflection signal for recyclable barrier material adoption curves.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nut Orchards | Captive almond and pistachio supply secures margin control against California drought volatility. |
| Hybrid Solar-Thermal Drying Retrofit | Pulse electric field pretreatment compatibility reduces thermal energy inputs by 15-20% versus conventional lines. |
| Recyclable Mono-Material Packaging Transition | EU Green Deal compliance creates first-mover qualification advantage with European retail private-label buyers. |
| Direct-to-Consumer Channel Expansion | Subscription models for camping kits bypass supermarket slotting fees and capture margin from REI-style specialty retailers. |
| Southeast Asia Distribution Partnership | Indonesia and Vietnam convenience store networks offer underpenetrated shelf-stable snack growth corridors. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, with primary interviews conducted among dehydration plant managers, military procurement officers, retail category buyers, nut orchard operators, and packaging material suppliers. FDA FSMA guidance documents, USDA grading standards, EFSA food contact material approvals, and ISO 22000 certification databases provided regulatory benchmarks. Bottom-up modeling of processor capacity and top-down reconciliation against CPG manufacturer procurement disclosures ensured cross-validation.
Segment-level volume and value estimates were reconciled across product type, application, end user, and distribution channel dimensions, with growth trajectories derived from procurement contract visibility and capacity expansion announcements. Input assumptions incorporated thermal energy cost curves, almond yield volatility patterns, and barrier packaging material transition timelines.
California water allocation disputes, mycotoxin testing protocol fragmentation, and EU packaging sustainability mandate acceleration are the dominant revision risks to modeled outputs. A model refresh is warranted upon material change in federal shelf-stable meal procurement volumes or FSMA enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
US Tomato Paste Market
Processed Foods
Processed Mango Products Market
Processed Foods
United States Processed Meat Market
Processed Foods
US Processed Pumpkin Market
Processed Foods
Artisanal Ice Cream Market
Processed Foods
Porridge Market
Processed Foods
Accompanying Marinated Product Market
Processed Foods
Processed Beef Market
Processed Foods
South America Processed Meat Market
Processed Foods
Africa Soup Market
Processed Foods
China Freeze-Dried Food Market
Processed Foods
South America Soup Market
Processed Foods
Asia-Pacific Ice Cream Market
Processed Foods
Global Potato Flake Market
Processed Foods
Mashed Potatoes Market
Processed Foods
Margarine Market