
 Low-Fat Desserts to Buy Market | 2026-2036
Low-Fat Desserts to Buy Market Size, Share, and Industry Trends Forecast 2026-2036
Low-Fat Desserts to Buy Market Analytics
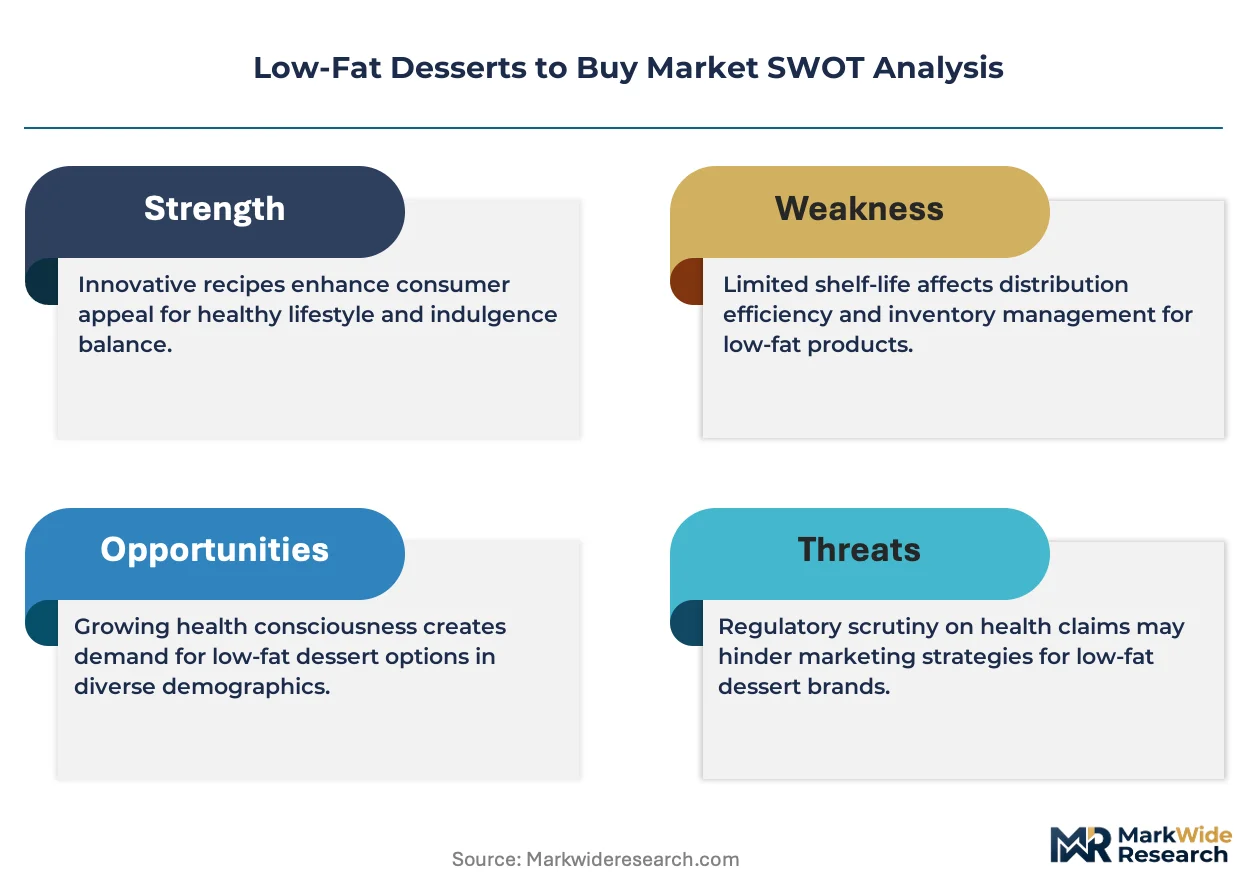
The low-fat desserts category is restructuring around a sharp split between premium artisan positioning and mass-market commodity pricing. Halo Top leverages its high-protein, low-calorie formulation legacy to sustain brand loyalty in the premium frozen segment. Yasso competes through Greek yogurt-based frozen bars that anchor its differentiation in the better-for-you ice cream alternative space. Simple Mills specializes in clean-label baking mixes and ready-to-eat treats, occupying a distinct niche for grain-free, low-fat dessert options in specialty retail channels.
Low-fat desserts to buy are commercially prepared sweet products formulated with reduced fat content, typically achieving less than three grams of fat per serving through modified emulsification systems, fat replacers such as maltodextrin or modified food starch, and adjusted aeration processes that maintain mouthfeel and structural integrity. These products serve consumers seeking indulgence within controlled macronutrient frameworks, particularly in weight management and cardiovascular health contexts. The ice cream segment leads absolute volume due to established freezer infrastructure and habitual purchase patterns, while dairy-free formulations represent the fastest-growing ingredient category as lactose intolerance awareness and plant-based dietary shifts expand the addressable consumer base. Sugar substitute formulations command premium shelf positioning and higher margin pools in health stores and online retail, where ingredient transparency drives purchase decisions more acutely than in conventional supermarkets.
The FDA governs nutrition labeling and health claims for low-fat products sold in the United States, while the USDA oversees dairy ingredient standards that affect formulation pathways for frozen desserts containing milk derivatives. The EPA regulates wastewater and emissions from dairy processing facilities, indirectly shaping production cost structures for manufacturers relying on conventional milkfat reduction rather than plant-based alternatives. Stakeholders must monitor evolving FDA guidance on acceptable sugar substitute labeling and anticipate how state-level sugar taxation proposals could redirect demand toward whole grain and fruit-based dessert formats.
Market Dynamics
The FDA's updated nutrition labeling requirements for added sugars are forcing manufacturers to reformulate legacy recipes while maintaining the sensory profiles consumers expect from indulgent desserts.
Growth Catalysts
- Gen Z purchasing concentration:Health-conscious younger consumers in urban supermarkets are accelerating purchases of refrigerated low-fat desserts, creating volume pull in coastal metropolitan clusters.
- Plant-based ingredient innovation:Dairy-free formulations using oat and almond protein bases are expanding the addressable consumer base among lactose-intolerant and flexitarian dietary segments.
- USDA dairy standard alignment:Manufacturers leveraging modified food starch and maltodextrin fat replacers within USDA ingredient guidelines can access federal procurement channels and school nutrition programs.
Market Restraints
- Sugar substitute cost volatility:Stevia and monk fruit extract pricing fluctuations compress margins for clean-label formulations positioned in premium health retail channels.
- Freezer infrastructure concentration:Cold chain distribution capacity clusters in Northeast and West Coast metropolitan corridors, limiting shelf access for emerging brands in interior markets.
- Clean-label technical ceiling:Consumer rejection of modified food starch and polydextrose in ingredient panels constrains texture engineering options for sub-three-gram fat targets.
Strategic Opportunities
- Functional ingredient convergence:Collagen-fortified and probiotic-enhanced dessert formats targeting beauty-from-within and gut health positioning command premium shelf placement in specialty retail.
- Direct-to-subscription channel expansion:Frozen dessert subscription boxes bypass conventional retail slotting fees and build predictable recurring revenue streams among wellness-focused households.
- State sugar taxation arbitrage:Manufacturers in jurisdictions without beverage and dessert sugar taxes can price-compete against conventional full-fat alternatives in adjacent categories.
Industry Challenges
- Reformulation talent scarcity:Food scientists with expertise in aeration process modification and emulsification system balancing for reduced-fat matrices command premium compensation in competitive labor markets.
- Dual certification complexity:USDA Organic and Non-GMO Project verification timelines extend product launch windows by eight to fourteen months, delaying revenue recognition for seasonal flavor introductions.
- Legacy equipment retrofit costs:Continuous freezer systems designed for full-fat ice cream require capital-intensive reconfiguration to handle lower-viscosity low-fat and dairy-free bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low-Fat Desserts to Buy Market |
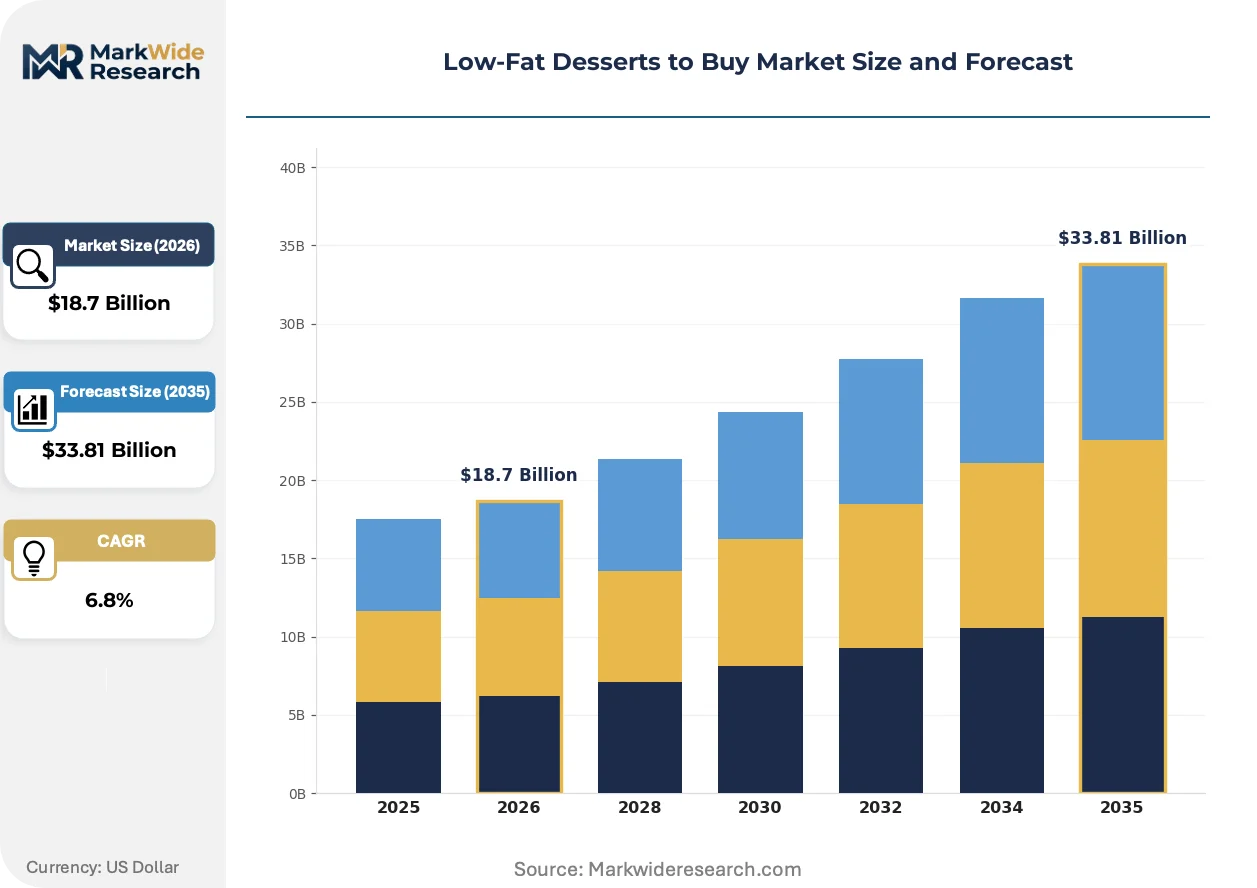
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mousse, Pudding, Cake, Ice Cream Ingredient Type: Fruit-Based, Dairy-Free, Sugar Substitute, Whole Grain Packaging Type: Cups, Boxes, Individual Portions, Multipacks Distribution Channel: Supermarkets, Online Retail, Health Stores, Specialty Shops |
| Companies Covered | Yasso, Halo Top, Enlightened, Simple Mills, SmartSweets, Tony’s Chocolonely, GoodPop, Fiber One, Talenti, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-Fat Desserts to Buy Market Evolving Landscape
Reformulation science and distribution technology are compressing the gap between indulgent sensory experience and controlled macronutrient targets. Three developments are restructuring competitive positioning.
Precision fermentation-derived dairy proteins are converging with conventional emulsification systems to replicate the crystallization behavior of milkfat without the caloric density. Premium frozen dessert manufacturers in California and New York metropolitan markets are adopting these ingredients at accelerated pilot scales. This convergence is enabling structural integrity in sub-three-gram fat formulations previously achievable only through synthetic fat replacers.
The FDA's updated guidance on added sugars disclosure is compressing formulation timelines for manufacturers dependent on conventional sucrose reduction strategies. Industrial consequence includes accelerated R&D investment in allulose and erythritol blend optimization. The ice cream segment is responding most aggressively, with coastal manufacturers reformulating core SKUs ahead of enforcement windows.
Urban millennial households are consolidating weekly dessert purchases into single-category stock-up trips rather than impulse convenience store acquisitions. This behavioral shift is disrupting traditional convenience channel distribution and elevating e-commerce frozen fulfillment infrastructure. The pattern is most visible in Seattle, San Francisco, and Austin metropolitan clusters where refrigerated last-mile delivery density supports subscription model viability.
Low-Fat Desserts to Buy Market Segmentation
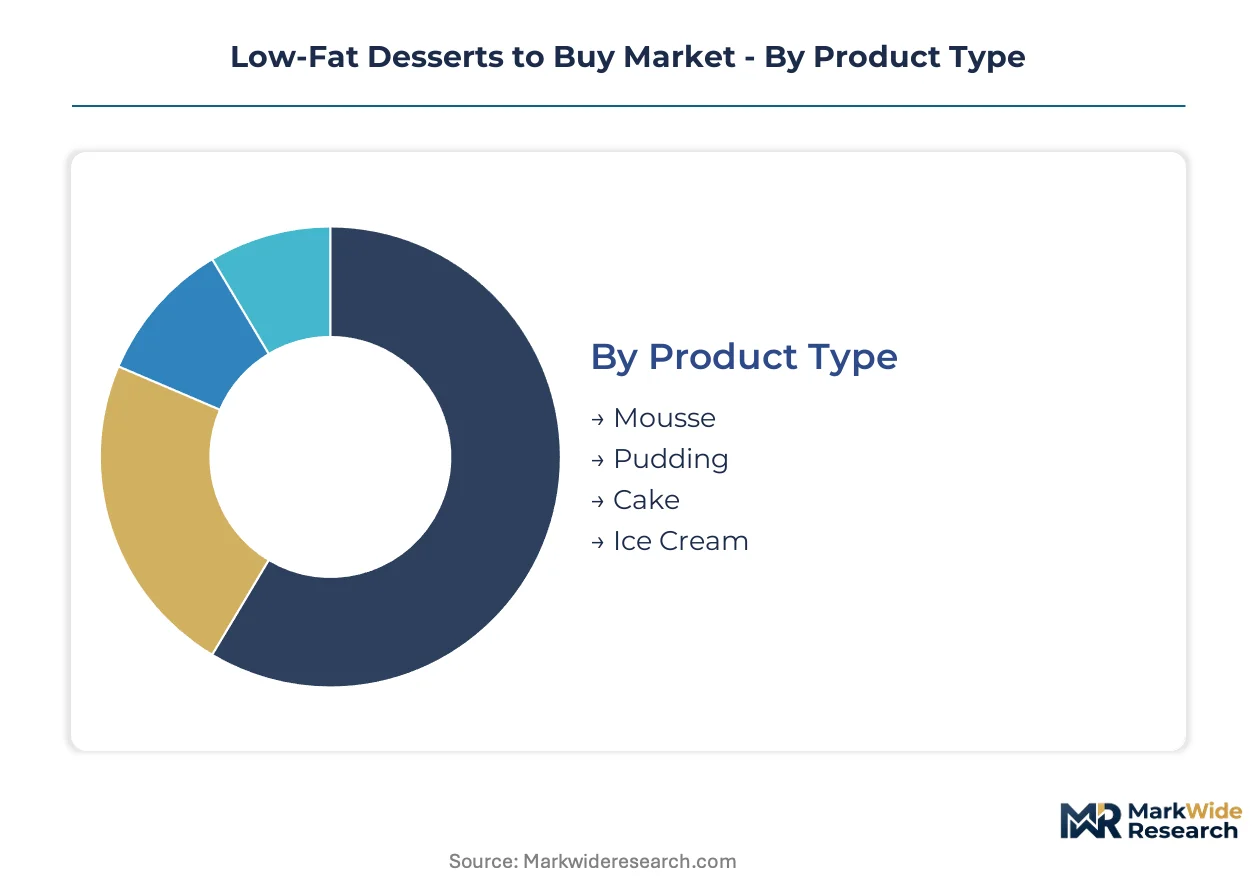
Segmentation in low-fat desserts reveals how formulation science, packaging economics, and channel access intersect to determine margin capture. Manufacturers must align product architecture with freezer infrastructure constraints and ingredient certification requirements that vary by retail tier.
Product Type:
Supply concentration in frozen manufacturing equipment favors high-volume formats with established cold chain distribution.
- Ice Cream:Aeration process engineering and modified emulsification systems deliver sub-three-gram fat targets while maintaining crystallization stability. Demand clusters in coastal metropolitan supermarkets with dedicated freezer aisle positioning, though legacy continuous freezer retrofit costs constrain new entrants.
- Cake:Shelf-stable formulations using whole grain bases and fruit purees bypass freezer infrastructure entirely. Health stores in Austin and Seattle metropolitan areas are expanding refrigerated cake placements for immediate consumption occasions.
- Mousse:Aerated dairy or plant-protein structures requiring precise temperature control throughout distribution.
- Pudding:Refrigerated cup formats with modified food starch stabilization for creamy texture at reduced fat content.
Today's leader: Ice Cream. Tomorrow's challenger: Cake.
Ingredient Type:
Cost tier stratification separates premium clean-label formulations from commodity fat-replacer dependent products.
- Sugar Substitute:Allulose and erythritol blends command premium shelf positioning in specialty retail, though stevia and monk fruit extract pricing volatility compress margins. The FDA's updated added sugars disclosure requirements are accelerating R&D investment in these formulations among coastal manufacturers.
- Dairy-Free:Oat and almond protein bases are expanding the addressable consumer base among lactose-intolerant and flexitarian dietary segments. Urban millennial households in San Francisco and New York are driving volume pull for these formulations.
- Fruit-Based:Natural sweetness and fiber content reduce dependence on synthetic fat replacers for structural integrity.
- Whole Grain:Clean-label positioning that satisfies USDA school nutrition program procurement standards.
Sugar Substitute captures current premium positioning. Dairy-Free is climbing the fastest as plant-based dietary shifts deepen.
Packaging Type:
Volume economics and last-mile delivery density determine which formats support profitable distribution.
- Individual Portions:Single-serve cups and bars align with urban millennial consolidation of weekly dessert purchases into stock-up trips. E-commerce frozen fulfillment infrastructure in Seattle and Austin metropolitan clusters supports subscription model viability for this format.
- Multipacks:Family-size configurations reduce per-unit packaging cost and support price competition in conventional supermarkets. Cold chain distribution capacity concentration in Northeast and West Coast corridors limits shelf access for emerging brands in interior markets.
- Cups:Standard refrigerated dessert container with established manufacturing equipment base.
- Boxes:Frozen novelty and cake formats requiring structural protection through distribution.
Multipacks dominate conventional channel volume. Individual Portions are gaining share fastest through direct-to-subscription expansion.
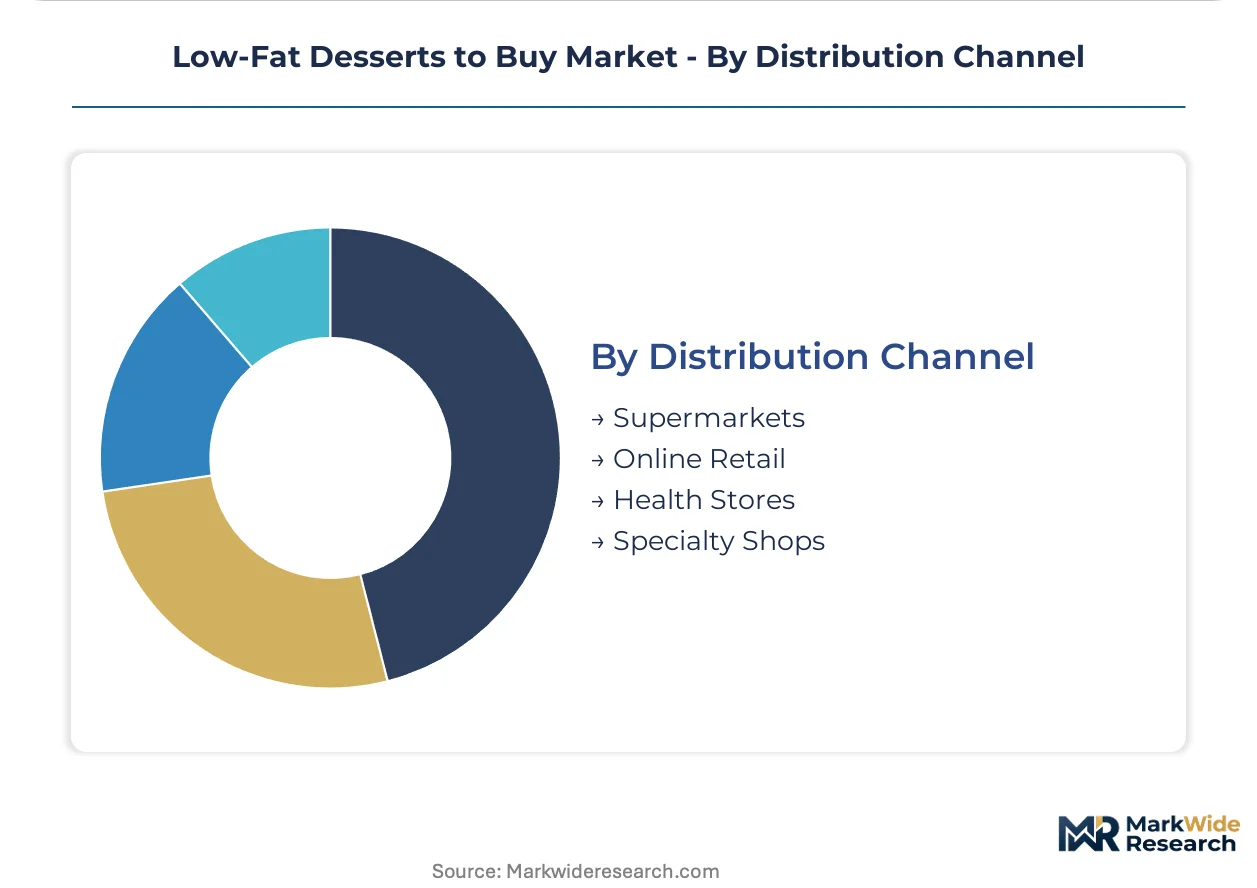
Distribution Channel:
Customer type stratification separates wellness-focused ingredient transparency seekers from convenience-driven mass market purchasers.
- Supermarkets:Coastal metropolitan stores with established wellness retail infrastructure are accelerating refrigerated low-fat dessert placements. Gen Z purchasing concentration in these urban locations creates volume pull for both premium and mass-market tiers.
- Online Retail:Frozen dessert subscription boxes bypass conventional retail slotting fees and build predictable recurring revenue streams. Last-mile delivery density requirements restrict viable operations to metropolitan clusters with sufficient household concentration.
- Health Stores:Specialty retail where ingredient transparency drives purchase decisions more acutely than in conventional supermarkets.
- Specialty Shops:Artisan and premium positioning with limited geographic reach but higher margin capture.
Supermarkets anchor absolute volume. Online Retail presents the steepest expansion trajectory as refrigerated fulfillment infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food scientists specializing in aeration process modification and emulsification system balancing command premium compensation in competitive labor markets across coastal metropolitan clusters. This talent concentration anchors production capacity in jurisdictions with established wellness retail infrastructure and cold chain distribution density.
United States
Gen Z purchasing concentration in urban supermarkets accelerates refrigerated low-fat dessert volume pull, particularly in Seattle, San Francisco, and Austin metropolitan clusters. The FDA governs nutrition labeling and health claims for low-fat products while the USDA oversees dairy ingredient standards affecting formulation pathways. Coastal metropolitan areas with higher disposable incomes concentrate demand for premium and mass-market tiers alike.
Canada
Health-conscious millennial households in Toronto and Vancouver metropolitan areas drive demand for clean-label frozen dessert formats. Health Canada and the PMRA regulate ingredient safety and labeling requirements for reduced-fat sweet products. Cold chain distribution infrastructure concentrates in Ontario and British Columbia, supporting refrigerated last-mile delivery density for subscription model viability.
United Kingdom
Urban consumers in London and Manchester metropolitan clusters demonstrate heightened ingredient transparency preferences in specialty retail channels. The Food Standards Agency enforces nutrition labeling requirements while the Competition and Markets Authority monitors pricing practices. Premium frozen dessert manufacturers pilot precision fermentation-derived dairy proteins in Greater London production facilities.
Germany
Flexitarian dietary shifts in Berlin and Munich urban centers expand the addressable consumer base for dairy-free formulations using oat and almond protein bases. The Federal Office of Consumer Protection and Food Safety (BVL) oversees food labeling compliance under EU framework regulations. Bavaria and North Rhine-Westphalia host manufacturing facilities leveraging modified food starch fat replacers within established dairy processing infrastructure.
Australia
Lactose intolerance awareness in Sydney and Melbourne metropolitan areas drives volume pull for plant-based dessert alternatives. Food Standards Australia New Zealand (FSANZ) governs nutrition content claims and health-related statements on packaged foods. New South Wales and Victoria concentrate refrigerated fulfillment infrastructure supporting direct-to-subscription channel expansion among wellness-focused households.
Low-Fat Desserts to Buy Market Competitive Landscape
Capital-heavy producers with captive freezer infrastructure and continuous processing equipment compete with asset-light designers outsourcing manufacturing to third-party co-packers. The market structure splits between consolidated multinational dairy processors and fragmented specialty brands occupying premium positioning tiers. Three archetypes dominate: legacy ice cream manufacturers with reformulated low-fat line extensions, venture-backed clean-label startups leveraging direct-to-consumer distribution, and private-label suppliers serving conventional supermarket channels. Competitive moves concentrate on portfolio diversification into functional ingredient formats and geographic expansion through refrigerated e-commerce fulfillment partnerships.
Within the premium frozen segment, Halo Top and Yasso exemplify archetype differentiation through formulation philosophy rather than manufacturing scale. Halo Top occupies a position anchored in high-protein, low-calorie legacy positioning, while Yasso represents Greek yogurt-based structural alternatives in the better-for-you ice cream space. Simple Mills sits within the clean-label baking specialist tier, occupying grain-free, low-fat positioning in specialty retail channels where ingredient transparency drives purchase decisions more acutely than in conventional supermarkets.
| Leading Market Players |
|---|
| Yasso |
| Halo Top |
| Enlightened |
| Simple Mills |
| SmartSweets |
| Tony's Chocolonely |
| GoodPop |
| Fiber One |
| Talenti |
| Others |
Value Network & Pricing Analysis
Premium clean-label certification ladders diverge sharply from commodity fat-replacer tiers, compressing margins at the mid-market while concentrating pricing power among USDA Organic and Non-GMO Project verified producers. This bifurcation manifests in supply chain configurations where certified ingredient sourcing and dedicated cold chain capacity anchor premium positioning, while modified food starch dependent formulations compete on scale economics through conventional retail slotting.
Pricing Analysis
Subscription bundling versus transactional per-unit purchasing splits the market into recurring revenue and impulse-buy segments. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and ingredient transparency intensity, with stevia and monk fruit extract volatility squeezing clean-label margins. Pricing pressure stems from sugar substitute cost fluctuations and freezer infrastructure slotting fees in coastal metropolitan clusters. Mass-market conventional supermarket purchasers exhibit highest price sensitivity, while wellness-focused direct-to-subscription households accept premium positioning for functional ingredient formats.
Supply Chain Analysis
Regional distribution centers in California, New York, and Texas anchor hub-and-spoke cold chain patterns for frozen dessert fulfillment. Manufacturing concentration in the United States draws from oat and almond protein suppliers, precision fermentation-derived dairy protein innovators, and modified food starch producers. Single-source vulnerability runs through stevia and monk fruit extract suppliers facing agricultural yield variability. Distribution runs through supermarket freezer aisle slotting, direct-to-subscription refrigerated last-mile networks, and health store specialty retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The low-fat desserts market compounds steadily as health-conscious generational cohorts normalize controlled macronutrient indulgence across weekly consumption rituals.
For Market Incumbents: Deploy precision fermentation ingredient partnerships to defend clean-label positioning against emerging plant-protein specialists. Expand captive cold chain capacity in Austin and Seattle metropolitan clusters to preempt subscription channel entrants. Reformulation talent scarcity in aeration process engineering threatens margin compression for legacy continuous freezer operators. For New Entrants and Emerging Players: Direct-to-subscription fulfillment partnerships offer the most penetrable white-space for asset-light brands bypassing conventional retail slotting barriers. Target interior metropolitan markets with underdeveloped refrigerated last-mile density, where emerging brands can establish subscription household concentration before incumbent freezer infrastructure expansion. White-label co-packer relationships with USDA-certified facilities accelerate speed-to-shelf for seasonal flavor introductions. For Investors and Strategic Acquirers: Asymmetric upside sits with venture-backed clean-label startups possessing direct-to-consumer subscriber bases and precision fermentation ingredient pipelines. Five-to-ten year viability favors brands with functional ingredient convergence capabilities in collagen fortification and probiotic enhancement. Watch FDA guidance evolution on added sugars disclosure enforcement as inflection signal for reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Partnership | Enables structural integrity in sub-three-gram fat formulations without synthetic fat replacers. |
| Direct-to-Subscription Launch | Bypasses conventional retail slotting fees and builds predictable recurring revenue among wellness households. |
| USDA Organic Certification Investment | Opens federal procurement channels and school nutrition program access for compliant manufacturers. |
| Cold Chain Capacity Expansion | Secures freezer aisle positioning in coastal metropolitan clusters with highest Gen Z purchasing concentration. |
| Functional Ingredient Convergence | Collagen and probiotic fortification commands premium shelf placement in specialty retail channels. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with food science R&D directors, retail category buyers, cold chain logistics operators, and subscription fulfillment specialists with secondary validation. FDA guidance documents, USDA procurement databases, Nielsen retail audit data, and customs records on stevia and monk fruit extract imports anchored bottom-up and top-down triangulation.
Segment-weighting approaches modeled product type, ingredient category, packaging format, and distribution channel dimensions across the analysis window. CAGRs derived from volume trajectory modeling against disposable income elasticity in coastal metropolitan clusters, with precision fermentation adoption curves and generational cohort purchasing pattern shifts as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA enforcement timing on added sugars disclosure, state-level sugar taxation proposals, and precision fermentation scale-up economics. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Asia-Pacific Soup Market
Processed Foods
Fat Free Food Market
Processed Foods
United States Fresh Noodles Market
Processed Foods
India Ready to Mix Food Market
Processed Foods
Global Potato Flake Market
Processed Foods
Tomato Paste Market
Processed Foods
Processed Cashew Market
Processed Foods
Processed Mango Products Market
Processed Foods
Low Moisture Food Market
Processed Foods
North America Soup Market
Processed Foods
Low Calorie Rice Pudding Market
Processed Foods
Europe Egg Powder Market
Processed Foods
Ready to Cook Market
Processed Foods
Block Margarine Market
Processed Foods
Low Fat Pasta Market
Processed Foods
Coffee Creamer Market