
 Xylitol Injection Market | 2026-2036
Xylitol Injection Market Size, Share, and Industry Trends Forecast 2026-2036
Xylitol Injection Market Insights
MDR sterility assurance requirements are decoupling small-batch compounders from scaled pharmaceutical manufacturers, reshaping the cost-of-entry calculus for European and North American markets. Pfizer Inc. leverages its sterile injectable infrastructure across multiple FDA-inspected sites to maintain supply continuity for hospital formularies. Fresenius Kabi AG anchors its position through vertical control over parenteral nutrition compounding, integrating xylitol into broader metabolic support portfolios. Baxter International Inc. competes on blow-fill-seal technology leadership, reducing particulate contamination risks that regulators now scrutinize more intensively.
Xylitol injection denotes a sterile, pyrogen-free parenteral solution containing the five-carbon sugar alcohol C5H12O5, manufactured via catalytic hydrogenation of xylose derived from hemicellulose hydrolysis, with osmolarity typically adjusted to 260-320 mOsm/L for intravenous compatibility. The formulation serves primarily as an alternative carbohydrate substrate in parenteral nutrition, offering lower glycemic index than dextrose for diabetic and stress-hyperglycemic patients. Single-dose vials capture the dominant share of hospital procurement due to reduced contamination risk and simplified inventory management, while multi-dose vials retain relevance in cost-constrained clinic settings where dosing frequency justifies preservative systems. IV therapy applications are expanding fastest as anesthesiology protocols adopt xylitol-containing perioperative fluids to modulate insulin response, though clinical nutrition remains the mature revenue base with established reimbursement pathways.
FDA current Good Manufacturing Practice enforcement and EMA's revised guidelines on elemental impurities in parenteral products are tightening analytical requirements for xylitol raw material sourcing, directly shaping supplier qualification timelines and batch release protocols. The country's national pharmaceutical regulator in India and CDSCO are aligning injectable standards with ICH Q3D guidelines, creating harmonized entry barriers for exporters targeting multiple jurisdictions. Stakeholders must monitor evolving pharmacopeial monograph revisions for xylitol purity specifications, as USP-NF and EP convergence on residual solvent limits will determine which manufacturers can sustain cross-border supply without dual qualification investments.
Market Dynamics
MDR sterility assurance requirements are decoupling small-batch compounders from scaled pharmaceutical manufacturers, reshaping the cost-of-entry calculus for European and North American markets. The FDA's tightened sterility testing protocols and EMA's revised guidelines on elemental impurities are forcing raw material suppliers to requalify sourcing networks.
Growth Catalysts
- Enhanced Recovery After Surgery protocols:Ambulatory surgical centers in the United States are integrating xylitol infusions into perioperative glycemic management, creating pull-through demand for parenteral formulations.
- EMA MDR compliance deadlines:The Medical Device Regulation's sterility assurance requirements are accelerating hospital pharmacy consolidation around qualified sterile injectable suppliers with validated aseptic processing.
- Catalytic hydrogenation advances:Improved xylose purification from hemicellulose hydrolysis is reducing residual aldehyde contaminants in pharmaceutical-grade xylitol feedstock.
Market Restraints
- Elemental impurity testing costs:ICH Q3D compliance for arsenic, cadmium, and lead screening in parenteral-grade xylitol is adding analytical overhead that disadvantages smaller API manufacturers.
- Single-source hemicellulose supply:Birch and beech wood hydrolysate concentration in Nordic and Baltic regions creates geographic vulnerability to pulp mill capacity fluctuations.
- Dextrose substitution inertia:Established reimbursement pathways for glucose-based parenteral nutrition slow formulary adoption of alternative carbohydrate substrates despite glycemic advantages.
Strategic Opportunities
- Indian CDSCO alignment with ICH:The country's national pharmaceutical regulator is harmonizing injectable standards, opening export pathways for domestic manufacturers targeting regulated markets.
- Perioperative fluid expansion:Anesthesiology departments are adopting xylitol-containing solutions for insulin response modulation during cardiac and bariatric procedures.
- Blow-fill-seal technology adoption:Continuous aseptic manufacturing systems are enabling particulate reduction that satisfies FDA intensified inspection focus.
Industry Challenges
- Compendial monograph divergence:USP-NF and EP residual solvent specifications for xylitol are not fully aligned, forcing dual qualification investments for cross-border suppliers.
- Aseptic processing workforce scarcity:Qualified personnel for sterile injectable manufacturing are concentrating at established FDA-inspected sites, constraining capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Xylitol Injection Market |
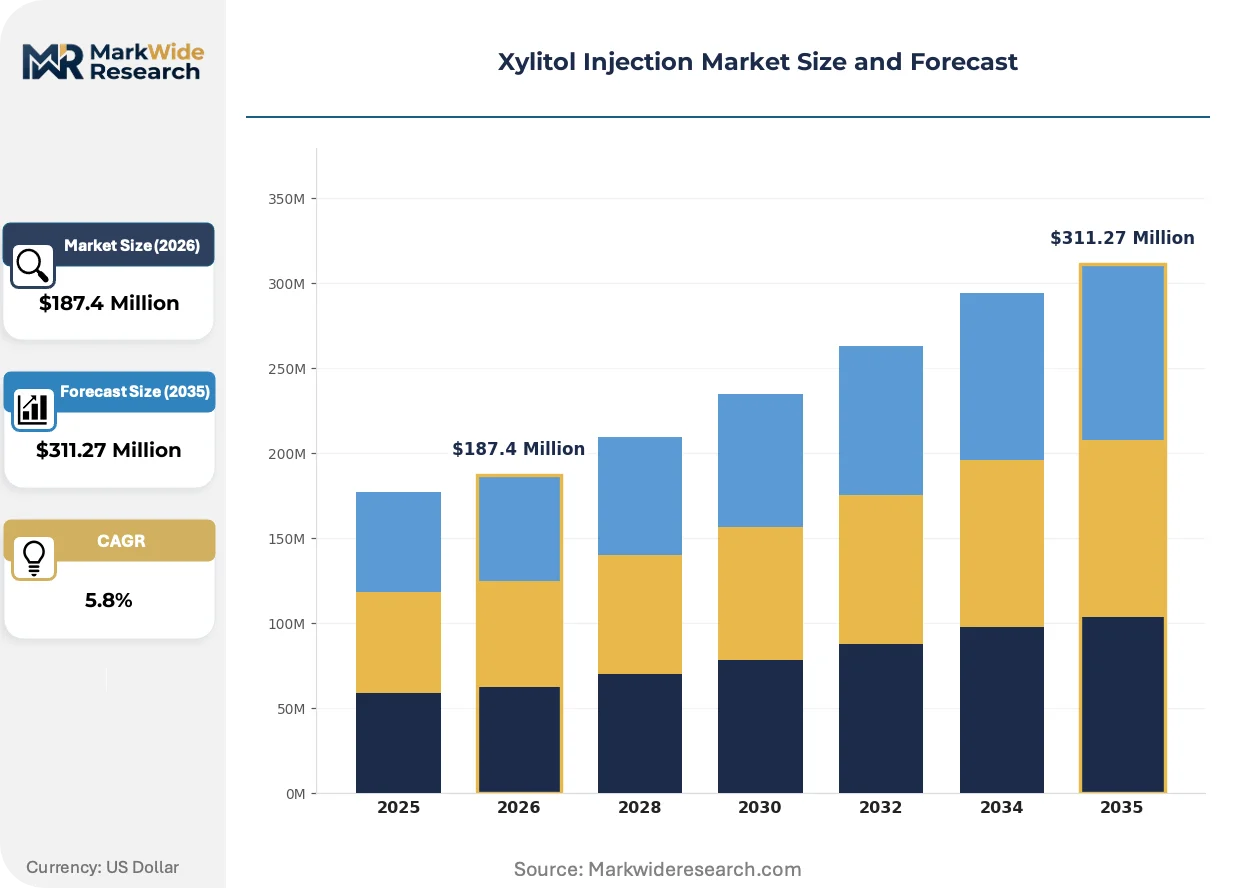
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sterile Injection, Single-Dose Vials, Multi-Dose Vials, Ampoules End User: Hospitals, Clinics, Home Healthcare, Research Laboratories Application: Clinical Nutrition, Oral Health, IV Therapy, Pain Management Packaging Type: Plastic Bottles, Glass Vials, Blister Packs, Sachets |
| Companies Covered | Pfizer Inc., Merck & Co., Inc., Fresenius Kabi AG, Teva Pharmaceutical Industries Ltd., Baxter International Inc., Sanofi, Hikma Pharmaceuticals PLC, Endo International plc, Mylan N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Xylitol Injection Market Trends and Innovations
Continuous manufacturing technologies and real-time release testing are compressing batch cycle times while regulatory scrutiny of particulate contamination intensifies across parenteral product categories.
Single-use bioreactor systems for xylitol catalytic hydrogenation are decentralizing production scale economics, allowing mid-volume manufacturers to achieve pharmaceutical-grade output without fixed stainless-steel infrastructure. Regional compounders in Germany and Switzerland are adopting these disposable technologies to serve hospital consortia with shortened supply chains. The shift is compressing minimum efficient scale thresholds and enabling distributed manufacturing networks that reduce transport-related stability risks.
EMA's revised guidelines on elemental impurities in parenteral products are mandating ICP-MS screening for catalyst residues across all xylitol API batches destined for European hospital formularies. The regulation is forcing raw material suppliers to document supply chain provenance back to hemicellulose source forests. Manufacturers without validated impurity profiling capabilities are exiting the qualified supplier pool, concentrating procurement relationships on analytical-capable producers.
Hospital pharmacy consortia are consolidating procurement around sole-source agreements with vertically integrated manufacturers capable of batch-specific CoA documentation. Group purchasing organizations in the United States are displacing fragmented multi-vendor sourcing with multi-year contracts tied to sterility assurance data packages. The concentration is most visible in integrated delivery networks across Texas and California, where formulary committees now require FDA establishment inspection history as a gatekeeping criterion.
Xylitol Injection Market Segmentation
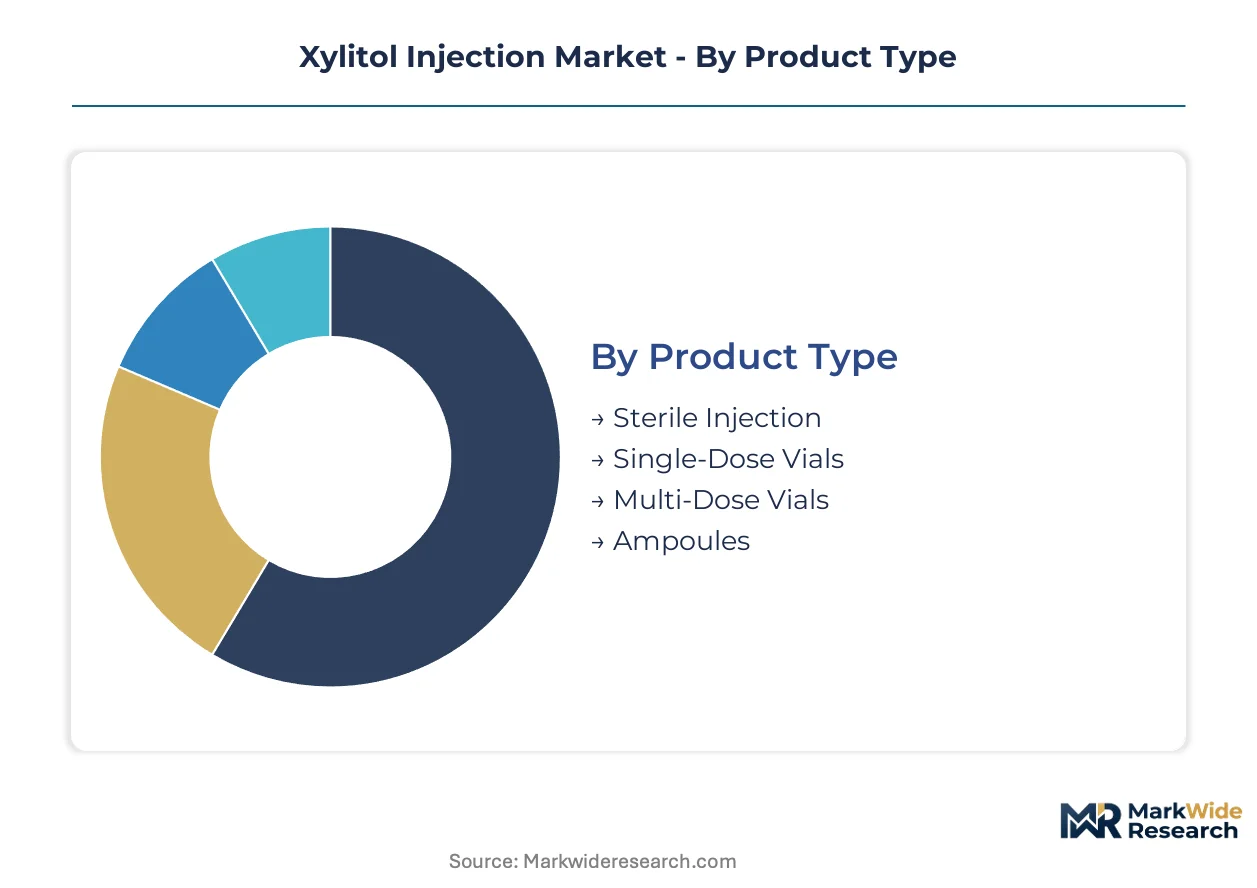
Xylitol injection procurement patterns diver sharply across delivery formats and care settings. Hospital formulary committees prioritize contamination risk profiles and inventory velocity when segmenting supplier contracts.
Product Type:
Upgrade cycles from multi-dose to single-dose formats are accelerating as sterility assurance requirements tighten across regulated markets.
- Single-Dose Vials:Sealed unit-dose glass or polymer containers eliminate preservative requirements and cross-contamination pathways. Demand concentrates in United States ambulatory surgical centers where FDA inspection history determines supplier qualification.
- Sterile Injection:Bulk parenteral solutions in flexible containers serve compounding pharmacy networks. German hospital consortia are consolidating procurement around blow-fill-seal manufactured lots with real-time particulate monitoring.
- Multi-Dose Vials:Preservative-containing formats retain cost advantages for high-volume clinic settings with controlled dosing frequencies.
- Ampoules:Score-neck glass units persist in emergency medicine kits where immediate break-seal access outweighs handling fragility.
Volume placements concentrate in Single-Dose Vials; the faster expansion belongs to Sterile Injection as integrated delivery networks seek compounding efficiencies.
End User:
Cost tier stratification separates capital-intensive hospital systems from resource-constrained outpatient facilities.
- Hospitals:Tier-one medical centers command batch-specific CoA documentation and validated aseptic processing data. Texas and California integrated delivery networks now require FDA establishment inspection history as gatekeeping criteria for formulary inclusion.
- Clinics:Outpatient infusion centers balance dosing frequency against per-unit procurement costs, favoring multi-dose formats where patient volume justifies preservative systems.
- Home Healthcare:Patient-administered parenteral nutrition drives demand for simplified infusion protocols and cold-chain stability.
- Research Laboratories:Investigational drug services require small-batch flexibility with elemental impurity profiling for protocol compliance.
Procurement volume clusters in Hospitals; Home Healthcare is climbing the fastest as reimbursement shifts toward site-neutral payment models.
Application:
Margin structures favor perioperative use cases over mature clinical nutrition segments with compressed pricing.
- IV Therapy:Perioperative fluid protocols for cardiac and bariatric procedures leverage xylitol's lower glycemic index for insulin response modulation. United States anesthesiology departments are driving fastest uptake in enhanced recovery protocols.
- Clinical Nutrition:Established parenteral carbohydrate substrate with reimbursement pathways locked into Medicare and commercial payer schedules.
- Pain Management:Adjunctive metabolic support in multimodal analgesia protocols remains investigational with limited formulary penetration.
- Oral Health:Topical and systemic applications for mucositis prevention in oncology patients show emerging trial activity.
Revenue concentration sits with Clinical Nutrition; IV Therapy claims the steepest expansion trajectory as surgical protocol adoption accelerates.
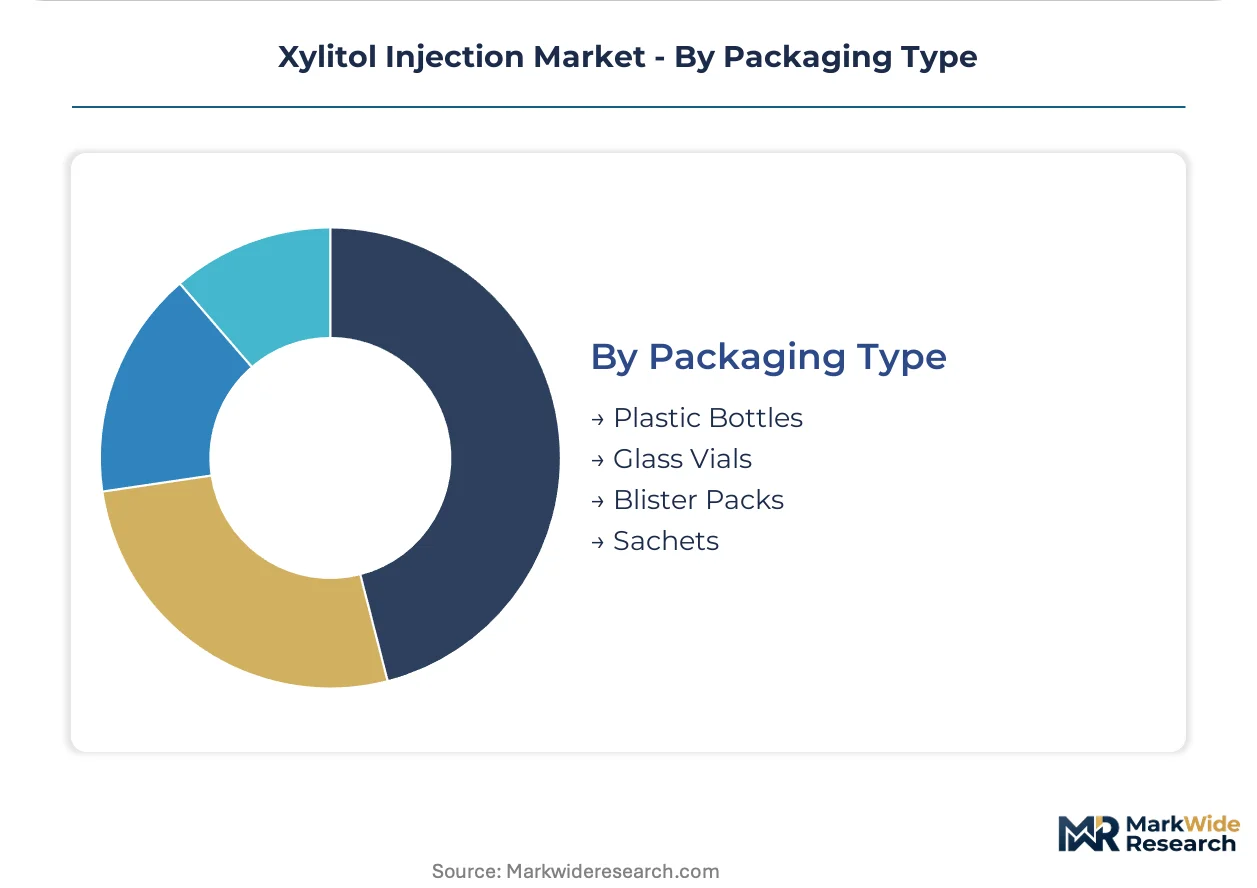
Packaging Type:
Supply concentration in Nordic hemicellulose sourcing shapes downstream packaging material selection for stability assurance.
- Glass Vials:Borosilicate containers with elastomeric closures dominate pharmaceutical-grade requirements. European manufacturers emphasize USP Type I glass for elemental impurity compliance under EMA revised guidelines.
- Plastic Bottles:Cyclic olefin polymer and polyethylene terephthalate formats reduce transport weight and breakage risk in home healthcare distribution.
- Blister Packs:Unit-dose barrier systems for pre-filled syringe alternatives in emergency medicine settings.
- Sachets:Powder-for-injection formats requiring reconstitution retain niche use in compounding pharmacy workflows.
Shipment volumes favor Glass Vials; Plastic Bottles are gaining share fastest as cold-chain logistics expand into community settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Gujarat and Maharashtra concentrate sterile injectable manufacturing capacity for export markets. These zones offer accelerated FDA and EMA inspection pathways alongside tax incentives for pharmaceutical-grade production.
United States
Ambulatory surgical centers in Texas and California drive perioperative xylitol infusion procurement for enhanced recovery protocols. FDA tightened sterility testing requirements elevate compliance costs for new market entrants. Hospital pharmacy consortia in the Southwest and Pacific regions consolidate procurement around suppliers with validated FDA establishment inspection histories.
Germany
Hospital consortia in Bavaria and North Rhine-Westphalia source blow-fill-seal manufactured xylitol solutions with real-time particulate monitoring. EMA Medical Device Regulation sterility assurance deadlines accelerate pharmacy consolidation around qualified aseptic processors. The Eindhoven-Ruhr corridor anchors compounding pharmacy networks serving metabolic support portfolios.
India
CDSCO alignment with ICH Q3D guidelines opens export pathways for domestic manufacturers targeting regulated markets. The country's national pharmaceutical regulator mandates elemental impurity screening for injectable-grade xylitol destined for European and North American buyers. Gujarat and Maharashtra special economic zones concentrate sterile injectable capacity with accelerated inspection pathways.
Switzerland
Swissmedic oversight of parenteral nutrition compounding drives demand for batch-specific CoA documentation. Regional compounders in Basel-Zurich corridor adopt single-use bioreactor systems for decentralized pharmaceutical-grade production. These facilities serve hospital consortia with shortened supply chains and reduced transport-related stability risks.
Japan
PMDA enforcement of revised elemental impurity guidelines shapes raw material qualification timelines for xylitol API. Kanto and Kansai regions concentrate parenteral nutrition manufacturing with integrated metabolic support portfolios. Tokyo-Osaka industrial corridor anchors sterile injectable production for domestic hospital formularies and regional export markets.
Xylitol Injection Market Competitive Landscape
United States producers anchor one tier; European specialists hold validated aseptic processing capabilities across multiple FDA-inspected sites. The market structure concentrates around vertically integrated pharmaceutical manufacturers with captive sterile injectable infrastructure. Three archetypes dominate: diversified multinationals with hospital formulary relationships, parenteral nutrition specialists with metabolic portfolio integration, and regional compounders leveraging disposable manufacturing technologies. Competitive moves center on M&A for sterile capacity acquisition and geographic expansion through regulatory harmonization.
Among diversified multinationals, Pfizer Inc. and Fresenius Kabi AG exemplify contrasting strategic positions. Pfizer represents the established pharmaceutical conglomerate archetype with distributed manufacturing footprints across inspected jurisdictions. Fresenius Kabi occupies the parenteral nutrition specialist position, anchoring market presence through integration into broader metabolic support offerings. Baxter International Inc. sits within the technology-differentiated tier, with blow-fill-seal manufacturing capabilities reducing particulate contamination exposure.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Merck & Co., Inc. |
| Fresenius Kabi AG |
| Teva Pharmaceutical Industries Ltd. |
| Baxter International Inc. |
| Sanofi |
| Hikma Pharmaceuticals PLC |
| Endo International plc |
| Mylan N.V. |
| Others |
Pricing and Supply Chain Analysis
Single-use bioreactor adoption for xylitol catalytic hydrogenation is compressing minimum efficient scale thresholds while simultaneously fragmenting supply concentration across mid-volume manufacturers in Germany and Switzerland. This technology shift enables regional compounders to achieve pharmaceutical-grade output without fixed stainless-steel infrastructure, reshaping cost economics for hospital consortia seeking shortened supply chains.
Pricing Analysis
Short lead-time premiums dominate hospital pharmacy procurement, with Texas and California integrated delivery networks paying contract premiums for batch-specific CoA documentation and validated aseptic processing data. The dominant pricing structure is contract-based long-term offtake tied to sterility assurance data packages, with price differentiation resting on FDA establishment inspection history and elemental impurity profiling capabilities. Cost compression in multi-dose formats is intensifying because clinic settings with controlled dosing frequencies favor preservative-containing alternatives. Outpatient infusion centers demonstrate highest price sensitivity, while tier-one medical centers prioritize contamination risk profiles over per-unit costs.
Supply Chain Analysis
ICH Q3D compliance certification gates raw material qualification, forcing suppliers to document hemicellulose provenance back to Nordic and Baltic source forests. Geographic supply concentration centers on Finland, Sweden, and Estonia for birch and beech wood hydrolysate, with German and Swiss compounders drawing from these feedstocks. Raw material dependencies include pharmaceutical-grade xylose, catalytic hydrogenation catalysts, and USP Type I borosilicate glass. Single-source hemicellulose vulnerability creates exposure to pulp mill capacity fluctuations. Distribution runs through hospital pharmacy consortia and group purchasing organizations consolidating around sole-source agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
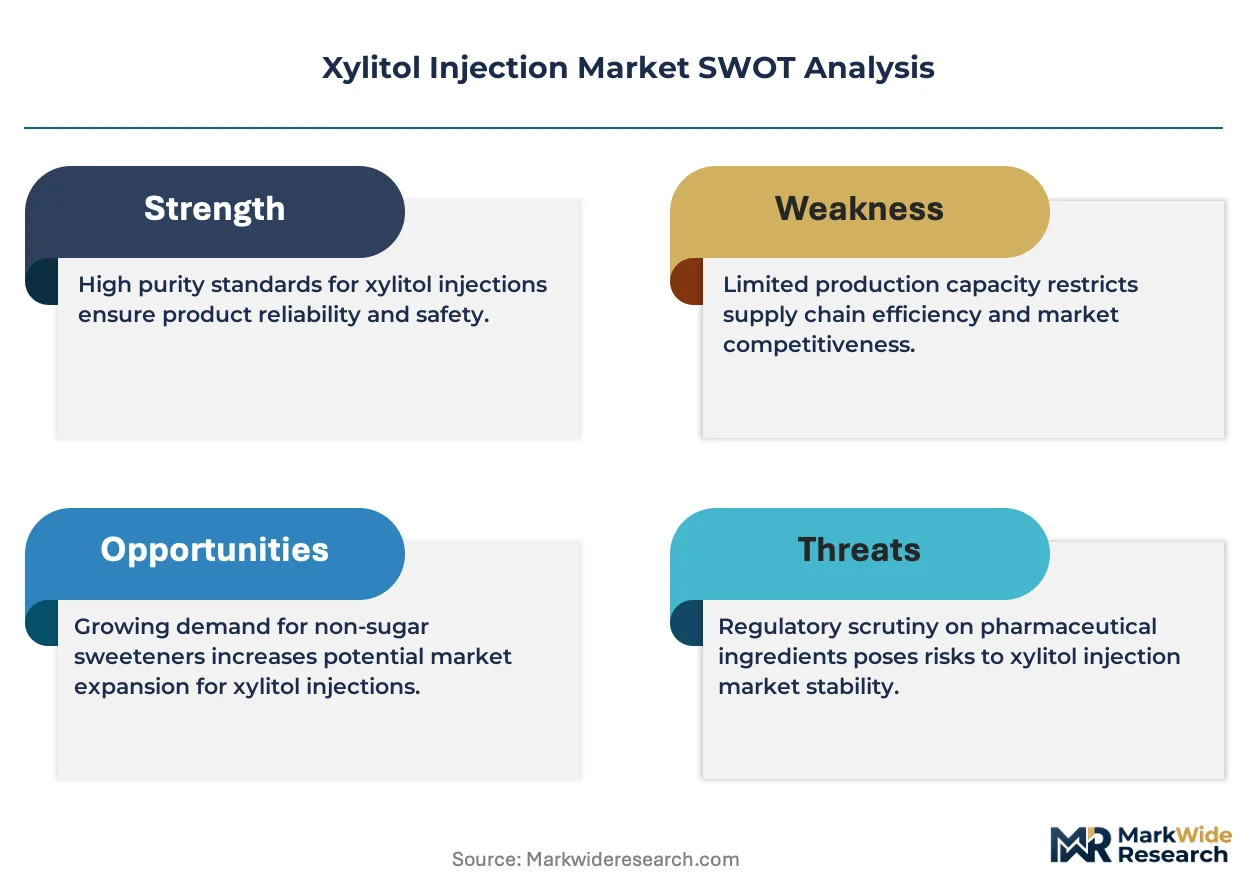
The Xylitol Injection Market functions as a cost-of-compliance story where FDA tightened sterility testing requirements and EMA MDR deadlines erect barrier-to-entry moats favoring manufacturers with validated aseptic processing infrastructure.
For Market Incumbents: Lock in formulary relationships through multi-year contracts tied to batch-specific CoA documentation and FDA establishment inspection histories. Pfizer Inc. and Fresenius Kabi AG exemplify defensive positioning through distributed manufacturing footprints and metabolic portfolio integration. Capacity addition in Gujarat and Maharashtra special economic zones captures Indian CDSCO-aligned export pathways. Threat of single-use bioreactor-enabled regional compounders necessitates channel control investments in hospital consortia procurement consolidation. For New Entrants and Emerging Players: Blow-fill-seal technology leadership offers a technology-first wedge into particulate-sensitive perioperative fluid segments where anesthesiology departments prioritize contamination risk reduction. The most penetrable white space sits in home healthcare parenteral nutrition, where patient-administered protocols demand simplified infusion systems and cold-chain stability. German and Swiss hospital consortia present geographic entry points through disposable manufacturing adoption. Go-to-market angle should emphasize real-time particulate monitoring and shortened supply chains for metabolic support portfolios. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified multinationals seeking sterile injectable capacity and hospital formulary relationships. Long-term viability favors vertically integrated manufacturers with captive hemicellulose sourcing and validated impurity profiling capabilities. Target archetype: regional compounders with single-use bioreactor infrastructure and established European hospital consortia contracts. Signal to watch is USP-NF and EP residual solvent specification convergence, which will determine which manufacturers can sustain cross-border supply without dual qualification investments.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Single-use bioreactor adoption enables mid-volume pharmaceutical-grade output without fixed infrastructure. |
| Regulatory Approval Pathway | FDA establishment inspection history serves as gatekeeping criterion for formulary inclusion in Texas and California. |
| Backward Integration | Captive hemicellulose sourcing from Nordic forests reduces geographic vulnerability to pulp mill fluctuations. |
| Hospital System Partnership | Sole-source agreements with group purchasing organizations displace fragmented multi-vendor procurement. |
| Geographic Expansion | CDSCO alignment with ICH Q3D opens export pathways from Gujarat and Maharashtra special economic zones. |
Research Methodology
FDA filings, EMA submissions, and ClinicalTrials.gov formed the secondary backbone, supplemented by formulary databases and hospital procurement records. Primary interviews with regulatory affairs leads, hospital procurement managers, formulary directors, and sterile manufacturing executives combined with secondary validation. Bottom-up and top-down triangulation anchored volume and value estimates across product types, end users, applications, and packaging formats.
Historical trendline analysis of hospital pharmacy procurement patterns and sterile injectable manufacturing capacity utilization informed projection frameworks. Segmentation dimensions modeled include delivery format, care setting, metabolic application, and regional regulatory cluster. CAGRs derived from surgical protocol adoption rates, reimbursement pathway evolution, and compounding pharmacy network expansion. Forecast inputs incorporated EMA MDR compliance deadlines and FDA sterility testing enforcement intensity.
Several conditions sit outside the modeled scope, including pharmacopeial monograph revision timing, hemicellulose feedstock price volatility, and novel carbohydrate substrate substitution. Forecasts reflect documented assumptions about regulatory harmonization progress and hospital consolidation trajectories. A model refresh is warranted upon material change in FDA inspection enforcement intensity or USP-NF and EP specification alignment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Europe Stevia Market
Sweeteners
Corn Syrup Market
Sweeteners
Europe Natural Sweetener Market
Sweeteners
Global Plant-Derived and Synthetic Sugar Market
Sweeteners
Maltol and Ethyl Maltol Market
Sweeteners
United States Food Sweetener Market
Sweeteners
Liquid Sugar Market
Sweeteners
Steviol Glycoside Market
Sweeteners
Africa and Middle East Sugarcane Syrup Market
Sweeteners
Xylose Market
Sweeteners
Asia Pacific Food Sweetener Market
Sweeteners
Australia Allulose Market
Sweeteners
North America Plant-Derived and Synthetic Sugar Market
Sweeteners
Brown Rice Syrup Market
Sweeteners
China Food Sweetener Market
Sweeteners
Glucose-Fructose Syrup (GFS) Market