
 Australia Allulose Market | 2026-2036
Australia Allulose Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Allulose Market Insights
Asset-light toll manufacturing and third-party fermentation leasing is reconfiguring competitive entry barriers for Australian allulose suppliers. Cargill, Incorporated leverages its global enzyme technology platform to sustain cost advantages in rare sugar conversion. Tate & Lyle PLC anchors its position through specialty ingredient distribution partnerships with local food manufacturers. Matsutani Chemical Industry Co. Ltd. differentiates via proprietary crystallization expertise that controls purity specifications for premium bakery applications.
Allulose is a rare monosaccharide, specifically a C-3 epimer of fructose, containing approximately 70% of sucrose sweetness with negligible caloric contribution due to limited intestinal absorption. Its primary commercial purpose centers on enabling sugar reduction in processed foods while preserving Maillard browning and bulk functional properties that high-intensity sweeteners cannot replicate. Powder formulations occupy the dominant share among product types, reflecting their stability in dry-mix applications and extended shelf compatibility. Beverage applications represent the fastest-growing segment, driven by clean-label sparkling water and functional drink reformulations across Australian retail channels.
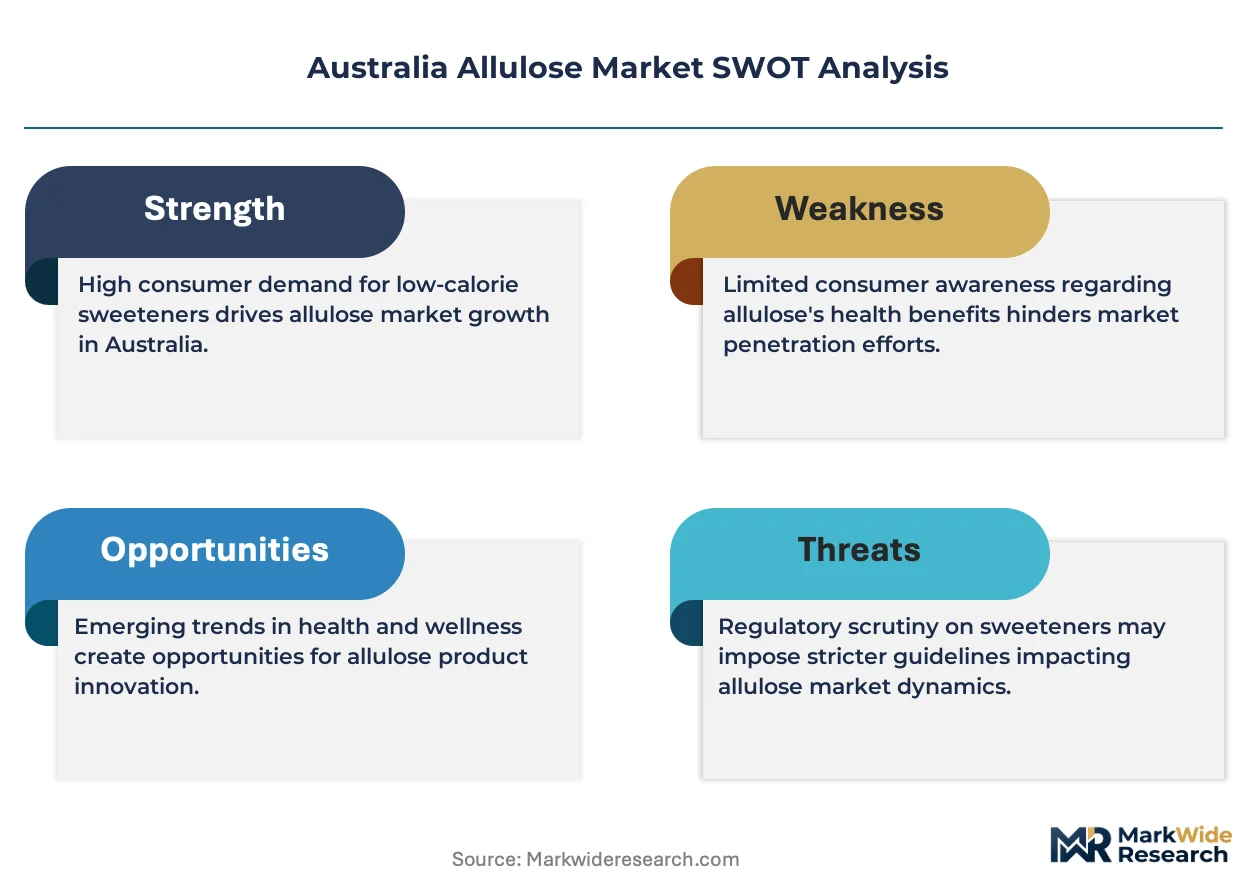
Food Standards Australia New Zealand (FSANZ) governs novel food determinations for allulose, while the Australia New Zealand Food Standards Code mandates labeling disclosures that directly influence manufacturer reformulation strategies. FSANZ approval pathways determine market access timelines, and the Australian Competition and Consumer Commission monitors health claim substantiation that shapes product positioning. Stakeholders must track pending novel food determinations for enzymatic allulose variants and assess how impending front-of-pack labeling changes will redirect procurement decisions across beverage and dairy supply chains.
Market Dynamics
FSANZ novel food approval pathways and impending front-of-pack sugar labeling reforms are compressing reformulation timelines for Australian beverage and dairy manufacturers. This regulatory momentum is forcing ingredient procurement restructuring across New South Wales and Victoria processing clusters.
Growth Catalysts
- Clean-label beverage reformulation:Sparkling water and functional drink producers in Australian retail channels are accelerating sugar reduction programs. Allulose preserves Maillard browning and bulk properties that aspartame and sucralose cannot replicate.
- FSANZ regulatory clarity:Novel food determinations for enzymatic allulose variants are establishing predictable market access timelines. This framework reduces regulatory uncertainty for fermentation-based production investments.
- Queensland and South Australia dairy processing expansion:Regional dairy clusters are adopting rare sugar sweeteners for reduced-sugar yogurt and flavored milk applications. Local formulation expertise is concentrating around Brisbane and Adelaide manufacturing hubs.
Market Restraints
- Enzyme input cost volatility:Specialty D-psicose 3-epimerase enzymes required for bioconversion face supply concentration among Japanese and Korean biotechnology suppliers. Australian toll manufacturers remain exposed to currency and freight cost swings.
- Technical crystallization limitations:Achieving pharmaceutical-grade purity specifications for premium bakery applications requires proprietary separation expertise that few third-party fermentation facilities possess.
- High-intensity sweetener substitution threat:Stevia glycoside and monk fruit extract formulations are improving taste profiles through bitter-masking technologies. These plant-derived alternatives compete for clean-label positioning in cost-sensitive applications.
Strategic Opportunities
- Western Australia and Tasmania geographic white space:Food and beverage manufacturing in these states remains underpenetrated for rare sugar adoption. Local distribution partnerships could capture first-mover positioning in Perth and Hobart processing corridors.
- Sports nutrition and clinical nutrition convergence:Protein fortification and glycemic management applications are creating hybrid product categories. Allulose enables sugar reduction without compromising palatability in medical foods and performance nutrition.
- Third-party fermentation infrastructure leasing:Asset-light manufacturing models allow new entrants to bypass capital-intensive bioreactor construction. Toll arrangements with existing Australian biotechnology facilities compress time-to-market for regional suppliers.
Industry Challenges
- Fermentation process engineering talent scarcity:Rare sugar bioconversion requires specialized expertise in continuous enzymatic reaction optimization. Australian universities produce limited graduates with combined food science and industrial biotechnology training.
- FSANZ compliance timeline compression:Novel food determination submissions require extensive toxicology and exposure assessment data. Smaller suppliers struggle to fund the regulatory science necessary for approval pathway navigation.
- Legacy high-intensity sweetener formulation integration:Existing manufacturing lines optimized for aspartame or sucralose handling require retrofitting for allulose powder flow properties and hygroscopicity management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Allulose Market |
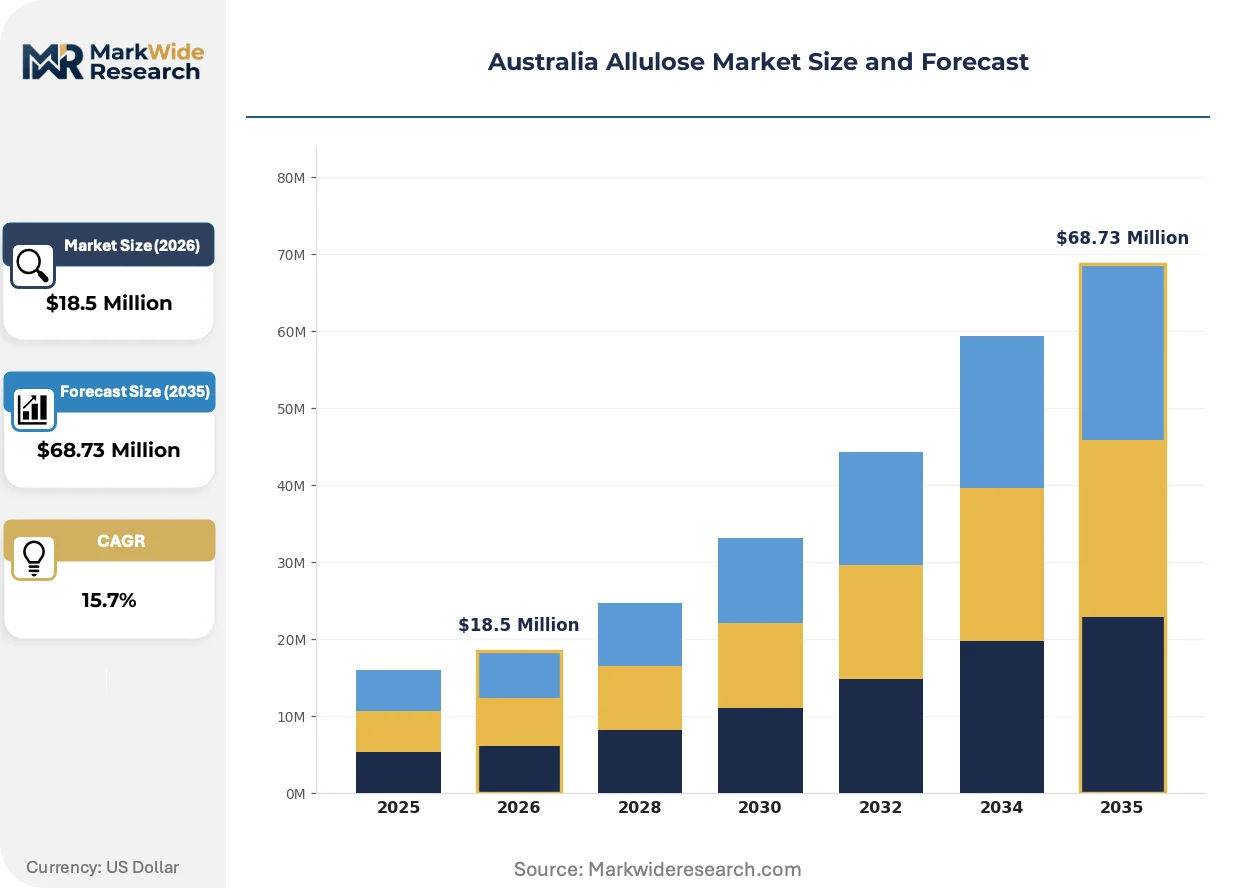
| Market Size in 2026 | $18.5 Million |
| Market Size in 2035 | $68.73 Million |
| CAGR (2026 – 2036) | 15.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Granulated, Crystalline Application: Beverages, Bakery, Confectionery, Dairy End User: Food Manufacturers, Beverage Producers, Restaurants, Retailers Distribution Channel: Online, Supermarkets, Health Stores, Direct Sales |
| Companies Covered | Cargill, Incorporated, Sweetener Solutions, Ingredion Incorporated, Samyang Corporation, CJ Cheil Jedang, Tate & Lyle PLC, Mitsubishi Shoji Foodtech, Anderson Advanced Ingredients, Matsutani Chemical Industry Co. Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Allulose Market Trends and Innovations
Bioprocess control technologies and regulatory disclosure requirements are compressing product development cycles across Australian food manufacturing. Three structural developments are reshaping how rare sugars enter commercial formulations.
Continuous enzymatic bioconversion systems with real-time spectroscopic monitoring are digitizing quality control in allulose production. Australian toll manufacturers are adopting these platforms to reduce batch-to-batch variability and accelerate release testing. Beverage producers in Sydney and Melbourne are digitizing their supply chain verification through blockchain-anchored certificates of analysis.
FSANZ updated sugar labeling standards mandating added-sugar disclosure on front-of-pack panels are forcing reformulation decisions. The Australia New Zealand Food Standards Code amendments require manufacturers to recalculate ingredient costs and sensory profiles simultaneously. Dairy processors in Victoria are responding fastest, with reduced-sugar product lines launching ahead of compliance deadlines.
Direct sourcing contracts between end-users and fermentation facilities are displacing traditional ingredient distributor intermediation. Large Australian beverage conglomerates are negotiating volume commitments with third-party biomanufacturers for guaranteed allulose supply. This procurement restructuring concentrates most visibly in New South Wales, where sparkling water production volumes justify dedicated production campaigns.
Australia Allulose Market Segmentation
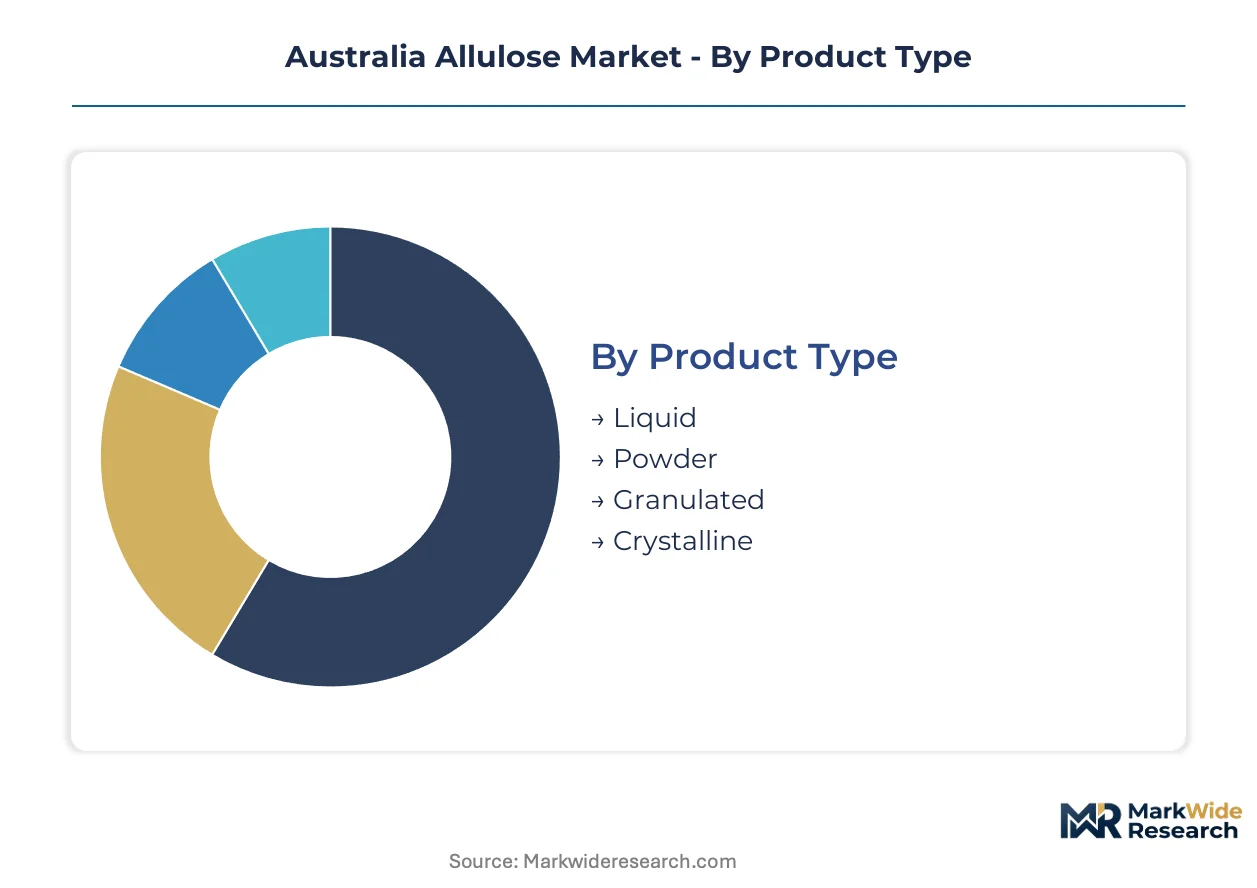
Segmentation in the Australia allulose market reveals distinct procurement rhythms across product formats and end-use channels. Powder formulations dominate dry-mix manufacturing cycles, while beverage sector demand accelerates on compressed reformulation timelines driven by FSANZ labeling mandates.
Product Type:
Inventory velocity varies sharply across physical formats, with liquid allulose turning over fastest in beverage applications and crystalline grades holding longest in premium bakery supply chains.
- Liquid:Aqueous solutions suit high-throughput beverage production lines in Sydney and Melbourne manufacturing clusters. Sparkling water reformulators prefer liquid delivery for seamless syrup integration without hydration steps.
- Powder:Spray-dried formulations dominate dry-mix applications across Australian food manufacturing. Extended shelf stability and flowability specifications make this the default specification for New South Wales and Victoria ingredient distributors.
- Granulated:Coarse particle size enables direct sugar substitution in tabletop sweetener retail formats. Health store channels in Brisbane and Perth favor granulated allulose for consumer-facing packaging.
- Crystalline:Pharmaceutical-grade purity specifications serve premium bakery and medical nutrition applications. Proprietary separation expertise concentrates among Japanese technology licensors supplying Australian toll manufacturers.
Powder anchors the volume base while liquid gains share at the steepest rate.
Application:
Margin capture diverges across use cases, with dairy applications commanding formulation premiums and confectionery remaining most price-sensitive.
- Beverages:Sparkling water and functional drink producers lead sugar reduction programs across Australian retail channels. Allulose preserves carbonation stability and clean-label positioning that stevia-sweetened alternatives struggle to match.
- Bakery:Maillard browning replication and bulk functional properties drive adoption in artisan and industrial baking segments. Victorian commercial bakeries specify crystalline grades for reduced-sugar bread and pastry applications.
- Confectionery:Hard candy and chocolate applications leverage allulose for reduced-glycemic formulations without cooling effects. Cost compression from high-intensity sweetener competition limits penetration in mass-market sugar confectionery.
- Dairy:Queensland and South Australia yogurt processors adopt rare sugars for flavored and reduced-sugar product lines. Protein fortification compatibility positions allulose favorably against erythritol in Greek-style formulations.
Beverages command the steepest expansion trajectory while bakery maintains the broadest installed formulation base.
End User:
Procurement sophistication separates large-scale manufacturers from fragmented foodservice operators, with direct sourcing contracts concentrating among beverage conglomerates.
- Food Manufacturers:Industrial bakeries and dairy processors in Victoria and New South Wales drive bulk volume procurement. FSANZ compliance requirements favor established suppliers with novel food determination documentation.
- Beverage Producers:Sparkling water specialists and functional drink brands negotiate dedicated production campaigns with toll fermentation facilities. Direct supply agreements displace traditional distributor intermediation in this segment.
- Restaurants:Foodservice adoption concentrates in health-focused cafe chains and bakery-cafe formats. Smaller operators rely on wholesale distributors rather than direct manufacturer relationships.
- Retailers:Supermarket private-label programs and health store chains source packaged tabletop sweeteners. Online direct-to-consumer channels capture premium pricing for organic-positioned allulose products.
Food manufacturers anchor procurement volume while beverage producers reshape supply chain structures through direct sourcing.
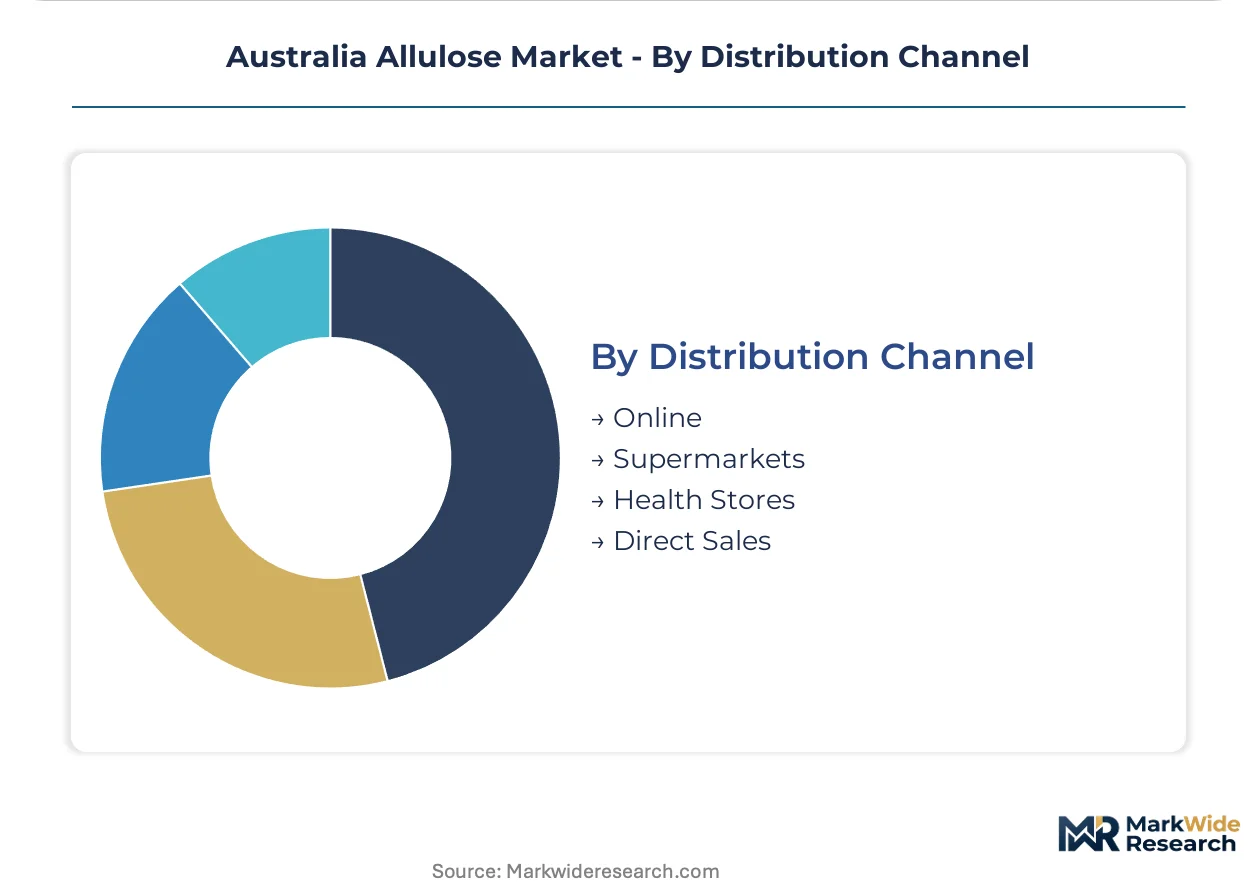
Distribution Channel:
Channel economics reflect customer scale fragmentation, with direct sales capturing largest accounts and online channels serving geographic white space.
- Online:E-commerce platforms serve Western Australia and Tasmania markets underserved by physical distribution infrastructure. Subscription models for tabletop sweeteners build recurring revenue in consumer segments.
- Supermarkets:Coles and Woolworths shelf placement determines mass-market penetration for granulated retail formats. Listing fees and promotional spend requirements favor suppliers with diversified product portfolios.
- Health Stores:Specialty retailers in Melbourne and Sydney premium suburbs command margin premiums for organic and non-GMO certified allulose. Pharmacist endorsement drives clinical nutrition crossover sales.
- Direct Sales:Large beverage and dairy manufacturers negotiate volume commitments bypassing distributor markups. This channel concentrates procurement restructuring in New South Wales processing corridors.
Direct sales capture the highest absolute volumes while online channels expand geographic coverage most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FSANZ novel food approvals and updated sugar labeling standards are redirecting ingredient procurement toward states with established food manufacturing infrastructure. Sub-regional demand concentrates where beverage and dairy processing clusters already operate at scale.
New South Wales
Sparkling water reformulation drives rare sugar procurement across Sydney manufacturing corridors. FSANZ compliance documentation requirements favor suppliers with established novel food determinations. Direct sourcing contracts between beverage conglomerates and toll fermentation facilities are displacing traditional distributor intermediation in this state.
Victoria
Dairy processors and commercial bakeries anchor bulk volume demand for crystalline and powder allulose grades. The Australia New Zealand Food Standards Code mandates front-of-pack added-sugar disclosure that accelerates reformulation timelines. Melbourne-based ingredient distributors concentrate formulation expertise for reduced-sugar yogurt and artisan bread applications.
Queensland
Regional dairy clusters adopt rare sugar sweeteners for flavored milk and Greek-style yogurt production. State-level food manufacturing incentives support processing expansion around Brisbane. Local formulation expertise is developing for protein fortification applications where allulose competes against erythritol.
South Australia
Adelaide manufacturing hubs specialize in reduced-sugar dairy and clinical nutrition products. TGA-aligned quality standards for medical foods create demand for pharmaceutical-grade purity specifications. Toll fermentation partnerships with interstate biotechnology facilities supply regional processors.
Western Australia
Perth processing corridors represent geographic white space with limited rare sugar adoption to date. E-commerce channels and direct distribution partnerships could capture first-mover positioning. Food and beverage manufacturing concentration remains lower than eastern states, constraining immediate volume potential.
Australia Allulose Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three discernible tiers. The vendor base concentrates around global ingredient conglomerates with enzyme technology platforms, regional distributors with formulation partnerships, and toll manufacturers with fermentation infrastructure. Strategic archetypes include technology licensors, specialty distributors, and asset-light biomanufacturers. Dominant competitive moves center on direct supply contract negotiation and third-party fermentation capacity leasing.
Within the global conglomerate tier, Cargill, Incorporated and Tate & Lyle PLC exemplify channel control through enzyme platforms and distribution networks respectively. Matsutani Chemical Industry Co. Ltd. represents the specialist archetype with proprietary separation expertise. These three anchors demonstrate how competitive positioning depends on controlling either upstream bioconversion technology or downstream formulation relationships.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Sweetener Solutions |
| Ingredion Incorporated |
| Samyang Corporation |
| CJ Cheil Jedang |
| Tate & Lyle PLC |
| Mitsubishi Shoji Foodtech |
| Anderson Advanced Ingredients |
| Matsutani Chemical Industry Co. Ltd. |
| Others |
Pricing and Supply Chain Analysis
Trans-Tasman shipping lanes linking Japanese and Korean enzyme suppliers to Australian toll manufacturers impose freight cost volatility that compresses margins for crystalline-grade allulose while enabling powder-grade price premiums in Sydney and Melbourne beverage corridors. This logistics dynamic concentrates pricing power among fermentation facilities with captive enzyme sourcing relationships.
Pricing Analysis
Certification level (FSANZ novel food determination status) creates the primary spread between pharmaceutical-grade crystalline and standard powder grades. Contract-based long-term offtake dominates volume procurement, with beverage conglomerates locking in dedicated production campaigns. Price differentiation rests on purity specifications and direct sourcing relationships versus distributor intermediation. Cost compression in standard powder grades is intensifying because high-intensity sweetener substitution threatens mass-market applications. Foodservice operators exhibit highest price sensitivity, while clinical nutrition manufacturers accept premium positioning for TGA-aligned quality standards.
Supply Chain Analysis
Toll fermentation capacity concentrates among third-party Australian biotechnology facilities leasing bioreactor infrastructure to new market entrants. Enzyme inputs draw from Japanese and Korean biotechnology suppliers, with D-psicose 3-epimerase availability anchoring production economics. Raw material dependencies center on specialty enzyme supply, fermentation feedstock substrates, and crystallization separation media. Single-source vulnerability in enzyme supply creates structural risk exposure to currency swings and freight disruption. Distribution runs through direct sales contracts for large beverage and dairy manufacturers, with online channels serving Western Australia and Tasmania geographic white space.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Australia allulose market sits at a platform-economics inflection where direct sourcing contracts between end-users and fermentation facilities are displacing traditional distributor intermediation, creating interoperability demands across blockchain-anchored supply chain verification systems.
For Market Incumbents: Build regulatory documentation moats through FSANZ novel food determination portfolio expansion. Deepen backward integration into proprietary enzyme technology platforms to reduce exposure to Japanese and Korean supplier concentration. Secure capacity addition in Queensland dairy processing corridors to capture regional expansion. Channel control through direct supply contract negotiation defends against emerging toll manufacturer competition. For New Entrants and Emerging Players: Pursue geographic white space in Western Australia and Tasmania where rare sugar adoption remains underpenetrated. Target sports nutrition and clinical nutrition convergence applications where protein fortification compatibility creates differentiation against erythritol. Leverage asset-light toll manufacturing partnerships to compress time-to-market without capital-intensive bioreactor construction. For Investors and Strategic Acquirers: Carve-out targets emerge from global ingredient conglomerates seeking to monetize non-core rare sugar technology assets. Long-term viability hinges on fermentation process engineering talent scarcity resolving through university-industry training partnerships. Watch enzymatic allulose variant novel food determination timelines as inflection signal for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| FSANZ Novel Food Determination Expansion | Regulatory approval pathways reduce market access uncertainty for enzymatic variant suppliers. |
| Third-Party Fermentation Capacity Leasing | Asset-light manufacturing models compress capital requirements for new Australian market entrants. |
| Direct Sourcing Contract Negotiation | Beverage conglomerates bypass distributor markups through volume commitments with toll facilities. |
| Enzyme Technology Platform Licensing | Proprietary D-psicose 3-epimerase access sustains cost advantages in rare sugar bioconversion. |
| Blockchain Supply Chain Verification | Digitized certificates of analysis anchor quality assurance for Sydney and Melbourne beverage producers. |
Research Methodology
Cross-validation between primary interviews with fermentation facility operators, FSANZ regulatory affairs specialists, and beverage procurement directors anchors the qualitative findings, while secondary validation draws from FSANZ novel food determination databases, Australia New Zealand Food Standards Code amendments, and customs trade data for enzyme and rare sugar imports. Bottom-up volume modeling from individual toll manufacturer capacity and top-down demand estimation from end-use sector reformulation timelines complete the triangulation.
Calibration against historical novel food approval timelines and beverage reformulation cycle data shapes the projection framework across the analysis window. Segmentation dimensions include product format (liquid, powder, granulated, crystalline), application (beverages, bakery, confectionery, dairy), and end-user procurement sophistication (direct sourcing versus distributor-mediated). CAGRs derive from elasticity-adjusted adoption curves and regulatory compliance deadline impacts. Forecast inputs incorporate FSANZ labeling mandate implementation schedules and Queensland dairy processing expansion incentives.
Macroeconomic conditions sit as an overlay; deviation in Australian dollar exchange rates against yen and won, or disruption in Trans-Tasman shipping lanes, would shift the trajectory. Forecasts reflect assumptions about regulatory timeline predictability and enzyme supplier pricing stability. Quarterly review of FSANZ novel food determination submission volumes and toll fermentation capacity utilization rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Indonesia Food Sweetener Market
Sweeteners
Turbinado Sugar Market
Sweeteners
Dextrates Market
Sweeteners
Spain Food Sweetener Market
Sweeteners
Agave Syrup Market
Sweeteners
China Food Sweetener Market
Sweeteners
Global Cane Molasses Market
Sweeteners
Africa and Middle East Sugarcane Syrup Market
Sweeteners
Dextrose Syrup Market
Sweeteners
Corn Sweeteners Market
Sweeteners
D-Mannose Market
Sweeteners
Global Low Intensity Sweeteners Market
Sweeteners
Asia-Pacific Cane Sugar Market
Sweeteners
Isomaltooligosaccharide Market
Sweeteners
Asia-Pacific Stevia Market
Sweeteners
Erythritol Market