
 Maltol and Ethyl Maltol Market | 2026-2036
Maltol and Ethyl Maltol Market Size, Share, and Industry Trends Forecast 2026-2036
Maltol and Ethyl Maltol Market Insights
China's chemical manufacturing corridor is narrowing the cost gap with Western maltol producers. Anhui Jinhe Industrial leverages captive furfural supply to sustain margin advantage across Asia-Pacific formulations. Solvay S.A. anchors European pharmaceutical-grade ethyl maltol through REACH-certified production in Belgium. Firmenich International SA differentiates via flavor house integration, controlling downstream application development for beverage clients.
Maltol and ethyl maltol are bicyclic enolones synthesized via furfural oxidation or fermentation pathways, with ethyl maltol exhibiting roughly fourfold greater flavor potency at lower caramelization thresholds; both function primarily as flavor enhancers and masking agents in processed consumables. The application dimension shows food additive and beverage industry segments leading volume, while pharmaceutical-grade specifications command premium positioning due to USP and EP certification requirements. Product type segmentation reveals ethyl maltol outpacing maltol in new formulation adoption, though maltol retains cost-sensitive applications in baked goods and confectionery.
US FDA food additive regulations under 21 CFR 172.515 govern maltol and ethyl maltol usage limits, while EU EFSA evaluations of flavoring substances (FL-no. 05.020 and 05.021) determine maximum permissible concentrations in finished foods. China's SAMR national food safety standards (GB 1886.283) mandate residue testing for synthetic flavorants, creating compliance barriers for uncertified imports. Stakeholders must monitor evolving purity specifications across FDA, EFSA, and SAMR jurisdictions to anticipate reformulation costs and qualify for pharmaceutical excipient contracts.
Market Dynamics
Furfural feedstock concentration in China's Shandong chemical corridor is compressing production economics for Western maltol manufacturers and forcing strategic repositioning toward pharmaceutical-grade specialization.
Growth Catalysts
- REACH purity thresholds:EFSA-mandated residue limits for synthetic flavorants are accelerating pharmaceutical-grade certification investments across European production facilities.
- Beverage flavor masking:North American low-sugar formulation trends are pulling ethyl maltol demand from carbonated soft drinks into functional waters and protein beverages.
- Furfural oxidation efficiency:Integrated furfural-to-maltol facilities in Anhui province are capturing margin through captive pyrolysis feedstock supply.
Market Restraints
- Feedstock volatility:Corn cob and oat hull prices for furfural production fluctuate with agricultural commodity cycles, squeezing non-integrated producers.
- Geographic supply lock-in:Over 60% of merchant furfural originates from Chinese integrated chemical parks, creating single-source vulnerability for Western maltol synthesis.
- Biotechnological substitution:Fermentation-derived maltol from engineered yeast strains threatens synthetic route economics at pilot scale.
Strategic Opportunities
- Indian pharmaceutical excipients:CDSCO's expanding USP-grade flavorant import approvals create white space for certified ethyl maltol in generic drug formulations.
- Clean-label convergence:EU Green Deal chemical sustainability criteria are favoring bio-based maltol in premium confectionery positioning.
- Direct-to-flavor-house distribution:Bypassing traditional chemical distributors reduces working capital cycles for beverage industry procurement teams.
Industry Challenges
- Cross-jurisdictional compliance:Simultaneous FDA 21 CFR 172.515, EFSA FL-no. 05.020, and SAMR GB 1886.283 certification timelines stretch quality assurance resources.
- Specialized synthesis expertise:Furfural oxidation catalyst optimization requires rare organometallic chemistry skill sets concentrated in legacy European and Chinese facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Maltol and Ethyl Maltol Market |
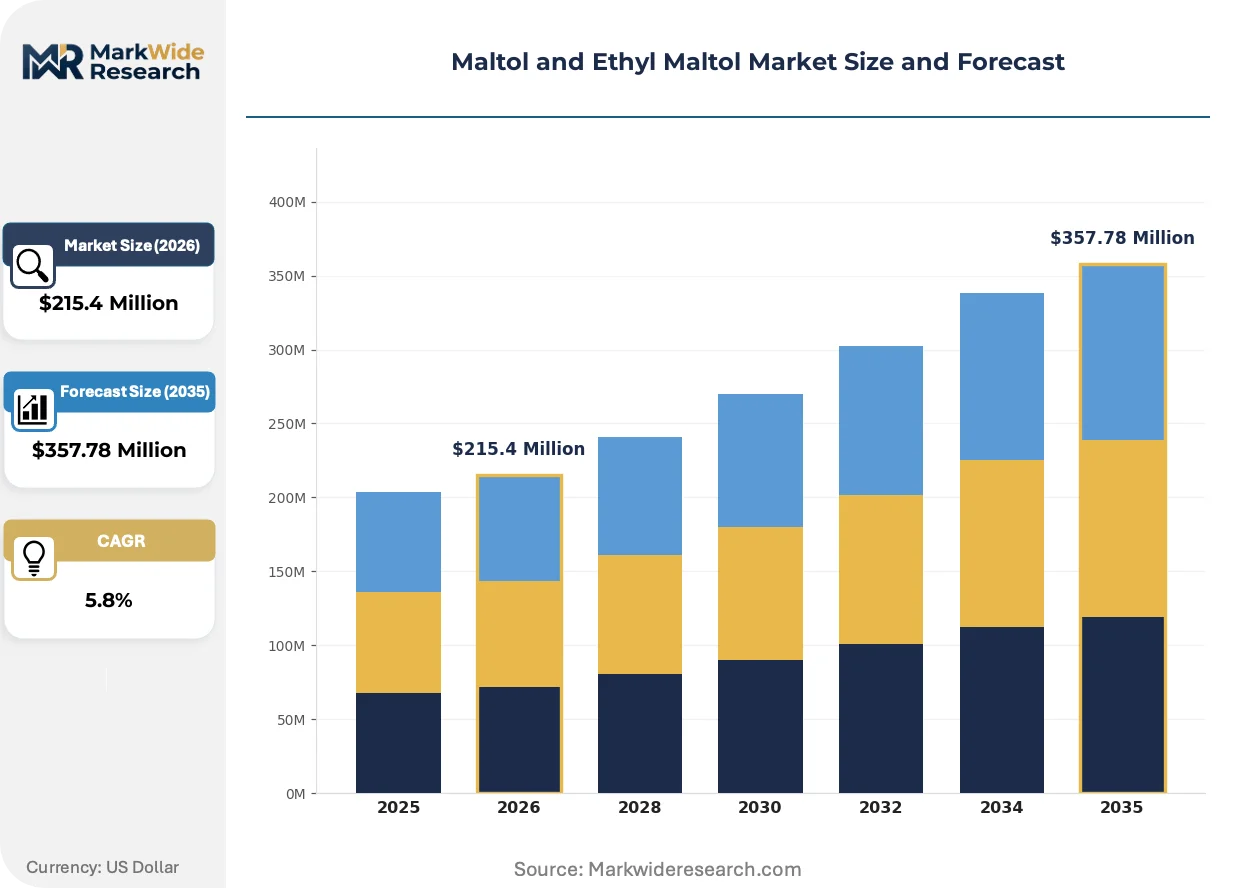
| Market Size in 2026 | $215.4 Million |
| Market Size in 2035 | $357.78 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Maltol, Ethyl Maltol, Flavors, Fragrances Application: Food Additive, Beverage Industry, Cosmetic Products, Pharmaceuticals End User: Food Manufacturers, Cosmetic Companies, Pharmaceutical Firms, Beverage Producers Distribution Channel: Online Sales, Direct Sales, Retail Stores, Wholesalers |
| Companies Covered | Firmenich International SA, Solvay S.A., Merck KGaA (Sigma-Aldrich), Anhui Jinhe Industrial Co., Ltd., Beijing Tianlihai Chemicals, Vigon International, Inc., Zhaoqing Perfumery, Xiamen Bestally Biotechnology, Foodchem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Maltol and Ethyl Maltol Market Trends and Innovations
Process intensification and regulatory stringency are bifurcating the maltol market into commodity food-grade supply and premium pharmaceutical-grade specialization, with technology choices locking in competitive positioning for decade-long asset cycles.
Continuous flow reactor technology for furfural oxidation is migrating from batch chemical processing toward pharmaceutical-grade maltol production. Solvay S.A. and specialized European manufacturers are adopting plug-flow systems to meet EP certification requirements for residual solvent limits. This migration is compressing batch reactor economics for non-integrated food-grade producers unable to justify capital intensity.
EFSA's 2023 re-evaluation of flavoring substances under Regulation (EC) No 1333/2008 is tightening maximum permissible concentrations for maltol in infant nutrition categories. French and German food safety authorities are enforcing enhanced purity documentation for ethyl maltol imports. Premium infant formula manufacturers are responding by qualifying dedicated pharmaceutical-grade supply chains separate from general food additive sourcing.
Beverage industry procurement teams are consolidating flavorant purchasing through integrated flavor house partnerships rather than direct chemical sourcing. Firmenich International SA and comparable houses are absorbing maltol procurement risk into long-term formulation service contracts. This channel compression is most advanced in North American carbonated and functional beverage categories, where single-source accountability reduces quality variance liability.
Maltol and Ethyl Maltol Market Segmentation
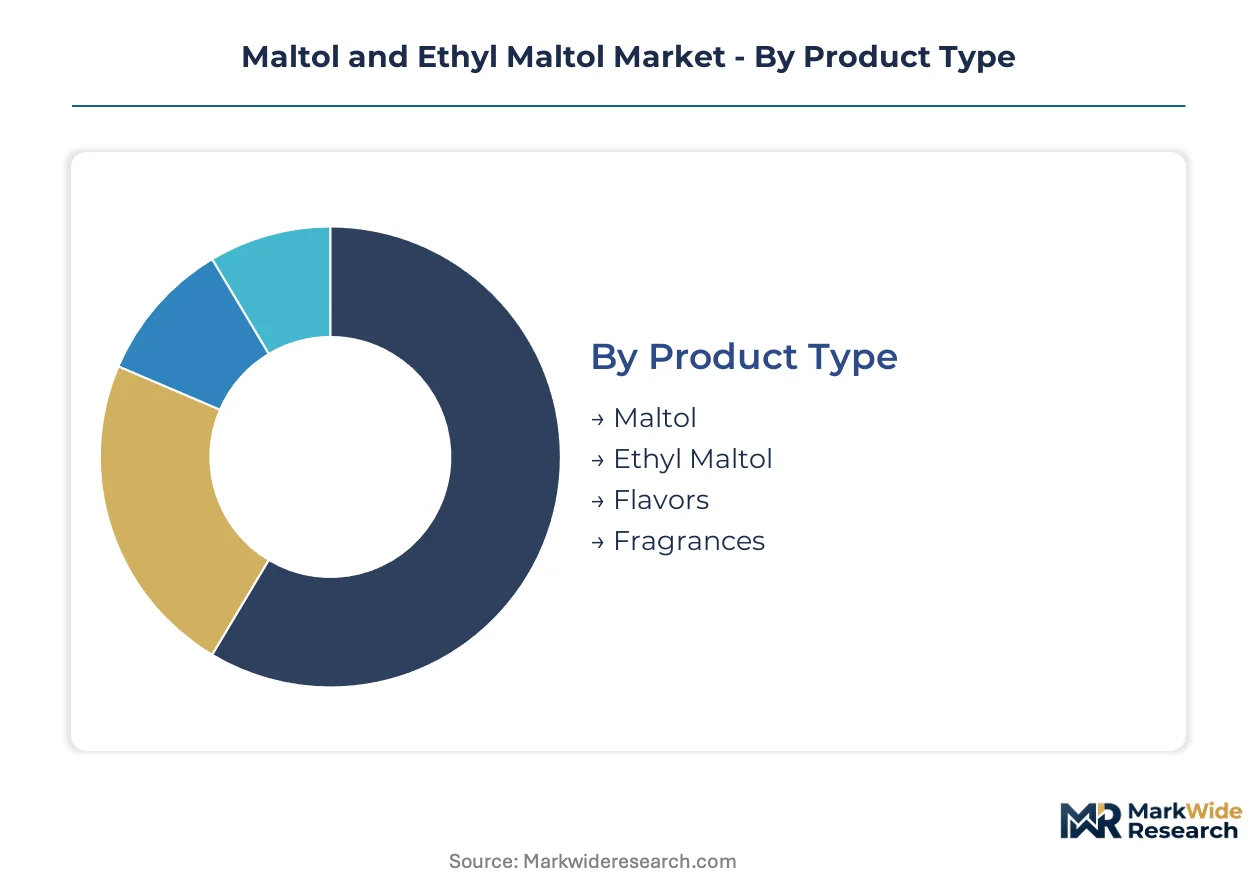
Maltol and ethyl maltol exhibit divergent value propositions across formulation contexts, with product chemistry determining application suitability and regulatory compliance burden. Segmentation clarity enables procurement teams to align specification grade with end-use liability exposure.
Product Type:
The use-case spectrum spans flavor potency differentiation and downstream integration depth, from commodity enolone supply to finished flavor system delivery.
- Maltol:A bicyclic enolone synthesized via furfural oxidation with moderate caramel-like flavor enhancement at higher usage thresholds. Cost-sensitive baked goods manufacturers in China's Shandong province favor maltol for bulk confectionery where thermal stability matters more than potency.
- Ethyl Maltol:The ethyl-substituted variant delivers approximately fourfold greater flavor intensity at lower caramelization temperatures. North American beverage producers specify ethyl maltol for low-sugar masking applications where reduced additive load supports clean-label positioning.
- Flavors:Pre-formulated flavor systems incorporating maltol or ethyl maltol as core enhancers, sold to food manufacturers seeking reduced R&D overhead.
- Fragrances:Cosmetic-grade specifications with modified volatility profiles for personal care applications, governed by IFRA concentration limits.
Established volume favors maltol; emerging adoption favors ethyl maltol.
Application:
Regulatory jurisdiction density varies sharply across these categories, with pharmaceutical and infant nutrition segments imposing the steepest purity documentation requirements.
- Food Additive:The largest volume category encompassing baked goods, confectionery, and savory applications. FDA 21 CFR 172.515 and EFSA FL-no. 05.020 govern maximum permissible concentrations, with SAMR GB 1886.283 compliance mandatory for Chinese importation.
- Beverage Industry:Carbonated soft drinks, functional waters, and protein beverages drive ethyl maltol specification due to superior solubility and lower usage rates. North American procurement teams are consolidating purchases through integrated flavor house contracts.
- Cosmetic Products:Fragrance and personal care applications require IFRA-compliant volatility grades, with European manufacturers leading formulation safety assessment protocols.
- Pharmaceuticals:USP and EP certification mandates residual solvent testing and heavy metal limits, creating supply chain bifurcation from food-grade sourcing. CDSCO import approvals are expanding access for Indian generic drug manufacturers.
Food additive volumes dominate current procurement; pharmaceutical applications command the steepest expansion trajectory.
End User:
Customer technical capability determines whether procurement targets commodity enolones or integrated flavor systems.
- Food Manufacturers:Large-scale bakery and confectionery operations with in-house flavor formulation teams purchase maltol directly from chemical distributors.
- Cosmetic Companies:Personal care formulators source fragrance-grade materials through specialized distributors with IFRA documentation capabilities.
- Pharmaceutical Firms:Excipient buyers require USP-grade ethyl maltol with validated supply chain documentation for ANDA submissions.
- Beverage Producers:Carbonated and functional drink manufacturers increasingly outsource flavorant procurement to integrated flavor houses like Firmenich International SA.
Beverage producers are shifting procurement responsibility fastest; pharmaceutical firms maintain the most stringent qualification protocols.
Distribution Channel:
Channel selection reflects order scale, technical service requirements, and geographic proximity to manufacturing clusters.
- Online Sales:E-commerce platforms serve small-scale food manufacturers and research institutions requiring sample quantities with rapid fulfillment.
- Direct Sales:Large beverage and pharmaceutical accounts negotiate long-term contracts directly with Solvay S.A. or Anhui Jinhe Industrial for volume security.
- Retail Stores:Limited to food-grade maltol in specialty chemical outlets serving artisanal food producers.
- Wholesalers:Regional chemical distributors stock standard grades for mid-tier food manufacturers without direct supplier relationships.
Direct sales capture premium-grade volume; online channels serve the smallest accounts with highest service cost ratios.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAMR's GB 1886.283 standards anchor China's dominance in maltol production, while FDA and EFSA regulations fragment demand-side compliance requirements across Western markets. Production clusters concentrate in Shandong province, with secondary capacity emerging in Belgium and Switzerland for pharmaceutical-grade supply.
China
Beverage manufacturers in Guangdong and Zhejiang provinces drive ethyl maltol consumption for low-sugar formulations targeting domestic health-conscious consumers. SAMR's residue testing mandates under GB 1886.283 create compliance barriers for uncertified imports while favoring integrated Shandong producers with captive furfural supply chains.
United States
Carbonated soft drink and functional beverage producers in Georgia and Texas consolidate flavorant procurement through integrated flavor house contracts. FDA 21 CFR 172.515 governs maximum permissible concentrations, with beverage industry procurement teams prioritizing ethyl maltol for reduced additive load positioning in clean-label products.
Germany
EFSA's FL-no. 05.020 and 05.021 evaluations determine maximum permissible concentrations for maltol across confectionery and infant nutrition categories. REACH-certified production facilities in North Rhine-Westphalia serve pharmaceutical-grade demand from Swiss and Dutch excipient buyers requiring EP certification documentation.
Belgium
Pharmaceutical-grade ethyl maltol production concentrates in Wallonia's chemical corridor, supplying European generic drug manufacturers with USP-certified materials. Solvay S.A. anchors regional capacity through REACH-compliant facilities serving excipient contracts requiring validated heavy metal and residual solvent documentation.
India
Generic drug manufacturers in Maharashtra and Gujarat expand USP-grade flavorant sourcing for ANDA submissions as CDSCO broadens import approval pathways. Domestic bakery and confectionery producers in Karnataka and Tamil Nadu favor cost-sensitive maltol for thermal-stable applications in traditional sweet formulations.
Maltol and Ethyl Maltol Market Competitive Landscape
Capability concentration sits with integrated chemical manufacturers possessing captive furfural supply; scale advantage sits with flavor houses controlling downstream formulation relationships. The market structures around three tiers: commodity enolone producers, pharmaceutical-grade specialists, and integrated flavor system providers. Two dominant competitive moves define current positioning: backward integration into pyrolysis feedstock supply and long-term service contracting with beverage procurement teams.
Within the integrated chemical tier, Anhui Jinhe Industrial Co., Ltd. exemplifies captive supply chain advantages through Shandong province manufacturing concentration. Solvay S.A. occupies the pharmaceutical-grade specialist position, anchoring European REACH-certified production. Firmenich International SA represents the flavor house integration archetype, absorbing procurement risk into beverage industry formulation service contracts.
| Leading Market Players |
|---|
| Firmenich International SA |
| Solvay S.A. |
| Merck KGaA (Sigma-Aldrich) |
| Anhui Jinhe Industrial Co., Ltd. |
| Beijing Tianlihai Chemicals |
| Vigon International, Inc. |
| Zhaoqing Perfumery |
| Xiamen Bestally Biotechnology |
| Foodchem |
| Others |
Pricing and Supply Chain Analysis
Overcapacity signals from Shandong province's integrated furfural-to-maltol facilities are compressing spot pricing for food-grade material while simultaneously eleving pharmaceutical-grade premiums. This utilization divergence forces Western producers toward certification-intensive specialization or exit from commodity segments.
Pricing Analysis
Geographic price spreads between Shandong-manufactured food-grade maltol and REACH-certified Belgian pharmaceutical-grade ethyl maltol exceed threefold at equivalent volumes. Three-tier pricing structure across pharmaceutical, food-grade, and fragrance specifications reflects certification burden and residual solvent testing requirements. Cost compression in commodity food-grade tiers intensifies because Anhui Jinhe Industrial's captive pyrolysis feedstock eliminates margin for non-integrated rivals. Small-scale artisanal food manufacturers exhibit highest price sensitivity, while pharmaceutical excipient buyers absorb premiums for validated supply chain documentation.
Supply Chain Analysis
Extended payment terms from Shandong producers are restructuring working capital requirements for European distributors unable to match Chinese supply-chain finance facilities. Raw material sourcing draws from corn cob and oat hull pyrolysis concentrated in China, with secondary furfural supply from South African bagasse operations and limited Thai rice husk capacity. Single-source vulnerability runs through Shandong's chemical corridor, where over 60 percent of merchant furfural originates from integrated parks. Distribution runs through flavor house consolidation in North America and direct pharmaceutical contracting in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation-derived maltol from engineered yeast strains is disrupting synthetic route economics at pilot scale, creating urgency around certification moats and feedstock control. This technological inflection compresses the window for strategic repositioning.
For Market Incumbents: Insulate pharmaceutical-grade positioning through EP and USP certification investments before bio-based alternatives achieve scale economics. Backward integration into captive furfural supply or long-term offtake agreements with Shandong pyrolysis operators secures margin against feedstock volatility. Solvay S.A.'s REACH-certified Belgian facilities demonstrate the defensive value of regulatory moats.
For New Entrants and Emerging Players: Pursue Indian pharmaceutical excipient white space as CDSCO expands USP-grade import approvals for generic drug formulations. Target Maharashtra and Gujarat generic manufacturers with validated heavy metal documentation and residual solvent testing capabilities. Direct sales contracting bypassing traditional chemical distributors reduces customer acquisition friction.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated flavor houses absorbing procurement risk into long-term beverage formulation service contracts. Five-to-ten year viability favors assets with captive feedstock supply or downstream formulation integration rather than standalone enolone synthesis. Monitor EFSA re-evaluation timelines for infant nutrition purity thresholds as regulatory inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Furfural Supply | Anhui Jinhe Industrial's captive pyrolysis operations demonstrate margin protection against agricultural commodity cycles. |
| Pharmaceutical-Grade Certification Investment | Solvay S.A.'s REACH-compliant Belgian facilities command excipient premiums through validated residual solvent documentation. |
| Flavor House Partnership Consolidation | Firmenich International SA absorbs maltol procurement risk into long-term beverage formulation service contracts. |
| Continuous Flow Reactor Adoption | Plug-flow systems for furfural oxidation meet EP certification requirements that batch reactors cannot satisfy. |
| Indian Market Entry via CDSCO Pathway | Generic drug manufacturers in Maharashtra expand USP-grade sourcing as import approvals broaden. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC filings from listed chemical producers, EFSA flavoring substance evaluations, and SAMR national food safety standards. Plant managers at Shandong integrated facilities, procurement leads at North American beverage manufacturers, distribution channel partners in European fragrance markets, and technical R&D directors at pharmaceutical excipient suppliers contributed interview data. Bottom-up volume triangulation from production facility capacity and top-down demand validation from end-use consumption patterns were cross-referenced.
Forecast inputs include grade-tier segmentation across pharmaceutical, food-grade, and fragrance specifications; end-use industry differentiation between beverage, confectionery, and excipient applications; and regional production hub clustering in Shandong, Wallonia, and emerging Indian import channels. CAGRs were derived from elasticity modeling against furfural feedstock pricing and regulatory compliance cost trajectories. Fermentation substitution timelines and EFSA re-evaluation schedules provided industry-specific scenario boundaries.
Sensitivities concentrate around bio-based maltol scale-up velocity, REACH purity threshold enforcement intensity, and Chinese environmental regulation implementation at provincial level. Forecasts reflect documented assumptions regarding feedstock supply continuity and certification timeline stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Xylitol Market
Sweeteners
Natural Malt Sweeteners Market
Sweeteners
Granulated Sugar Market
Sweeteners
Xylitol Injection Market
Sweeteners
Sucrose Esters Market
Sweeteners
North America Stevia Market
Sweeteners
Sugar Beet Juice Extract Market
Sweeteners
Sorbitol Market
Sweeteners
Crystalline Fructose Market
Sweeteners
China Food Sweetener Market
Sweeteners
Global Low Intensity Sweeteners Market
Sweeteners
Monk Fruit Sweetener Market
Sweeteners
Sugar Syrups Market
Sweeteners
D-Mannose Market
Sweeteners
Coconut Sugar Market
Sweeteners
Refined Cane Sugar Market