
 Steviol Glycoside Market | 2026-2036
Steviol Glycoside Market Size, Share, and Industry Trends Forecast 2026-2036
Steviol Glycoside Market Analysis
Organic certification under USDA NOP and equivalent EU organic standards is redrawing competitive boundaries in steviol glycoside supply chains. PureCircle leverages its vertically integrated cultivation and extraction footprint across multiple continents to sustain raw material security. HOWTIAN anchors its position through dominant manufacturing scale in China's stevia-growing belt, while Cargill competes via advanced bioconversion platforms that produce rare glycosides without conventional leaf extraction.
Steviol glycosides comprise a family of diterpene glycosides extracted from Stevia rebaudiana leaves, with sweetness intensities ranging from 200 to 400 times that of sucrose and minimal caloric contribution. Rebaudioside A and Rebaudioside D dominate product type demand, with Reb D gaining traction as cleaner-taste profiles displace earlier-generation stevioside formulations. Within end use, beverages represent the most mature revenue pool, though pharmaceuticals and nutraceuticals attract faster growth as tablet and syrup formulators seek sugar-reduction pathways that preserve label claims.
FDA GRAS determinations and EFSA purity specifications govern which glycoside variants achieve commercial scale in North American and European food systems, while China's NMPA and national food safety standards shape domestic and export-oriented production. JECFA specifications on steviol equivalent ratios further constrain formulation choices for multinational brands. Stakeholders must monitor evolving patent landscapes around enzymatic glycoside conversion, as these intellectual property positions will determine which suppliers can offer next-generation sweetness solutions without royalty burdens.
Market Dynamics
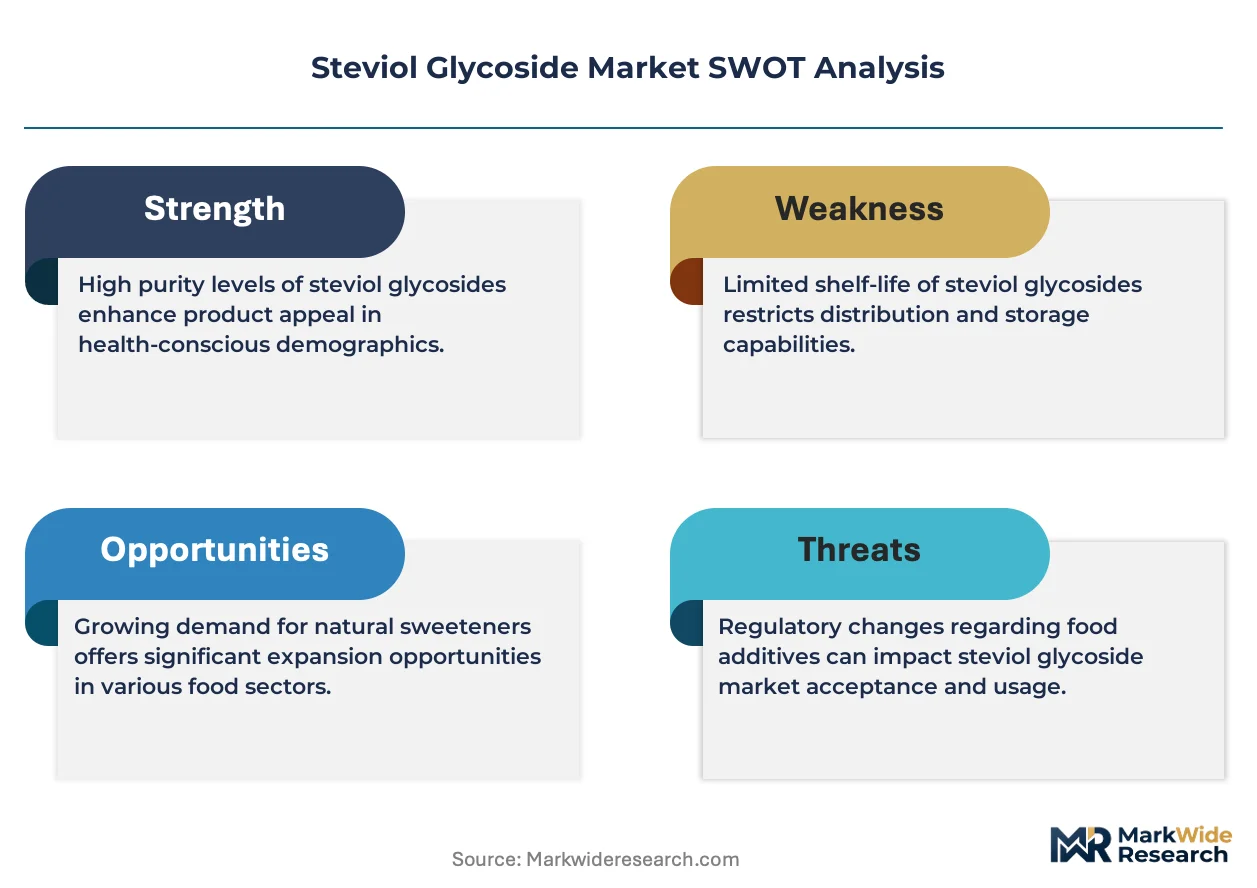
Enzymatic bioconversion is decomposing traditional leaf-extraction economics by enabling rare glycoside production without cultivation constraints, forcing incumbent extractors to retool processing infrastructure or cede premium product tiers to biotechnology platforms.
Growth Catalysts
- US FDA GRAS pathway acceleration:Streamlined notification procedures for novel steviol glycosides compress regulatory clearance timelines, enabling faster commercialization of Reb D and Reb M variants in North American beverage formulations.
- Carbonated drink reformulation:Major beverage manufacturers across Thailand, Indonesia, and Vietnam are systematically replacing sucrose and high-fructose corn syrup with steviol glycoside blends to meet sugar-reduction commitments.
- Enzymatic glycoside conversion:Cell-culture and fermentation-based production methods bypass agricultural yield variability, securing supply consistency for pharmaceutical tablet and syrup applications requiring precise sweetness profiles.
Market Restraints
- Agricultural input cost volatility:Stevia leaf prices fluctuate with water availability and labor costs in China's Yunnan and Guangdong cultivation belts, compressing extractor margins during drought cycles.
- Supply concentration risk:Over 70% of conventional leaf extraction capacity resides within 200 kilometers of Jining and Qingdao processing clusters, creating geographic vulnerability to regional logistics disruptions.
- Technical formulation limitations:Lingering bitter and licorice aftertastes in stevioside and early-generation Reb A restrict deployment in delicate flavor systems such as dairy and confectionery.
Strategic Opportunities
- Underpenetrated pharmaceutical applications:Pediatric and geriatric syrup formulators in Germany and France seek sugar-reduction pathways that preserve palatability without triggering glycemic response concerns.
- EU organic certification tailwinds:USDA NOP and EU organic standard equivalency agreements create premium pricing tiers for certified steviol glycosides in Scandinavian and Benelux health-food channels.
- Direct-to-manufacturer distribution platforms:Digital procurement marketplaces connecting Chinese extractors with European and North American formulators are compressing traditional distributor markups by 15-25 percentage points.
Industry Challenges
- Specialized bioprocess engineering talent scarcity:Fermentation-scale glycoside production requires hybrid skill sets spanning molecular biology and industrial chemical engineering, with qualified personnel concentrated in Basel, Boston, and Shanghai metropolitan clusters.
- Patent landscape navigation complexity:Dense intellectual property filings around enzymatic conversion pathways and specific glycoside crystal forms force prospective entrants into costly freedom-to-operate analyses or royalty-bearing license negotiations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steviol Glycoside Market |
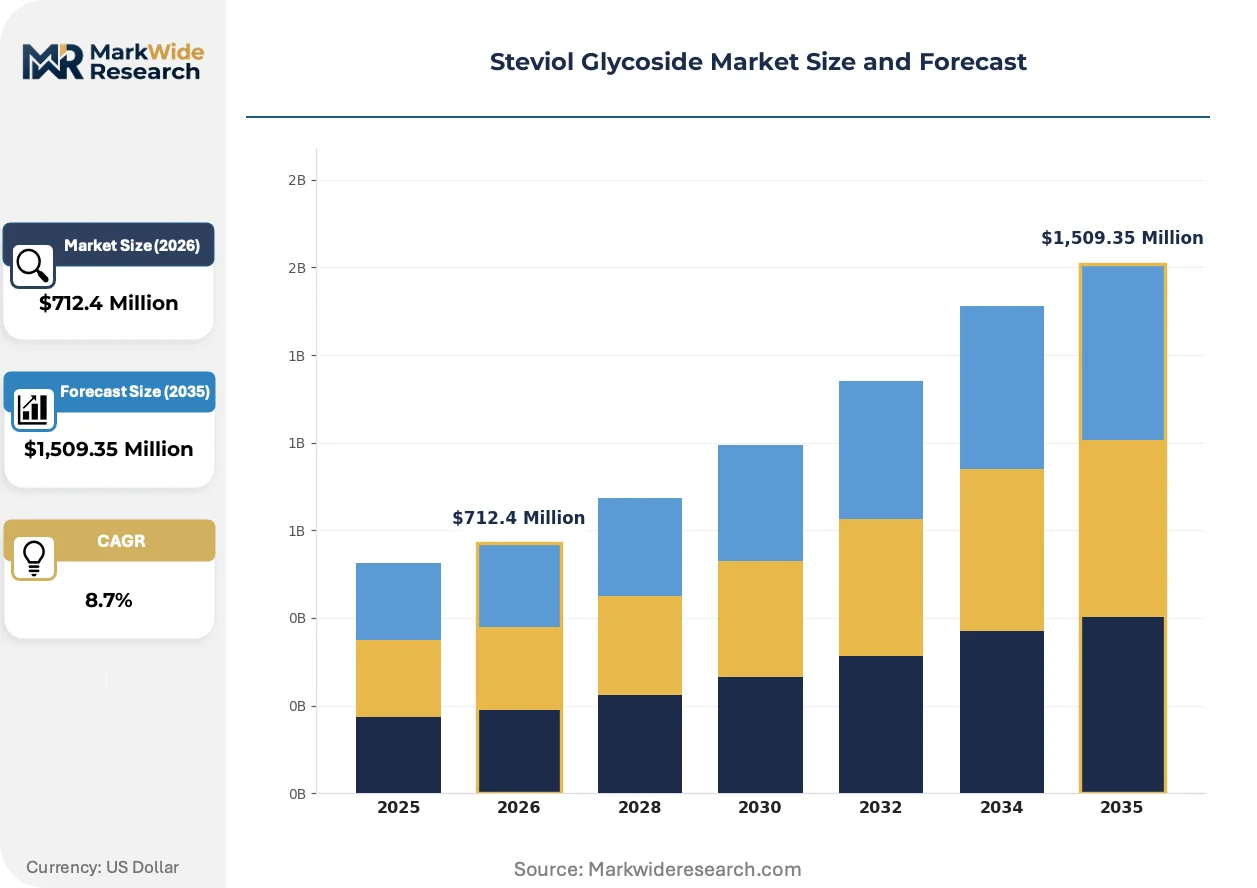
| Market Size in 2026 | $712.4 Million |
| Market Size in 2035 | $1,509.35 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rebaudioside A, Rebaudioside D, Stevioside, Rubusoside End Use: Beverages, Food Products, Pharmaceuticals, Nutraceuticals Form: Liquid Extracts, Powdered Form, Granulated Form, Crystalline Application: Sweetening Agent, Flavor Enhancer, Sugar Substitute, Dietary Supplement |
| Companies Covered | ADM, HOWTIAN, PureCircle, Sweegen, Sunwin Stevia International, Cargill, GLG Life Tech Corp, Layn Corp, Tate & Lyle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steviol Glycoside Market Emerging Trajectories
Biotechnology platforms are fundamentally restructuring production economics while regulatory harmonization efforts and procurement digitization reshape how value flows through steviol glycoside supply chains.
Precision fermentation is decomposing the century-old dominance of agricultural extraction by producing Rebaudioside M and Rebaudioside D through microbial cell factories. Pharmaceutical formulators and premium beverage developers are adopting these bioconverted glycosides at accelerating rates despite 20-40% cost premiums. This technology is compressing the addressable market for conventional leaf-based Reb A while creating entirely new competitive arenas around strain optimization and bioreactor scale-up.
EFSA's evolving purity specifications and JECFA's steviol equivalent ratio guidelines are tightening contaminant thresholds for glycoside variants entering European food systems. Manufacturers must now maintain separate production lines and analytical protocols for EU-bound versus other-destination shipments. Reb D and Reb M suppliers targeting infant nutrition and medical foods face the steepest compliance investments, with some redirecting capacity toward less stringently regulated Asian and Middle Eastern markets.
Formulator procurement patterns are migrating from annual volume contracts toward spot-market purchasing coordinated through specialized ingredient exchanges. Large beverage conglomerates in Brazil and Mexico now blend direct supplier relationships with platform-based purchasing to arbitrage price volatility between Chinese harvest seasons and bioconversion batch releases. This behavioral shift is most pronounced in carbonated and ready-to-drink categories where formulation flexibility permits rapid glycoside substitution.
Steviol Glycoside Market Segmentation
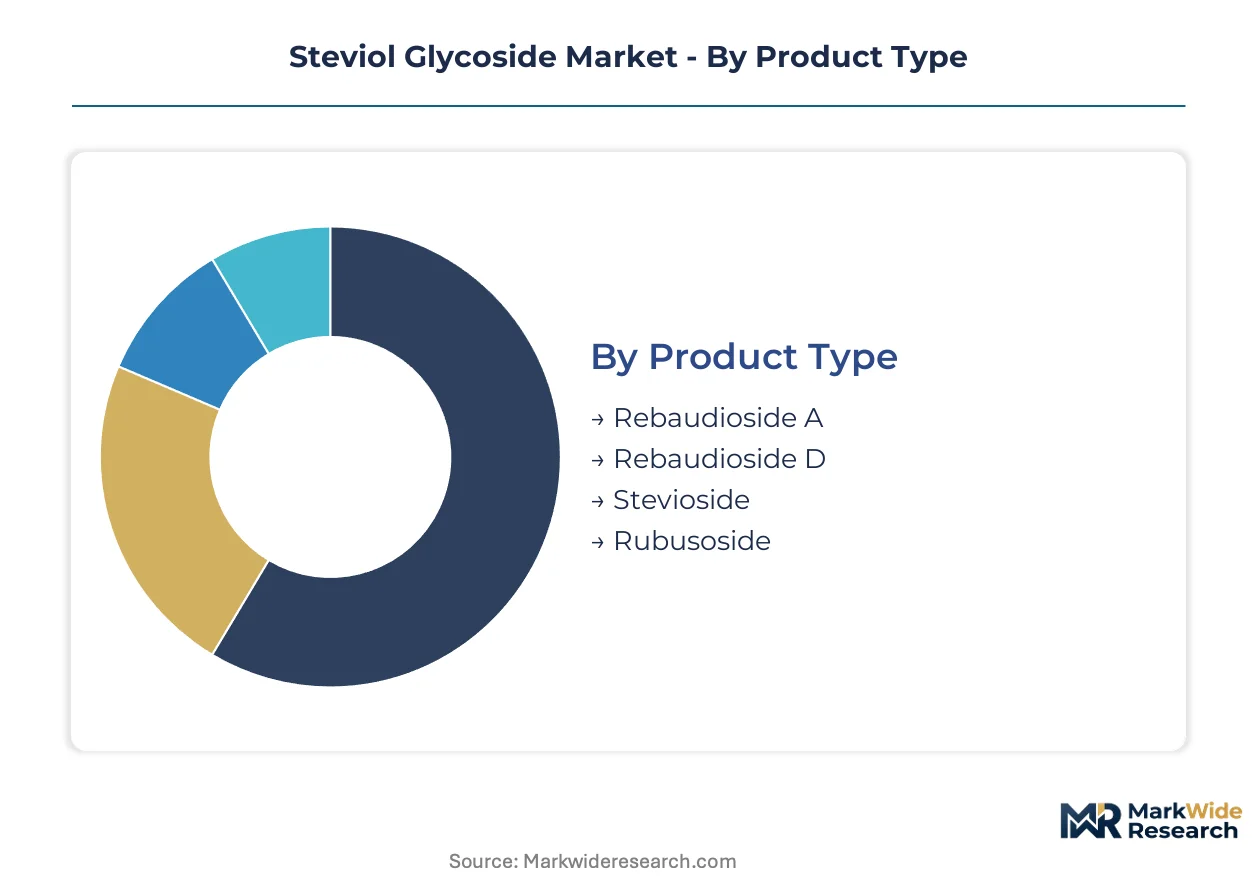
Segmentation in the steviol glycoside market determines formulation flexibility, regulatory pathway complexity, and procurement channel access. Each dimension—product chemistry, end-use application, physical form, and functional role—creates distinct margin profiles and customer access requirements.
Product Type:
Leaf-extracted and bioconverted variants flow through different channel structures, with fermentation-derived glycosides bypassing agricultural procurement networks entirely.
- Rebaudioside A:The most widely produced steviol glycoside, extracted through conventional leaf processing and standardized to 95-98% purity. Beverage manufacturers in Thailand and Indonesia source Reb A through established distributor networks for carbonated drink reformulation, though lingering bitter aftertastes limit deployment in premium applications.
- Rebaudioside D:Cleaner taste profile with reduced licorice notes, now produced via both leaf extraction and precision fermentation. North American beverage developers are prioritizing Reb D for ready-to-drink portfolios, with FDA GRAS notifications accelerating commercial adoption.
- Stevioside:Early-generation glycoside with pronounced bitterness, concentrated in cost-sensitive Asian markets and traditional medicine applications.
- Rubusoside:Minor glycoside with distinct pharmacological properties, extracted as a byproduct and directed toward research-scale pharmaceutical applications.
Rebaudioside A dominates installed base. Rebaudioside D is where expansion concentrates.
End Use:
Volume scale and margin structure diverge sharply across end-use categories, with beverage procurement driving economies of scale while pharmaceutical applications command specification premiums.
- Beverages:Carbonated soft drinks, ready-to-drink teas, and functional waters represent the largest consumption pool. Thai and Vietnamese bottlers are systematically replacing sucrose with steviol glycoside blends to meet sugar-reduction commitments.
- Food Products:Bakery, confectionery, and dairy applications require glycoside blends with masking agents to overcome aftertaste limitations. European organic certification creates premium pricing tiers in Scandinavian retail channels.
- Pharmaceuticals:Pediatric and geriatric syrup formulators in Germany seek sugar-reduction pathways that preserve palatability without glycemic impact.
- Nutraceuticals:Tablet and capsule applications favor high-purity Reb A and Reb D with documented steviol equivalent ratios for label compliance.
Beverages anchor volume throughput. Pharmaceuticals generate the steepest margin expansion.
Form:
Physical form selection determines handling infrastructure requirements, dissolution kinetics, and shelf-stability performance in finished goods.
- Liquid Extracts:Pre-dissolved glycoside solutions with standardized concentrations, preferred by beverage bottlers for direct dosing into batch tanks without powder handling infrastructure.
- Powdered Form:Spray-dried glycoside concentrates with bulk density optimized for pneumatic conveying systems, dominating industrial-scale food manufacturing.
- Granulated Form:Agglomerated particles with improved flow characteristics and reduced dusting, specified by pharmaceutical tablet compressors for precise dosing.
- Crystalline:High-purity single-glycoside crystals, produced through advanced purification and directed toward premium beverage and research applications.
Powdered form commands the broadest manufacturing footprint. Crystalline production is climbing the fastest.
Application:
Functional positioning within finished formulations dictates purity specifications, regulatory documentation requirements, and customer technical support intensity.
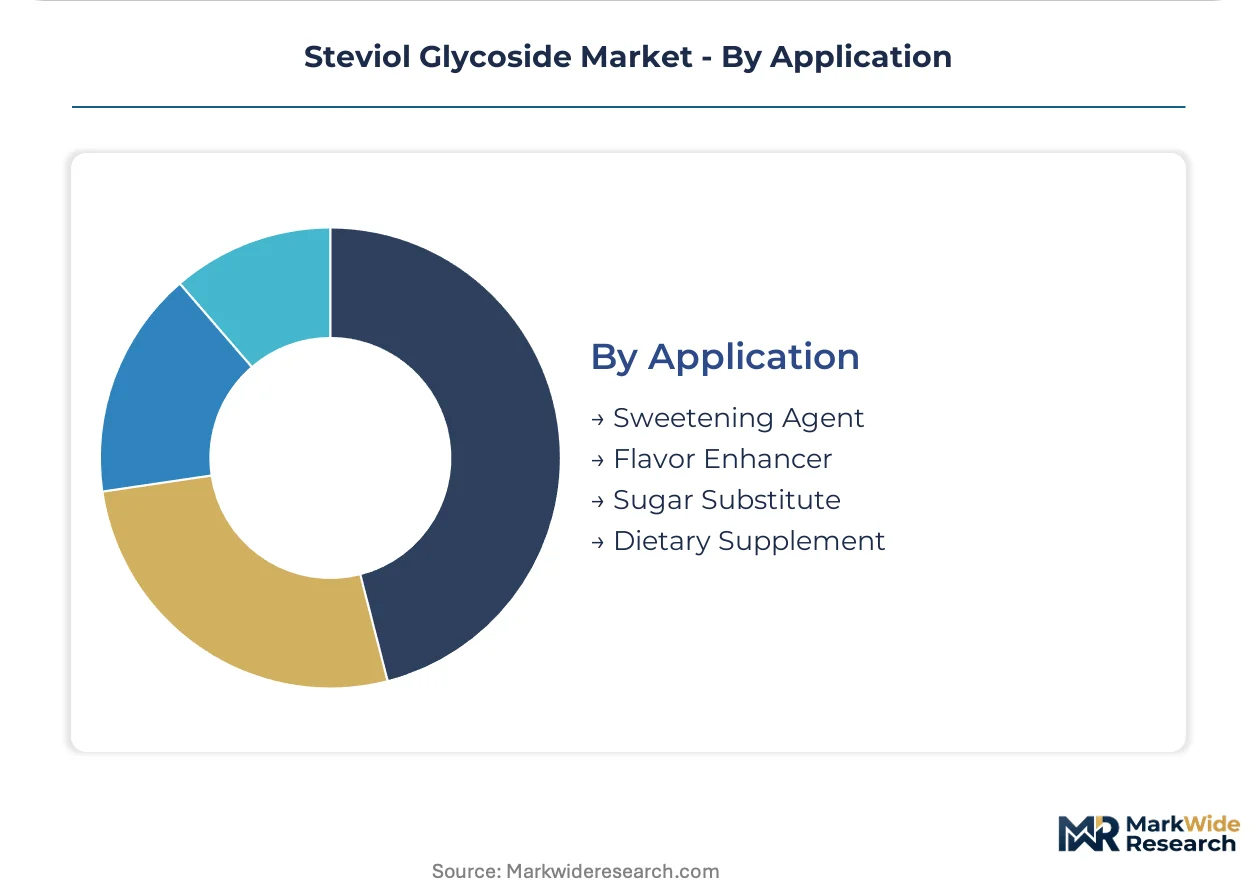
- Sweetening Agent:Primary caloric replacement function, with dosage calibrated to match sucrose sweetness equivalence in reformulated products.
- Flavor Enhancer:Sub-threshold glycoside additions that amplify other taste modalities without contributing perceptible sweetness.
- Sugar Substitute:Direct consumer-facing positioning in tabletop and retail baking applications, requiring clean-label marketing support.
- Dietary Supplement:Glycosides positioned for metabolic health claims, subject to stricter substantiation requirements in EU and US markets.
Sweetening agent applications absorb the majority of production volume. Dietary supplement positioning is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Qingdao-Jining processing corridor anchors China's steviol glycoside production, with dedicated rail links connecting Shandong Province extraction facilities to Qingdao Port for trans-Pacific shipment. This infrastructure underwrites the geography's dominance in global supply.
China
Yunnan and Guangdong cultivators supply leaf feedstock to Shandong-based extractors operating at industrial scale. NMPA food safety standards govern domestic production while GB standards shape export-oriented quality protocols. Jining and Qingdao processing clusters concentrate over 70% of conventional extraction capacity within a 200-kilometer radius.
United States
North American beverage formulators drive demand for Reb D and Reb M variants in carbonated and ready-to-drink portfolios. FDA GRAS notifications accelerate novel glycoside clearance timelines, compressing regulatory bottlenecks. Boston and California metropolitan areas host biotechnology platforms developing precision fermentation alternatives to leaf extraction.
Germany
Pediatric and geriatric syrup formulators in Germany seek sugar-reduction pathways that preserve palatability without glycemic impact. EFSA purity specifications and JECFA steviol equivalent ratio guidelines constrain glycoside variants entering European food systems. Frankfurt and Hamburg logistics hubs coordinate distribution to Scandinavian and Benelux health-food channels.
Thailand
Carbonated drink manufacturers systematically replace sucrose with steviol glycoside blends to meet sugar-reduction commitments. Thai FDA regulations align with ASEAN harmonized standards for sweetener approvals. Bangkok metropolitan bottling facilities source Reb A through established distributor networks for reformulated beverage portfolios.
Indonesia
Ready-to-drink tea and functional water producers adopt glycoside sweeteners across Java-based manufacturing operations. National food and drug administration requirements shape import documentation for Chinese-sourced extracts. Surabaya and Jakarta processing corridors integrate steviol glycosides into reformulated product lines targeting health-conscious consumers.
Steviol Glycoside Market Vendor Landscape
Listed leaders compete with private specialists across extraction technology and bioconversion capability dimensions. The vendor base stratifies between agricultural leaf processors and fermentation-platform operators, with hybrid models emerging at the intersection. Three archetypes dominate: vertically integrated cultivator-extractors, pure-play biotechnology platforms, and diversified ingredient conglomerates. Capacity expansion and enzymatic conversion licensing constitute the dominant competitive moves reshaping supply-side positioning.
Within the biotechnology-platform tier, Sweegen and Cargill exemplify fermentation-based production approaches that bypass agricultural constraints. HOWTIAN anchors the scale-driven extractor segment with dominant manufacturing presence in China's stevia-growing belt. PureCircle occupies a position bridging conventional extraction and advanced purification capabilities across multiple continental footprints.
| Leading Market Players |
|---|
| ADM |
| HOWTIAN |
| PureCircle |
| Sweegen |
| Sunwin Stevia International |
| Cargill |
| GLG Life Tech Corp |
| Layn Corp |
| Tate & Lyle |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day inventory cycles in Shandong Province extraction facilities concentrate pricing power among vertically integrated cultivator-extractors while compressing margins for toll processors dependent on spot leaf markets. This lead-time band reflects the agricultural seasonality of Yunnan and Guangdong cultivation belts, where water availability and labor costs transmit directly into raw material pricing volatility.
Pricing Analysis
Volume-discount tiering structures separate fermentation-derived Reb D and Reb M from conventional leaf-extracted Reb A, with bioconverted glycosides commanding premium positioning due to supply consistency. Price differentiation rests on purity certification levels and FDA GRAS notification status, with organic-certified variants under USDA NOP standards accessing Scandinavian health-food premiums. Cost compression in standard-grade Reb A is intensifying because enzymatic bioconversion platforms are displacing agricultural extraction for pharmaceutical applications. Beverage manufacturers in Thailand and Indonesia exhibit highest price sensitivity, while pediatric syrup formulators in Germany prioritize taste-profile consistency over unit economics.
Supply Chain Analysis
Inventory lead-time observations reveal stark bifurcation between cell-culture production with batch-to-batch predictability and leaf-extraction subject to climatic variability. Geographic supply concentrates in China, with Shandong Province processing clusters anchoring conventional extraction, while biotechnology platforms in the United States and Switzerland deploy precision fermentation. Raw material dependencies span stevia leaf feedstock, fermentation substrates, and enzymatic conversion catalysts. Single-source vulnerability concentrates in the Qingdao-Jining corridor where over seventy percent of leaf-extraction capacity resides within two hundred kilometers. Distribution runs through direct procurement relationships for large beverage conglomerates and specialized ingredient exchanges for mid-tier formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Steviol glycoside adoption sits in early-cycle expansion as precision fermentation platforms unlock rare glycoside production without agricultural constraints, accelerating penetration in pharmaceutical and premium beverage segments previously inaccessible to leaf-extracted variants.
For Market Incumbents: Consolidate backward integration into Yunnan and Guangdong cultivation belts to secure leaf feedstock against drought-driven price spikes, while simultaneously licensing enzymatic conversion patents to biotechnology platforms threatening premium tier displacement. Capacity additions in Shandong Province extraction facilities must parallel investments in FDA GRAS notification capabilities to maintain North American market access against fermentation-based competitors. For New Entrants and Emerging Players: Technical support gaps in pediatric and geriatric syrup formulation represent immediate white-space where incumbent extractors under-serve European pharmaceutical customers seeking sugar-reduction pathways with documented steviol equivalent ratios. Direct-to-manufacturer digital procurement platforms offer the most penetrable channel structure, compressing traditional distributor markups by connecting Chinese extractors with mid-tier European and North American formulators lacking established supplier relationships. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified ingredient conglomerates seeking to divest non-core sweetener divisions amid biotechnology platform competition, particularly extraction assets with stranded capacity as fermentation economics improve. Long-term viability favors hybrid models combining agricultural security with bioconversion licensing flexibility. Patent expiration timelines around enzymatic glycoside conversion signal inflection points for royalty-free production expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Bioconversion Licensing | Fermentation platforms bypass agricultural yield variability while securing pharmaceutical-grade supply consistency. |
| Backward Integration into Cultivation | Captive leaf feedstock from Yunnan and Guangdong belts insulates margins against drought-driven input volatility. |
| FDA GRAS Notification Investment | Accelerated regulatory clearance timelines compress commercialization bottlenecks for Reb D and Reb M variants. |
| Organic Certification Program | USDA NOP and EU organic equivalency unlocks premium pricing tiers in Scandinavian and Benelux health-food channels. |
| Direct-to-Manufacturer Platform Launch | Digital procurement marketplaces disintermediate traditional distributors, capturing margin compression value. |
Methodological Framework
Desk research of FDA GRAS notification databases, EFSA purity specifications, JECFA steviol equivalent guidelines, and Chinese GB standards preceded structured interviews with extraction plant managers, beverage formulation scientists, pharmaceutical procurement leads, and biotechnology platform engineers. Secondary validation drew from customs trade data, patent filings around enzymatic conversion pathways, and SEC filings of listed ingredient suppliers. Bottom-up volume modeling across product type, end use, and form segments triangulated against top-down market sizing from production capacity assessments.
Variance-decomposition framing isolates volume, price, and mix effects across the projection horizon, with analytical outputs reflecting segmented CAGRs derived from adoption curve modeling in beverages, pharmaceuticals, and nutraceuticals. Segmentation dimensions span glycoside chemistry, physical form, application function, and regional regulatory clusters. Forecast inputs incorporate biotechnology platform scale-up timelines, EFSA evolving purity specifications, and procurement pattern shifts toward spot-market purchasing.
Underlying assumptions cover FDA GRAS pathway continuity, EFSA-JECFA regulatory harmonization, and enzymatic bioconversion cost curves, with deviation risk concentrated in patent litigation around glycoside crystal forms and agricultural input cost spikes in Chinese cultivation belts. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Sorbitol Market
Sweeteners
Global Stevia Sugar Blends Market
Sweeteners
North America Plant-Derived and Synthetic Sugar Market
Sweeteners
Fructose Market
Sweeteners
Global Starch Sweetener Market
Sweeteners
Natural Caloric Sweeteners Market
Sweeteners
Sugar Alcohol Market
Sweeteners
Canada Food Sweetener Market
Sweeteners
Sugar Market
Sweeteners
South Korea Allulose Market
Sweeteners
Reduced Sugar Products Market
Sweeteners
Sodium Saccharin Market
Sweeteners
United States Xylitol Market
Sweeteners
Invert Sugar Market
Sweeteners
Sucralose Market
Sweeteners
Xylitol Injection Market