
 Orthopedic Insole Manufacturing Thermosealer Market | 2026-2036
Orthopedic Insole Manufacturing Thermosealer Market Size, Share, and Industry Trends Forecast 2026-2036
Orthopedic Insole Manufacturing Thermosealer Market Insights
Modular packaging of thermosealing units with CAD-compatible pressure-mapping systems is restructuring how orthopedic workshops evaluate capital equipment. Bauerfeind AG leverages its German manufacturing footprint to dominate European supply of integrated thermosealer-workstation bundles. Spenco Medical Corporation specializes in North American distribution channels for mid-volume sealing equipment. ComfortFit Orthotic Labs, Inc. anchors its competitive position through deep vertical integration into custom orthotic fabrication workflows.
An orthopedic insole manufacturing thermosealer is a heat-sealing apparatus that applies controlled thermal energy to thermoplastic materials used in custom foot orthotics, operating at precise temperature ranges to bond multi-layer EVA, cork, or carbon fiber composites without degrading material properties. Continuous band thermosealers lead volume deployment in high-throughput footwear manufacturing lines where belt-driven sealing enables uninterrupted production cycles. Induction heating technology represents the fastest-expanding segment as workshops adopt electromagnetic energy transfer for reduced thermal lag and improved seal consistency across variable material thicknesses. Portable thermosealers occupy a concentrated margin pool serving mobile orthopedic clinics and sports medicine practices requiring point-of-care fabrication capability.
The FDA enforces quality system regulation validation for thermosealing equipment deployed in medical device manufacturing, while the EU MDR mandates technical documentation and conformity assessment for thermosealers producing CE-marked orthotic devices. ISO 13485 certification requirements shape supplier qualification criteria, effectively filtering equipment vendors from workshop procurement lists. Stakeholders must monitor evolving harmonized standards for electromagnetic compatibility and biocompatibility testing as regulatory scope broadens beyond finished orthotics to encompass production equipment itself.
Market Dynamics
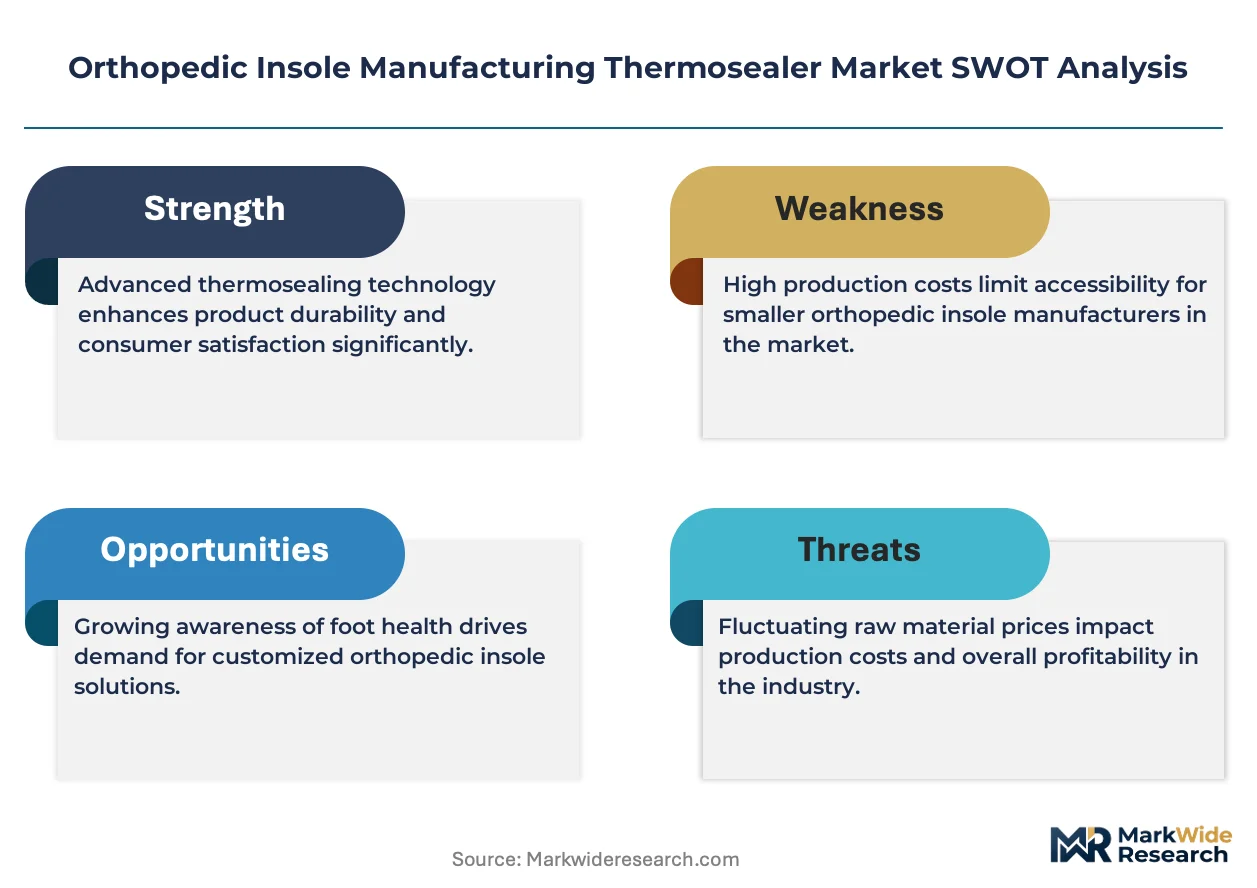
The orthopedic insole manufacturing thermosealer market is being fundamentally restructured by the convergence of EU MDR equipment validation mandates with modular CAD-integrated workstation procurement patterns, forcing orthopedic workshops to treat thermosealers as regulated medical device production assets rather than general fabrication tools.
Growth Catalysts
- EU MDR Technical Documentation Mandate:Workshops across Germany, France, and Italy must now deploy validated thermosealing equipment for CE-marked orthotics, creating replacement demand for legacy unvalidated units.
- Sports Medicine Clinic Expansion:Custom-molded insole procurement by sports equipment providers is accelerating as athletic performance optimization drives podiatric service integration into training facilities.
- Induction Heating Adoption:Electromagnetic energy transfer technology is displacing conventional thermal methods in high-precision workshops seeking reduced thermal lag across variable EVA and carbon fiber composite thicknesses.
Market Restraints
- Copper Coil Supply Concentration:Induction heating thermosealers depend on specialized copper winding components sourced primarily from Chinese electrical component manufacturers, exposing European workshops to input volatility.
- FDA Quality System Validation Burden:US-based orthopedic device manufacturers face extended equipment qualification timelines under 21 CFR Part 820, compressing capital deployment flexibility.
- Manual Thermosealer Substitution:Low-volume orthopedic practices in price-sensitive markets continue deploying handheld heat guns for single-patient orthotics, limiting addressable market expansion for automated equipment.
Strategic Opportunities
- Mobile Point-of-Care Fabrication:Portable thermosealer units present white space penetration potential in sports medicine practices and military field medical units requiring deployable orthotic production capability.
- ISO 13485-Certified Equipment Bundling:Workshops are consolidating vendor relationships around suppliers offering pre-validated thermosealer-CAD workstation packages, reducing internal quality system documentation burden.
- India PLI Scheme Alignment:Medical device manufacturing incentives under India's Production Linked Incentive scheme are attracting thermosealer suppliers to establish localized assembly for domestic orthopedic workshop supply.
Industry Challenges
- Electromagnetic Compatibility Certification:Thermosealer manufacturers face complex multi-jurisdiction testing for IEC 60601-1-2 compliance, particularly for induction heating variants generating radio frequency interference.
- Legacy Pneumatic System Integration:Workshops with established compressed air infrastructure encounter friction retrofitting modern electric thermosealers into workflows designed around pneumatic actuation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Orthopedic Insole Manufacturing Thermosealer Market |
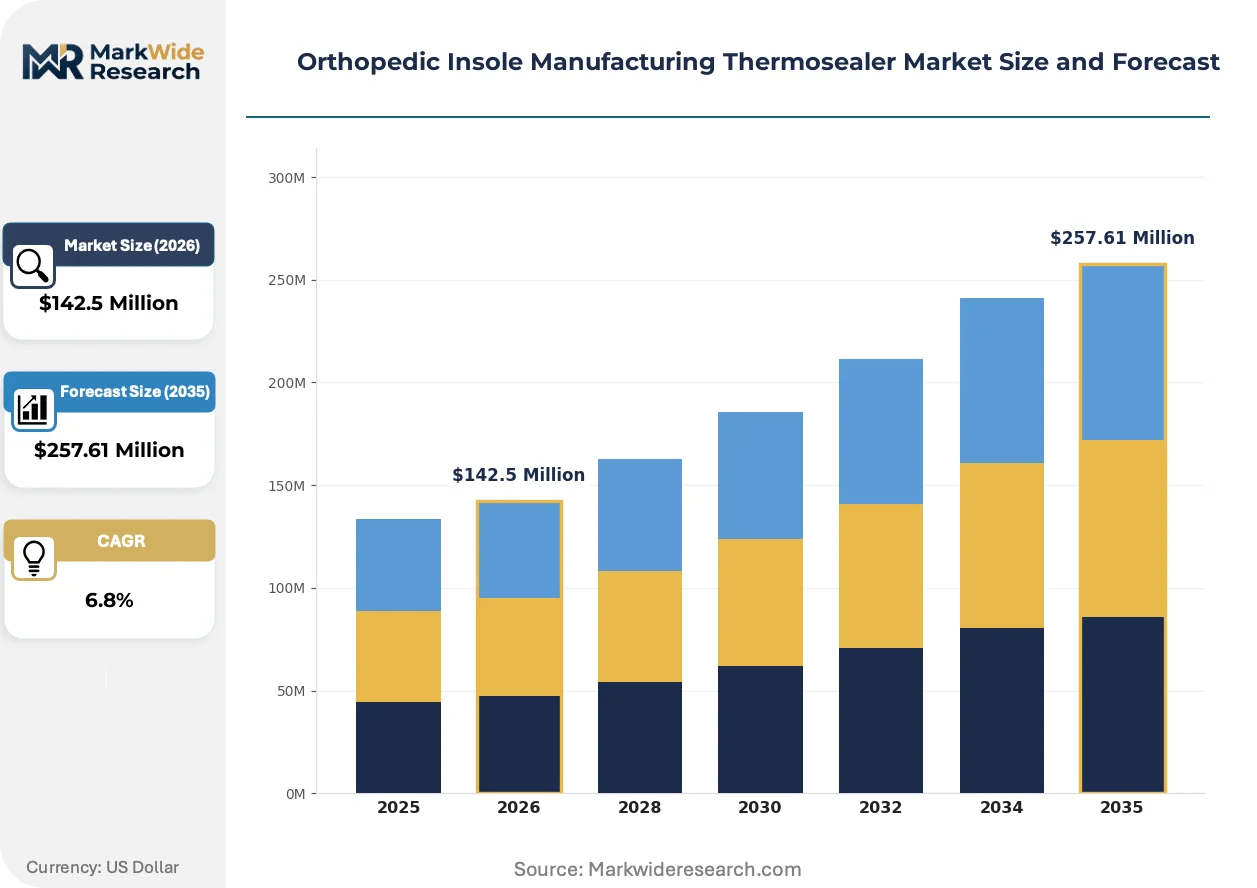
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $257.61 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Impulse Thermosealer, Continuous Band Thermosealer, Button-Type Thermosealer, Portable Thermosealer Technology: Electric Heating, Pneumatic Heating, Induction Heating, Infrared Heating, Ultrasonic Sealing Application: Custom Orthotics, Sports Insoles, Diabetic Footwear, Work Safety Footwear, Pediatric Insoles End User: Orthopedic Workshops, Footwear Manufacturers, Medical Clinics, Rehabilitation Centers, Sports Equipment Providers |
| Companies Covered | ComfortFit Orthotic Labs, Inc., Spenco Medical Corporation, Bauerfeind AG, Orthofeet Inc., Footbalance System Ltd., Aetrex Worldwide, Inc., Powerstep, Tynor Orthotics Pvt. Ltd., Hanger Clinic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Orthopedic Insole Manufacturing Thermosealer Market Trends and Innovations
Heat-sealing technology for orthopedic applications is undergoing rapid functional integration, with equipment vendors racing to embed process validation, pressure mapping compatibility, and regulatory documentation automation into unified workstation platforms.
Induction heating thermosealers are unifying temperature control precision with electromagnetic energy delivery across multi-layer composite materials. German orthopedic workshops around Düsseldorf are adopting these systems at accelerated pace to meet EU MDR process validation requirements. This technology convergence is compressing the competitive window for conventional resistance-heating equipment suppliers unable to demonstrate equivalent seal consistency documentation.
EU MDR Annex I general safety and performance requirements are extending conformity assessment scope to production equipment itself, not merely finished orthotic devices. Thermosealer manufacturers must now generate technical documentation demonstrating electromagnetic compatibility and biocompatibility of materials contacting patient-facing components. Mid-volume orthopedic workshops in France and Italy are prioritizing equipment vendors with established notified body relationships to accelerate procurement approval.
Buyer consolidation around integrated workstation procurement is displacing standalone thermosealer purchases in European orthopedic clusters. Workshops are negotiating bundled contracts combining sealing equipment with CAD-compatible pressure mapping systems and automated documentation software. This purchasing pattern shift is most visible in Germany's Berlin orthopedic workshop cluster, where capital committees now evaluate total workflow validation rather than isolated equipment specifications.
Orthopedic Insole Manufacturing Thermosealer Market Segmentation
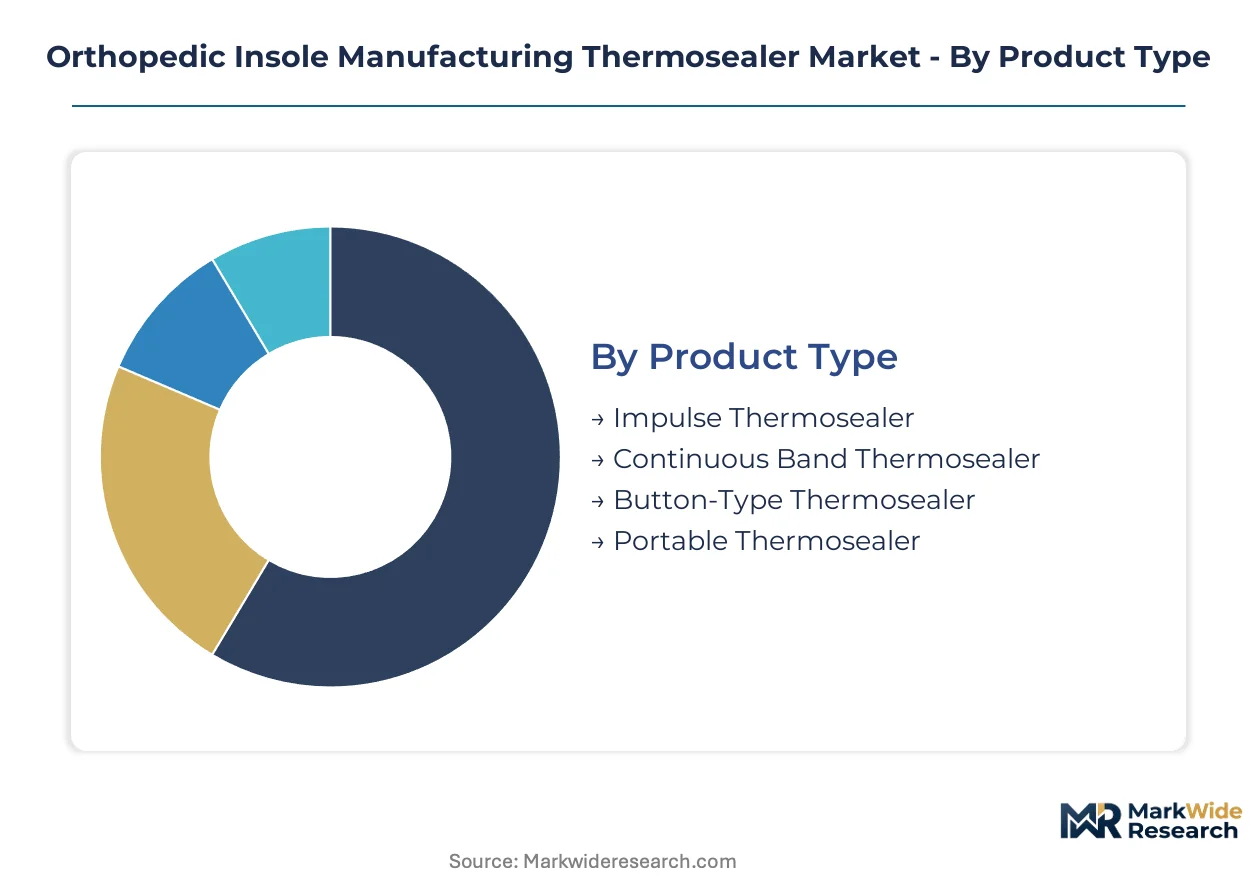
Thermosealer procurement patterns diverge sharply between standalone units for low-volume workshops and embedded systems for integrated CAD-workstation bundles. Orthopedic device manufacturers select equipment based on validation requirements, throughput needs, and material compatibility constraints.
Product Type:
Standalone thermosealers serve isolated sealing tasks in small workshops, while embedded variants integrate into automated production lines with CAD and pressure-mapping systems.
- Continuous Band Thermosealer:Belt-driven sealing mechanisms enable uninterrupted production cycles across multi-layer EVA and carbon fiber composites. Demand concentrates in Germany's Düsseldorf orthopedic cluster where high-throughput workshops process medical-grade orthotics under EU MDR validation mandates. The thermal consistency documentation these systems generate satisfies notified body requirements for CE-marked device production.
- Portable Thermosealer:Battery-powered or lightweight electric units deploy to mobile clinics and sports medicine practices requiring point-of-care fabrication. Sports equipment providers in North American training facilities are expanding procurement of these units to deliver same-day custom-molded insoles for athletic performance optimization.
- Impulse Thermosealer:Resistance-heating jaws deliver rapid thermal pulses for single-patient orthotics in low-volume settings.
- Button-Type Thermosealer:Manual actuation systems persist in price-sensitive markets where workshops prioritize capital cost over throughput.
Volume placements concentrate in Continuous Band Thermosealers; the faster expansion belongs to Portable Thermosealers.
Technology:
Cost tiers separate legacy thermal methods from precision electromagnetic and ultrasonic alternatives, with mid-volume workshops facing upgrade pressure from regulatory validation requirements.
- Induction Heating:Electromagnetic energy transfer eliminates thermal lag across variable material thicknesses in carbon fiber and cork composites. German workshops around Berlin are adopting these systems at accelerated pace to meet EU MDR process validation requirements for CE-marked orthotics. The reduced heat degradation of thermoplastic materials improves seal consistency documentation for notified body submissions.
- Electric Heating:Resistance-element systems dominate installed base in European orthopedic workshops with established electrical infrastructure. Mid-volume French and Italian workshops continue deploying these units where pneumatic retrofit costs exceed upgrade budgets.
- Pneumatic Heating:Compressed air-actuated thermal systems persist in legacy workshops with existing infrastructure investments.
- Infrared Heating:Radiant energy delivery suits specialized applications requiring non-contact thermal treatment of sensitive composites.
- Ultrasonic Sealing:High-frequency mechanical vibration bonding emerges for thermoplastic elastomers incompatible with conventional thermal methods.
Electric Heating retains the largest installed base; Induction Heating is climbing the fastest as workshops replace legacy resistance systems.
Application:
Customer type determines equipment specification, with medical device manufacturers facing stricter validation requirements than commercial footwear producers.
- Custom Orthotics:Patient-specific foot orthoses require thermosealers capable of bonding multi-layer EVA, cork, and carbon fiber composites without degrading material properties. Orthopedic workshops in Germany's Berlin cluster prioritize equipment with ISO 13485 certification and automated documentation software to reduce internal quality system burden.
- Sports Insoles:Athletic performance optimization drives demand for rapid-curing systems in training facility fabrication labs. Sports equipment providers are expanding procurement of induction-heating units to deliver same-day custom-molded insoles with consistent mechanical properties across variable athlete biomechanics.
- Diabetic Footwear:Therapeutic insoles for neuropathic patients require biocompatible seal validation under EU MDR Annex I requirements.
- Work Safety Footwear:Industrial protective insoles prioritize durability testing documentation for employer liability compliance.
- Pediatric Insoles:Smaller form factors and growth-adjustment features demand precision temperature control for delicate material handling.
Custom Orthotics commands the highest equipment specification intensity; Sports Insoles is gaining share fastest among non-medical segments.
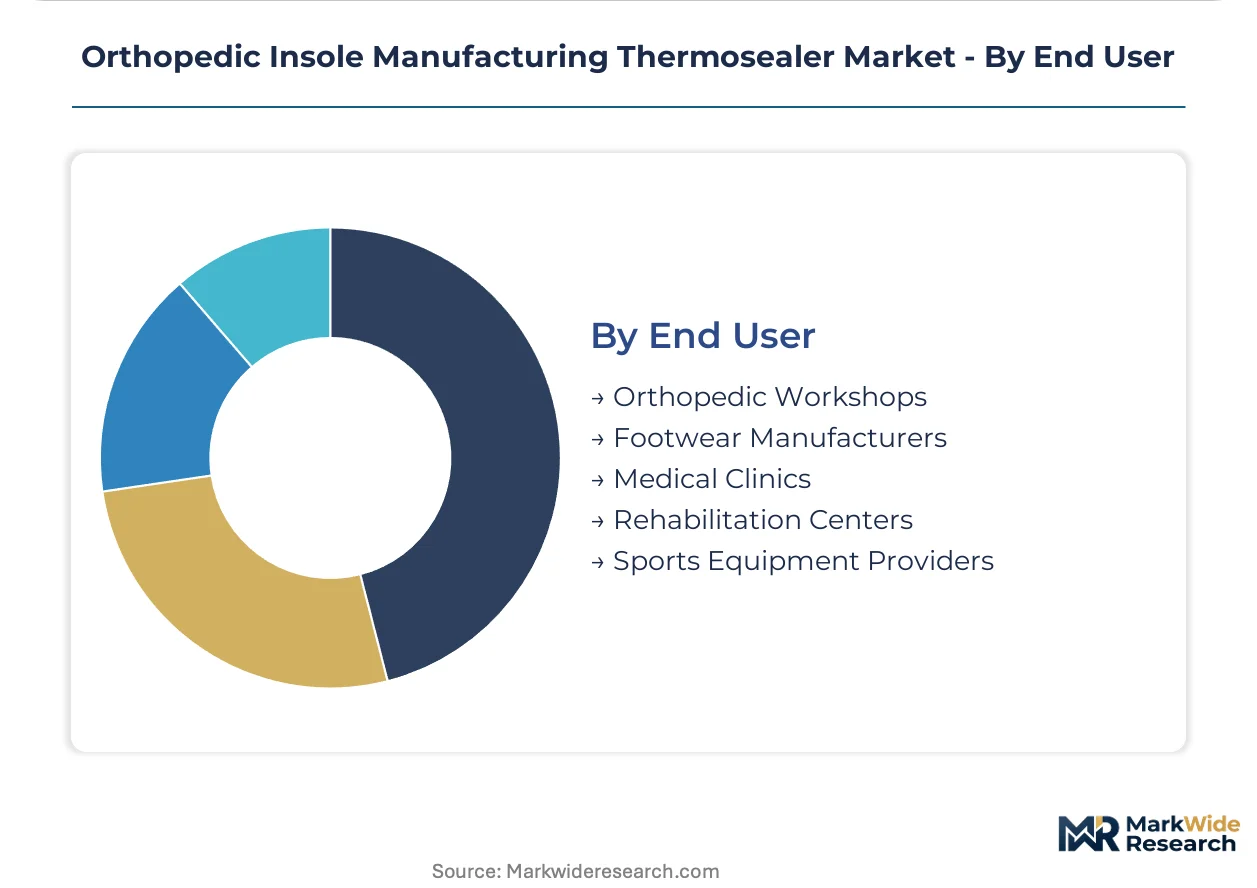
End User:
Procurement authority and validation expertise vary across workshop, manufacturing, and clinical settings, shaping vendor relationship structures.
- Orthopedic Workshops:German and Italian custom orthotic fabricators dominate equipment procurement, consolidating vendor relationships around bundled thermosealer-CAD workstation packages. These buyers evaluate total workflow validation rather than isolated equipment specifications, prioritizing suppliers with established notified body relationships.
- Footwear Manufacturers:High-volume commercial producers deploy continuous band systems in automated production lines. These customers prioritize throughput metrics and maintenance intervals over regulatory documentation depth.
- Medical Clinics:Hospital-based podiatry departments require portable or compact benchtop units for in-house orthotic fabrication.
- Rehabilitation Centers:Post-surgical and trauma recovery facilities balance patient-specific customization with reimbursement documentation requirements.
- Sports Equipment Providers:Athletic training facilities and professional team medical staffs represent emerging demand for point-of-care fabrication capability.
Orthopedic Workshops account for the deepest validation requirements; Sports Equipment Providers represents the steepest expansion trajectory among end-user categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany produces the majority of validated thermosealing equipment while the United States consumes portable units for point-of-care expansion. China supplies critical copper winding components for induction heating systems. India is emerging as an assembly location under medical device manufacturing incentives.
United States
Sports medicine clinics in training facilities are procuring portable thermosealers for same-day custom insole fabrication. The FDA enforces 21 CFR Part 820 quality system validation requirements on equipment used in medical-grade orthotic production. California and Texas host the densest concentrations of orthopedic device manufacturers upgrading legacy sealing systems.
Germany
Orthopedic workshops around Düsseldorf and Berlin dominate European demand for continuous band and induction heating thermosealers. The EU MDR mandates technical documentation and conformity assessment for equipment producing CE-marked devices. Bavaria's medical technology corridor supplies integrated thermosealer-CAD workstation bundles across the continent.
China
Domestic orthopedic workshops are adopting induction heating technology for carbon fiber composite sealing in custom orthotics production. The National Medical Products Administration requires registration of thermosealing equipment used in medical device manufacturing. Zhejiang and Jiangsu provinces concentrate copper coil component fabrication for global induction heating system supply.
India
Orthopedic workshops in Maharashtra and Gujarat are expanding procurement of mid-volume sealing equipment for domestic custom insole production. The Production Linked Incentive scheme for medical device manufacturing is attracting thermosealer suppliers to establish localized assembly. Tamil Nadu's medical device park is developing as a hub for equipment qualification under CDSCO oversight.
Italy
Mid-volume orthopedic fabricators in Lombardy and Emilia-Romagna are prioritizing equipment vendors with established notified body relationships for EU MDR compliance. The country's national pharmaceutical regulator enforces conformity assessment scope extension to production equipment itself. Milan's orthopedic workshop cluster is consolidating vendor relationships around pre-validated workstation packages.
Orthopedic Insole Manufacturing Thermosealer Market Competitive Landscape
The competitive structure tilts toward integrated equipment-workstation bundling as workshops seek to reduce internal quality system documentation burden. European and North American vendors dominate the premium tier through ISO 13485 certification and established regulatory relationships. Two strategic archetypes have emerged: vertically integrated orthotic laboratories with captive equipment supply, and specialized sealing equipment manufacturers with deep CAD integration capabilities. Dominant competitive moves include strategic partnerships between thermosealer producers and pressure-mapping software vendors, plus geographic expansion into Indian medical device manufacturing zones under PLI scheme alignment.
Among German fabricators, Bauerfeind AG anchors the integrated equipment-workstation bundle archetype through its domestic manufacturing footprint. Spenco Medical Corporation exemplifies North American distribution channel specialization for mid-volume sealing equipment. ComfortFit Orthotic Labs, Inc. occupies a position within the vertically integrated laboratory tier, leveraging backward integration into custom orthotic fabrication workflows to control equipment specification and deployment.
| Leading Market Players |
|---|
| ComfortFit Orthotic Labs, Inc. |
| Spenco Medical Corporation |
| Bauerfeind AG |
| Orthofeet Inc. |
| Footbalance System Ltd. |
| Aetrex Worldwide, Inc. |
| Powerstep |
| Tynor Orthotics Pvt. Ltd. |
| Hanger Clinic |
| Others |
Pricing and Supply Chain Analysis
EU MDR-mandated equipment validation for CE-marked orthotics is forcing orthopedic workshops to abandon legacy unvalidated thermosealers, compressing procurement timelines and concentrating buyer power around ISO 13485-certified suppliers capable of delivering pre-documented sealing systems. This specification shift is reshaping how vendors structure pricing and how component suppliers qualify for medical device manufacturing tiers.
Pricing Analysis
Margin tightening in mid-volume equipment reflects workshop consolidation around bundled thermosealer-CAD workstation packages. Pricing stratifies across premium induction-heating systems with full validation documentation, standard electric-heating units for established electrical infrastructure, and economy-tier manual sealers for price-sensitive single-patient practices. Cost compression accelerates in the standard tier as French and Italian workshops delay upgrades to manage pneumatic retrofit expenses. Sports equipment providers demonstrate lowest price sensitivity, prioritizing point-of-care deployment speed over capital cost.
Supply Chain Analysis
ISO 13485 certification gates entry for copper winding component suppliers feeding induction heating system manufacturers. Production concentrates in Germany for validated equipment assembly, China for specialized electrical components, and India for emerging localized assembly under PLI scheme incentives. Critical dependencies include precision copper coils from Zhejiang and Jiangsu provinces, thermoplastic composite feedstocks from Bavarian chemical corridors, and electromagnetic compatibility testing services from notified bodies in Milan and Berlin. Single-source vulnerability in Chinese copper component supply exposes European workshops to input volatility. Distribution runs through orthopedic workshop clusters rather than broad industrial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The orthopedic insole manufacturing thermosealer market sits in a technology-transition phase as induction heating displaces legacy resistance-heating systems, compressing the competitive window for equipment suppliers unable to demonstrate equivalent seal consistency documentation for EU MDR compliance.
For Market Incumbents: Acquire pressure-mapping software capabilities to defend against modular workstation bundling trends that threaten standalone thermosealer margins. Consolidate notified body relationships in Germany and Italy to accelerate procurement approval timelines for workshop customers facing compressed validation deadlines. Build backward integration into copper winding component supply to mitigate Chinese input volatility exposure. For New Entrants and Emerging Players: Capture mobile point-of-care fabrication demand in North American sports medicine clinics and military field medical units where portable thermosealer penetration remains underdeveloped. Target India's Maharashtra and Gujarat orthopedic workshop clusters where PLI scheme alignment creates localized assembly advantages against imported equipment. Lead with ISO 13485 pre-certification to bypass incumbent documentation advantages. For Investors and Strategic Acquirers: The window for entry favors specialized sealing equipment manufacturers with deep CAD integration capabilities over vertically integrated orthotic laboratories with captive equipment supply. Long-term viability hinges on electromagnetic compatibility certification expertise as regulatory scope broadens to production equipment itself. Watch induction heating adoption rates in Berlin and Düsseldorf workshop clusters as inflection indicators for technology displacement speed.| Strategic Initiative | Industry Significance |
|---|---|
| Notified Body Partnership | Accelerates EU MDR equipment validation for workshop procurement committees in Milan and Berlin. |
| Copper Coil Supply Agreement | Secures precision winding components from Zhejiang manufacturers against input volatility. |
| Pressure-Mapping Integration | Embeds thermosealers into CAD-compatible workstation bundles dominating German orthopedic clusters. |
| PLI Scheme Localization | Positions assembly operations in Tamil Nadu medical device park for Indian domestic supply. |
| Portable Unit Development | Addresses white space in sports medicine point-of-care fabrication across North American training facilities. |
Research Methodology
Trade association filings, medical device registration databases, and orthopedic workshop procurement records formed the secondary backbone of this analysis. Primary interviews with biomedical engineers, GPO contracts managers, and regulatory affairs specialists at notified bodies were combined with customs data and SEC equipment manufacturer disclosures. Bottom-up and top-down triangulation validated segment-level demand estimates across the analysis window.
Bottom-up modeling built from individual workshop equipment procurement patterns, while top-down constraints checked against aggregate medical device production statistics. Segmentation dimensions included heating technology type, equipment mobility class, end-user facility type, and regional regulatory cluster. CAGRs were derived from installed base replacement cycles and technology displacement curves. Forecast inputs incorporated EU MDR implementation timelines and sports medicine clinic expansion trajectories.
The model holds under steady regulatory enforcement intensity; deviation in FDA quality system interpretation or EU MDR notified body capacity would shift equipment qualification timelines. Forecasts reflect assumptions about copper component supply continuity and electromagnetic compatibility testing throughput. A model refresh is warranted upon material change in induction heating adoption rates or PLI scheme incentive structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
North America Kyphoplasty Market
Orthopedic Devices
India Orthopedic Braces and Supports Market
Orthopedic Devices
Orthopedic Wire Pin Driver Market
Orthopedic Devices
Orthopedic Braces Market
Orthopedic Devices
UAE Spinal Surgery Devices Market
Orthopedic Devices
Patients Repositioning and Offloading Device Market
Orthopedic Devices
Veterinary Orthopedic Drills Market
Orthopedic Devices
US Orthopedic Implants Market
Orthopedic Devices
Unicompartmental Knee Prosthesis Market
Orthopedic Devices
Chondroplasty Market
Orthopedic Devices
Spine Surgery Devices Market
Orthopedic Devices
Europe Orthopedic Devices Market
Orthopedic Devices
Revision Knee Replacement Market
Orthopedic Devices
Bone Graft Fixation System Market
Orthopedic Devices
Orthopedic Drill Bits Market
Orthopedic Devices
Global Orthopedic Implant Market