
 Sanding Machine Market | 2026-2036
Sanding Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Sanding Machine Market Analytics
Integration of IoT-enabled vibration monitoring and automated abrasive wear detection is reshaping sanding machine architecture across industrial lines. Biesse leverages connected sensor arrays to optimize belt tracking in high-throughput woodworking environments. HOMAG Group anchors European demand through its dominance in wide-belt systems for panel processing. Robert Bosch competes in the compact professional segment with battery platforms that extend runtime without tethered power constraints.
A sanding machine is a powered finishing tool that employs rotating, oscillating, or reciprocating abrasive surfaces to remove material from workpieces, typically operating at spindle speeds between 1,500 and 4,000 RPM depending on substrate density and desired surface roughness. Its primary industrial purpose is to prepare surfaces for coating, bonding, or final aesthetic presentation across wood, metal, and composite materials. Belt sanders occupy the largest installed base in heavy material removal applications where throughput determines equipment selection. Orbital sanders represent the fastest-expanding category among battery-operated platforms serving mobile contractors. Drum sanders retain concentrated margin pools in specialized hardwood flooring and precision dimensioning workflows.
OSHA enforces permissible exposure limits for respirable crystalline silica in construction and manufacturing environments, compelling sanding equipment makers to integrate dust collection interfaces and sealed motor housings. The EPA regulates volatile organic compound emissions from coating operations downstream of sanding stages, indirectly shaping abrasive selection and surface preparation protocols. EU REACH restrictions on hazardous substances in abrasives and binding resins constrain supply chains serving European manufacturers. Stakeholders must monitor evolving cordless power tool safety standards from IEC and regional battery transportation regulations as lithium-ion platforms expand market share.
Market Dynamics
EU F-Gas Regulation mandates refrigerant phase-downs that cascade into pneumatic system redesigns, forcing sanding equipment manufacturers to re-engineer motor housings and sealing architectures for low-emission compliance.
Growth Catalysts
- Battery platform maturation:Lithium-ion cell energy density improvements enable cordless belt sanders to match corded torque profiles, unlocking residential renovation workflows previously tethered to fixed power sources.
- OSHA silica exposure limits:Permissible exposure thresholds for respirable crystalline silica mandate integrated dust collection interfaces, creating replacement demand for legacy equipment lacking sealed motor housings.
- Hardwood flooring restoration:Drum sander demand concentrates in specialized contractors serving heritage building refurbishment and high-end residential refinishing across Germany and Italy.
Market Restraints
- Abrasive supply concentration:Synthetic corundum and silicon carbide production clusters in China's Henan and Ningxia provinces expose European and North American OEMs to freight cost volatility and export quota uncertainty.
- REACH substance restrictions:ECHA classification of certain binding resins as substances of very high concern forces abrasive reformulation, extending R&D cycles and compressing margin pools for European manufacturers.
- Manual finishing substitution:Automated CNC routing with integrated finish passes displaces standalone sanding stations in high-volume panel processing, narrowing the addressable market for wide-belt systems.
Strategic Opportunities
- India construction equipment channel:BIS certification alignment and domestic assembly partnerships position sanding equipment makers to capture infrastructure-driven woodworking demand in commercial real estate and furniture manufacturing clusters.
- IoT-enabled predictive maintenance:Vibration sensor arrays and cloud-connected abrasive wear algorithms create recurring revenue streams through consumable subscription models and remote diagnostics.
- EU Green Deal public procurement:Tender specifications prioritizing energy-efficient pneumatic systems and circular material recovery open public-sector woodworking facilities to premium equipment upgrades.
Industry Challenges
- Electronics-embedded mechanical engineering talent:Firmware development for brushless motor control and sensor fusion exceeds the skill base of traditional power tool engineering organizations, forcing competitive bidding for scarce embedded systems specialists.
- Dual certification timelines:IEC cordless power tool safety standards and regional battery transportation regulations require parallel testing tracks, delaying product launches by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sanding Machine Market |
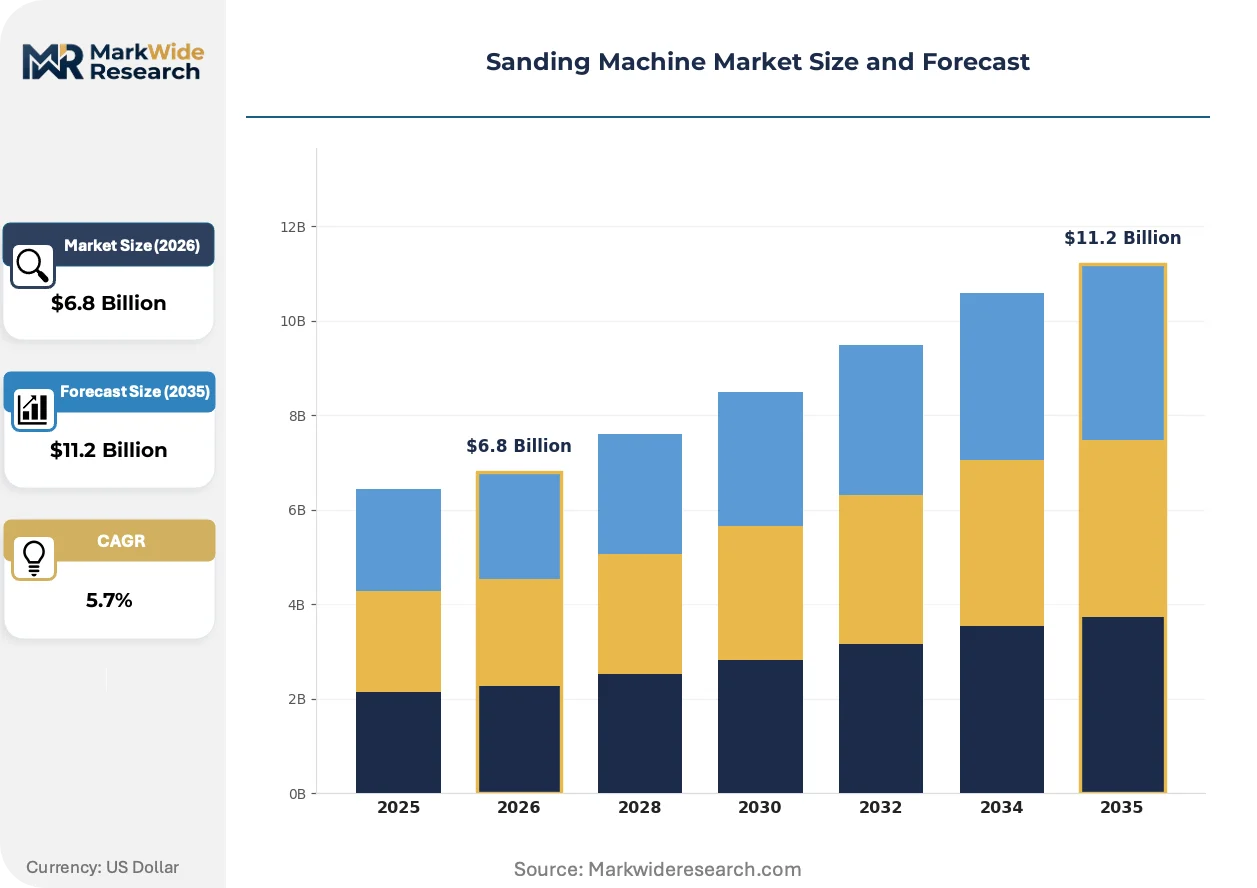
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Belt Sanders, Orbital Sanders, Handheld Sanders, Drum Sanders Application: Woodworking, Metalworking, Automotive Refinishing, Construction End User: Manufacturers, DIY Hobbyists, Contractors, Retailers Power Source: Electric, Pneumatic, Battery-operated, Hydraulic |
| Companies Covered | Biesse, SCM Group, HOMAG Group, Timesavers, Costa Levigatrici, Weinig, Robert Bosch, Makita Corporation, Festool, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sanding Machine Market Evolving Landscape
Connected sensor architectures and automated abrasive management systems are compressing equipment lifecycle economics while redefining operator skill requirements across industrial and professional segments.
Brushless DC motor controllers with integrated torque sensing are digitizing spindle load monitoring in real time. Cabinet furniture manufacturers in Italy adopt these platforms to eliminate manual feed-rate adjustments, compressing training curves for semi-skilled operators. The technology is digitizing quality consistency metrics that previously required dedicated inspection stations.
EPA enforcement of volatile organic compound emissions from coating operations downstream of sanding stages tightens surface preparation protocols. Manufacturers serving automotive refinishing and aerospace coating supply chains must document abrasive selection rationale and dust capture efficiency. Wide-belt systems in North American metal fabrication facilities face heightened documentation burdens for NESHAP compliance.
Equipment-as-a-service contracting displaces capital purchase models among mid-scale European woodworking cooperatives. Monthly fee structures bundle machine uptime guarantees, abrasive replenishment, and predictive maintenance alerts. Germany's Mittelstand furniture manufacturers demonstrate the strongest uptake, preferring operational expenditure classification for tax and balance-sheet treatment.
Sanding Machine Market Segmentation
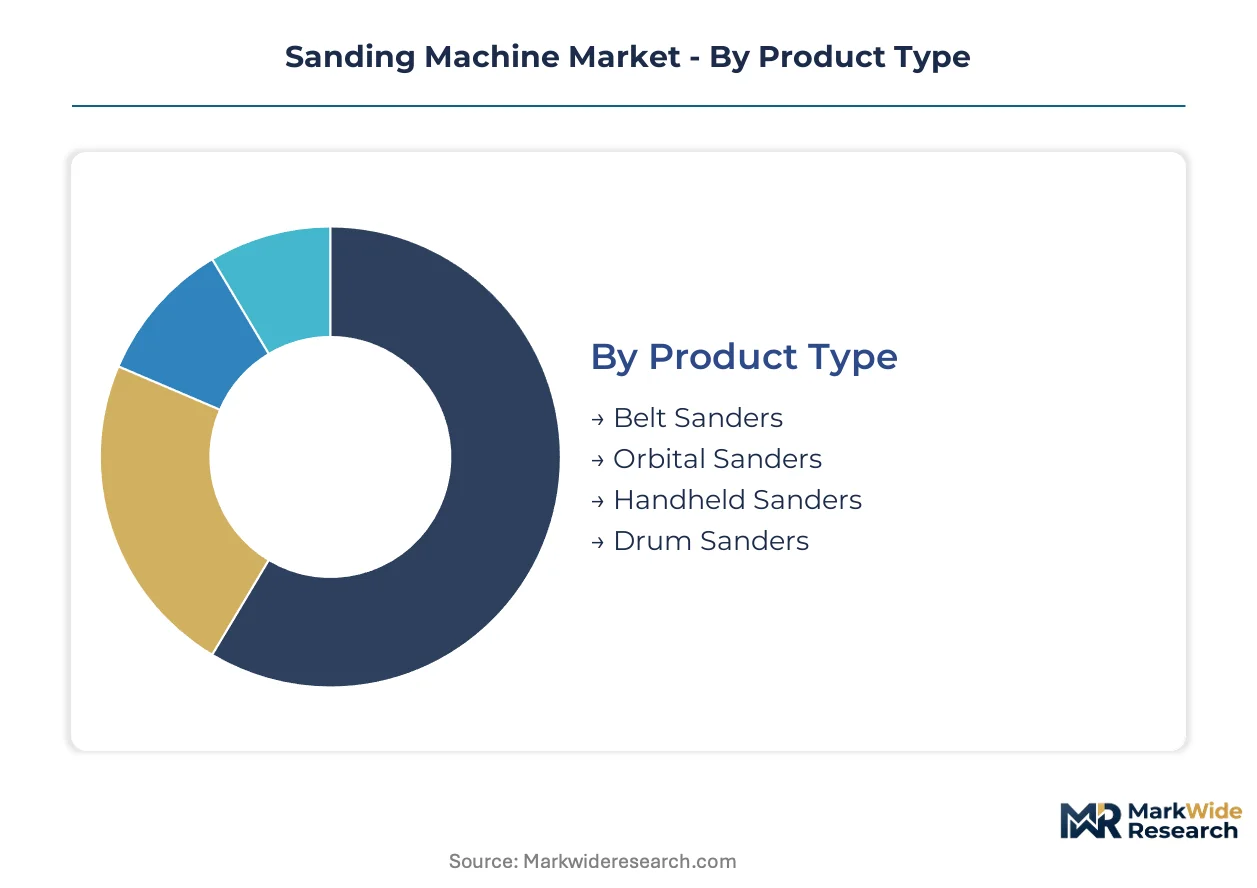
Sanding machine procurement patterns diverge sharply across power platforms, material substrates, and operator skill levels. Equipment specification requirements in regulated industrial environments differ fundamentally from residential renovation workflows, creating distinct margin architectures and replacement cycles.
Product Type:
Equipment architecture determines throughput capacity, surface finish quality, and operator mobility across material removal workflows.
- Belt Sanders:Continuous abrasive belt systems operating between 1,500 and 3,000 RPM deliver aggressive stock removal on flat surfaces. Demand concentrates in North American metal fabrication shops and European panel processing facilities where linear throughput dictates equipment selection.
- Orbital Sanders:Random-orbit action combining rotary and elliptical motion patterns minimizes visible scratch marks on final surfaces. Battery-operated platforms from Bosch and Makita dominate residential renovation channels in the United States and Canada, displacing corded units in mobile contractor toolkits.
- Handheld Sanders:Compact form factors prioritize operator maneuverability in confined spaces and vertical surfaces.
- Drum Sanders:Cylindrical abrasive drums excel in dimensioning hardwood flooring to precise thickness tolerances.
Belt sanders command the established base. The steepest expansion runs through orbital sanders.
Application:
Surface preparation protocols vary by substrate density, coating adhesion requirements, and downstream regulatory exposure.
- Woodworking:Cabinet furniture manufacturers in Italy and Germany drive wide-belt system demand for panel calibration and veneer preparation. EU F-Gas Regulation compliance requirements favor low-emission pneumatic configurations in high-volume production environments.
- Metalworking:Ferrous and non-ferrous deburring operations in automotive stamping plants and aerospace machine shops require specialized abrasive grits and integrated coolant delivery. OSHA silica exposure mandates are accelerating dust collection retrofit cycles in United States fabrication facilities.
- Automotive Refinishing:Clearcoat preparation and primer sanding demand consistent scratch pattern geometry to prevent coating defects.
- Construction:On-site drywall finishing and subfloor preparation prioritize portability and rapid abrasive changeover.
Woodworking anchors volume concentration. Automotive refinishing is gaining share fastest on coating quality standardization.
End User:
Procurement authority and total cost sensitivity separate institutional buyers from discretionary purchasers.
- Manufacturers:Capital equipment committees in German Mittelstand furniture cooperatives increasingly specify equipment-as-a-service contracts bundling uptime guarantees and predictive maintenance. Operational expenditure classification drives preference over traditional capital purchase models.
- Contractors:Mobile finishing crews in North American residential construction prioritize battery platform interoperability and rapid charging infrastructure. Milwaukee and DeWalt ecosystem lock-in influences repeat purchase patterns.
- DIY Hobbyists:Price-sensitive segment concentrated in big-box retail channels with limited technical support requirements.
- Retailers:Distribution intermediaries stocking entry-level and mid-tier professional equipment for walk-in trade.
Manufacturers dominate revenue contribution. Contractors show the steepest expansion trajectory on renovation demand.
Power Source:
Energy delivery architecture constrains torque profiles, emissions compliance, and tethered mobility.
- Electric:Corded AC motors deliver sustained torque for heavy material removal in fixed workstation configurations. European woodworking facilities favor three-phase industrial connections for wide-belt sanders in continuous production environments.
- Battery-operated:Lithium-ion cell energy density improvements above 250 Wh/kg enable belt sanders to match corded performance specifications. North American residential contractors are converting tool fleets to cordless platforms for site flexibility.
- Pneumatic:Compressed air systems eliminate brush motor maintenance in high-dust environments but require compressor infrastructure investment.
- Hydraulic:Specialized offshore and mining applications where explosive atmosphere certification prohibits electrical ignition sources.
Electric systems retain the installed base majority. Battery-operated configurations are climbing the fastest on lithium-ion platform maturation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics reveal a bifurcated trade pattern: Germany and Italy export precision wide-belt systems to North American panel processors, while China supplies abrasive consumables and entry-level handheld units to price-sensitive markets. This exchange concentrates value capture in European engineering centers and volume production in Asian manufacturing clusters.
United States
Residential renovation contractors in Texas and Florida are converting tool fleets to battery-operated platforms for site mobility. OSHA silica exposure mandates are accelerating dust collection retrofit cycles in fabrication facilities. Milwaukee-based tool manufacturers and Chicago-area metalworking shops anchor demand for cordless belt sanders.
Germany
Mittelstand furniture cooperatives in Bavaria and North Rhine-Westphalia increasingly specify equipment-as-a-service contracts bundling uptime guarantees. EU F-Gas Regulation compliance requirements favor low-emission pneumatic configurations in high-volume production environments. Stuttgart and Hamburg harbor industrial machinery export corridors serving Central European panel processors.
China
Synthetic corundum production clusters in Henan and Ningxia provinces supply abrasive materials to global OEMs, exposing supply chains to freight cost volatility. GB standards for power tool safety and MIIT industrial equipment directives shape domestic manufacturing protocols. Shanghai and Shenzhen electronics manufacturers are integrating sensor arrays into brushless motor controllers for export markets.
Italy
Cabinet furniture manufacturers in Lombardy and Veneto drive wide-belt system demand for panel calibration and veneer preparation. ECHA REACH restrictions on binding resins force abrasive reformulation, extending R&D cycles for domestic manufacturers. Bologna and Milan anchor specialized hardwood flooring restoration equipment supply chains serving heritage building refurbishment.
India
Infrastructure-driven woodworking demand in Maharashtra and Gujarat commercial real estate clusters is expanding equipment procurement. BIS certification alignment and domestic assembly partnerships position foreign OEMs for market entry. Bangalore furniture manufacturing hubs and Delhi-NCR construction channels concentrate demand for entry-level and mid-tier professional equipment.
Sanding Machine Market Competitive Landscape
On the supply side, the industry is tiered between precision engineering specialists serving industrial panel processors and volume manufacturers supplying residential renovation channels. European heritage brands occupy premium positions in wide-belt and drum sander categories, while Japanese and German power tool conglomerates dominate battery-operated handheld segments. Three strategic archetypes define competitive positioning: integrated machinery groups with captive abrasive supply, pure-play sanding equipment specialists, and diversified power tool platforms leveraging battery ecosystem lock-in. Capacity expansion in Southeast Asian assembly facilities and strategic partnerships for IoT-enabled predictive maintenance represent dominant competitive moves.
Within the integrated machinery tier, Biesse and HOMAG Group exemplify European engineering concentration, anchoring premium wide-belt system supply chains through Italian and German manufacturing heritage. Robert Bosch occupies a position in the compact professional segment, representing diversified power tool platform strategies that extend battery runtime without tethered power constraints. These three companies illustrate how geographic origin and corporate structure correlate with market archetype: limited-liability European engineering specialists versus German-based diversified industrial conglomerates.
| Leading Market Players |
|---|
| Biesse |
| SCM Group |
| HOMAG Group |
| Timesavers |
| Costa Levigatrici |
| Weinig |
| Robert Bosch |
| Makita Corporation |
| Festool |
| Others |
Value Network & Pricing Analysis
Synthetic corundum and silicon carbide production clusters in China's Henan and Ningxia provinces concentrate upstream abrasive supply, compressing margin pools for European and North American OEMs while shifting pricing power toward consumable suppliers and specialized coating formulators serving regulated end-markets.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with differentiation driven by ISO vibration certification tiers and bundled predictive maintenance subscriptions. Cost compression in economy-tier handheld units intensifies as Chinese manufacturers expand direct distribution through e-commerce channels. Residential contractors exhibit the highest price sensitivity, while German Mittelstand furniture cooperatives prioritize operational expenditure classification over unit acquisition cost.
Supply Chain Analysis
Export control regimes limiting brushless motor controller technology flows from Shanghai and Shenzhen electronics manufacturers constrain supply chain flexibility for European sanding equipment OEMs seeking IoT-enabled sensor integration. Abrasive consumables draw from Chinese synthetic mineral production, Italian binding resin formulation, and German precision coating application. Single-source vulnerability concentrates in lithium-ion cell supply from South Korean and Chinese producers. Distribution runs through authorized dealer networks for industrial wide-belt systems and big-box retail channels for battery-operated handheld platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes this market, with battery platform maturation driving cordless adoption penetration in residential renovation channels previously tethered to fixed power infrastructure.
For Market Incumbents: Entrench position through backward integration into abrasive consumable production and captive sensor array manufacturing in Stuttgart industrial corridors. Automated CNC routing with integrated finish passes threatens standalone wide-belt system demand; defend through equipment-as-a-service contracting bundling uptime guarantees and predictive maintenance alerts for German Mittelstand cooperatives.
For New Entrants and Emerging Players: Pursue white-space opportunity in India's Maharashtra and Gujarat commercial real estate clusters, where BIS certification alignment gaps create entry pathways for mid-tier professional equipment. Target infrastructure-driven woodworking demand through domestic assembly partnerships with Bangalore furniture manufacturing hubs. Lead with battery platform interoperability as the primary go-to-market angle against established ecosystem lock-in.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European wide-belt specialists possessing installed base density but limited IoT capability stacks. Long-term viability over a 5-10 year window hinges on consumable recurring revenue attachment rates and predictive maintenance algorithm maturity. Watch for inflection in equipment-as-a-service contract penetration among German furniture cooperatives as the signal for platform consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| IoT Sensor Integration | Brushless motor controllers from Shenzhen suppliers enable real-time spindle load monitoring for Italian cabinet manufacturers. |
| Equipment-as-a-Service Rollout | Monthly fee structures with uptime guarantees attract German Mittelstand furniture cooperatives seeking operational expenditure classification. |
| Battery Platform Expansion | Lithium-ion cell density improvements above 250 Wh/kg unlock cordless belt sander performance parity with corded units. |
| Abrasive Supply Backward Integration | In-house synthetic corundum production mitigates freight cost volatility from Henan province export quota uncertainty. |
| India Market Entry Partnership | BIS certification alignment and domestic assembly in Maharashtra position capture of infrastructure-driven woodworking demand. |
Research Methodology
Operator-level perspectives from maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads anchored the qualitative base. Primary fieldwork combined with secondary validation through SEC 10-K filings, customs and trade data, industrial machinery export statistics, and power tool safety standard documentation from IEC and OSHA. Bottom-up equipment shipment modeling and top-down macroeconomic alignment provided triangulation across data sources.
Scenario-bracketing framed the analytical approach across the projection horizon, with segmentation dimensions spanning power platform architecture, material substrate application, and operator skill classification. CAGRs derived from equipment replacement cycle analysis, technology diffusion curves for battery platforms, and regulatory compliance-driven retrofit demand. Forecast inputs incorporated EU F-Gas Regulation phase-down timelines and OSHA silica exposure enforcement intensity.
Macroeconomic conditions sit as an overlay; deviation in residential construction starts, commercial real estate investment cycles, or lithium-ion raw material pricing would shift the trajectory. Forecasts reflect documented assumptions regarding technology adoption rates and regulatory enforcement consistency. Material shifts in REACH substance restriction scope or IEC cordless power tool safety standard revisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Wire Cutters Market
Tools
Grease Gun Market
Tools
Floor Scraper Market
Tools
Portable Pressure Washer Market
Tools
Ratchet Wringer Market
Tools
Construction Anchors Market
Tools
Cutting Tool Inserts Market
Tools
Core Shooter Machine Market
Tools
Bi-Metal Band Saw Blade Market
Tools
Concrete Saw Market
Tools
Stationary Wood Planer Market
Tools
Grinding Machines Market
Tools
Handheld Pipe Cutter Market
Tools
Gear Honing Machines Market
Tools
Total Station Market
Tools
Pipe Alignment Clamps Market