
 Shape Moulding Machines Market | 2026-2036
Shape Moulding Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Shape Moulding Machines Market Insights
The gap between premium servo-electric shape moulding systems and commodity hydraulic units is broadening as energy efficiency mandates harden across manufacturing jurisdictions. Erlenbach GmbH leverages its German engineering heritage to sustain premium positioning in high-precision automotive foam applications. Kurtz Ersa anchors its competitive stance through integrated process control systems that dominate European appliance insulation lines.
Shape moulding machines are industrial forming equipment that heat and press expandable polymers—primarily expanded polystyrene and expanded polypropylene—into cavity-defined geometries using steam, electric, or hybrid heating with clamping forces typically spanning 20 to 400 metric tons. Their primary purpose is producing lightweight, impact-absorbing, thermally insulating components for transportation, packaging, and construction end-uses. Automatic product-type configurations lead installed capacity in high-volume automotive seating and safety-part production where cycle-time consistency governs OEM qualification. Hybrid systems represent the fastest-expanding category as manufacturers balance capital constraints against electricity-cost volatility and tightening carbon-accounting rules. Material-type segmentation tilts toward plastic substrates, though composite-grade machines are capturing margin pools in aerospace seat-core and medical-cooler applications where fire-retardant specification premiums apply.
EU F-Gas Regulation and REACH chemical restrictions are reshaping machine specifications by restricting hydrofluorocarbon blowing agents and mandating material traceability across supply chains. EPA industrial emissions guidelines and China's GB standards on volatile organic compound discharge impose parallel compliance burdens on North American and Asian installed bases. ISO 9001 quality management and CE marking remain baseline market-access requirements, though OEMs increasingly layer IATF 16949 automotive-specific audits onto supplier qualifications. Stakeholders must weigh captive retrofit investments against platform replacement timelines as regulatory thresholds tighten without grandfathering existing assets.
Market Dynamics
EU F-Gas Regulation phase-downs are compressing the installed base of steam-heated hydraulic systems while accelerating electric-driven retrofits across German and Chinese automotive clusters.
Growth Catalysts
- Automotive lightweighting mandates:OEM seating programs in Germany and the United States specify hybrid shape moulding units for expanded polypropylene safety cores. Tier-one suppliers are qualifying automatic configurations to meet cycle-time consistency thresholds.
- REACH chemical traceability:EU material passport requirements are forcing converters to upgrade machine control systems for batch-level polymer tracking. This pulls replacement demand forward in European appliance insulation lines.
- Packaging cluster densification:Fresh produce cold-chain expansion in China concentrates demand for high-throughput expanded polystyrene box production near Shanghai and Guangdong logistics hubs.
Market Restraints
- Steel and copper input volatility:Clamping frame and heating element fabrication costs fluctuate with commodity exchange pricing, squeezing margin on mid-tonnage hydraulic units.
- Blowing agent supply concentration:Lower-GWP hydrocarbon and CO2-based agent production centers on a narrow German-Belgian supplier base, exposing converters to allocation risk during EU quota periods.
- Technical limitation in thick-wall moulding:Electric-only heating struggles to penetrate automotive bumper core applications above 80mm wall thickness where steam diffusion maintains edge.
Strategic Opportunities
- Medical-cooler composite penetration:Fire-retardant expanded polypropylene specifications for pharmaceutical cold-chain packaging in the United States command machine-grade premiums above commodity EPS lines.
- China dual carbon alignment:Provincial energy-intensity targets in Jiangsu and Zhejiang subsidize electric-driven system purchases, opening retrofit windows at state-owned packaging converters.
- Inductive heating convergence:Integration of electromagnetic pre-heating with servo-electric clamping is unifying cycle control for thin-wall automotive components, compressing energy draw below hybrid benchmarks.
Industry Challenges
- Controls engineering talent scarcity:Programming of integrated process control systems for multi-zone temperature management requires skill sets concentrated at German and Japanese OEM engineering centers.
- IATF 16949 certification timeline:Automotive supplier qualification audits extend 14-18 months for new machine installations, delaying revenue recognition on greenfield capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shape Moulding Machines Market |
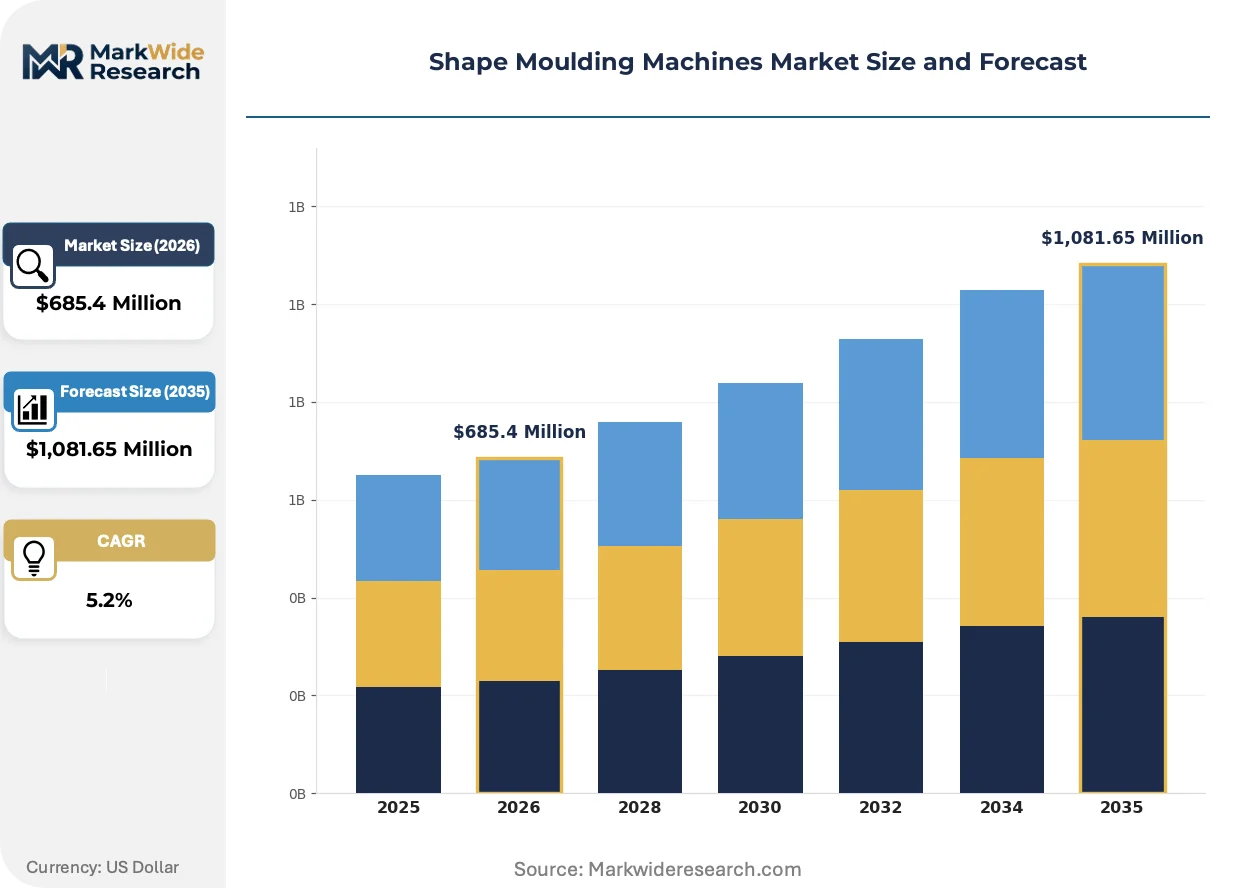
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,081.65 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Semi-Automatic, Manual, Hybrid Material Type: Plastic, Metal, Ceramic, Composite Application: Automotive Parts, Electrical Components, Consumer Goods, Industrial Equipment End User: Manufacturers, OEMs, Prototyping Firms, Research Institutions |
| Companies Covered | Erlenbach GmbH, Heitz GmbH & Co. KG, Kurtz Ersa, Behl GmbH, AKKAYA, HIRSCH Servo Group, Fangyuan Plastics Machinery, DS EPS Machinery, Hebei Zhenyou Machinery Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shape Moulding Machines Market Trends and Innovations
Machine architecture is pivoting from energy-intensive steam systems toward precision electric heating as carbon accounting penetrates procurement specifications across transportation and appliance end-uses.
Servo-electric clamping with inductive mold heating is unifying force and thermal control in a single closed-loop architecture. German automotive seating suppliers are piloting these configurations for expanded polypropylene instrument panel substrates. The technology is compressing energy consumption per part by eliminating steam boiler parasitic load.
EPA industrial emissions guidelines are tightening volatile organic compound discharge thresholds for North American expandable polystyrene operations. Converters in Michigan and Ohio are retrofitting hydraulic units with sealed vacuum systems and thermal oxidizers. Appliance insulation lines bear the heaviest compliance burden due to continuous-operation duty cycles.
Buyer consolidation among multinational packaging groups is compressing equipment procurement into centralized technical sourcing functions. Regional machine distributors are losing specification influence to direct OEM relationships managed from corporate engineering headquarters. This pattern is most visible in United States fresh-produce logistics where three buyers control sixty percent of annual EPS box capacity additions.
Shape Moulding Machines Market Segmentation
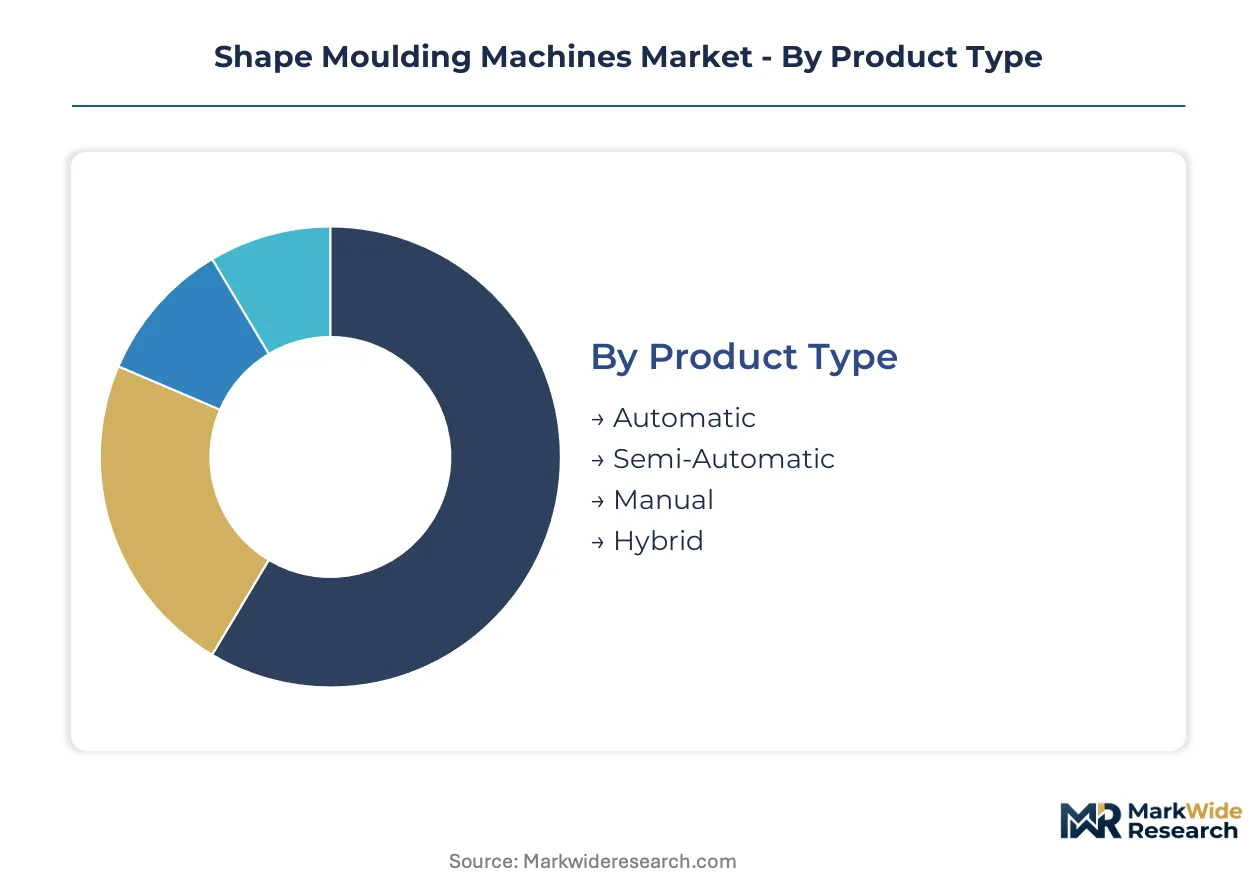
Segmentation in shape moulding machines reveals how specification tiers align with distinct buyer economics across automotive, packaging, and appliance end-uses. Technology choices cascade through material compatibility, cycle-time requirements, and regulatory compliance burdens.
Product Type:
Machine architecture separates along the automation and heating technology axis, with capital intensity and energy accounting driving specification divergence.
- Automatic:Fully automated configurations integrate servo-electric clamping with multi-zone temperature control for cycle-time consistency below 90 seconds. Demand concentrates at German and United States automotive seating suppliers where OEM qualification mandates automatic process validation.
- Hybrid:Combined steam-electric heating systems balance capital constraints against electricity-cost volatility, with fastest expansion in Chinese packaging clusters facing provincial dual carbon targets. These units capture retrofit demand from hydraulic steam systems facing EU F-Gas phase-down pressures.
- Semi-Automatic:Operator-assisted loading with automated clamping and heating cycles serves mid-volume appliance insulation lines in Poland and Mexico where labor arbitrage persists.
- Manual:Hand-loaded configurations with pneumatic clamping dominate prototyping operations and low-volume custom packaging in India and Vietnam.
Mature deployment sits with Automatic systems in German automotive clusters. Newer deployment is concentrated in Hybrid configurations across Chinese state-owned packaging converters.
Material Type:
Substrate compatibility determines heating system specifications, mould surface treatments, and clamping force calibrations across end-use applications.
- Plastic:Expandable polystyrene and polypropylene formulations dominate installed capacity, with EPS box production concentrated near Shanghai and Guangdong logistics hubs serving fresh-produce cold chains.
- Composite:Fire-retardant expanded polypropylene specifications for aerospace seat-cores and pharmaceutical coolers command machine-grade premiums above commodity lines in the United States.
- Metal:Powder metallurgy and metal injection moulding applications require elevated clamping forces above 300 metric tons, with demand anchored in Japanese precision component manufacturing.
- Ceramic:Technical ceramic forming for heat-resistant industrial components represents niche specification, concentrated in German industrial equipment supply chains.
Plastic substrates anchor volume deployment across packaging and automotive safety components. Composite-grade machines are gaining share fastest in aerospace and medical cold-chain applications where specification premiums justify capital investment.
Application:
End-use geometry and performance requirements dictate machine tonnage, heating modality, and control system sophistication.
- Automotive Parts:Expanded polypropylene safety cores for instrument panels and bumper systems require precise density distribution, with qualification cycles extending 14-18 months under IATF 16949 audits at German and United States tier-one suppliers.
- Consumer Goods:Appliance insulation lines for refrigerators and freezers bear heavy EPA emissions compliance burdens in Michigan and Ohio due to continuous-operation duty cycles.
- Electrical Components:Precision housings for power distribution equipment demand tight dimensional tolerance, concentrated in South Korean and Taiwanese electronics manufacturing clusters.
- Industrial Equipment:Protective packaging and machinery components serve diversified demand across European and North American capital goods sectors.
Automotive Parts applications concentrate premium specification deployment. Consumer Goods lines show steepest retrofit activity as EPA guidelines tighten volatile organic compound thresholds.
End User:
Procurement authority and technical specification control vary sharply across buyer types, shaping distribution channel economics.
- OEMs:Direct technical sourcing from corporate engineering headquarters dominates automotive and appliance insulation procurement, compressing regional distributor influence.
- Manufacturers:Tier-two and tier-three packaging converters in China and India rely on distributor relationships for mid-tonnage hydraulic units.
- Prototyping Firms:Low-volume, high-mix operations prioritize manual and semi-automatic flexibility for rapid tooling changeover.
- Research Institutions:University and national laboratory programs pilot inductive heating and electromagnetic pre-heating technologies before commercial scale-up.
OEMs anchor high-value automatic and hybrid system deployment. Research Institutions concentrate experimental heating modality trials ahead of broader commercial adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai anchors the densest concentration of shape moulding machine demand, with Guangdong logistics corridors and Jiangsu provincial manufacturing zones completing China's dominant position in packaging-driven equipment procurement.
Germany
Automotive seating programs and appliance insulation lines drive hybrid and automatic system demand. EU F-Gas Regulation phase-downs compress the installed base of steam-heated hydraulic units. Bavarian automotive clusters and North Rhine-Westphalian converter operations concentrate retrofit activity toward electric-driven configurations.
United States
Expanded polypropylene safety cores for instrument panels and pharmaceutical cold-chain packaging command premium machine specifications. EPA industrial emissions guidelines tighten volatile organic compound thresholds for Michigan and Ohio appliance insulation lines. Fresh-produce logistics hubs in California and Florida concentrate EPS box production capacity additions.
China
Provincial dual carbon targets in Jiangsu and Zhejiang subsidize electric-driven system purchases at state-owned packaging converters. GB standards on volatile organic compound discharge impose compliance burdens on Shanghai and Guangdong installed bases. Yangtze River Delta and Pearl River Delta logistics corridors anchor high-throughput expanded polystyrene box production.
Japan
Precision component manufacturing and electronics packaging sustain demand for elevated clamping-force configurations. METI energy-efficiency directives accelerate servo-electric adoption in Kanto and Kansai industrial zones. Nagoya-area automotive suppliers pilot inductive heating convergence for thin-wall component applications.
India
Mid-tonnage hydraulic units serve low-volume custom packaging and prototyping operations. BIS quality certification requirements shape import specifications for European and East Asian equipment. Maharashtra and Gujarat industrial corridors concentrate operator-assisted semi-automatic deployments where labor arbitrage persists.
Shape Moulding Machines Market Competitive Landscape
Premium-margin players sit above commodity-margin players across heating technology sophistication and control system integration depth. The vendor base separates into three tiers: German engineering houses commanding automotive qualification premiums, Chinese fabricators scaling through packaging volume contracts, and specialized European insulation equipment providers. Consolidation pressure concentrates among mid-tonnage hydraulic specialists facing input cost volatility and regulatory retrofit timelines. Dominant competitive moves include backward integration into control system software and geographic expansion through distributor acquisition in Southeast Asian packaging clusters.
Within the German engineering tier, Erlenbach GmbH and Kurtz Ersa occupy positions defined by automotive and appliance insulation qualification depth. Fangyuan Plastics Machinery and Hebei Zhenyou Machinery Technology represent Chinese fabricators scaling through provincial dual carbon subsidy capture. AKKAYA and HIRSCH Servo Group exemplify European specialists bridging mid-market packaging demand with servo-electric technology transitions. Each archetype faces distinct margin pressure from steel and copper input volatility, blowing agent supply concentration, and IATF 16949 certification timeline extensions.
| Leading Market Players |
|---|
| Erlenbach GmbH |
| Heitz GmbH & Co. KG |
| Kurtz Ersa |
| Behl GmbH |
| AKKAYA |
| HIRSCH Servo Group |
| Fangyuan Plastics Machinery |
| DS EPS Machinery |
| Hebei Zhenyou Machinery Technology |
| Others |
Pricing and Supply Chain Analysis
Servo-electric heating convergence in automotive seating applications simultaneously compresses energy costs per part and concentrates specification control among German and Japanese engineering houses with integrated control system capabilities. This technology shift rewards captive software development while penalizing commodity hydraulic fabricators facing steel and copper input volatility.
Pricing Analysis
Yield-guarantee contracts tied to cycle-time consistency and energy-per-part metrics anchor premium pricing for automatic and hybrid configurations at German automotive tier-one suppliers. Three-tier pricing structure across premium servo-electric, standard hybrid, and economy hydraulic levels reflects IATF 16949 certification depth and control system integration sophistication. Cost compression in mid-tonnage hydraulic units is intensifying because Chinese state-owned packaging converters exploit provincial dual carbon subsidies to demand electric-driven retrofits at compressed margins. Tier-two packaging converters in India and Vietnam exhibit highest price sensitivity, while OEM seating programs in Germany and the United States demonstrate lowest sensitivity due to qualification lock-in effects.
Supply Chain Analysis
CE marking and IATF 16949 certification gating restrict component sourcing to qualified German, Japanese, and South Korean control system suppliers with proven multi-zone temperature management track records. Clamping frame fabrication draws from German and Chinese steel mill supply bases, while servo motor and drive assemblies hinge on Japanese and South Korean electronics manufacturing clusters. Single-source vulnerability concentrates in lower-GWP hydrocarbon blowing agent production centered on German-Belgian chemical suppliers. Distribution runs through direct OEM technical sourcing relationships for automotive and appliance insulation procurement, bypassing regional distributors in consolidated multinational packaging group accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The shape moulding machines market is consolidating as EU F-Gas Regulation phase-downs and IATF 16949 certification timelines force mid-tonnage hydraulic specialists into distressed asset sales or exit.
For Market Incumbents: Hedge margin erosion in commodity hydraulic lines by backward integration into control system software development and captive servo motor supply partnerships. Prioritize certification maintenance investments to defend automotive qualification status against emerging Chinese electric-driven challengers exploiting Jiangsu provincial subsidies. Capacity rationalization in European steam-heated installed bases should precede hybrid retrofit program launches. For New Entrants and Emerging Players: Capture white-space in medical-cooler composite-grade machine specifications for United States pharmaceutical cold-chain packaging, where fire-retardant expanded polypropylene premiums justify capital investment without entrenched incumbent relationships. Target Chinese state-owned packaging converters in Zhejiang and Jiangsu provinces facing dual carbon compliance deadlines with electric-driven system offerings priced below German engineering house benchmarks. Lead with energy-per-part performance guarantees rather than capital cost positioning. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified industrial equipment groups seeking automotive foam processing capabilities. Long-term viability favors servo-electric technology specialists with captive control system IP and established IATF 16949 audit histories over hydraulic fabricators dependent on commodity steel inputs. Watch for inflection in EU F-Gas quota allocation announcements signaling accelerated replacement demand timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Control Software | German engineering houses defend automotive qualification premiums against Chinese electric-driven challengers. |
| Hybrid System Retrofit Programs | EU F-Gas phase-downs compress steam-heated installed bases toward electric-driven configurations. |
| Medical-Cooler Composite Penetration | Fire-retardant expanded polypropylene specifications command machine-grade premiums in United States pharmaceutical packaging. |
| Provincial Subsidy Capture in China | Jiangsu and Zhejiang dual carbon targets subsidize electric-driven purchases at state-owned converters. |
| Inductive Heating Convergence Development | Electromagnetic pre-heating integration compresses energy draw below hybrid benchmarks for thin-wall automotive components. |
Research Methodology
Multi-period observation of machine shipment volumes, retrofit activity rates, and certification audit timelines anchored the trend analysis, supplemented by interviews with plant engineers at German automotive tier-one suppliers, procurement leads at Chinese state-owned packaging converters, aftermarket service heads at European appliance insulation lines, and technical R&D directors at control system OEMs. Secondary validation incorporated customs and trade data from German and Chinese export registries, SEC filings from diversified industrial equipment groups, IATF 16949 certification body disclosures, and EU F-Gas quota allocation records. Bottom-up equipment demand modeling triangulated against top-down end-use industry capacity expansion announcements.
The input-output matrix framework mapped segmentation dimensions including product type architecture, material substrate compatibility, end-use application geometry, and regional regulatory cluster across the projection horizon. CAGRs were derived from installed base turnover rates, replacement demand timing, and greenfield capacity absorption capacity. Industry-specific forecast inputs incorporated EU F-Gas phase-down schedule compliance costs and Chinese provincial dual carbon target enforcement intensity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to blowing agent supply allocation disruptions, steel and copper commodity price volatility, and IATF 16949 certification timeline extensions. Forecasts reflect documented assumptions regarding regulatory grandfathering provisions and technology substitution elasticities. A model refresh is warranted upon material change in EU F-Gas quota enforcement severity or Chinese provincial energy-intensity target recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Floor Saw Market
Tools
Gouging Torch Market
Tools
US Chalk Reel and Line Market
Tools
Gas Cutting Machine Market
Tools
Global Protractor Market
Tools
Foam Cutting Machine Market
Tools
Wire Cutters Market
Tools
Brushcutter Market
Tools
Cordless Blind Rivet Gun Market
Tools
Rotary Tools Market
Tools
Global Punch and Die Storage Cabinet Market
Tools
China Power Tools Market
Tools
China Power Tools and Hand Tools Market
Tools
Set Screw Market
Tools
Rotary Knife Cutters Market
Tools
Global Cutting Discs Market