
 Woodworking Router Bits Market | 2026-2036
Woodworking Router Bits Market Size, Share, and Industry Trends Forecast 2026-2036
Woodworking Router Bits Market Analysis
Computer numerical control integration into small-batch joinery operations is reconfiguring how custom furniture shops specify cutting geometries. Freud America leverages its carbide formulation expertise to anchor premium positioning among cabinet specialists on the US East Coast. Bosch competes through scale advantages in multi-tool platform ecosystems that bundle router bits with cordless power tool lines. Amana Tool Corporation specializes in industrial-grade spiral compression bits for CNC nesting operations in North American panel processing.
Woodworking router bits are rotary cutting tools with precisely ground flutes, typically manufactured from solid carbide or carbide-tipped high-speed steel substrates, designed to remove material from wood stock along predetermined profiles or joinery paths. These tools operate at spindle speeds between 8,000 and 30,000 RPM depending on diameter and material density, serving primary functions from edge profiling to dovetail cutting in solid wood and engineered panel products. Carbide-tipped configurations command the widest installed base among professional contractors due to regrindability and cost efficiency over multiple sharpening cycles. Flush-trim bits retain dominant share in furniture production workflows where template-guided pattern replication standardizes component output across high-volume runs. Spiral bits represent the fastest-expanding category as CNC router adoption penetrates mid-size European and North American custom millwork shops.
OSHA machine guarding standards and the EU Machinery Directive shape product safety requirements for collet compatibility, maximum RPM ratings, and chip ejection geometry in professional distribution channels. REACH restrictions on cobalt content in carbide substrates force material suppliers to certify alternative binder formulations, adding compliance documentation burdens for bit manufacturers exporting into European markets. ISO 19072 tooling interface standards influence shank diameter tolerances that determine interchangeability across router platforms from different power tool OEMs. Stakeholders must monitor how emerging digital product passport mandates under the EU Ecodesign for Sustainable Products Regulation alter traceability requirements for tungsten sourcing in carbide cutting tools.
Market Dynamics
CNC router penetration into mid-size custom millwork shops is compressing demand cycles for spiral compression geometries while simultaneously elevating performance specifications for collet runout tolerances and chip evacuation efficiency.
Growth Catalysts
- EU Ecodesign for Sustainable Products Regulation:Digital product passport mandates for tungsten traceability are accelerating certified carbide sourcing upgrades among export-oriented German and Italian bit manufacturers.
- Residential construction recovery:North American single-family housing starts are restoring replacement demand for flush-trim and edge-profiling bit sets among professional cabinet installers.
- Diamond-like carbon coatings:Thin-film deposition advances are extending cutting edge retention in abrasive engineered wood substrates, reducing sharpening frequency for high-volume panel processors.
Market Restraints
- Tungsten price volatility:Concentrated supply from Chinese mining operations creates margin compression for carbide substrate dependent manufacturers during commodity spike cycles.
- REACH cobalt restrictions:Alternative nickel-chromium binder formulations under ECHA review impose recertification costs and performance uncertainty for European-sourced cutting tool exports.
- Manual router substitution:Track saw and domino joinery systems from power tool platform ecosystems capture material removal tasks previously requiring bit-based operations.
Strategic Opportunities
- India furniture manufacturing expansion:PLI scheme incentives for wood processing clusters in Gujarat and Punjab create first-mover positioning for carbide-tipped spiral bit suppliers establishing local distribution.
- 5-axis CNC convergence:Integration of robotic material handling with continuous rotary axis machining opens specification opportunities for complex undercut geometries in architectural millwork.
- Direct-to-fabricator e-commerce:Specialized cutting tool marketplaces bypass traditional industrial distributor markups for small-batch custom furniture shops requiring rapid geometry turnaround.
Industry Challenges
- CNC programming skill scarcity:Custom millwork shops face recruitment gaps for operators capable of optimizing feeds and speeds for specialized compression geometries in nested panel production.
- ISO 19072 tolerance compliance:Shank diameter interchangeability certification across incompatible router platforms from competing power tool OEMs requires redundant tooling inventories for multi-brand shops.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Woodworking Router Bits Market |
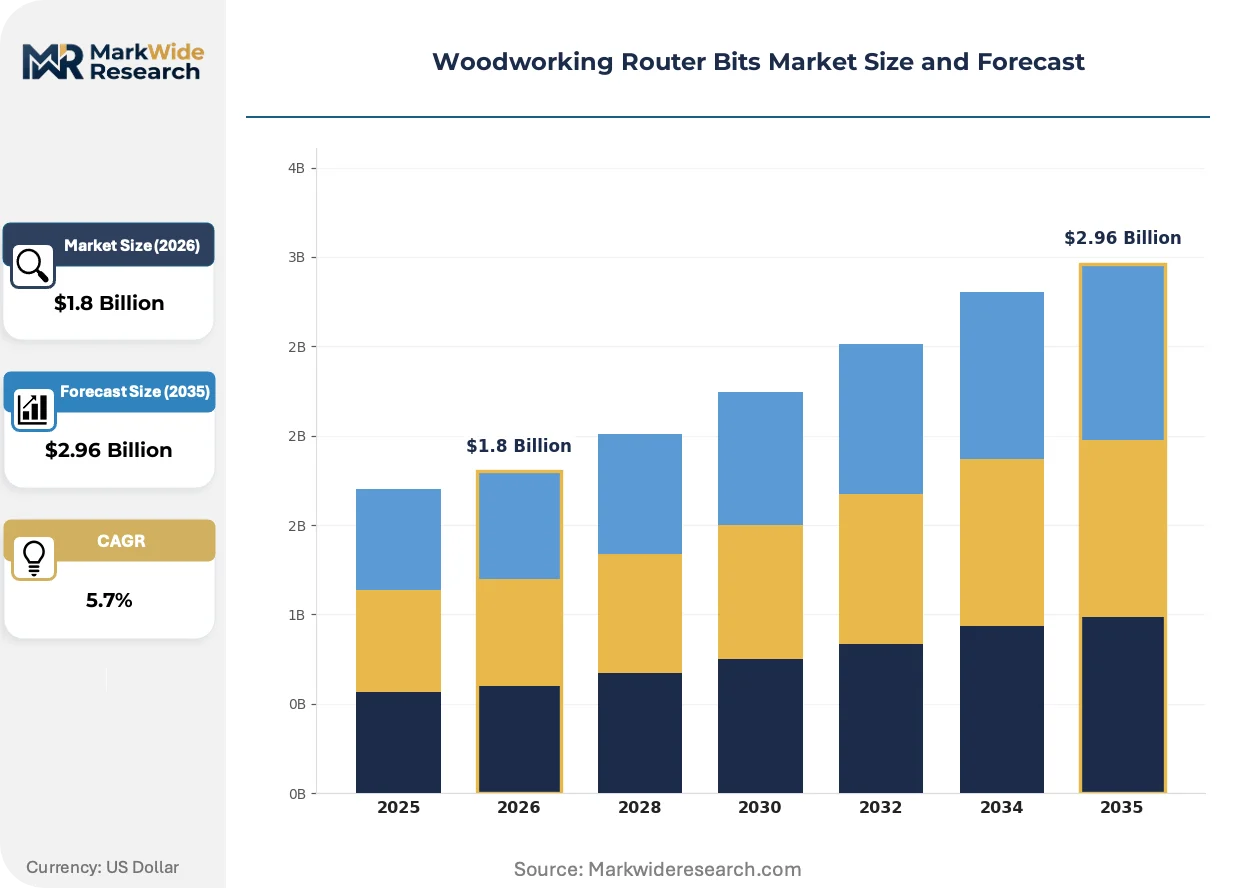
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Bit Type: Straight, Spiral, Flush-Trim, V-Groove Material: High-Speed Steel, Carbide, Carbide-Tipped, Chrome Vanadium Application: Woodworking, Cabinet Making, Joinery, Furniture Production End User: Professionals, Hobbyists, Manufacturers, Contractors |
| Companies Covered | Bosch, Reed Manufacturing Co., Freud America, Vexor Custom Woodworking Tools, Superb Tooling, Amana Tool Corporation, SpeTool, LU&MA, Whiteside Machine Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Woodworking Router Bits Market Emerging Trajectories
Solid carbide spiral geometries are displacing traditional straight-flute configurations as spindle speed capabilities advance and chip load optimization becomes computationally accessible to smaller fabrication operations.
Diamond-like carbon coating deposition via plasma-enhanced chemical vapor deposition is rendering obsolete uncoated carbide edge life in abrasive particleboard and MDF cutting cycles. Mid-size European millwork shops in Germany's Black Forest cluster are retrofitting existing tool holders with coated spiral compression bits to extend batch runs between tool changes. The technology is compressing total cost of ownership calculations for high-volume nested panel operations previously dependent on frequent resharpening services.
REACH cobalt content restrictions under ECHA oversight are forcing reformulation of cemented carbide binders toward nickel-based alternatives. European bit manufacturers face documentation burdens for material safety data sheets and supply chain attestations. Export-oriented producers in Italy's Emilia-Romagna tooling district are restructuring supplier relationships to secure certified alternative substrate feedstock ahead of enforcement phase-ins.
Specification authority is migrating from purchasing departments to CNC programmers and production engineers who directly configure cutting parameters in CAM software. Industrial distributors with legacy field sales models are losing influence to technical content platforms and direct manufacturer portals where geometry selection algorithms replace catalog browsing. This behavioral shift concentrates in North American custom architectural millwork where shop-floor technical staff retain procurement autonomy for consumable tooling.
Woodworking Router Bits Market Segmentation
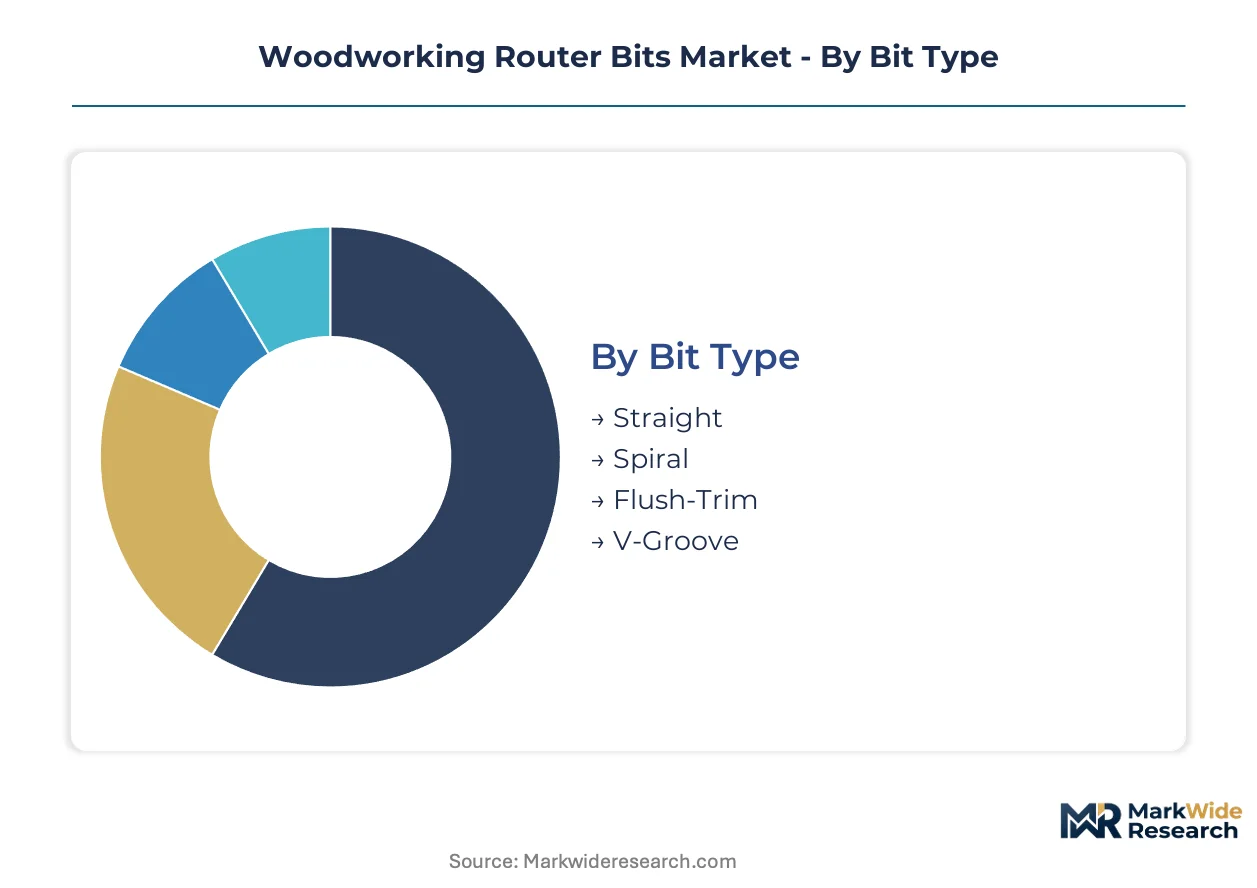
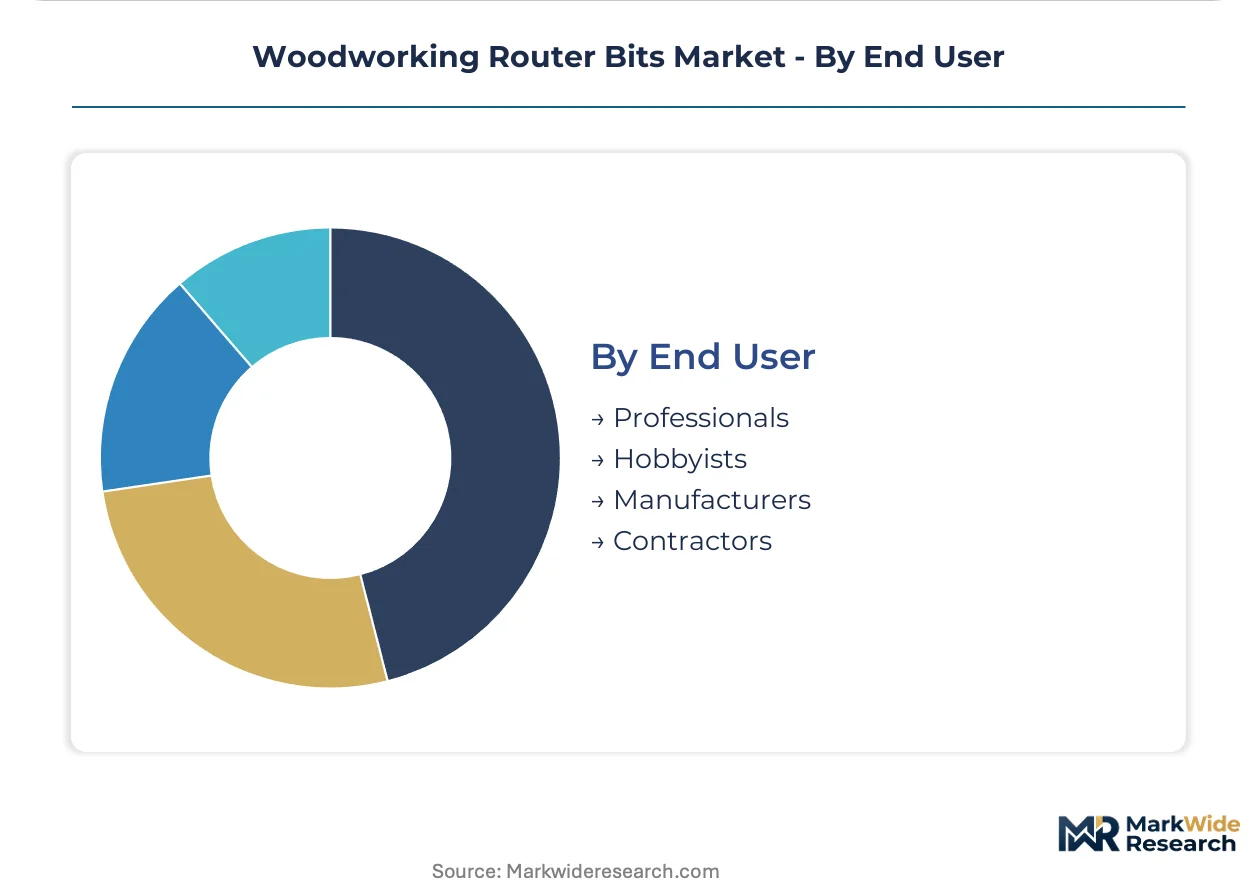
Router bit specification varies sharply by operational intensity, with professional cabinet shops demanding carbide-tipped geometries that withstand thousands of linear feet between sharpening cycles. Hobbyist segments prioritize upfront cost over edge retention, creating divergent service and replacement revenue streams for distributors.
Bit Type:
After-sales intensity concentrates in spiral and flush-trim configurations, where CNC operators require technical support for chip load optimization and collet compatibility troubleshooting.
- Straight:Single-flute and double-flute straight bits deliver clean shoulder cuts in softwood and hardwood stock for basic edge profiling and dado cutting. Demand clusters among US Midwest custom furniture shops running manual routers for one-off architectural millwork pieces, constrained by slower material removal rates compared to spiral alternatives.
- Spiral:Up-cut and down-cut spiral geometries slice with shearing action that reduces tear-out in figured hardwoods and abrasive engineered panels. German Black Forest precision tooling clusters and China's Yangtze River Delta furniture manufacturing belt are driving specification upgrades as CNC nesting operations displace manual pattern routing.
- Flush-Trim:Template-guided bearing bits dominate high-volume furniture production workflows where component standardization determines output consistency.
- V-Groove:Engraving and sign-making applications utilize 60-degree and 90-degree included angle geometries for decorative edge treatment and lettering.
By volume, straight bits lead due to legacy installed base and lowest unit cost. By growth pace, spiral bits are ahead as CNC router adoption penetrates mid-size European and North American custom millwork operations.
Material:
Cost tier stratification separates premium carbide formulations from economy-grade chrome vanadium, with recertification burdens under REACH cobalt restrictions compressing mid-tier positioning.
- High-Speed Steel:M2 and M7 alloy substrates offer economical entry points for occasional-use hobbyists and light-duty trim carpentry. Hobbyist segments in North American big-box retail channels favor HSS starter sets for infrequent edge profiling tasks where edge longevity remains secondary to purchase price.
- Carbide:Solid micro-grain carbide delivers maximum hardness and heat resistance for continuous production environments. Italian Emilia-Romagna tooling manufacturers and German Black Forest precision clusters are securing certified tungsten feedstock ahead of EU digital product passport enforcement for supply chain traceability.
- Carbide-Tipped:Brazed carbide cutting edges on high-speed steel bodies balance regrindability with cost efficiency, commanding widest professional contractor adoption.
- Chrome Vanadium:Alloy steel formulations serve price-sensitive developing market segments where tool life expectations align with disposable rather than resharpenable economics.
By volume, carbide-tipped configurations lead among professional contractors seeking regrindability. By growth pace, solid carbide is expanding most quickly as spindle speed capabilities advance and batch-run optimization becomes computationally accessible.
Application:
Customer maturity varies by production scale, with furniture production workflows demanding predictive tooling cost models and automated replenishment systems.
- Woodworking:General-purpose routing encompasses edge profiling, rabbeting, and decorative molding in solid lumber and veneer-core plywood. Demand concentrates in US East Coast cabinet specialist shops where Freud America anchors premium positioning through carbide formulation expertise and localized technical support.
- Cabinet Making:Precision joinery and component sizing for kitchen and bath installations require consistent cut quality across high-volume repetitive operations. North American residential construction recovery is restoring replacement demand for flush-trim and edge-profiling bit sets among professional installers.
- Joinery:Dovetail, mortise, and tenon cutting bits enable structural wood connections in furniture and architectural millwork.
- Furniture Production:Nested panel processing and CNC-based mass customization drive specification authority toward production engineers configuring cutting parameters in CAM software.
By volume, woodworking applications lead due to broadest end-use coverage. By growth pace, furniture production is climbing the fastest as 5-axis CNC convergence with robotic material handling opens specification opportunities for complex undercut geometries.
End User:
Procurement autonomy concentrates with shop-floor technical staff in professional segments, while hobbyist purchasing flows through e-commerce marketplaces bypassing traditional industrial distributor markups.
- Professionals:Cabinet installers, trim carpenters, and finish carpenters prioritize reliability and edge retention for on-site service calls. US East Coast professional contractors favor carbide-tipped configurations from established brands offering rapid field replacement and technical documentation.
- Hobbyists:Weekend woodworkers and maker-space participants prioritize accessibility and educational content over maximum performance. Direct-to-fabricator e-commerce platforms are capturing this segment through specialized cutting tool marketplaces offering rapid geometry turnaround for small-batch projects.
- Manufacturers:Panel processors and furniture OEMs negotiate volume contracts with tooling suppliers for predictable consumable costs.
- Contractors:General construction and renovation firms bundle router bit procurement with broader power tool platform ecosystems.
By volume, professionals lead due to replacement frequency and bit variety requirements. By growth pace, hobbyists are gaining share fastest as direct e-commerce penetration reduces search friction for specialized geometries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision tooling clusters export carbide-tipped geometries to North American cabinet manufacturers, while China's Yangtze River Delta furniture belt drives spiral bit specification upgrades for CNC nesting operations.
United States
Residential construction recovery is restoring replacement demand for flush-trim and edge-profiling bit sets among professional installers. OSHA machine guarding standards shape collet compatibility and maximum RPM requirements for professional distribution channels. Freud America anchors premium positioning among US East Coast cabinet specialists through carbide formulation expertise and localized technical support infrastructure.
Germany
Export-oriented bit manufacturers face digital product passport mandates for tungsten traceability under EU Ecodesign for Sustainable Products Regulation. REACH cobalt restrictions under ECHA oversight are forcing cemented carbide binder reformulation toward nickel-based alternatives. The Black Forest precision tooling cluster is retrofitting existing tool holders with coated spiral compression bits to extend batch runs between tool changes.
China
Concentrated tungsten supply from domestic mining operations creates margin compression dynamics for carbide substrate dependent manufacturers during commodity spike cycles. The Yangtze River Delta furniture manufacturing belt is driving specification upgrades as CNC nesting operations displace manual pattern routing. MIIT industrial upgrading policies are accelerating spindle speed capability investments in mid-size millwork fabrication facilities.
Italy
Emilia-Romagna tooling district producers are restructuring supplier relationships to secure certified alternative substrate feedstock ahead of EU enforcement phase-ins. CE marking requirements under EU Machinery Directive influence chip ejection geometry standards for professional-grade cutting tools. Regional manufacturers specialize in industrial-grade spiral compression bits for European panel processing workflows.
India
PLI scheme incentives for wood processing clusters in Gujarat and Punjab are creating first-mover positioning opportunities for carbide-tipped spiral bit suppliers establishing local distribution. BIS certification requirements shape product safety documentation for imported cutting tools. Domestic furniture manufacturing expansion is compressing demand cycles for spiral compression geometries while elevating performance specifications.
Woodworking Router Bits Market Vendor Landscape
On the supply side, the industry is fragmented across three distinct capability tiers. Carbide formulation specialists, multi-tool platform conglomerates, and CNC-focused industrial-grade producers each occupy differentiated positioning vectors. Strategic moves concentrate on certified substrate sourcing upgrades and direct-to-fabricator e-commerce channel development.
Among North American specialists, Freud America and Amana Tool Corporation exemplify divergent archetype positioning. Freud America represents the carbide formulation expertise tier anchoring premium market positioning. Amana Tool Corporation occupies the industrial-grade CNC specialization segment. Bosch, as a multi-tool platform conglomerate, competes through scale advantages in cordless power tool ecosystem bundling. These three patterns illustrate how competitive positioning fragments across technical specialization, manufacturing scale, and platform integration vectors.
| Leading Market Players |
|---|
| Bosch |
| Reed Manufacturing Co. |
| Freud America |
| Vexor Custom Woodworking Tools |
| Superb Tooling |
| Amana Tool Corporation |
| SpeTool |
| LU&MA |
| Whiteside Machine Company |
| Others |
Supply Flow & Price Mechanics
Chinese tungsten mining concentration anchors carbide substrate costs, pushing margin pools toward downstream bit manufacturers with certified alternative binder formulations and direct-to-fabricator channel control. Pricing power fragments across three technology tiers while REACH compliance costs reshape procurement economics for European export-oriented producers.
Pricing Analysis
Coated spiral compression bits command 40-60% premiums over uncoated straight-flute legacy configurations, while diamond-like carbon deposition costs compress as plasma-enhanced chemical vapor deposition scales. Three-tier pricing structure across premium, standard, and economy levels separates solid carbide CNC-grade geometries from regrindable carbide-tipped contractor sets and disposable chrome vanadium hobbyist lines. Pricing pressure stems from tungsten commodity volatility concentrated in Chinese state-controlled mining operations. Hobbyist segments exhibit highest price sensitivity, prioritizing upfront purchase cost over lifetime edge retention calculations.
Supply Chain Analysis
Tungsten ore extraction concentrates in China, Russia, and Vietnam, with intermediate carbide powder processing clustering in Chinese state-owned enterprises and German specialty chemical producers. Finished bit manufacturing draws from cemented carbide substrates, high-speed steel billets, and diamond-like carbon coating deposition equipment. Single-source vulnerability runs through Chinese tungsten concentrate supply during export quota enforcement periods. Distribution runs through industrial distributors with legacy field sales models, though direct-to-fabricator e-commerce platforms are capturing specification authority from CNC programmers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The woodworking router bits market sits in a residential construction recovery cycle, with North American single-family housing starts restoring replacement demand for professional-grade cutting tools. Stakeholder strategies must account for specification authority migration toward shop-floor technical staff and CNC programming capabilities.
For Market Incumbents: Pre-empt cobalt binder substitution disruption by accelerating nickel-chromium formulation certification ahead of ECHA enforcement phase-ins. Secure captive tungsten feedstock through backward integration into certified mining operations or long-term offtake agreements with traceable suppliers. Defend against direct-to-fabricator e-commerce disintermediation by embedding geometry selection algorithms into CAM software partnerships.
For New Entrants and Emerging Players: Build out India PLI scheme positioning by establishing local distribution partnerships in Gujarat and Punjab wood processing clusters before incumbent certification burdens escalate. Target hobbyist segment penetration through specialized cutting tool marketplaces offering rapid geometry turnaround and educational content integration. Pursue white-label supply relationships with North American power tool platform ecosystems seeking bit bundling capabilities.
For Investors and Strategic Acquirers: Capital is best deployed toward carbide formulation specialists with certified alternative substrate capabilities and established CNC technical support infrastructure. Long-term viability favors producers with backward integration into traceable tungsten sourcing and direct channel relationships with panel processing OEMs. Watch for inflection signals in India furniture manufacturing cluster formation and 5-axis CNC adoption rates in European architectural millwork.
| Strategic Initiative | Industry Significance |
|---|---|
| Certified Alternative Binder Investment | REACH cobalt restrictions force nickel-chromium formulation upgrades ahead of ECHA enforcement timelines. |
| Direct-to-Fabricator E-Commerce Buildout | Specialized marketplaces bypass industrial distributor markups for small-batch custom furniture shops. |
| India Distribution Establishment | PLI scheme incentives in Gujarat and Punjab create first-mover positioning for spiral bit suppliers. |
| CAM Software Partnership Integration | Geometry selection algorithms embedded in programming platforms capture specification authority migration. |
| Traceable Tungsten Supply Securement | EU digital product passport mandates require certified sourcing documentation for European market access. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC filings from listed power tool OEMs, and ISO certification registries. Primary interviews engaged CNC programmers at North American custom millwork shops, procurement directors at German Black Forest precision tooling clusters, and distribution managers at European industrial supply houses. Secondary validation drew from ECHA substance restriction notifications, MIIT industrial equipment upgrading policy documents, and BIS certification requirement updates. Bottom-up bit volume estimates triangulated against top-down construction activity indices and furniture production output statistics.
Forecast inputs span bit type, material substrate, application intensity, and end-user procurement autonomy across the analysis window. Segmentation modeling incorporated CNC adoption penetration curves, residential construction permit trajectories, and regulatory compliance cost pass-through assumptions. CAGRs derived from installed base replacement cycles, technology substitution elasticities, and geographic manufacturing cluster formation patterns. Spindle speed capability investments and diamond-like carbon coating adoption rates served as industry-specific demand modifiers.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated Chinese tungsten miners or platform-ecosystem power tool OEMs would shift outcomes. Cross-checking against customs export data for carbide cutting tools and regional housing start permits is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Saw Blades Market
Tools
Portable Grinders Market
Tools
Quick Release Pins Market
Tools
Deburring Tool Market
Tools
Rotary Hammer Drill Market
Tools
Core Shooter Machine Market
Tools
Portable Milling Machine Market
Tools
MIG Guns Market
Tools
Sander Market
Tools
Portable Rolling Toolbox Market
Tools
Hand and Power Tools Market
Tools
Mold Racks Market
Tools
Hydraulic Torque Wrench Market
Tools
Mechanical Springs Market
Tools
Cordless Long Neck Grinder Market
Tools
Press Machine Market