
 Fiber Laser Cutting Machines Market | 2026-2036
Fiber Laser Cutting Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Fiber Laser Cutting Machines Market Analytics
Distributor networks for industrial laser systems is narrowing as manufacturers build direct-service arms in key manufacturing corridors. Trumpf leverages its integrated software-hardware ecosystem to control aftermarket revenue streams. Bystronic anchors its position through localized service hubs across European industrial belts. Amada competes by sustaining dense technician coverage in Japanese and Southeast Asian fabrication centers.
A fiber laser cutting machine generates a coherent beam through rare-earth-doped fiber gain media, typically ytterbium at 1064 nm, delivering power densities exceeding 10^6 W/cm² for melt-and-blow material removal. CW Laser systems dominate thick-plate processing in shipbuilding and heavy equipment, where power scaling above 20 kW shortens cycle times. Pulsed Laser configurations command premium positioning in electronics and medical device applications requiring minimal heat-affected zones. Ultrafast Laser segments attract specialized demand for cold ablation of brittle substrates, though unit economics currently limit broader metal fabrication penetration.
OSHA laser safety standards in the United States mandate interlocked enclosures and beam containment for Class 4 industrial systems, elevating compliance costs for entry-level suppliers. CE marking under the EU Machinery Directive requires documented risk assessments and third-party conformity verification for European market access. Buyers must weigh total cost of ownership against throughput gains as power thresholds climb and regulatory frameworks tighten across multiple jurisdictions.
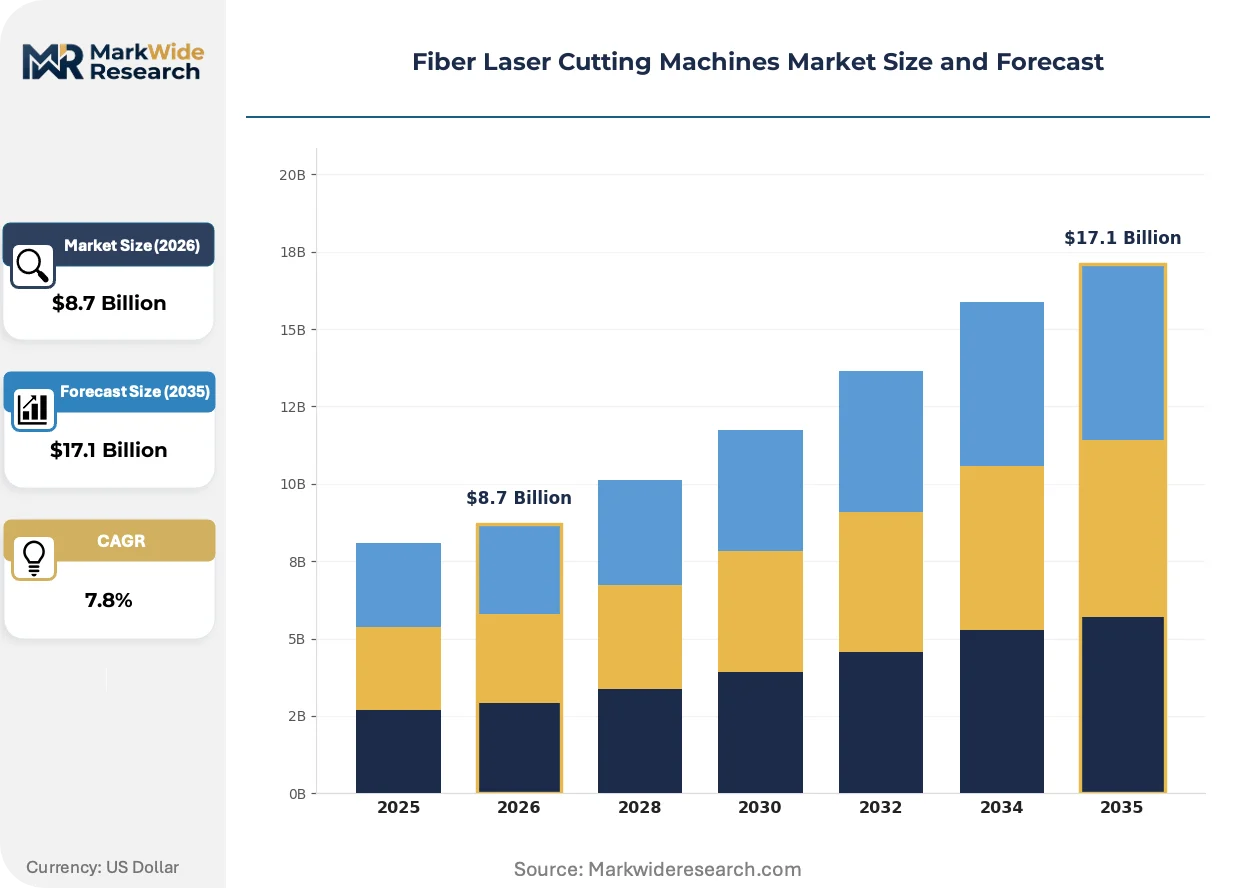
Market Dynamics
Power scaling above 20 kW is compressing cycle times in thick-plate processing while simultaneously elevating capital barriers and forcing supplier consolidation around integrated software-hardware ecosystems.
Growth Catalysts
- Automotive OEM demand:High-strength steel processing requirements from electric vehicle manufacturers are pulling fiber laser systems into stamping and body-in-white fabrication lines.
- China's MEE dual carbon goals:Energy-efficiency mandates are accelerating replacement of CO2 laser systems with ytterbium-doped fiber architectures in Yangtze River Delta manufacturing clusters.
- CE marking pathway:Third-party conformity verification under the EU Machinery Directive creates competitive moats for suppliers with documented risk assessment capabilities.
Market Restraints
- Rare-earth supply concentration:Ytterbium-doped fiber gain media depend on Chinese rare-earth processing infrastructure, exposing downstream equipment manufacturers to input volatility.
- OSHA compliance costs:Interlocked enclosure and beam containment requirements for Class 4 industrial systems elevate fixed costs for entry-level suppliers competing on price.
- Plasma-arc substitution:Thick-plate shipbuilding applications below 25 mm thickness retain plasma cutting for capital-constrained yards prioritizing upfront equipment cost over throughput.
Strategic Opportunities
- India's PLI scheme:Production-linked incentives for precision manufacturing equipment create localized assembly opportunities for suppliers establishing captive service networks.
- Ultrafast-cold ablation convergence:Femtosecond pulse architectures paired with beam delivery robotics open medical stent and semiconductor substrate applications beyond traditional metal fabrication.
- Direct-service channel expansion:Manufacturers bypassing distributor networks to capture aftermarket revenue streams in Germany's Stuttgart and Munich industrial corridors.
Industry Challenges
- Optical technician scarcity:Ytterbium fiber alignment and resonator maintenance require specialized photonics training that vocational programs have not scaled to match equipment deployment rates.
- Legacy ERP integration:Shop-floor control software from Trumpf, Bystronic, and Amada uses proprietary data protocols that resist integration with buyer MES systems without custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiber Laser Cutting Machines Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CW Laser, Pulsed Laser, Hybrid Laser, Ultrafast Laser End User: Aerospace, Automotive OEMs, Electronics, Metal Fabrication Application: Sheet Metal Cutting, Tube Cutting, Engraving, Marking Technology: Fiber Technology, Solid-State Laser, CO2 Laser, Others |
| Companies Covered | Trumpf, Bystronic, Amada, IPG Photonics Corporation, Han's Laser Technology Industry Group Co., Ltd, Coherent Corp., Mazak Corporation, LVD, Prima Power, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiber Laser Cutting Machines Market Evolving Landscape
Beam delivery and process control architectures are converging with industrial IoT platforms, compressing the traditional separation between cutting equipment and factory-level production planning systems.
Artificial intelligence-driven nesting and cut-path optimization software is digitizing material yield calculations in real-time during job execution. Tier-one automotive stampers in Germany and Japan are deploying these systems at scale. The technology is digitizing how contract manufacturers quote complex multi-part jobs, collapsing the traditional separation between estimation and production engineering functions.
REACH restrictions on chromium-bearing alloys are forcing stainless steel processors to certify alternative grades for laser-cut medical device components. The European Chemicals Agency's sunset date assessments are accelerating qualification timelines for nickel-titanium and cobalt-chrome substitutes. Medical device contract manufacturers in Ireland and Switzerland are rebuilding supplier qualification protocols around these material transitions.
Buying committees now mandate total cost of ownership models spanning 10-year depreciation horizons rather than prioritizing upfront capital expenditure. Japanese and Southeast Asian fabrication centers are unbundling after-sales service contracts from equipment financing, treating technician coverage density as a separately negotiable performance metric. This pattern is most pronounced in precision component supply chains serving aerospace tier-two suppliers.
Fiber Laser Cutting Machines Market Segmentation
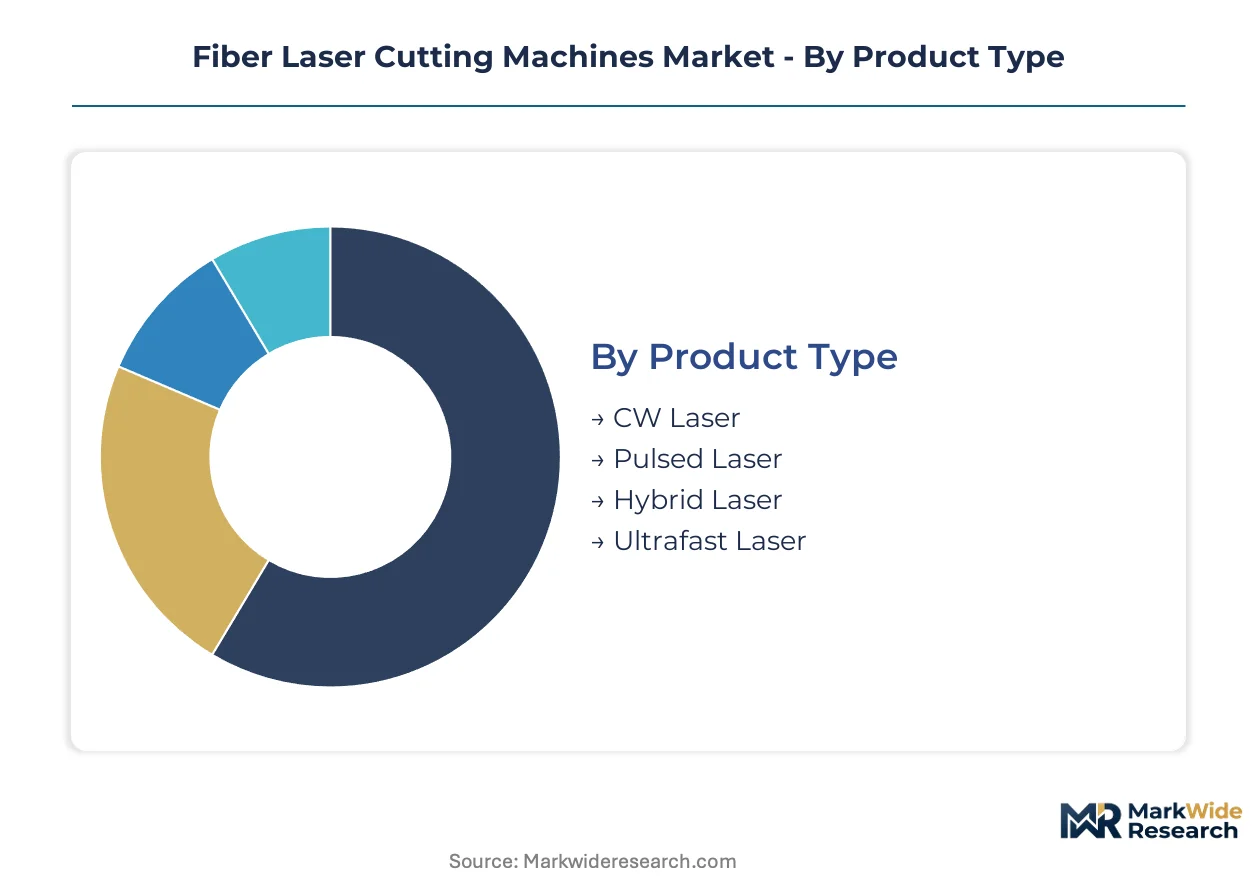
Equipment procurement patterns diverge sharply across power classes and end-use specifications. Buyers optimize capital deployment differently when cycle times, material thickness, and regulatory compliance requirements vary.
Product Type:
CW Laser systems turn over slowest due to heavy infrastructure requirements, while Ultrafast Laser units cycle fastest as medical device manufacturers qualify new platforms.
- CW Laser:Continuous-wave ytterbium-doped architectures deliver sustained power densities above 10^6 W/cm² for melt-and-blow removal. Shipbuilding yards in South Korea and Japan deploy 20 kW-plus units for thick-plate hull sections where throughput justifies capital intensity. Cycle times compress nonlinearly as power scales.
- Pulsed Laser:Q-switched or MOPA configurations generate peak powers in nanosecond windows, minimizing heat-affected zones in electronics substrate processing. Demand concentrates in Shenzhen and Dongguan manufacturing clusters serving smartphone supply chains where precision tolerances are tightest.
- Hybrid Laser:Combines fiber delivery with adaptive beam shaping for mixed-material processing. Metal fabrication job shops in Germany's Stuttgart corridor favor these for contract manufacturing flexibility.
- Ultrafast Laser:Femtosecond pulse architectures enable cold ablation of brittle substrates. Medical stent manufacturers in Switzerland and Ireland drive qualification timelines for cobalt-chrome and nickel-titanium processing.
CW Laser dominates installed base. Ultrafast Laser is where expansion concentrates.
End User:
Cost tiers separate capital-intensive OEM integration from job-shop rental models, with electronics contract manufacturers occupying the mid-tier.
- Aerospace:Tier-one airframers mandate 10-year total cost of ownership models covering depreciation, maintenance, and regulatory documentation. Boeing and Airbus supply chains in Wichita and Hamburg enforce AS9100D traceability requirements that elevate supplier qualification barriers.
- Automotive OEMs:Electric vehicle manufacturers in Germany and China pull fiber laser systems into body-in-white fabrication lines for high-strength steel processing. Stamping press integration requires synchronized material handling and real-time quality feedback loops.
- Electronics:PCB and semiconductor substrate processing demands sub-50-micron kerf widths with minimal dross. Taiwanese and South Korean contract manufacturers prioritize equipment with documented cleanroom compatibility.
- Metal Fabrication:Independent job shops compete on turnaround speed and material yield optimization. Indian precision manufacturing clusters under the PLI scheme are localizing assembly to reduce import duty exposure.
Metal Fabrication dominates installed base. Automotive OEMs is where expansion concentrates.
Application:
Volume concentration separates high-throughput sheet operations from specialized tube and marking configurations.
- Sheet Metal Cutting:Flat-bed gantries process carbon steel, stainless, and aluminum in thickness ranges from 0.5 mm to 50 mm. German precision manufacturing clusters around Munich optimize nesting algorithms through AI-driven software integration.
- Tube Cutting:Rotary chuck systems handle structural hollow sections for construction and agricultural equipment. Chinese Yangtze River Delta fabricators are replacing CO2 systems with ytterbium-diber architectures under MEE dual carbon mandates.
- Engraving:Shallow-depth marking for traceability and branding applications. Medical device contract manufacturers in Ireland rebuild qualification protocols around REACH-compliant chromium-free alloys.
- Marking:High-speed alphanumeric and 2D code application for component serialization. Electronics manufacturers in Japan unbundle after-sales service contracts from equipment financing.
Sheet Metal Cutting dominates installed base. Tube Cutting is where expansion concentrates.
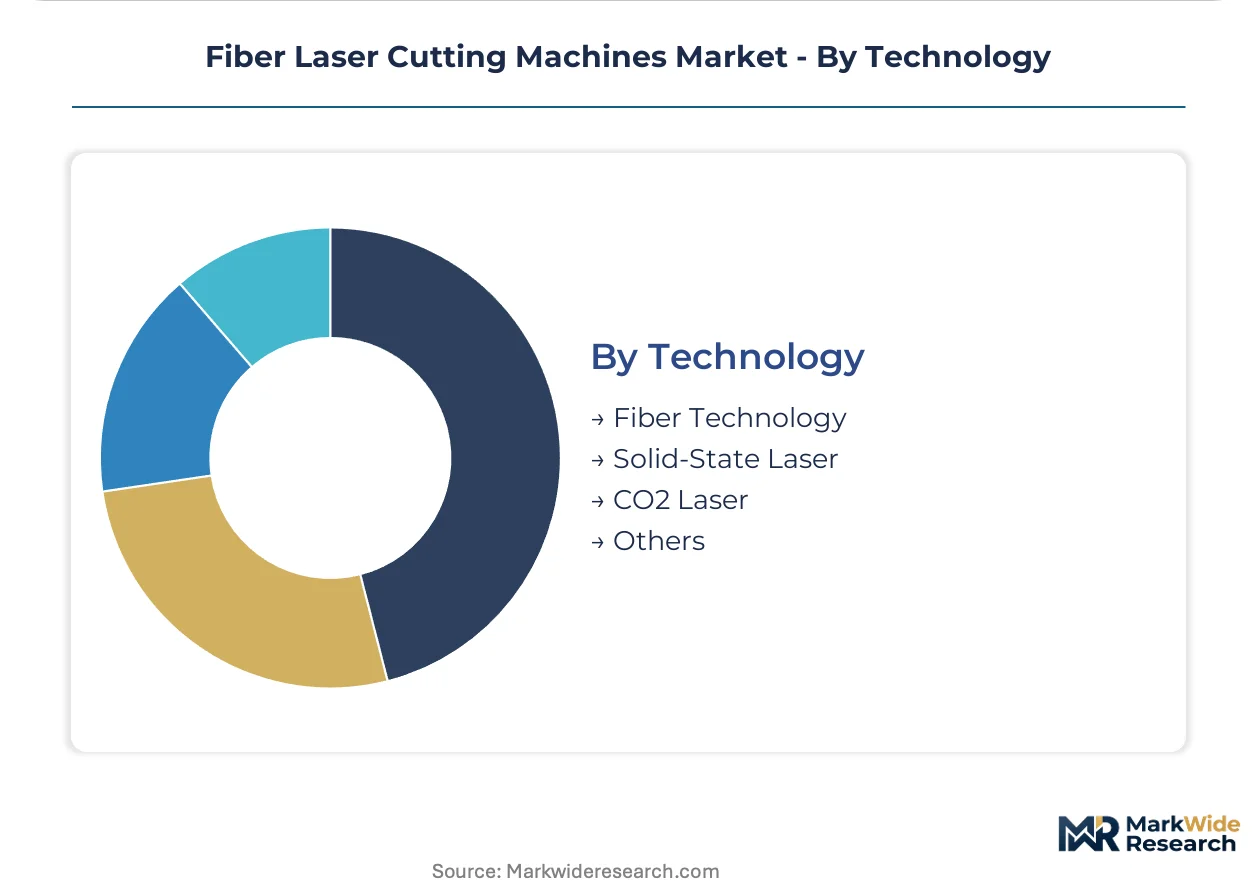
Technology:
Supply concentration in rare-earth processing infrastructure shapes competitive dynamics across technology categories.
- Fiber Technology:Ytterbium-doped silica gain media pumped by diode lasers achieve wall-plug efficiencies above 30%. Chinese rare-earth processing concentration exposes equipment manufacturers to input volatility in ytterbium supply.
- Solid-State Laser:Nd:YAG or Yb:YAG rod and disk configurations persist in legacy installations. Maintenance requirements for optical alignment and thermal management limit new deployments.
- CO2 Laser:Gas discharge systems at 10.6 μm wavelength retain niche applications in non-metallic materials. Energy efficiency disadvantages are accelerating replacement timelines in regulated jurisdictions.
- Others:Direct diode and disk laser architectures serve specialized industrial applications. Limited penetration in mainstream metal fabrication due to beam quality constraints.
Fiber Technology dominates installed base. CO2 Laser replacement cycles are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment pricing power concentrates in Germany's precision manufacturing clusters while Chinese suppliers compete on localized assembly economics under the PLI scheme. Buyers in Stuttgart and Munich corridors extract premium service terms through dense technician coverage requirements. Yangtze River Delta fabricators leverage dual carbon mandates to accelerate CO2 replacement cycles.
Germany
Automotive OEM demand for high-strength steel processing pulls fiber laser systems into body-in-white fabrication lines. CE marking under the EU Machinery Directive enforces third-party conformity verification for market access. Stuttgart and Munich industrial corridors concentrate procurement from buyers unbundling after-sales service contracts from equipment financing.
China
Energy-efficiency mandates from the MEE accelerate ytterbium-doped fiber adoption in metal fabrication job shops. Dual carbon goals enforce replacement timelines for CO2 laser systems in regulated jurisdictions. Yangtze River Delta manufacturing clusters localize assembly to reduce import duty exposure under precision manufacturing incentives.
United States
Aerospace tier-one supply chains enforce AS9100D traceability requirements that elevate supplier qualification barriers. OSHA laser safety standards mandate interlocked enclosures and beam containment for Class 4 industrial systems. Wichita fabrication centers prioritize total cost of ownership models spanning 10-year depreciation horizons.
Japan
Electronics contract manufacturers demand sub-50-micron kerf widths with documented cleanroom compatibility. METI industrial standards shape procurement specifications for semiconductor substrate processing equipment. Kanto and Kansai manufacturing belts sustain dense technician coverage as a separately negotiable performance metric.
India
Production-linked incentives for precision manufacturing equipment create localized assembly opportunities for captive service networks. BIS certification requirements structure equipment import protocols for metal fabrication job shops. Maharashtra and Gujarat industrial corridors concentrate demand from automotive component suppliers scaling high-strength steel processing.
Fiber Laser Cutting Machines Market Competitive Landscape
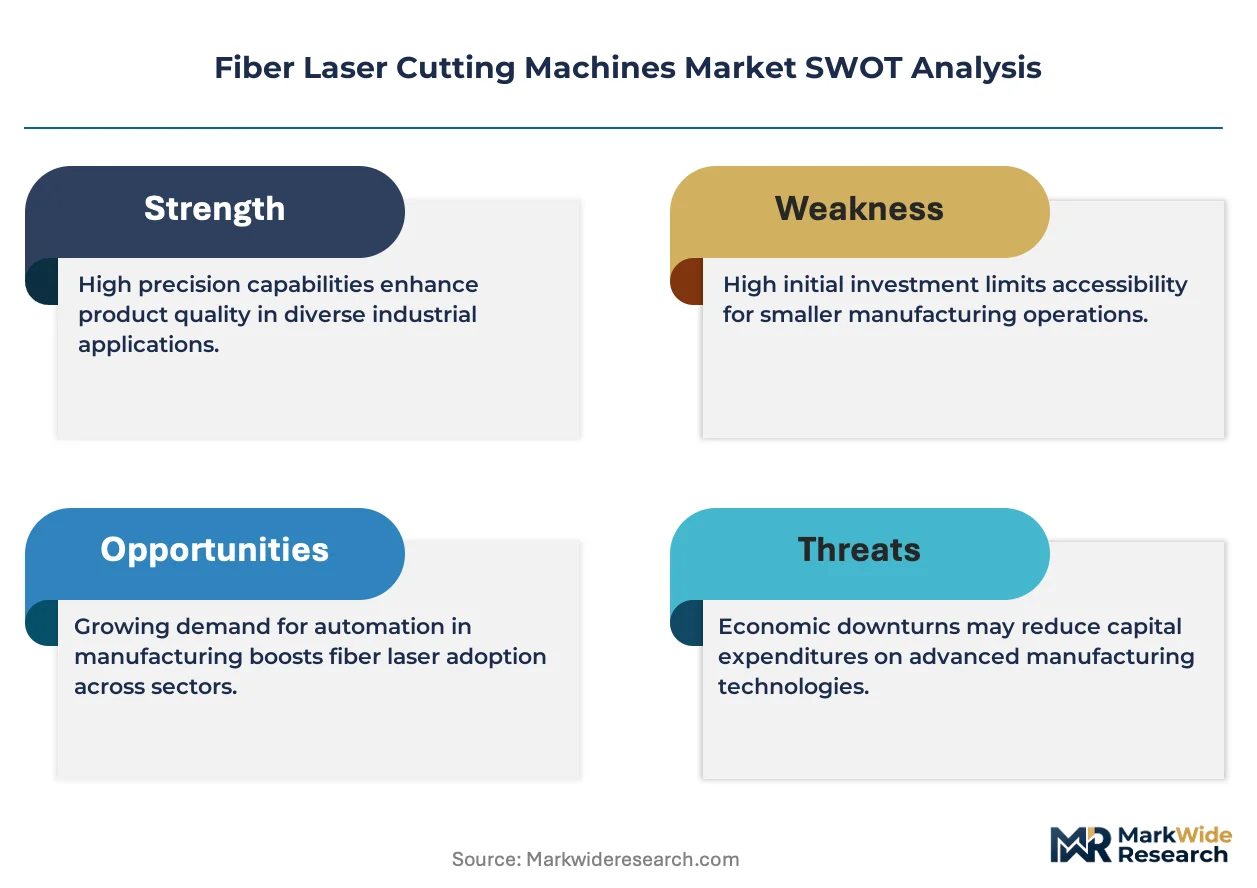
Integrated software-hardware ecosystems and pure-play equipment fabricators split the market along service-capture and capital-efficiency vectors. Consolidation pressure intensifies as power scaling above 20 kW elevates R&D thresholds and compresses margins for undifferentiated suppliers. Strategic archetypes include vertically integrated platform vendors controlling aftermarket revenue streams, regional specialists anchoring localized service density, and rare-earth-integrated upstream players managing input volatility. Dominant competitive moves span direct-service channel expansion bypassing distributor networks and AI-driven nesting software integration collapsing estimation-production engineering boundaries.
Among Germany-based integrated platform vendors, Trumpf exemplifies the software-hardware ecosystem archetype. Bystronic occupies a position within the European service-hub specialist tier. Amada represents the dense technician coverage model in Japanese and Southeast Asian fabrication centers. These three anchors illustrate how geographic service density and proprietary control architectures define competitive positioning without requiring scale-driven consolidation.
| Leading Market Players |
|---|
| Trumpf |
| Bystronic |
| Amada |
| IPG Photonics Corporation |
| Han's Laser Technology Industry Group Co., Ltd |
| Coherent Corp. |
| Mazak Corporation |
| LVD |
| Prima Power |
| Others |
Value Network & Pricing Analysis
Yangtze River Delta port congestion elevates landed costs for ytterbium-doped fiber gain media, compressing margins for equipment assemblers while amplifying price spreads between configured-to-order systems and standard configurations. Chinese rare-earth processing concentration feeds directly into buyer negotiation leverage in Germany's Stuttgart corridor.
Pricing Analysis
The customization-premium spread separates configured-to-order fiber laser systems from standard gantry configurations by fifteen to twenty-five percent. Three-tier pricing structure across premium, standard, and economy levels reflects CE marking certification status and bundled after-sales service density. Cost compression in entry-level tiers is intensifying because plasma-arc substitution retains shipbuilding accounts below 25 mm thickness. Metal fabrication job shops in India exhibit highest price sensitivity, while aerospace tier-one suppliers prioritize total cost of ownership over upfront capital expenditure.
Supply Chain Analysis
Export-control regimes limiting diode laser pump source flows constrain equipment manufacturers sourcing from Chinese and German suppliers. Ytterbium-doped fiber gain media draws from Chinese rare-earth processing infrastructure, with resonator optics anchored in Japanese and German precision manufacturing clusters. Single-source vulnerability concentrates in ytterbium supply chains, exposing downstream assemblers to input volatility. Distribution runs through direct-service channels bypassing distributor networks in European industrial belts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket service revenue streams expand faster than hardware shipments as buyers unbundle technician coverage density from equipment financing. Software-hardware ecosystem control captures recurring revenue through predictive maintenance and nesting optimization subscriptions.
For Market Incumbents: Harden proprietary data protocol integration against middleware competitors by expanding API partnerships with MES platform vendors. Deepen captive ytterbium supply arrangements through backward integration into rare-earth processing partnerships. CE marking documentation capabilities create switching costs that plasma-arc substitution cannot replicate.
For New Entrants and Emerging Players: Build out localized assembly operations in Maharashtra and Gujarat industrial corridors under India's PLI scheme precision manufacturing incentives. Target medical stent processing applications where ultrafast laser qualification timelines favor nimble suppliers. Establish direct-service hubs in Yangtze River Delta clusters to capture CO2 replacement cycles under MEE dual carbon mandates.
For Investors and Strategic Acquirers: REACH sunset date assessments for chromium-bearing alloys reshape the acquisition landscape by elevating medical device contract manufacturers with alternative-grade qualification protocols. Five-to-ten year viability favors suppliers with documented risk assessment capabilities under EU Machinery Directive frameworks. Watch for rare-earth export licensing restrictions as inflection indicators for input cost volatility.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-Service Channel Expansion | Bypassing distributor networks captures aftermarket revenue in Stuttgart and Munich corridors. |
| AI-Driven Nesting Software Integration | Trumpf and Bystronic collapse estimation-production engineering boundaries for automotive stampers. |
| Localized Assembly Under PLI Scheme | Maharashtra and Gujarat facilities reduce import duty exposure for Indian metal fabrication job shops. |
| Ultrafast-Cold Ablation Convergence | Femtosecond architectures paired with beam delivery robotics open medical stent applications. |
| Backward Integration into Ytterbium Supply | Captive rare-earth processing partnerships hedge against Chinese supply concentration volatility. |
Research Methodology
Initial hypotheses were tested against primary input from plant engineers, aftermarket service heads, OEM procurement teams, and laser safety compliance officers and refined through secondary validation against SEC filings, EU Machinery Directive conformity databases, customs trade records, and industrial laser association membership directories. Bottom-up equipment shipment tallies were triangulated against top-down manufacturing value-added estimates across the analysis window.
Demand-supply-balance framing anchored the analytical framework, modeling power class, end-use specification, application type, and regional regulatory cluster dimensions throughout the forecast period. CAGRs were derived from segment-level growth rate reconciliation against macro industrial production indices. Forecast inputs incorporated MEE dual carbon mandate enforcement timelines and REACH sunset date progression for chromium-bearing alloys.
Stress conditions across rare-earth export licensing, ytterbium price volatility, and CE marking compliance cost inflation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding power scaling adoption curves and plasma-arc substitution thresholds. Material shifts in OSHA laser safety standard revisions or EU Machinery Directive scope expansions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Caulking Gun Market
Tools
Screwdriver Market
Tools
Saw Blades Market
Tools
Key Cutting Machine Market
Tools
Air Drills Market
Tools
Wood Floor Grinding Machine Market
Tools
Hydraulic Torque Wrench Market
Tools
Floor Pads Market
Tools
Pruning Saw Market
Tools
Mold Racks Market
Tools
Gear Cutting Machines Market
Tools
Total Station Market
Tools
Cold and Hot Tool Steel Market
Tools
Concrete Saw Market
Tools
Global Metal Forming Machine Tools Market
Tools
Clamps Market